
Cash, financial and flexible budgets
Printable study notes to use alongside Part B.3.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
Cash, financial and flexible budgets
MODULE 3 | PART B.3 | STUDENT COMPANION
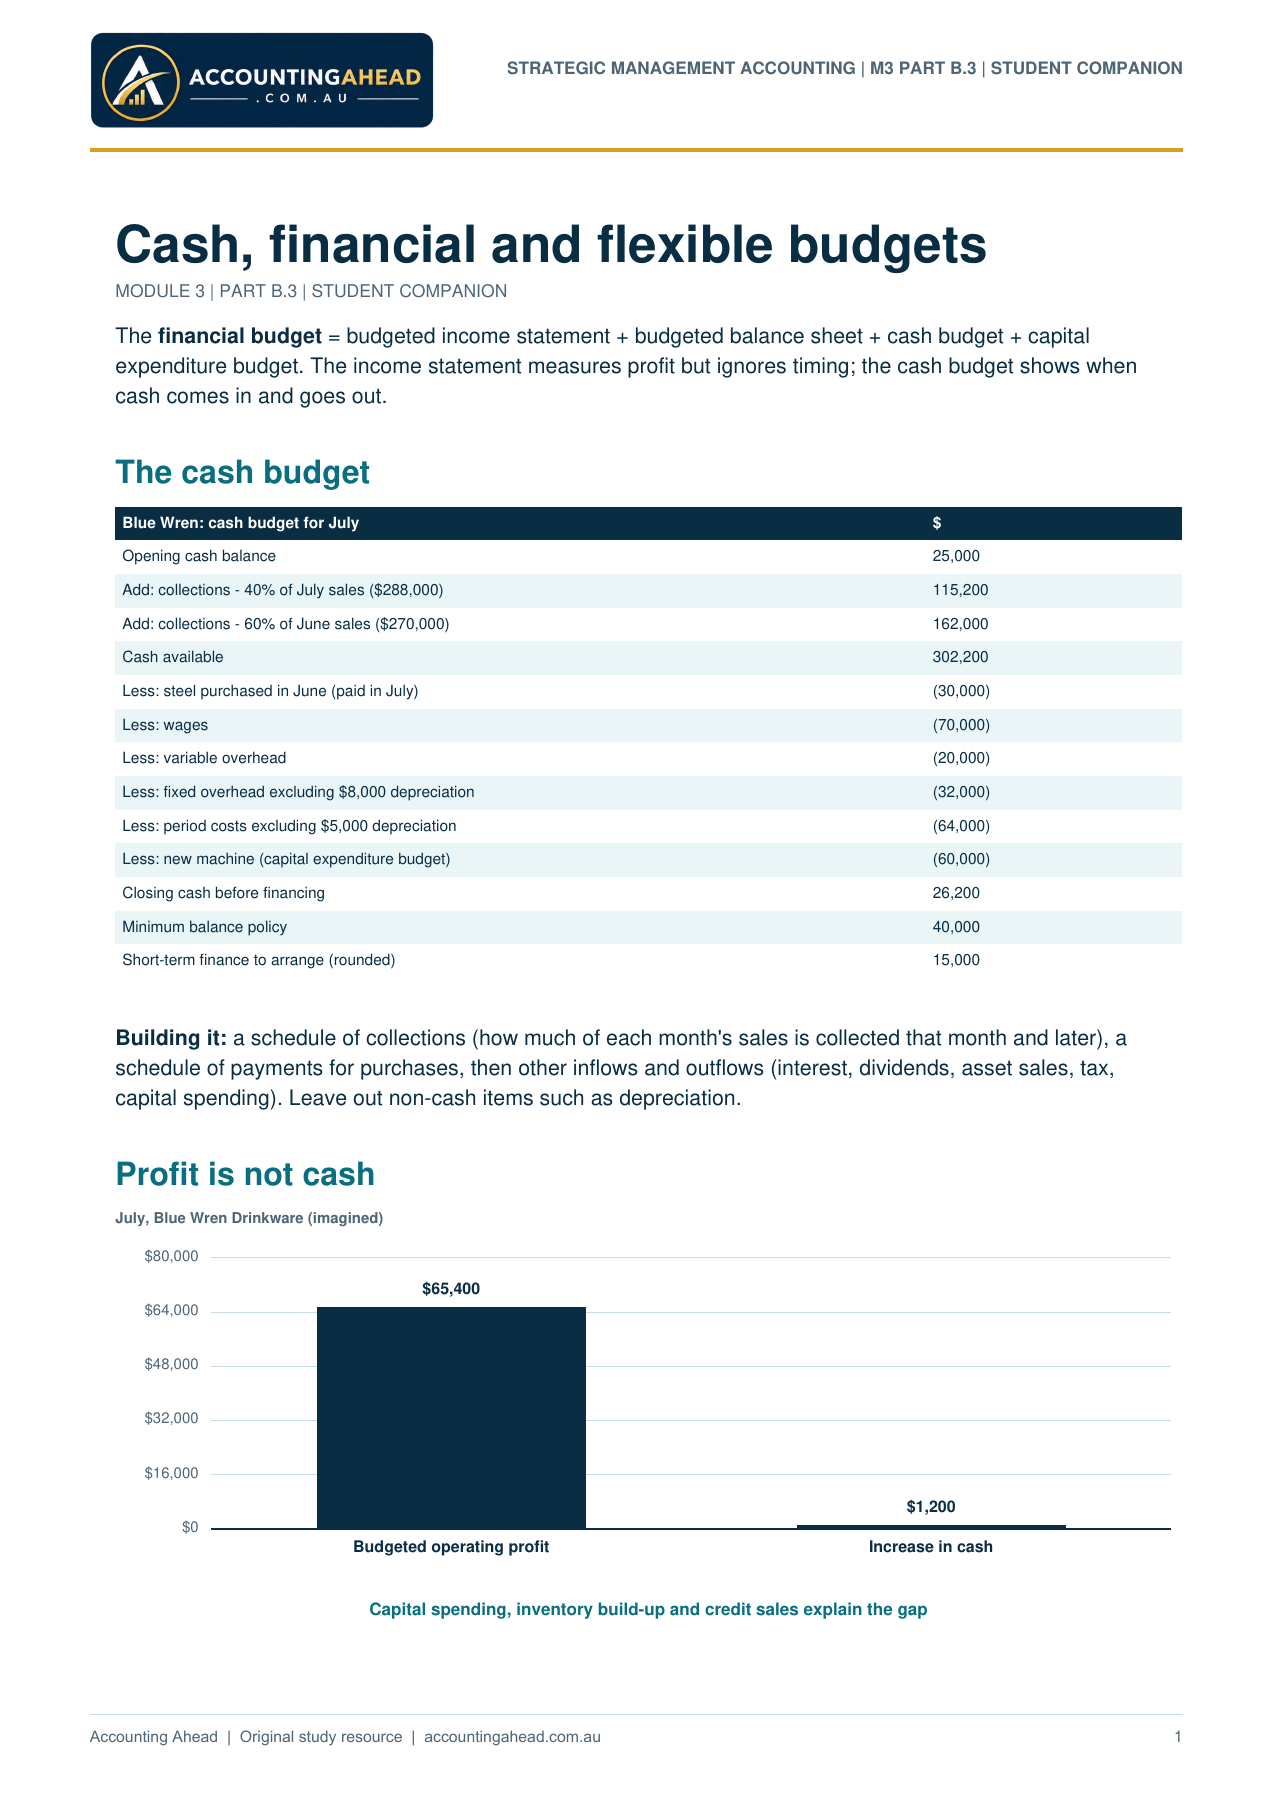
The financial budget = budgeted income statement + budgeted balance sheet + cash budget + capital
expenditure budget. The income statement measures profit but ignores timing; the cash budget shows when
cash comes in and goes out.
The cash budget
Blue Wren: cash budget for July $
Opening cash balance 25,000
Add: collections - 40% of July sales ($288,000) 115,200
Add: collections - 60% of June sales ($270,000) 162,000
Cash available 302,200
Less: steel purchased in June (paid in July) (30,000)
Less: wages (70,000)
Less: variable overhead (20,000)
Less: fixed overhead excluding $8,000 depreciation (32,000)
Less: period costs excluding $5,000 depreciation (64,000)
Less: new machine (capital expenditure budget) (60,000)
Closing cash before financing 26,200
Minimum balance policy 40,000
Short-term finance to arrange (rounded) 15,000
Building it: a schedule of collections (how much of each month's sales is collected that month and later), a
schedule of payments for purchases, then other inflows and outflows (interest, dividends, asset sales, tax,
capital spending). Leave out non-cash items such as depreciation.
Profit is not cash
$0
$16,000
$32,000
$48,000
$64,000
$80,000
$65,400
Budgeted operating profit
$1,200
Increase in cash
July, Blue Wren Drinkware (imagined)
Capital spending, inventory build-up and credit sales explain the gap
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART B.3 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
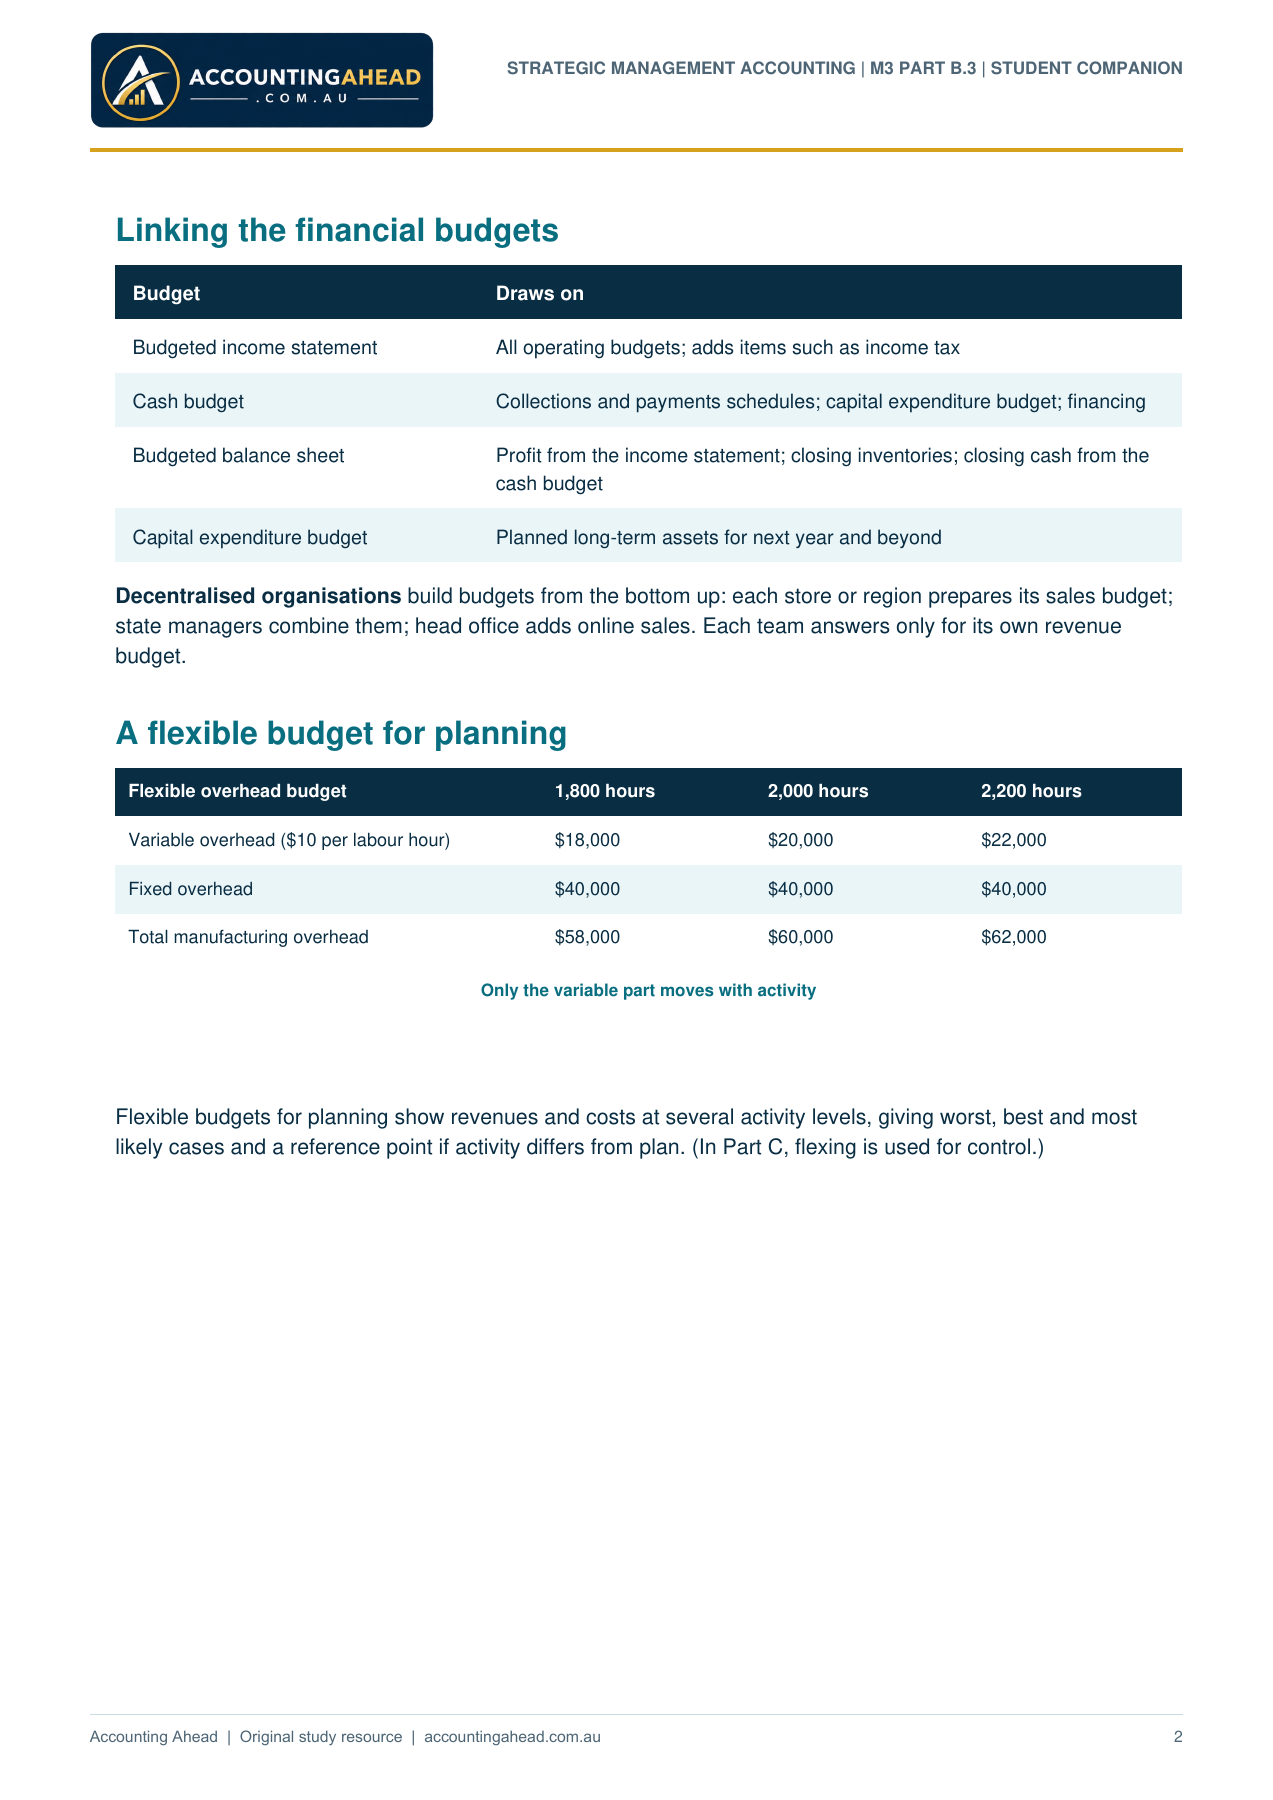
Linking the financial budgets
Budget Draws on
Budgeted income statement All operating budgets; adds items such as income tax
Cash budget Collections and payments schedules; capital expenditure budget; financing
Budgeted balance sheet Profit from the income statement; closing inventories; closing cash from the
cash budget
Capital expenditure budget Planned long-term assets for next year and beyond
Decentralised organisations build budgets from the bottom up: each store or region prepares its sales budget;
state managers combine them; head office adds online sales. Each team answers only for its own revenue
budget.
A flexible budget for planning
Flexible overhead budget 1,800 hours 2,000 hours 2,200 hours
Variable overhead ($10 per labour hour) $18,000 $20,000 $22,000
Fixed overhead $40,000 $40,000 $40,000
Total manufacturing overhead $58,000 $60,000 $62,000
Only the variable part moves with activity
Flexible budgets for planning show revenues and costs at several activity levels, giving worst, best and most
likely cases and a reference point if activity differs from plan. (In Part C, flexing is used for control.)
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART B.3 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
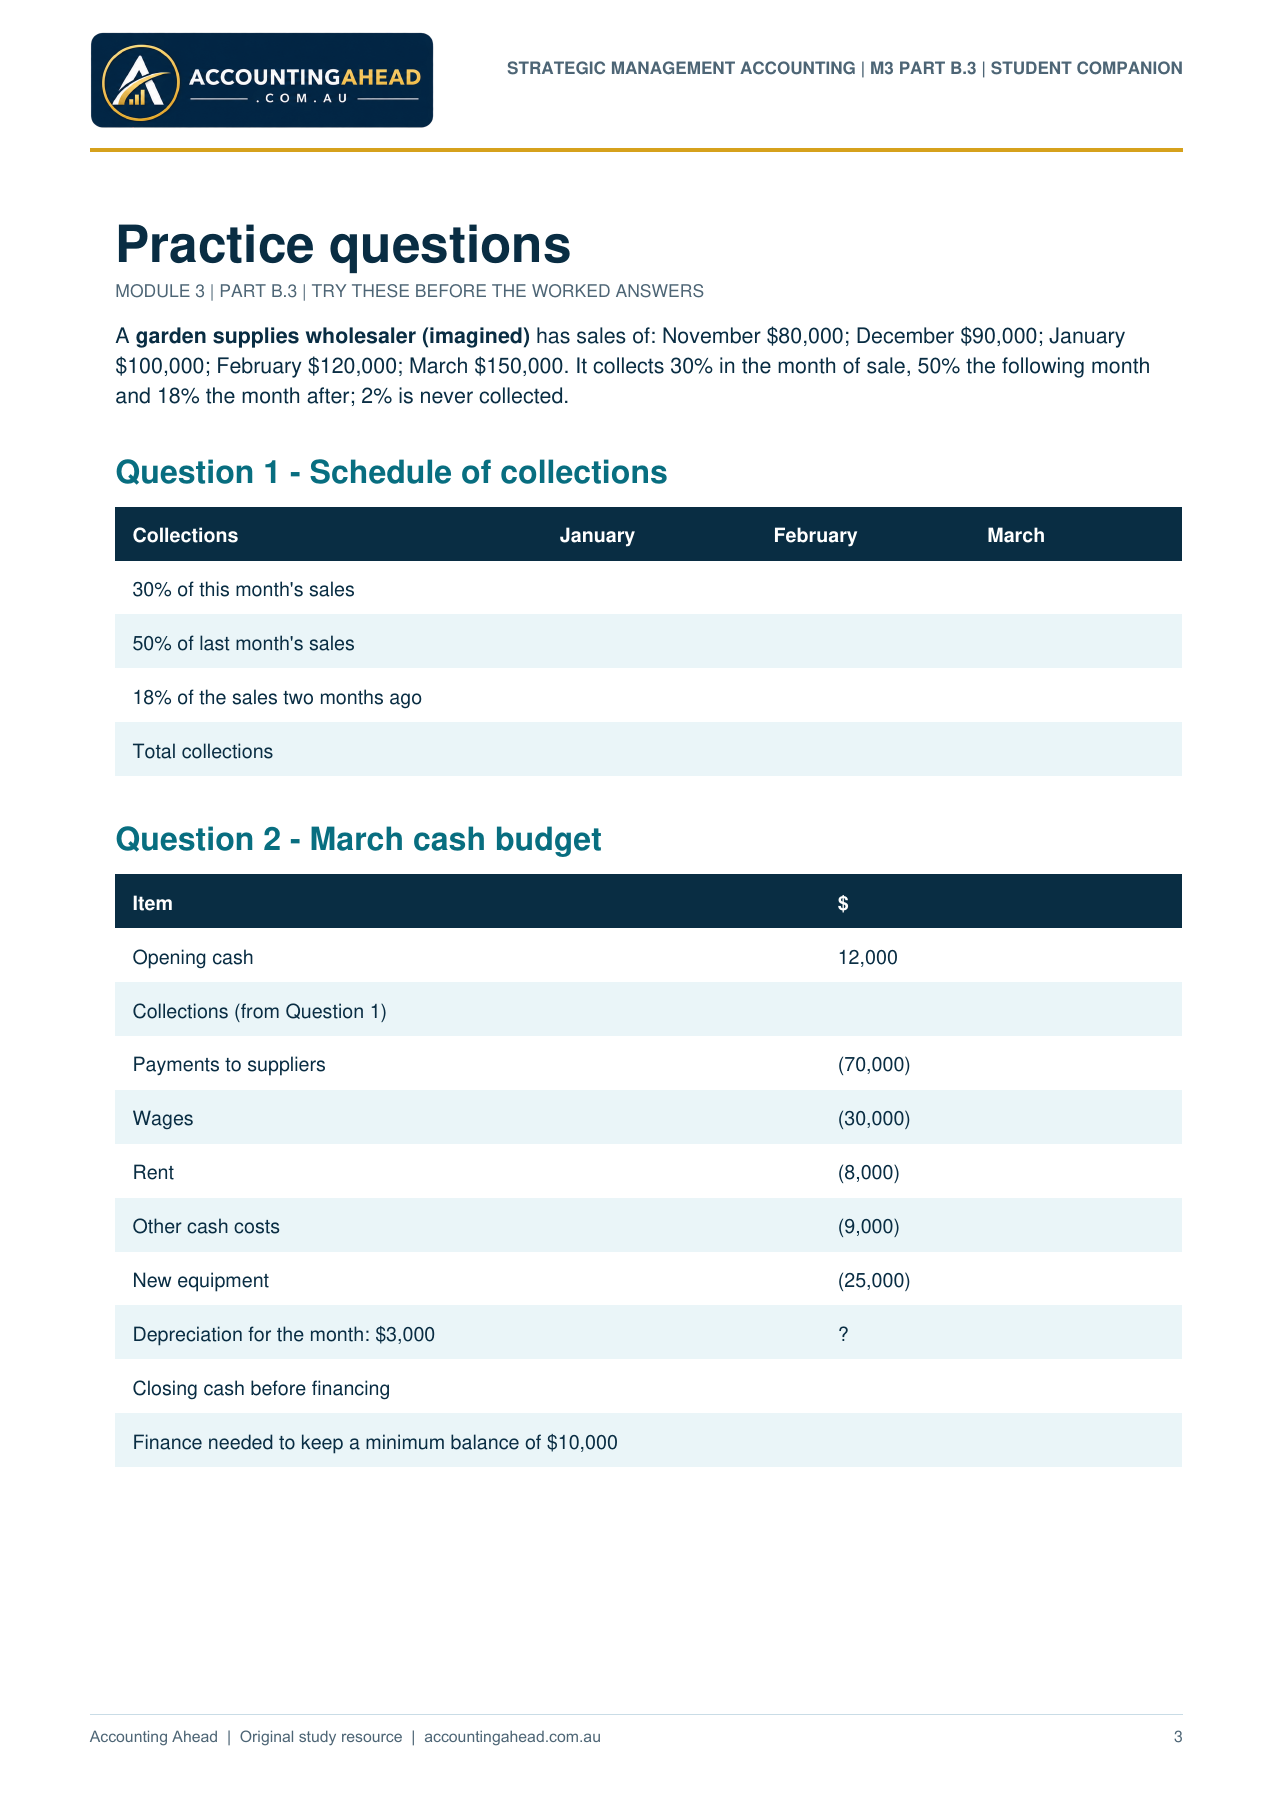
Practice questions
MODULE 3 | PART B.3 | TRY THESE BEFORE THE WORKED ANSWERS
A garden supplies wholesaler (imagined) has sales of: November $80,000; December $90,000; January
$100,000; February $120,000; March $150,000. It collects 30% in the month of sale, 50% the following month
and 18% the month after; 2% is never collected.
Question 1 - Schedule of collections
Collections January February March
30% of this month's sales
50% of last month's sales
18% of the sales two months ago
Total collections
Question 2 - March cash budget
Item $
Opening cash 12,000
Collections (from Question 1)
Payments to suppliers (70,000)
Wages (30,000)
Rent (8,000)
Other cash costs (9,000)
New equipment (25,000)
Depreciation for the month: $3,000 ?
Closing cash before financing
Finance needed to keep a minimum balance of $10,000
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART B.3 | STUDENT COMPANION
3
Accounting Ahead | Original study resource | accountingahead.com.au
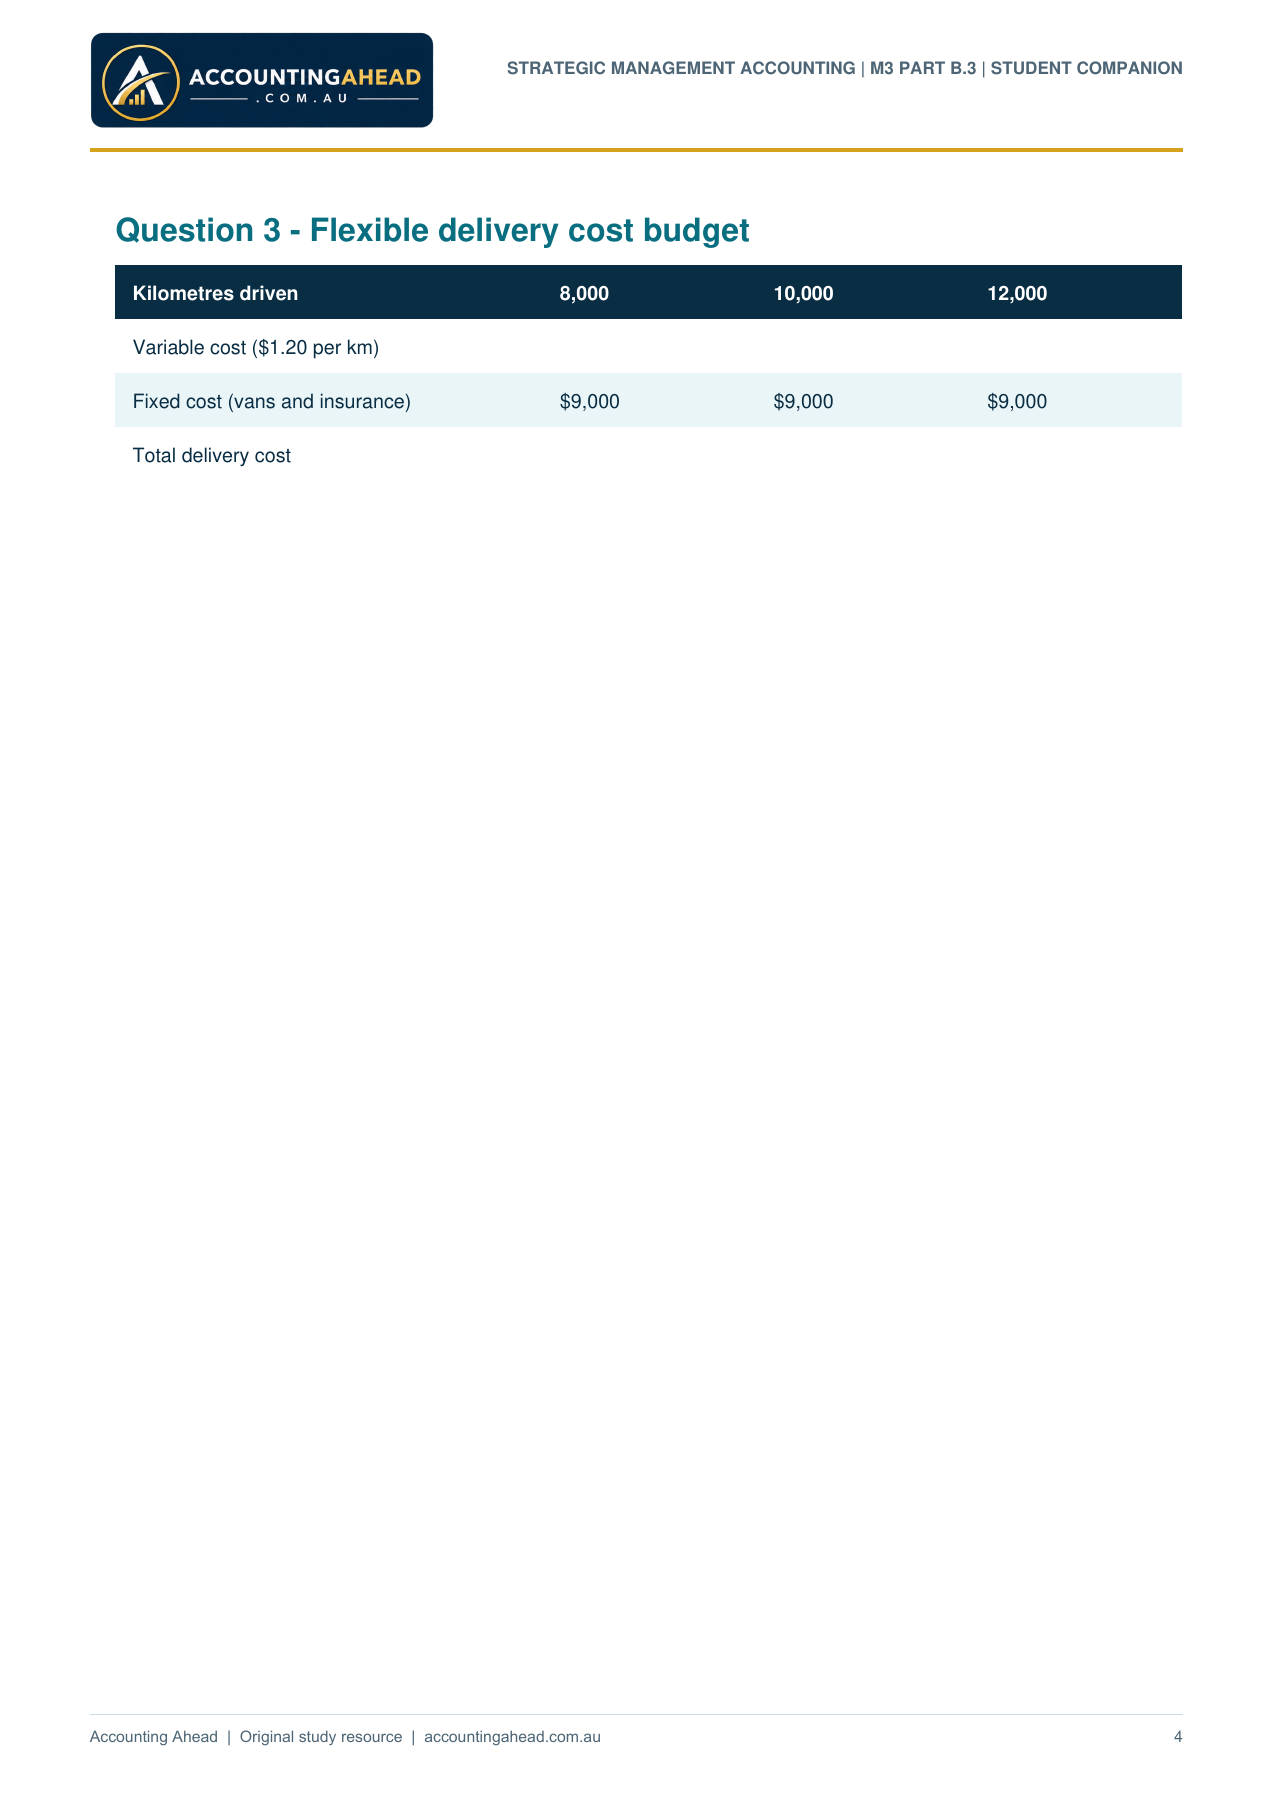
Question 3 - Flexible delivery cost budget
Kilometres driven 8,000 10,000 12,000
Variable cost ($1.20 per km)
Fixed cost (vans and insurance) $9,000 $9,000 $9,000
Total delivery cost
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART B.3 | STUDENT COMPANION
4
Accounting Ahead | Original study resource | accountingahead.com.au
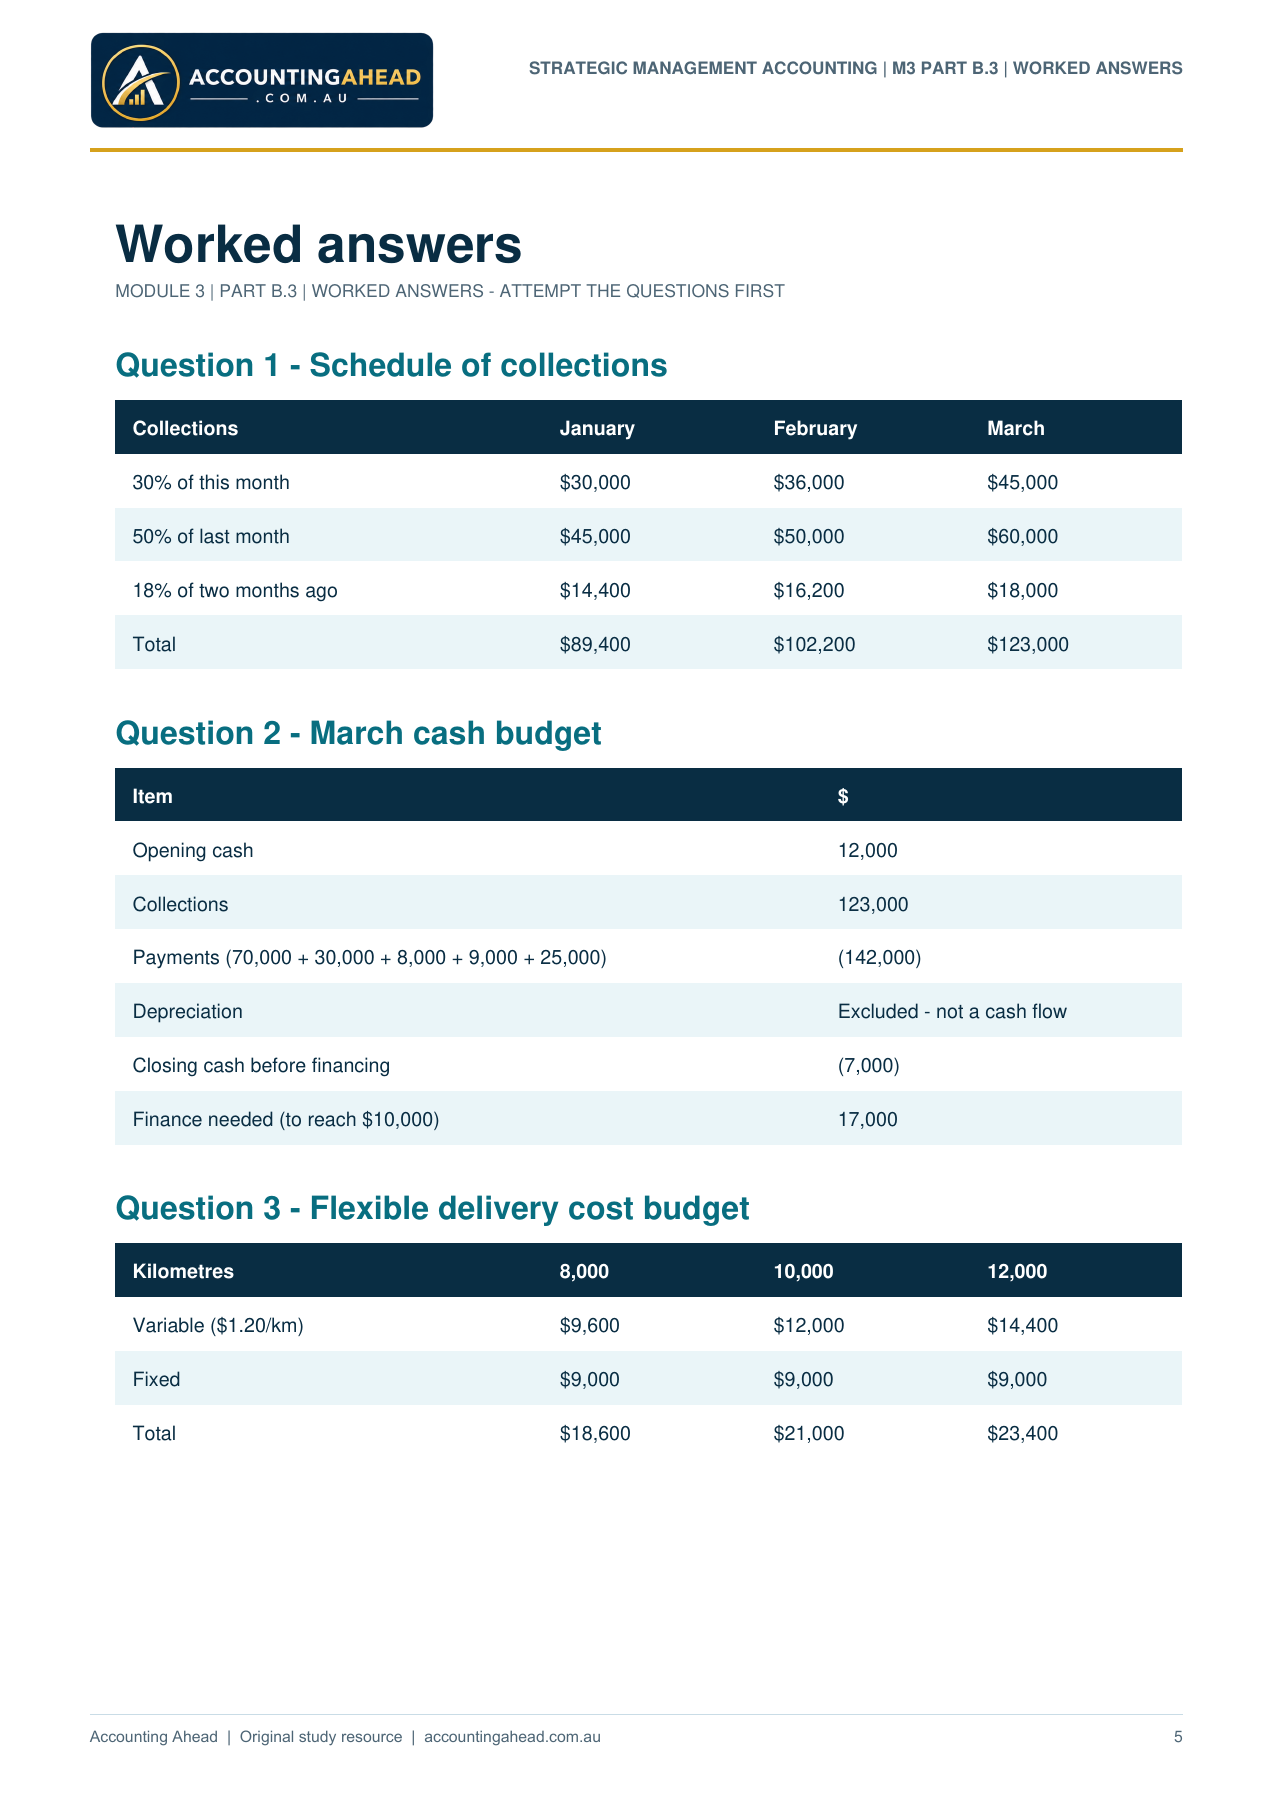
Worked answers
MODULE 3 | PART B.3 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
Question 1 - Schedule of collections
Collections January February March
30% of this month $30,000 $36,000 $45,000
50% of last month $45,000 $50,000 $60,000
18% of two months ago $14,400 $16,200 $18,000
Total $89,400 $102,200 $123,000
Question 2 - March cash budget
Item $
Opening cash 12,000
Collections 123,000
Payments (70,000 + 30,000 + 8,000 + 9,000 + 25,000) (142,000)
Depreciation Excluded - not a cash flow
Closing cash before financing (7,000)
Finance needed (to reach $10,000) 17,000
Question 3 - Flexible delivery cost budget
Kilometres 8,000 10,000 12,000
Variable ($1.20/km) $9,600 $12,000 $14,400
Fixed $9,000 $9,000 $9,000
Total $18,600 $21,000 $23,400
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART B.3 | WORKED ANSWERS
5