
Variance 2: direct material price and efficiency
Printable study notes to use alongside Part C.2.2.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
Variance 2: direct material price and
efficiency
MODULE 3 | PART C.2.2 | STUDENT COMPANION
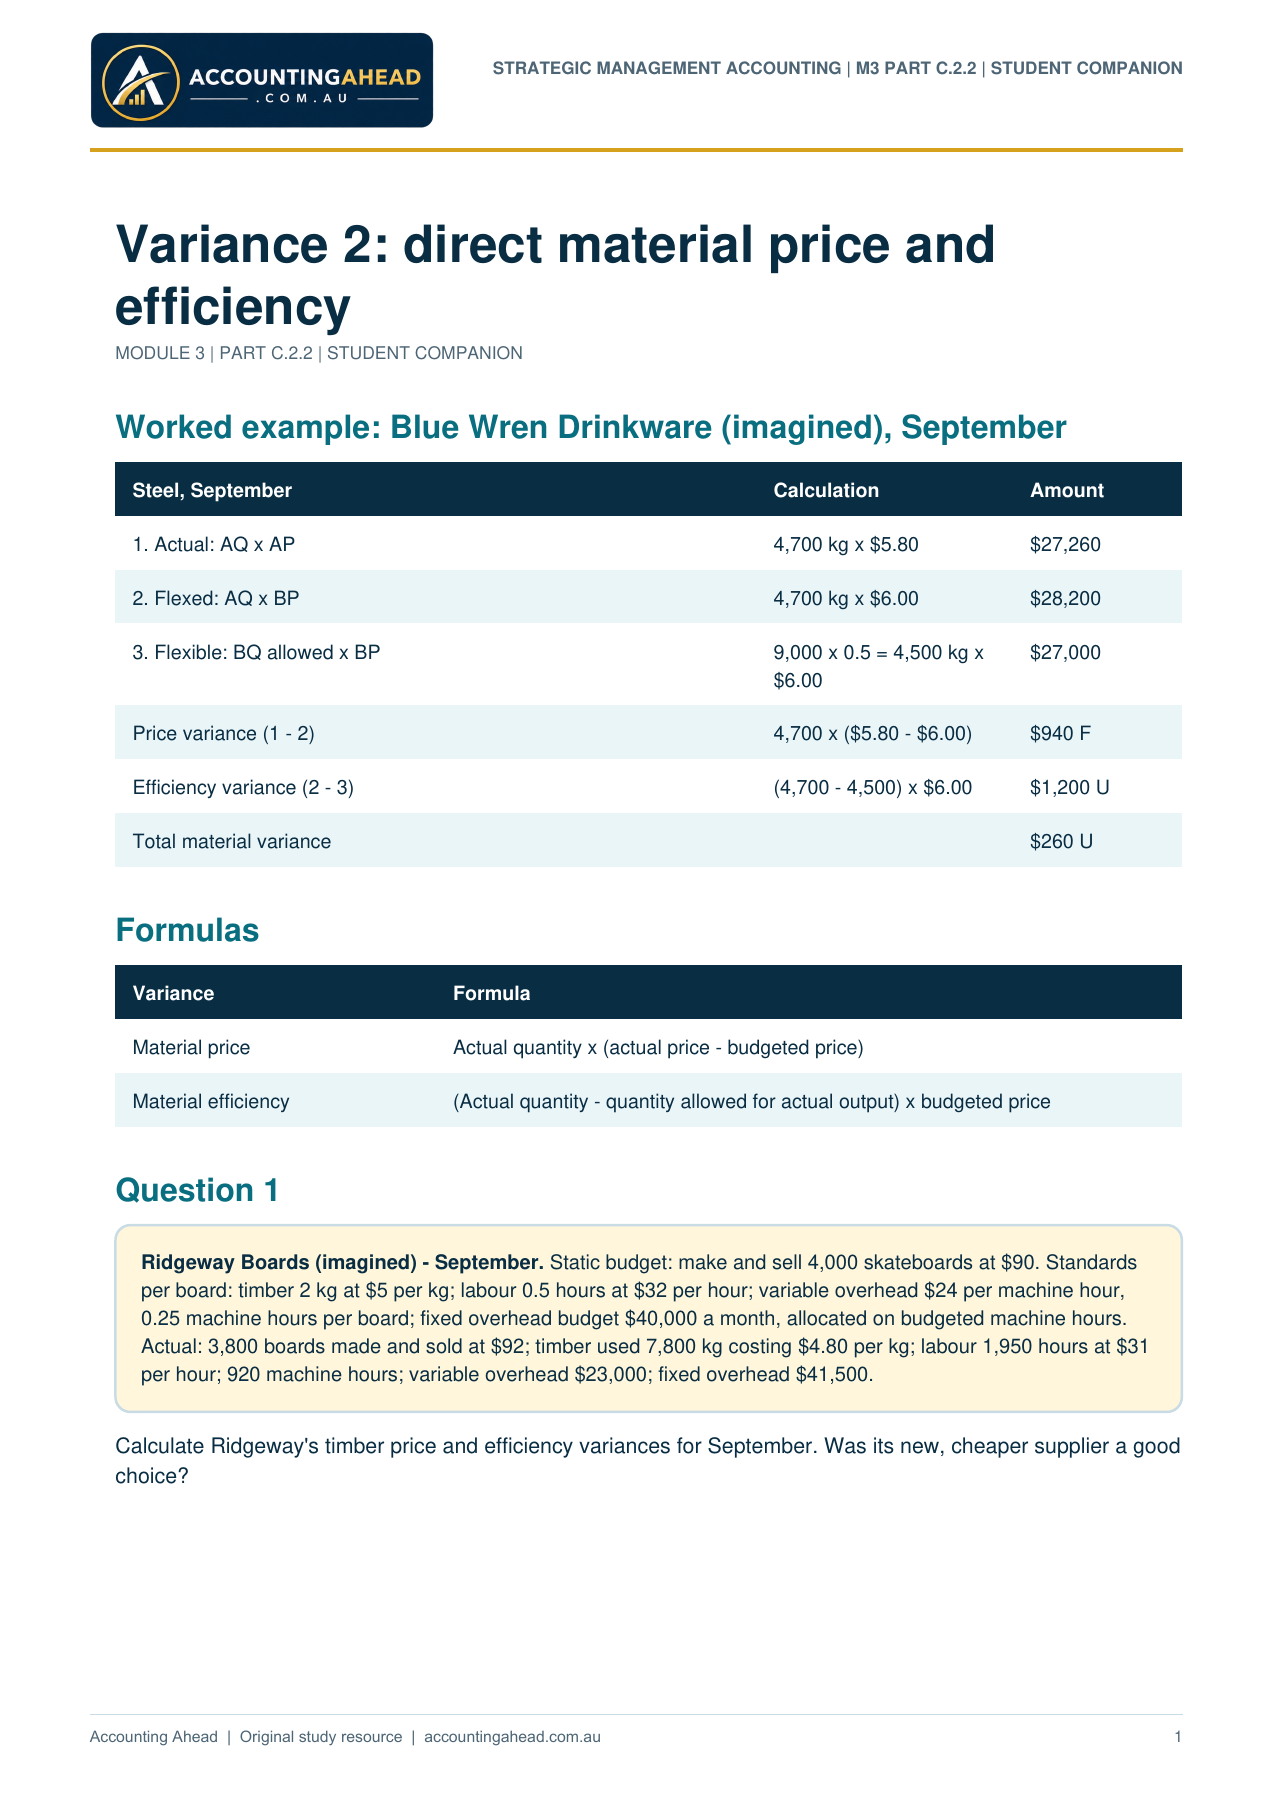
Worked example: Blue Wren Drinkware (imagined), September
Steel, September Calculation Amount
1. Actual: AQ x AP 4,700 kg x $5.80 $27,260
2. Flexed: AQ x BP 4,700 kg x $6.00 $28,200
3. Flexible: BQ allowed x BP 9,000 x 0.5 = 4,500 kg x
$6.00
$27,000
Price variance (1 - 2) 4,700 x ($5.80 - $6.00) $940 F
Efficiency variance (2 - 3) (4,700 - 4,500) x $6.00 $1,200 U
Total material variance $260 U
Formulas
Variance Formula
Material price Actual quantity x (actual price - budgeted price)
Material efficiency (Actual quantity - quantity allowed for actual output) x budgeted price
Question 1
Ridgeway Boards (imagined) - September. Static budget: make and sell 4,000 skateboards at $90. Standards
per board: timber 2 kg at $5 per kg; labour 0.5 hours at $32 per hour; variable overhead $24 per machine hour,
0.25 machine hours per board; fixed overhead budget $40,000 a month, allocated on budgeted machine hours.
Actual: 3,800 boards made and sold at $92; timber used 7,800 kg costing $4.80 per kg; labour 1,950 hours at $31
per hour; 920 machine hours; variable overhead $23,000; fixed overhead $41,500.
Calculate Ridgeway's timber price and efficiency variances for September. Was its new, cheaper supplier a good
choice?
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART C.2.2 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART C.2.2 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
Worked answers
MODULE 3 | PART C.2.2 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
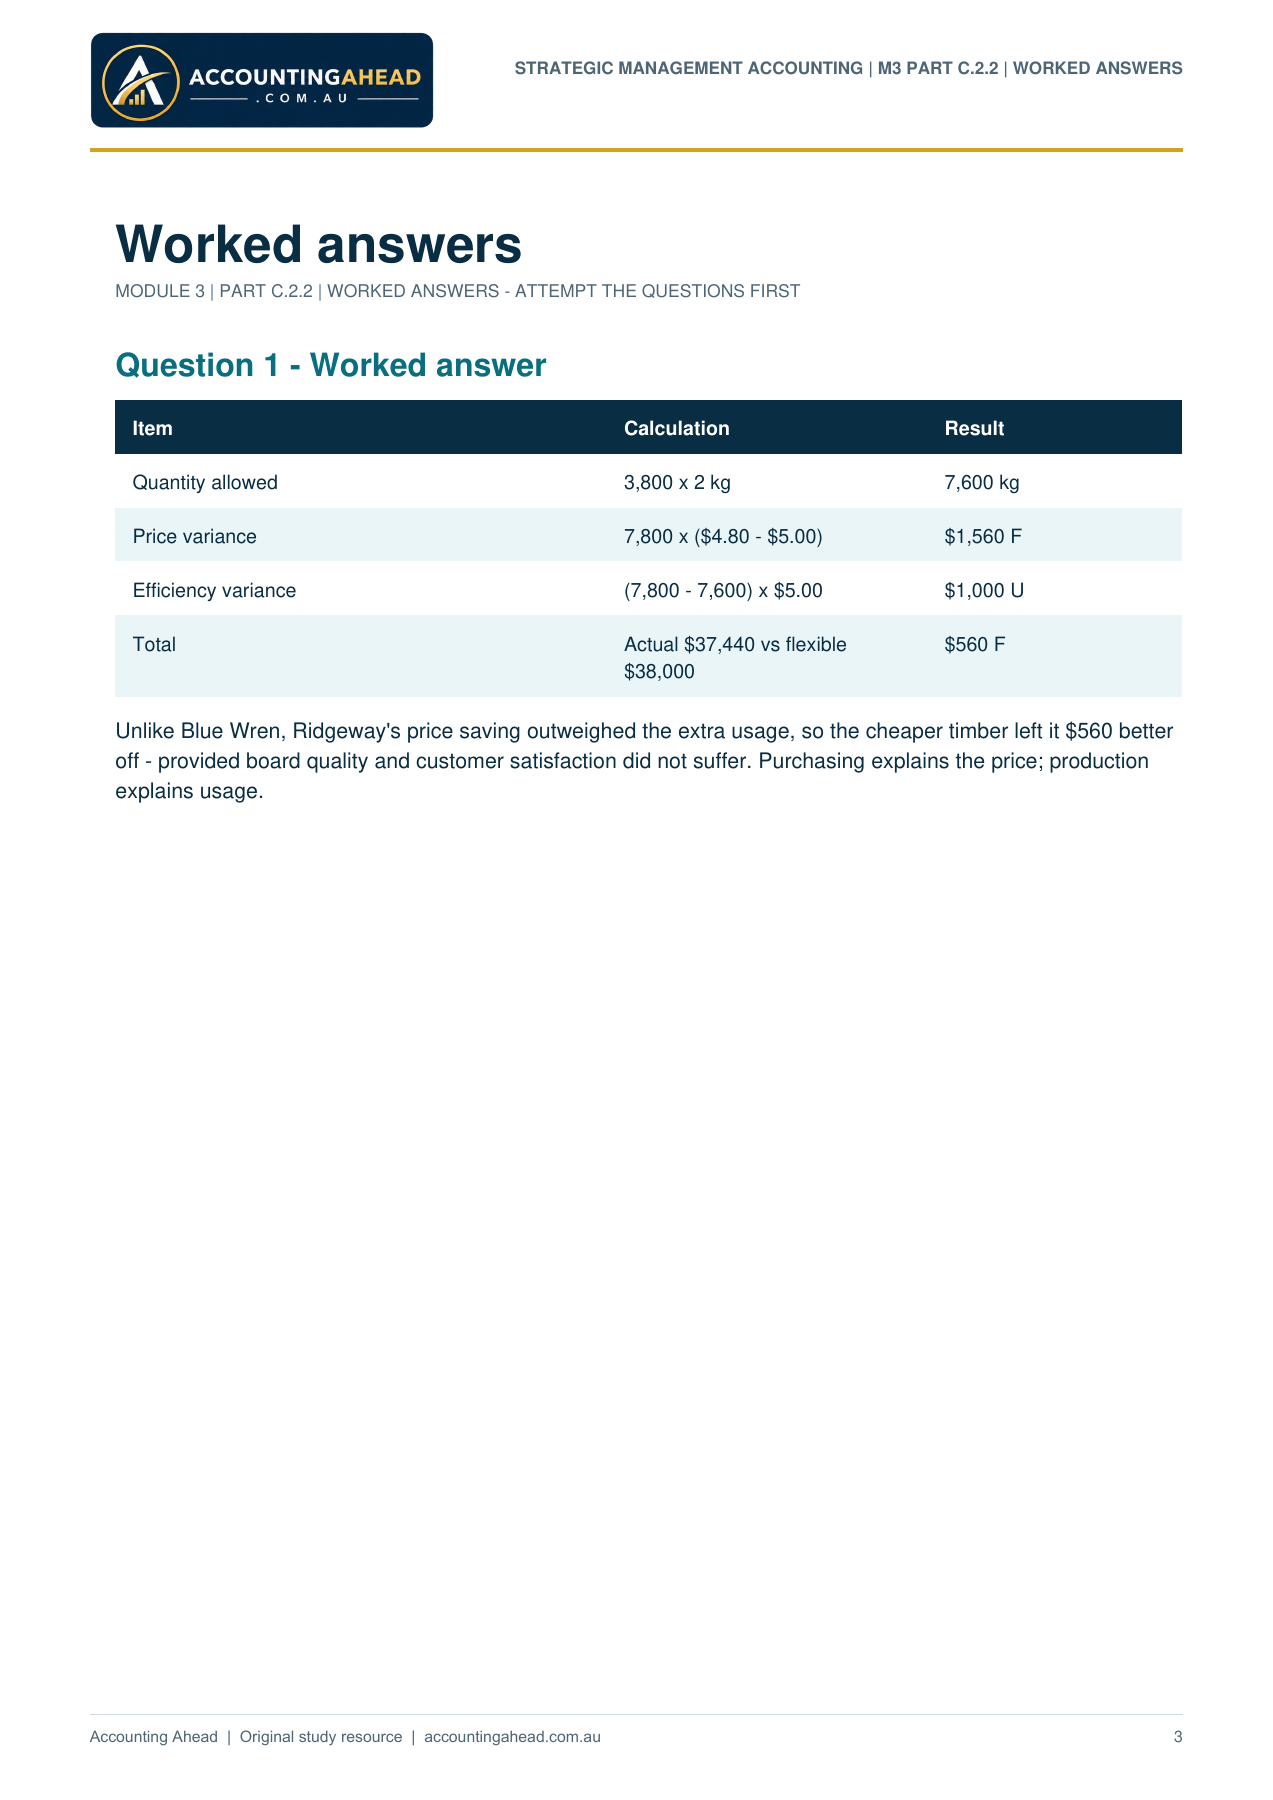
Question 1 - Worked answer
Item Calculation Result
Quantity allowed 3,800 x 2 kg 7,600 kg
Price variance 7,800 x ($4.80 - $5.00) $1,560 F
Efficiency variance (7,800 - 7,600) x $5.00 $1,000 U
Total Actual $37,440 vs flexible
$38,000
$560 F
Unlike Blue Wren, Ridgeway's price saving outweighed the extra usage, so the cheaper timber left it $560 better
off - provided board quality and customer satisfaction did not suffer. Purchasing explains the price; production
explains usage.
STRATEGIC MANAGEMENT ACCOUNTING | M3 PART C.2.2 | WORKED ANSWERS
3