
Getting the cash flows right
Printable study notes to use alongside Part C.3.2.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
Getting the cash flows right
MODULE 4 | PART C.3.2 | STUDENT COMPANION
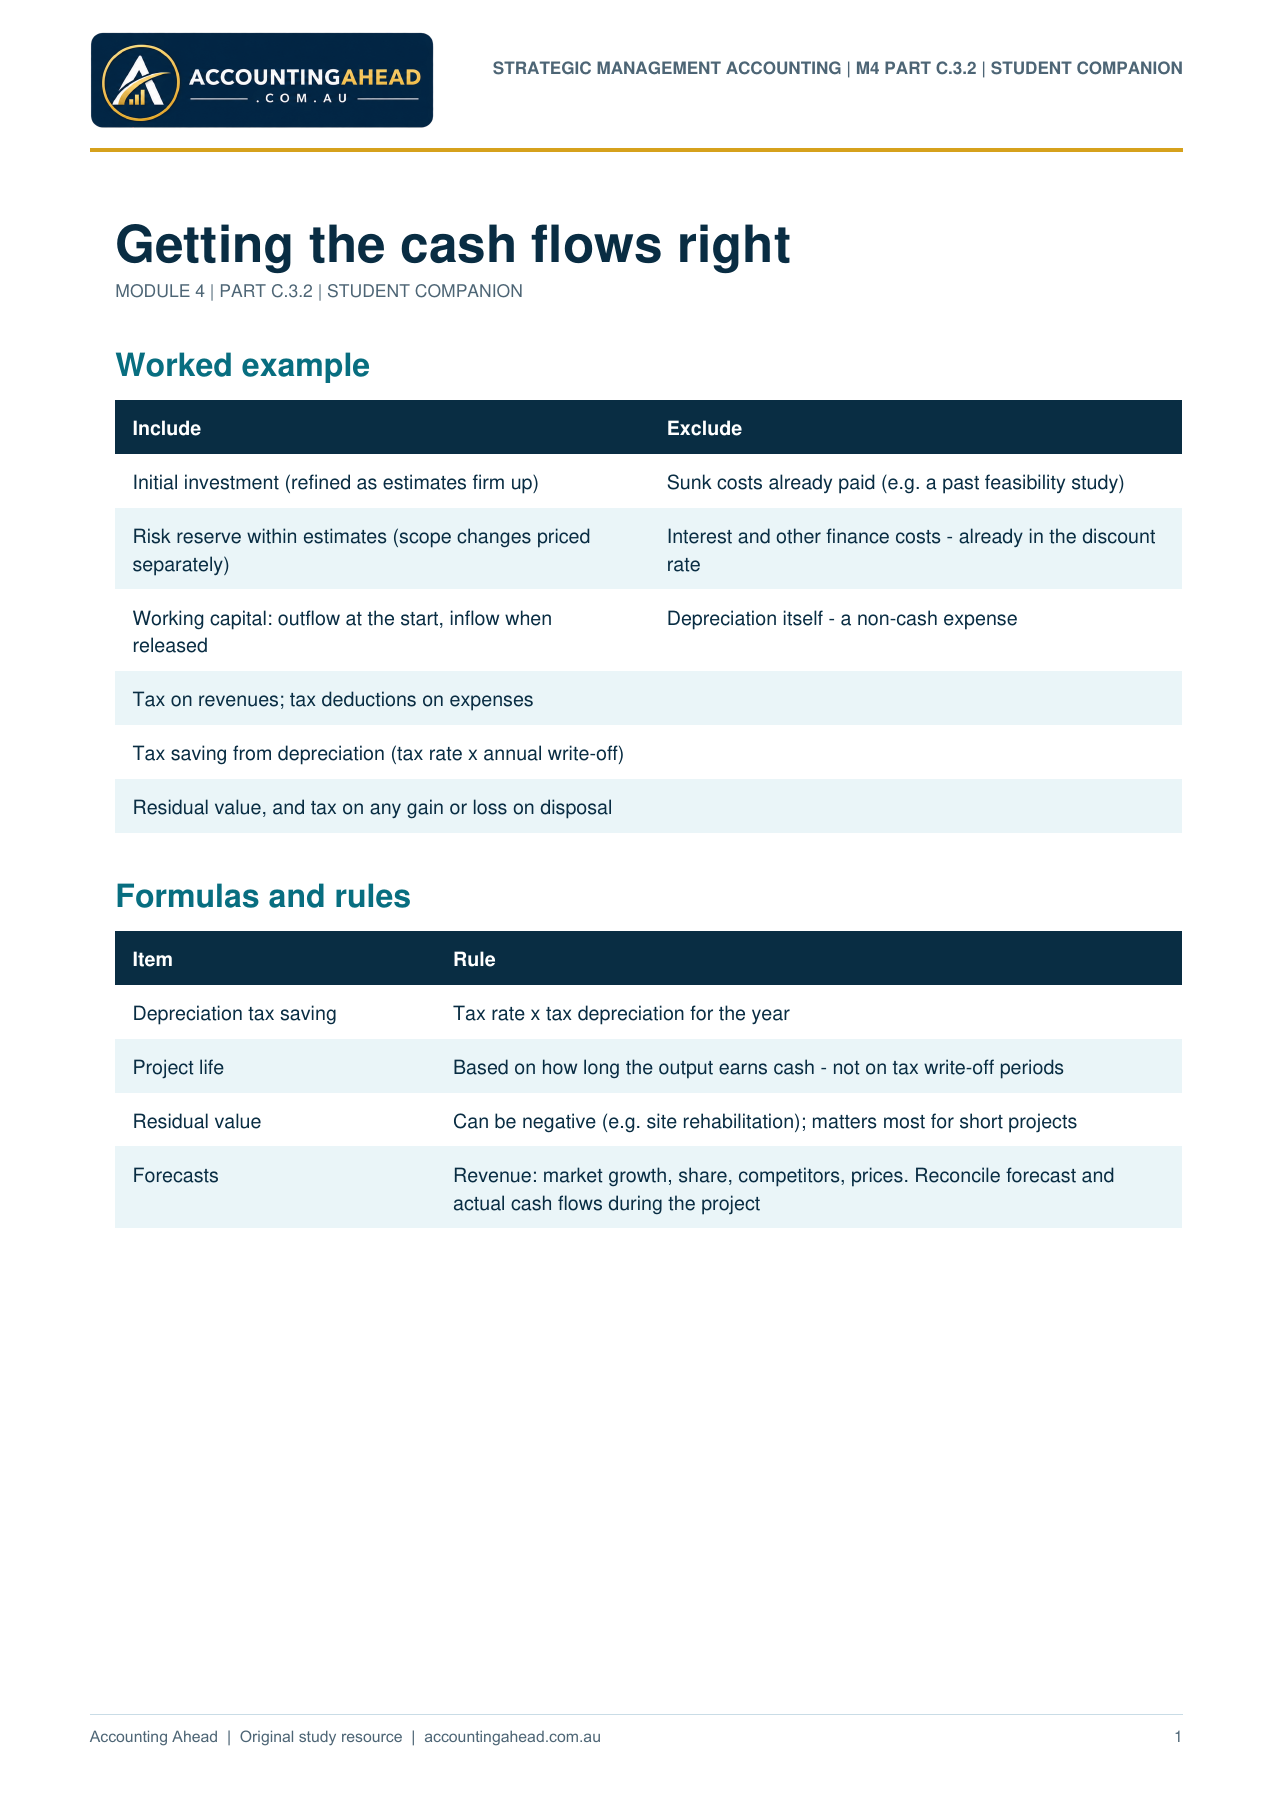
Worked example
Include Exclude
Initial investment (refined as estimates firm up) Sunk costs already paid (e.g. a past feasibility study)
Risk reserve within estimates (scope changes priced
separately)
Interest and other finance costs - already in the discount
rate
Working capital: outflow at the start, inflow when
released
Depreciation itself - a non-cash expense
Tax on revenues; tax deductions on expenses
Tax saving from depreciation (tax rate x annual write-off)
Residual value, and tax on any gain or loss on disposal
Formulas and rules
Item Rule
Depreciation tax saving Tax rate x tax depreciation for the year
Project life Based on how long the output earns cash - not on tax write-off periods
Residual value Can be negative (e.g. site rehabilitation); matters most for short projects
Forecasts Revenue: market growth, share, competitors, prices. Reconcile forecast and
actual cash flows during the project
STRATEGIC MANAGEMENT ACCOUNTING | M4 PART C.3.2 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
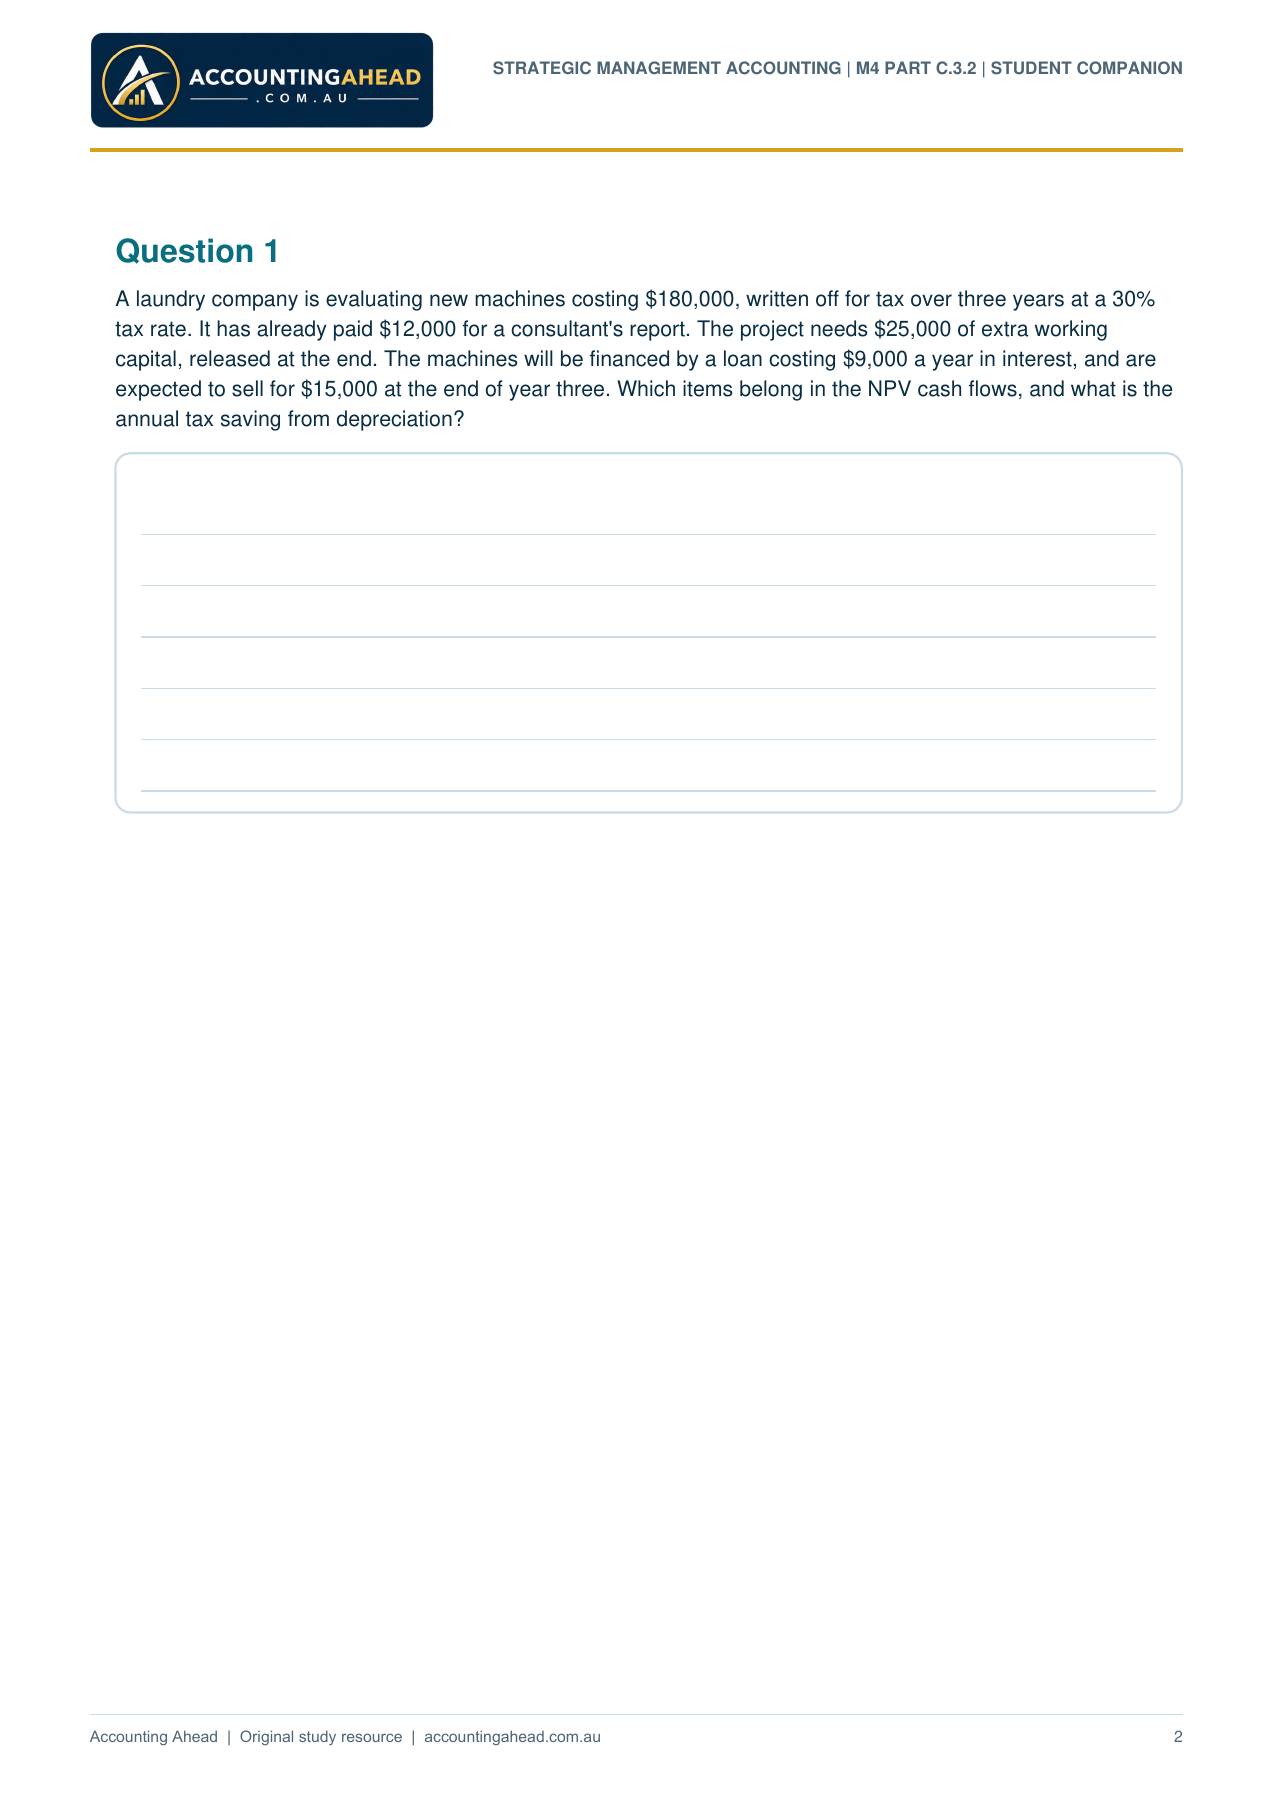
Question 1
A laundry company is evaluating new machines costing $180,000, written off for tax over three years at a 30%
tax rate. It has already paid $12,000 for a consultant's report. The project needs $25,000 of extra working
capital, released at the end. The machines will be financed by a loan costing $9,000 a year in interest, and are
expected to sell for $15,000 at the end of year three. Which items belong in the NPV cash flows, and what is the
annual tax saving from depreciation?
STRATEGIC MANAGEMENT ACCOUNTING | M4 PART C.3.2 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
Worked answers
MODULE 4 | PART C.3.2 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
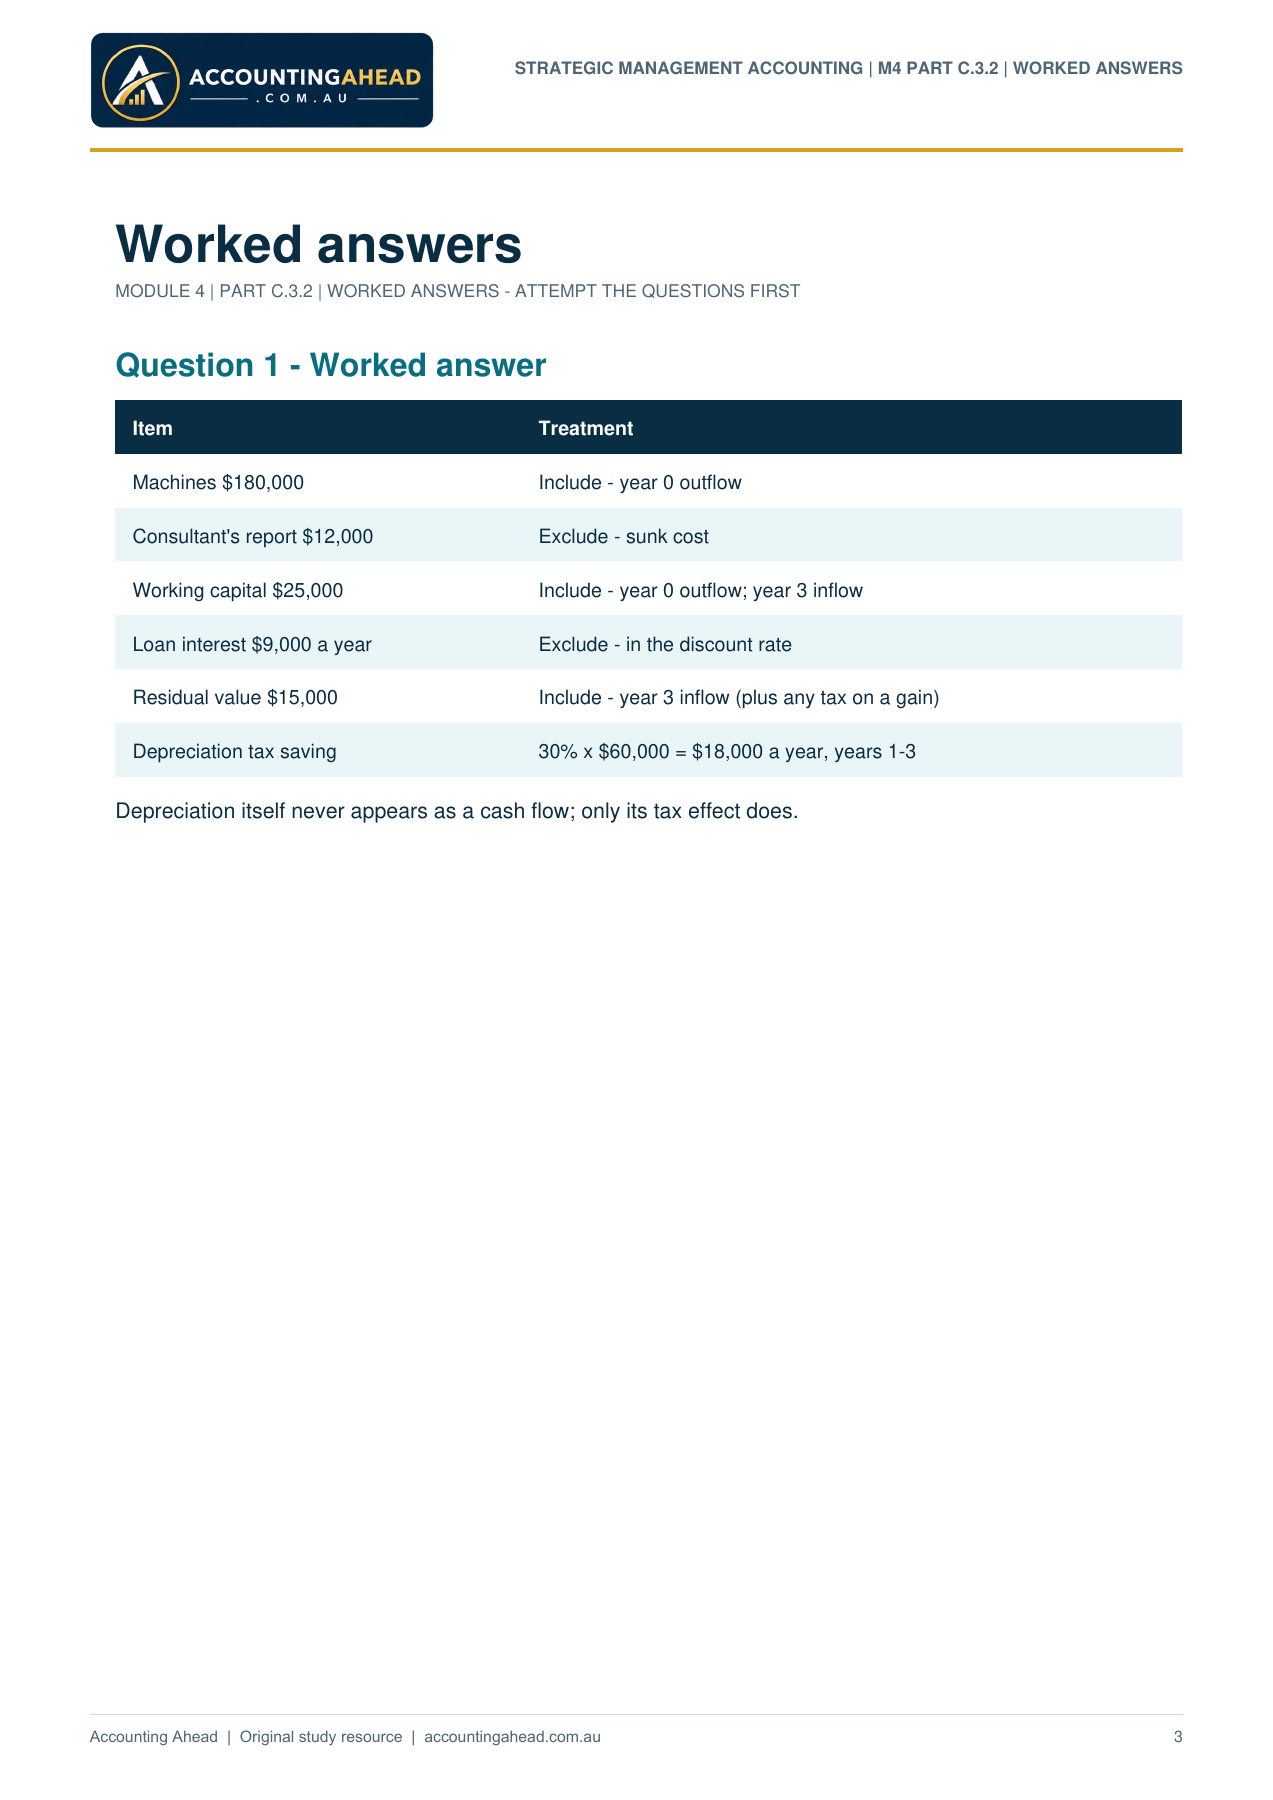
Question 1 - Worked answer
Item Treatment
Machines $180,000 Include - year 0 outflow
Consultant's report $12,000 Exclude - sunk cost
Working capital $25,000 Include - year 0 outflow; year 3 inflow
Loan interest $9,000 a year Exclude - in the discount rate
Residual value $15,000 Include - year 3 inflow (plus any tax on a gain)
Depreciation tax saving 30% x $60,000 = $18,000 a year, years 1-3
Depreciation itself never appears as a cash flow; only its tax effect does.
STRATEGIC MANAGEMENT ACCOUNTING | M4 PART C.3.2 | WORKED ANSWERS
3