
Types of assurance engagements
Printable study notes, diagrams and practice support for Part 1.3.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
Types of assurance engagements
MODULE 1 | 1.3 | STUDENT COMPANION
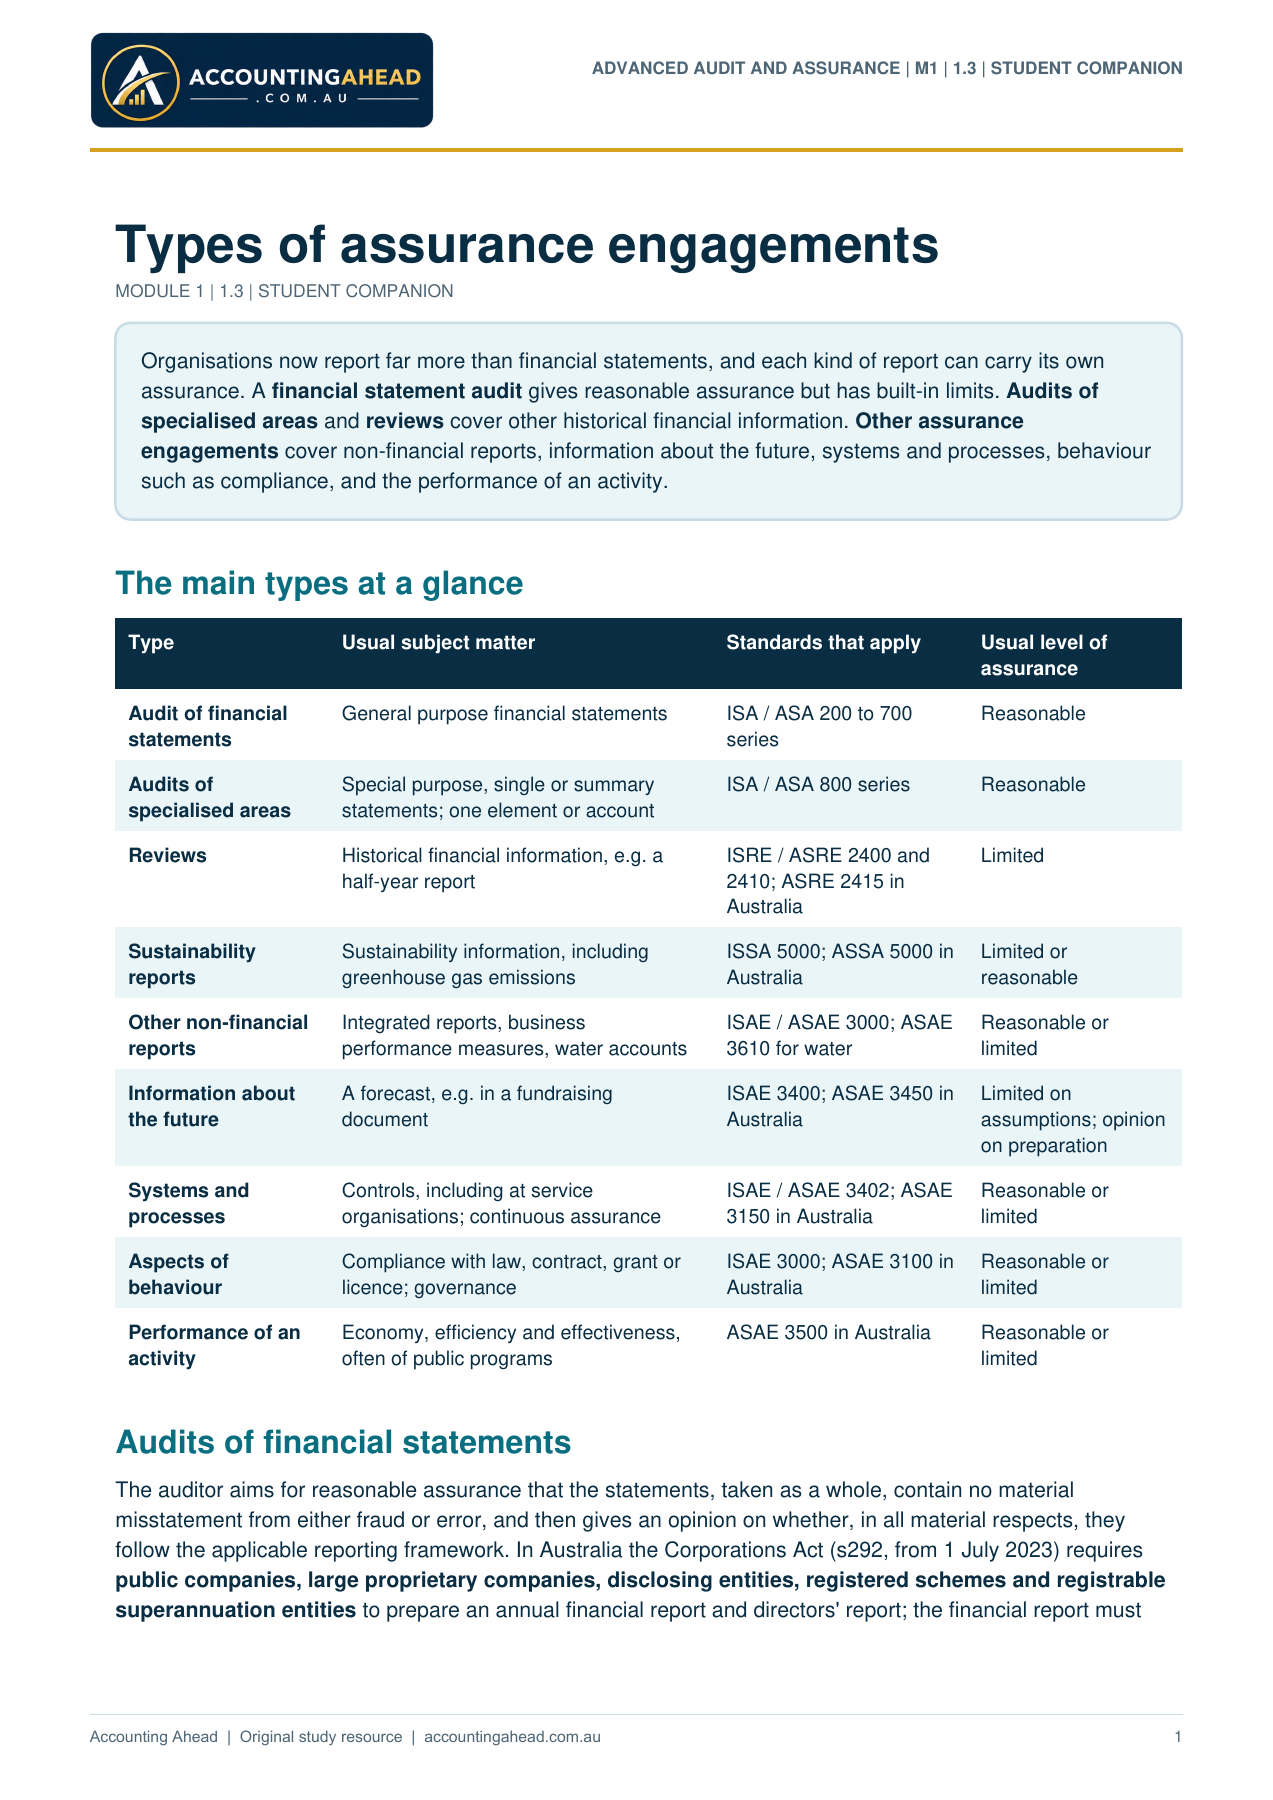
Organisations now report far more than financial statements, and each kind of report can carry its own
assurance. A financial statement audit gives reasonable assurance but has built-in limits. Audits of
specialised areas and reviews cover other historical financial information. Other assurance
engagements cover non-financial reports, information about the future, systems and processes, behaviour
such as compliance, and the performance of an activity.
The main types at a glance
Type Usual subject matter Standards that apply Usual level of
assurance
Audit of financial
statements
General purpose financial statements ISA / ASA 200 to 700
series
Reasonable
Audits of
specialised areas
Special purpose, single or summary
statements; one element or account
ISA / ASA 800 series Reasonable
Reviews Historical financial information, e.g. a
half-year report
ISRE / ASRE 2400 and
2410; ASRE 2415 in
Australia
Limited
Sustainability
reports
Sustainability information, including
greenhouse gas emissions
ISSA 5000; ASSA 5000 in
Australia
Limited or
reasonable
Other non-financial
reports
Integrated reports, business
performance measures, water accounts
ISAE / ASAE 3000; ASAE
3610 for water
Reasonable or
limited
Information about
the future
A forecast, e.g. in a fundraising
document
ISAE 3400; ASAE 3450 in
Australia
Limited on
assumptions; opinion
on preparation
Systems and
processes
Controls, including at service
organisations; continuous assurance
ISAE / ASAE 3402; ASAE
3150 in Australia
Reasonable or
limited
Aspects of
behaviour
Compliance with law, contract, grant or
licence; governance
ISAE 3000; ASAE 3100 in
Australia
Reasonable or
limited
Performance of an
activity
Economy, efficiency and effectiveness,
often of public programs
ASAE 3500 in Australia Reasonable or
limited
Audits of financial statements
The auditor aims for reasonable assurance that the statements, taken as a whole, contain no material
misstatement from either fraud or error, and then gives an opinion on whether, in all material respects, they
follow the applicable reporting framework. In Australia the Corporations Act (s292, from 1 July 2023) requires
public companies, large proprietary companies, disclosing entities, registered schemes and registrable
superannuation entities to prepare an annual financial report and directors' report; the financial report must
ADVANCED AUDIT AND ASSURANCE | M1 | 1.3 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
comply with the accounting standards and give a true and fair view, and the auditor must be independent and
follow the auditing standards.
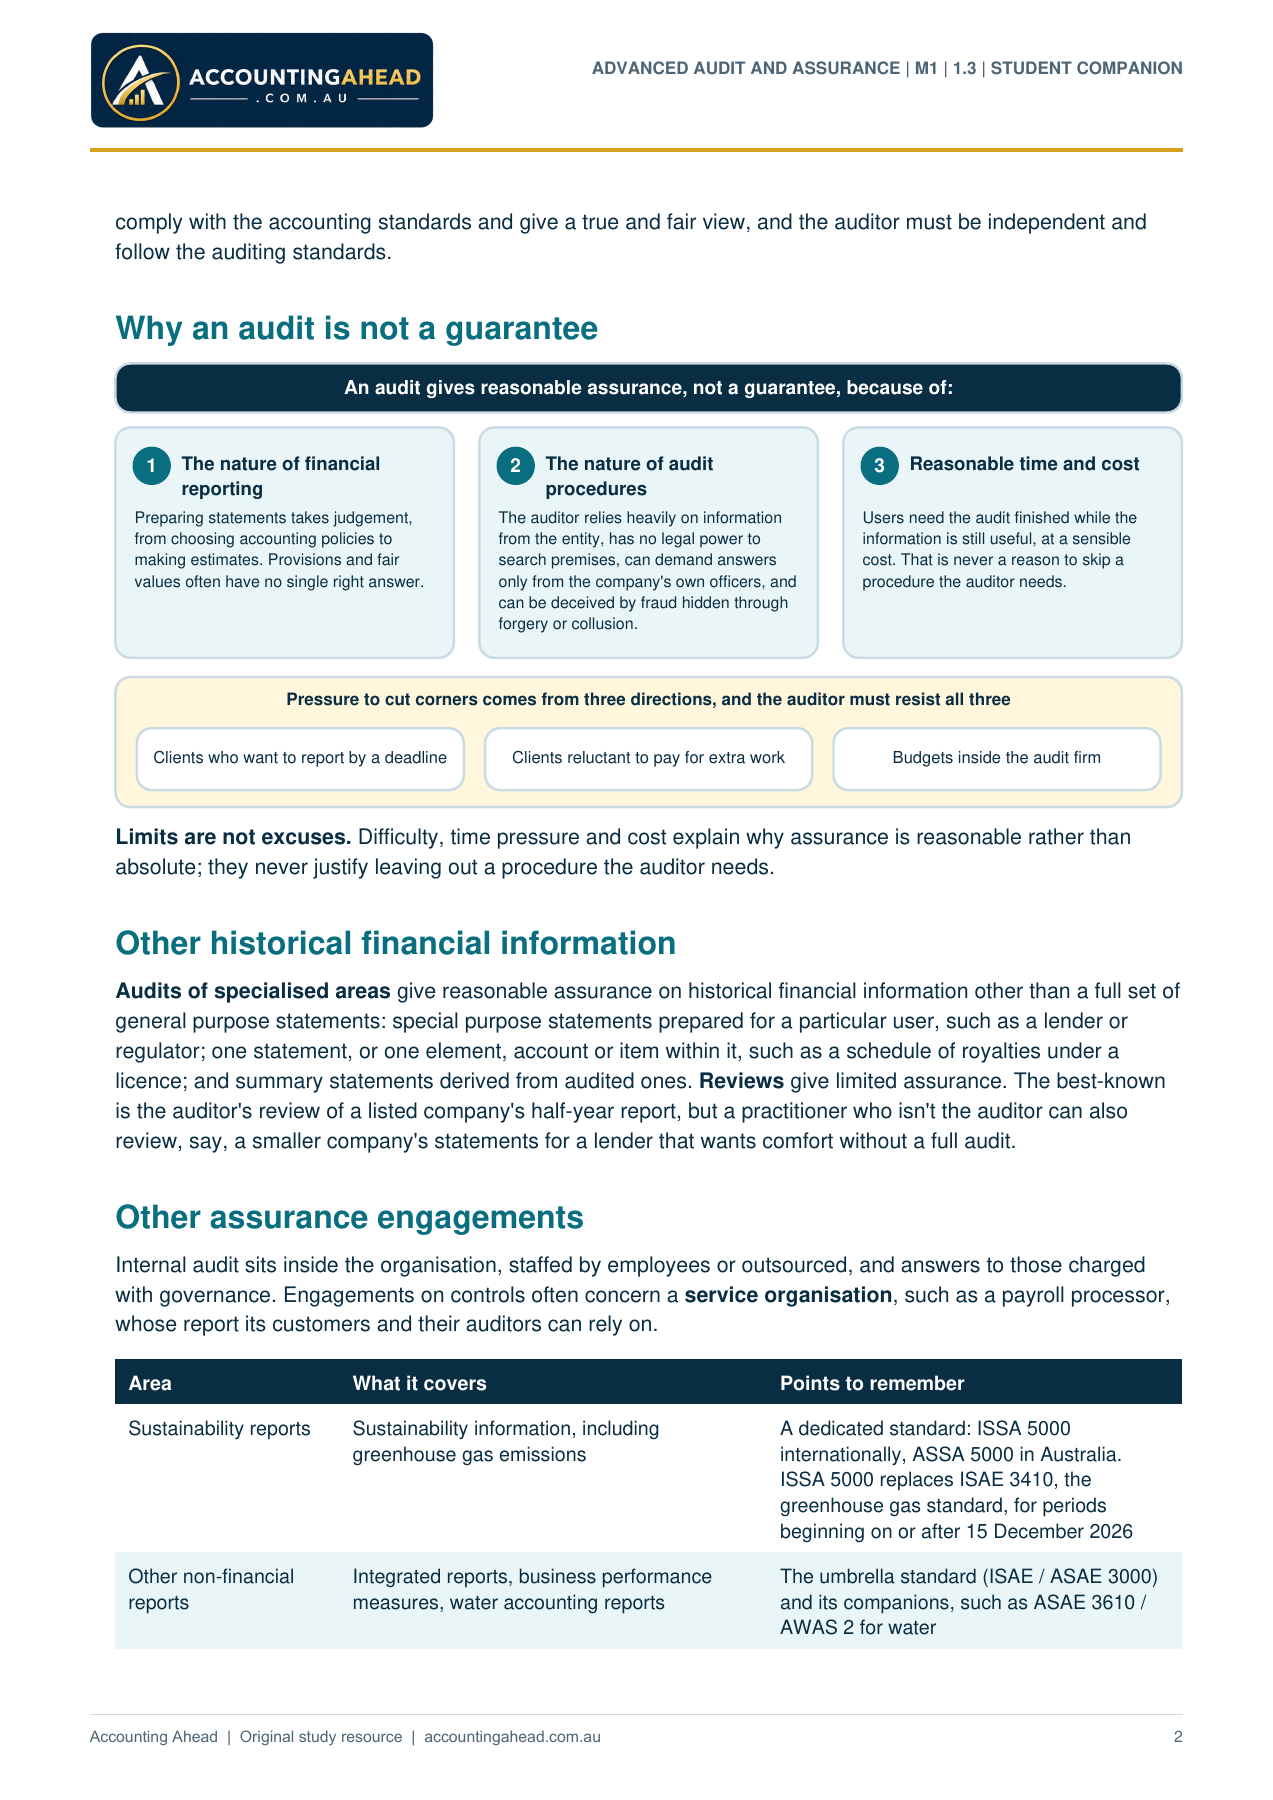
Why an audit is not a guarantee
An audit gives reasonable assurance, not a guarantee, because of:
1 The nature of financial
reporting
Preparing statements takes judgement,
from choosing accounting policies to
making estimates. Provisions and fair
values often have no single right answer.
2 The nature of audit
procedures
The auditor relies heavily on information
from the entity, has no legal power to
search premises, can demand answers
only from the company's own officers, and
can be deceived by fraud hidden through
forgery or collusion.
3 Reasonable time and cost
Users need the audit finished while the
information is still useful, at a sensible
cost. That is never a reason to skip a
procedure the auditor needs.
Pressure to cut corners comes from three directions, and the auditor must resist all three
Clients who want to report by a deadline Clients reluctant to pay for extra work Budgets inside the audit firm
Limits are not excuses. Difficulty, time pressure and cost explain why assurance is reasonable rather than
absolute; they never justify leaving out a procedure the auditor needs.
Other historical financial information
Audits of specialised areas give reasonable assurance on historical financial information other than a full set of
general purpose statements: special purpose statements prepared for a particular user, such as a lender or
regulator; one statement, or one element, account or item within it, such as a schedule of royalties under a
licence; and summary statements derived from audited ones. Reviews give limited assurance. The best-known
is the auditor's review of a listed company's half-year report, but a practitioner who isn't the auditor can also
review, say, a smaller company's statements for a lender that wants comfort without a full audit.
Other assurance engagements
Internal audit sits inside the organisation, staffed by employees or outsourced, and answers to those charged
with governance. Engagements on controls often concern a service organisation, such as a payroll processor,
whose report its customers and their auditors can rely on.
Area What it covers Points to remember
Sustainability reports Sustainability information, including
greenhouse gas emissions
A dedicated standard: ISSA 5000
internationally, ASSA 5000 in Australia.
ISSA 5000 replaces ISAE 3410, the
greenhouse gas standard, for periods
beginning on or after 15 December 2026
Other non-financial
reports
Integrated reports, business performance
measures, water accounting reports
The umbrella standard (ISAE / ASAE 3000)
and its companions, such as ASAE 3610 /
AWAS 2 for water
ADVANCED AUDIT AND ASSURANCE | M1 | 1.3 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
Area What it covers Points to remember
Information about the
future
Forecasts and other prospective financial
information, e.g. in a fundraising document
Limited, negatively worded assurance on
the assumptions; an opinion on preparation
and presentation; a warning that results are
likely to differ
Systems and
processes
Internal audit; engagements on controls;
continuous auditing
Controls engagements cover design only, or
design plus operating effectiveness over a
period. Continuous auditing needs systems
the practitioner can trust
Aspects of behaviour Compliance with law, regulation, contract,
grant or licence; corporate governance
practices or statements
A compliance report names its criteria and
the period covered
Performance of an
activity
Economy, efficiency and effectiveness,
especially of public sector programs
Auditors-General report their performance
audits to Parliament
The three Es of a performance audit
E The question Imagined example: a council library service
Economy Were the right inputs acquired at the lowest
cost?
Did it pay a fair price for books and digital licences?
Efficiency Was the most output obtained from those
inputs?
Loans and program sessions per staff hour,
compared with similar councils
Effectiveness Did the activity achieve its objectives? Did its early literacy program lift reading levels in the
target suburbs?
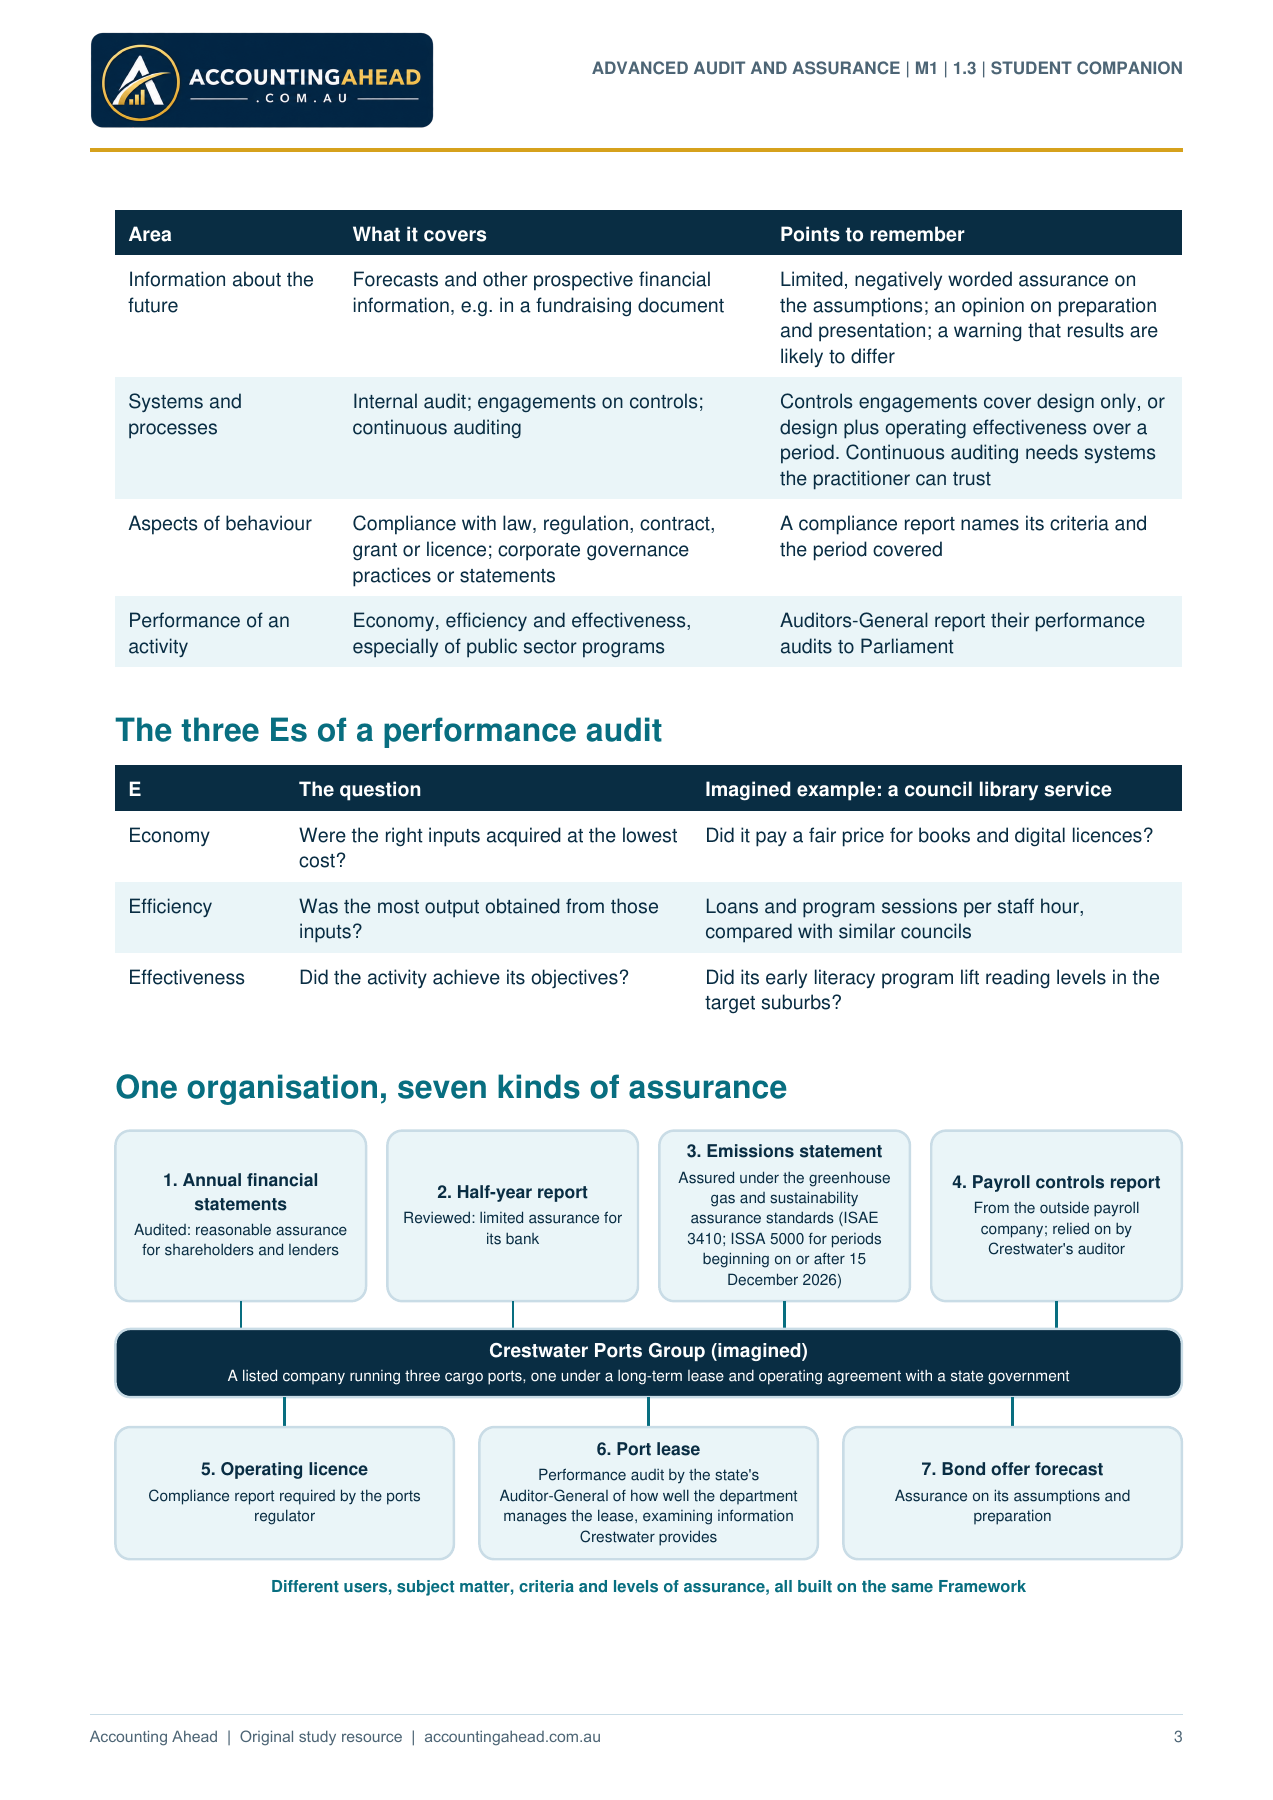
One organisation, seven kinds of assurance
1. Annual financial
statements
Audited: reasonable assurance
for shareholders and lenders
2. Half-year report
Reviewed: limited assurance for
its bank
3. Emissions statement
Assured under the greenhouse
gas and sustainability
assurance standards (ISAE
3410; ISSA 5000 for periods
beginning on or after 15
December 2026)
4. Payroll controls report
From the outside payroll
company; relied on by
Crestwater's auditor
Crestwater Ports Group (imagined)
A listed company running three cargo ports, one under a long-term lease and operating agreement with a state government
5. Operating licence
Compliance report required by the ports
regulator
6. Port lease
Performance audit by the state's
Auditor-General of how well the department
manages the lease, examining information
Crestwater provides
7. Bond offer forecast
Assurance on its assumptions and
preparation
Different users, subject matter, criteria and levels of assurance, all built on the same Framework
ADVANCED AUDIT AND ASSURANCE | M1 | 1.3 | STUDENT COMPANION
3
Accounting Ahead | Original study resource | accountingahead.com.au
Back to the opening question. Crestwater needs several kinds of assurance because different users rely on
different information: shareholders and lenders on the financial statements, its bank on the half-year report, the
regulator on licence compliance, investors in its bonds on the forecast, and Parliament on how the state
manages the port lease. Each engagement has its own subject matter, criteria and level of assurance.
Practice questions
MODULE 1 | 1.3 | TRY THESE BEFORE THE WORKED ANSWERS
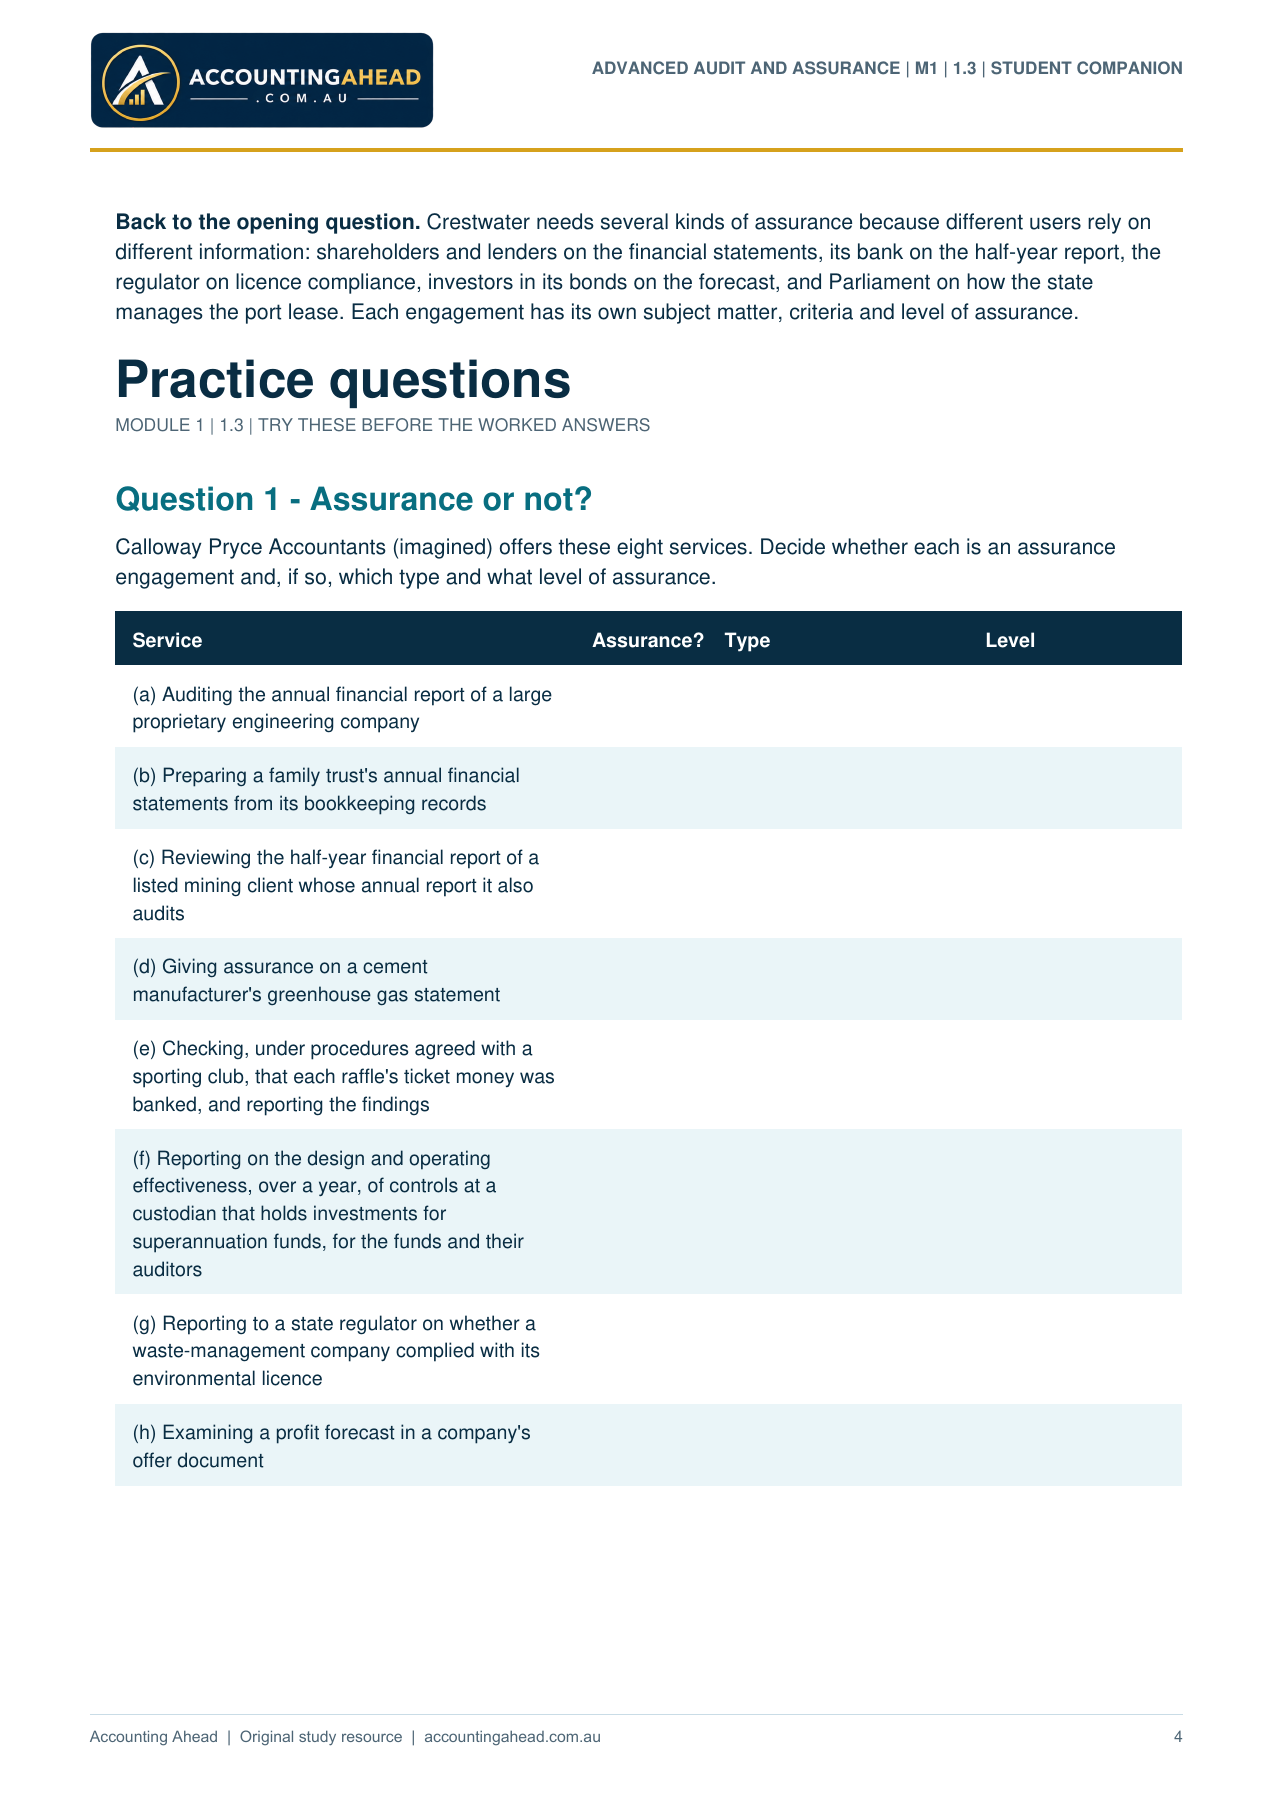
Question 1 - Assurance or not?
Calloway Pryce Accountants (imagined) offers these eight services. Decide whether each is an assurance
engagement and, if so, which type and what level of assurance.
Service Assurance? Type Level
(a) Auditing the annual financial report of a large
proprietary engineering company
(b) Preparing a family trust's annual financial
statements from its bookkeeping records
(c) Reviewing the half-year financial report of a
listed mining client whose annual report it also
audits
(d) Giving assurance on a cement
manufacturer's greenhouse gas statement
(e) Checking, under procedures agreed with a
sporting club, that each raffle's ticket money was
banked, and reporting the findings
(f) Reporting on the design and operating
effectiveness, over a year, of controls at a
custodian that holds investments for
superannuation funds, for the funds and their
auditors
(g) Reporting to a state regulator on whether a
waste-management company complied with its
environmental licence
(h) Examining a profit forecast in a company's
offer document
ADVANCED AUDIT AND ASSURANCE | M1 | 1.3 | STUDENT COMPANION
4
Accounting Ahead | Original study resource | accountingahead.com.au
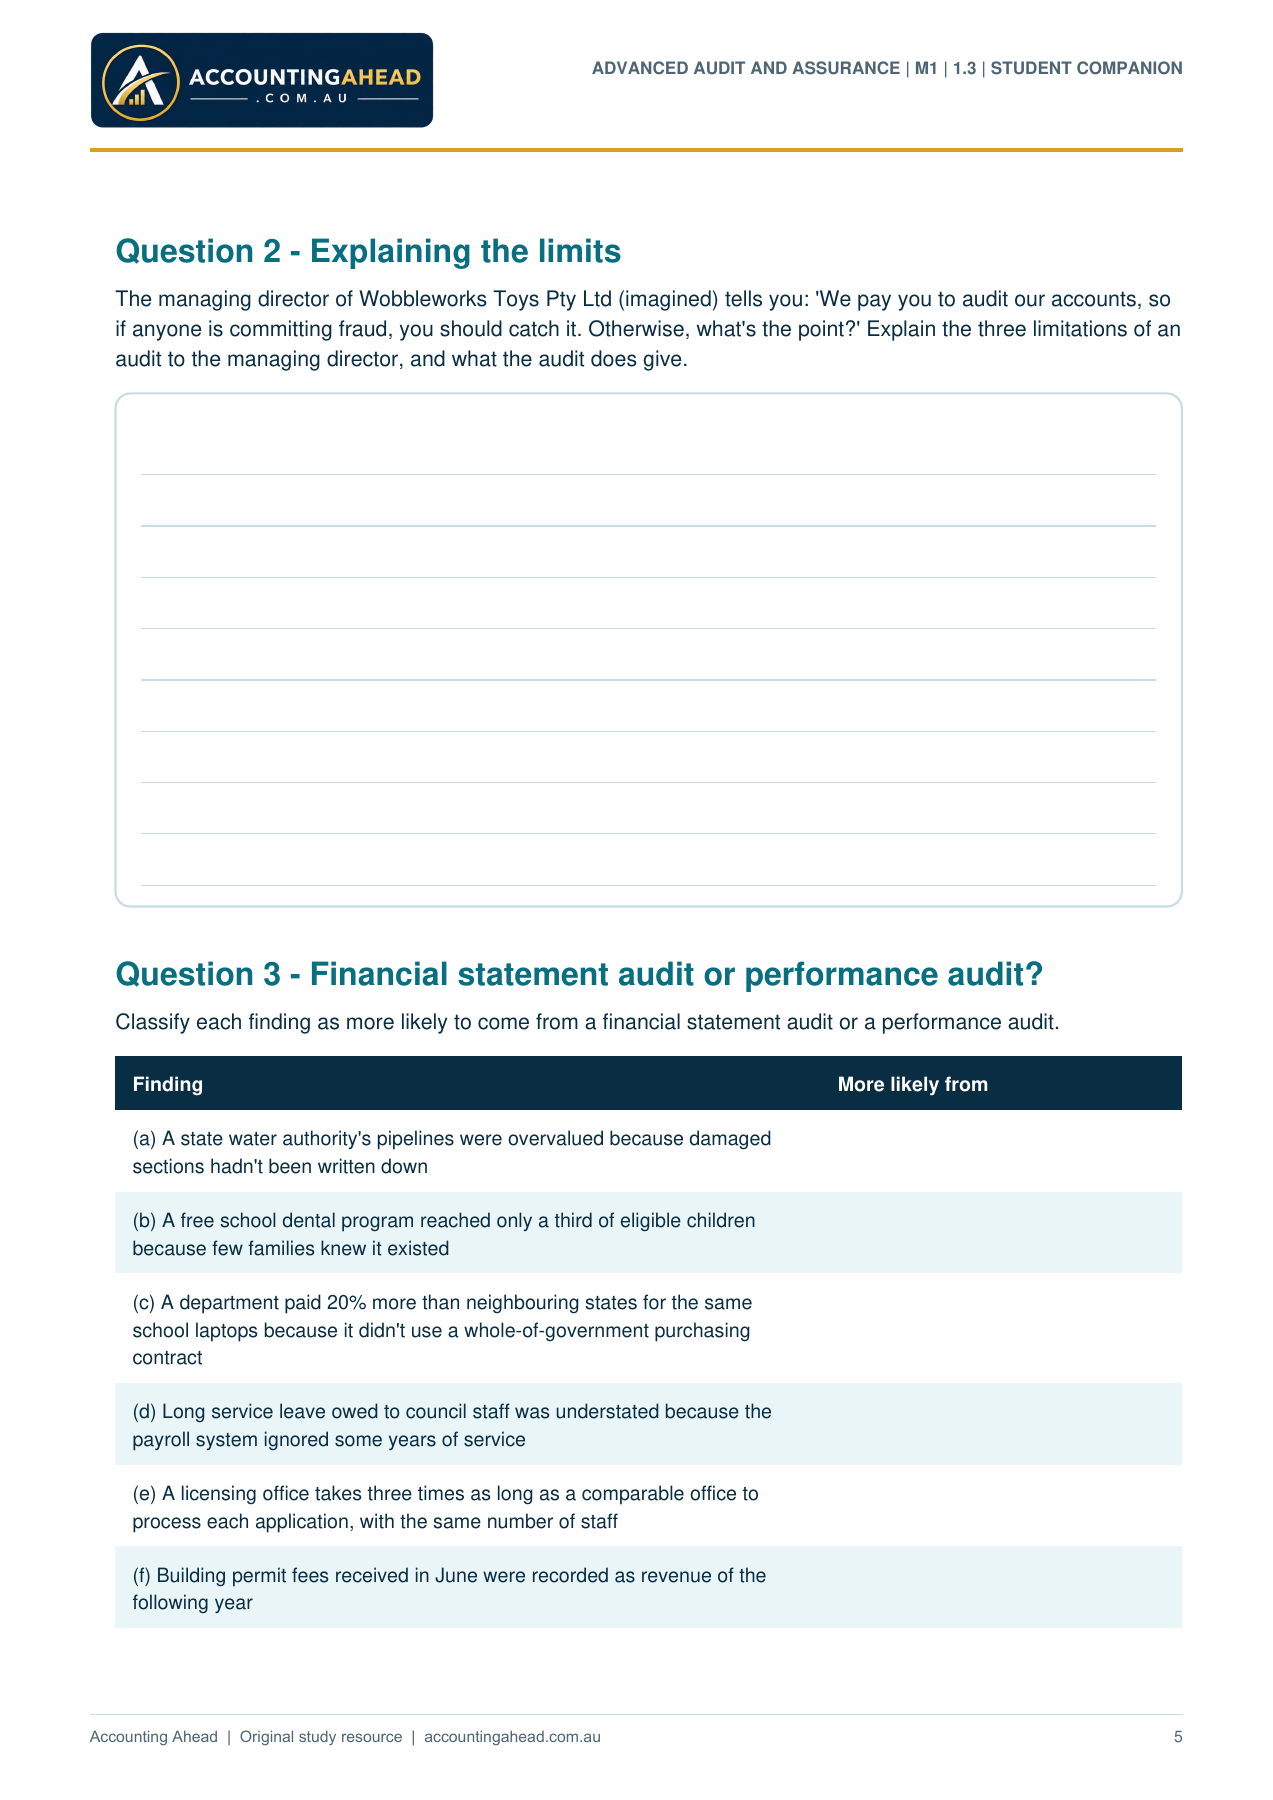
Question 2 - Explaining the limits
The managing director of Wobbleworks Toys Pty Ltd (imagined) tells you: 'We pay you to audit our accounts, so
if anyone is committing fraud, you should catch it. Otherwise, what's the point?' Explain the three limitations of an
audit to the managing director, and what the audit does give.
Question 3 - Financial statement audit or performance audit?
Classify each finding as more likely to come from a financial statement audit or a performance audit.
Finding More likely from
(a) A state water authority's pipelines were overvalued because damaged
sections hadn't been written down
(b) A free school dental program reached only a third of eligible children
because few families knew it existed
(c) A department paid 20% more than neighbouring states for the same
school laptops because it didn't use a whole-of-government purchasing
contract
(d) Long service leave owed to council staff was understated because the
payroll system ignored some years of service
(e) A licensing office takes three times as long as a comparable office to
process each application, with the same number of staff
(f) Building permit fees received in June were recorded as revenue of the
following year
ADVANCED AUDIT AND ASSURANCE | M1 | 1.3 | STUDENT COMPANION
5
Accounting Ahead | Original study resource | accountingahead.com.au
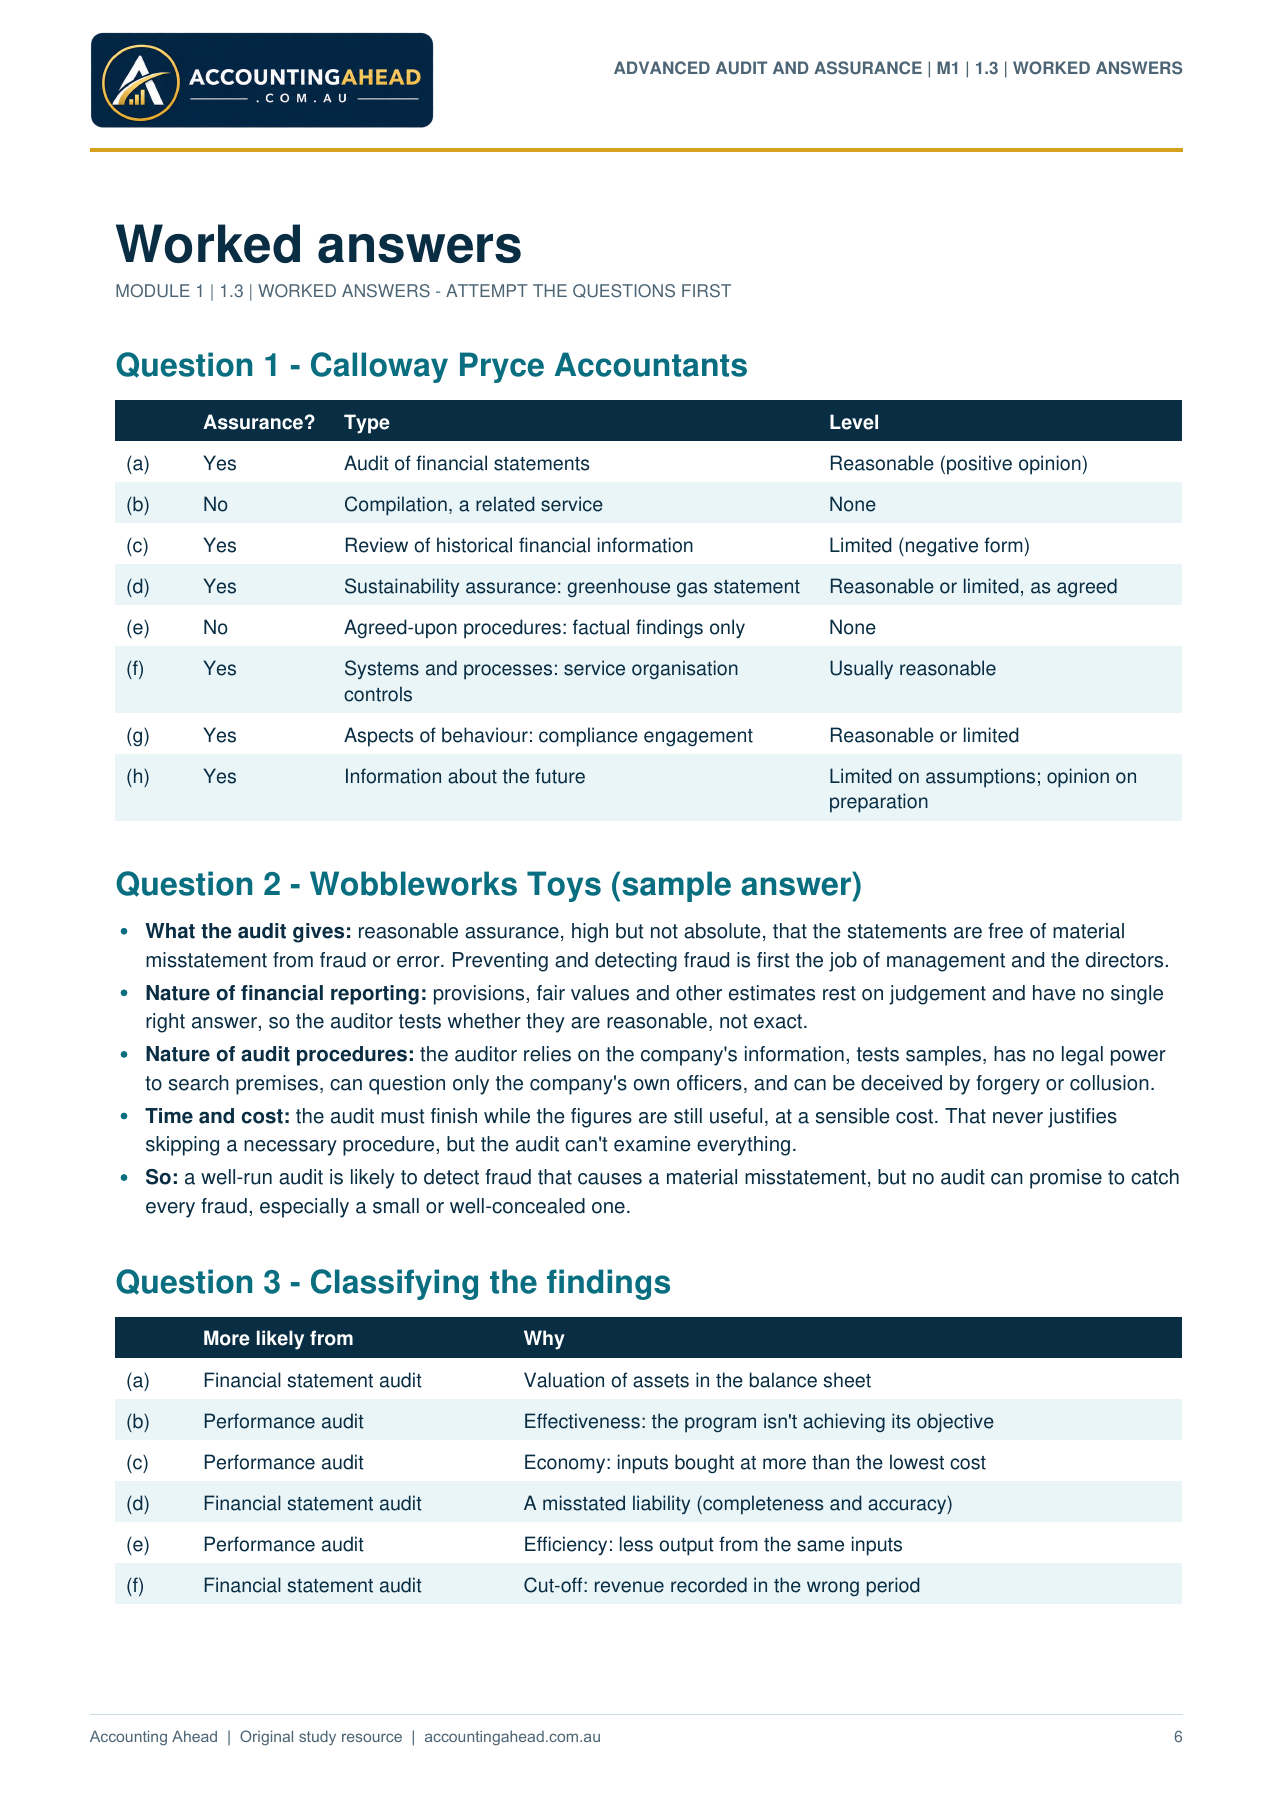
Worked answers
MODULE 1 | 1.3 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
Question 1 - Calloway Pryce Accountants
Assurance? Type Level
(a) Yes Audit of financial statements Reasonable (positive opinion)
(b) No Compilation, a related service None
(c) Yes Review of historical financial information Limited (negative form)
(d) Yes Sustainability assurance: greenhouse gas statement Reasonable or limited, as agreed
(e) No Agreed-upon procedures: factual findings only None
(f) Yes Systems and processes: service organisation
controls
Usually reasonable
(g) Yes Aspects of behaviour: compliance engagement Reasonable or limited
(h) Yes Information about the future Limited on assumptions; opinion on
preparation
Question 2 - Wobbleworks Toys (sample answer)
What the audit gives: reasonable assurance, high but not absolute, that the statements are free of material
misstatement from fraud or error. Preventing and detecting fraud is first the job of management and the directors.
Nature of financial reporting: provisions, fair values and other estimates rest on judgement and have no single
right answer, so the auditor tests whether they are reasonable, not exact.
Nature of audit procedures: the auditor relies on the company's information, tests samples, has no legal power
to search premises, can question only the company's own officers, and can be deceived by forgery or collusion.
Time and cost: the audit must finish while the figures are still useful, at a sensible cost. That never justifies
skipping a necessary procedure, but the audit can't examine everything.
So: a well-run audit is likely to detect fraud that causes a material misstatement, but no audit can promise to catch
every fraud, especially a small or well-concealed one.
Question 3 - Classifying the findings
More likely from Why
(a) Financial statement audit Valuation of assets in the balance sheet
(b) Performance audit Effectiveness: the program isn't achieving its objective
(c) Performance audit Economy: inputs bought at more than the lowest cost
(d) Financial statement audit A misstated liability (completeness and accuracy)
(e) Performance audit Efficiency: less output from the same inputs
(f) Financial statement audit Cut-off: revenue recorded in the wrong period
ADVANCED AUDIT AND ASSURANCE | M1 | 1.3 | WORKED ANSWERS
6