Advanced Audit and Assurance file vault
Find your printable handouts and flowcharts by module and lecture. Open each resource page to preview and download its PDF or full-size image.
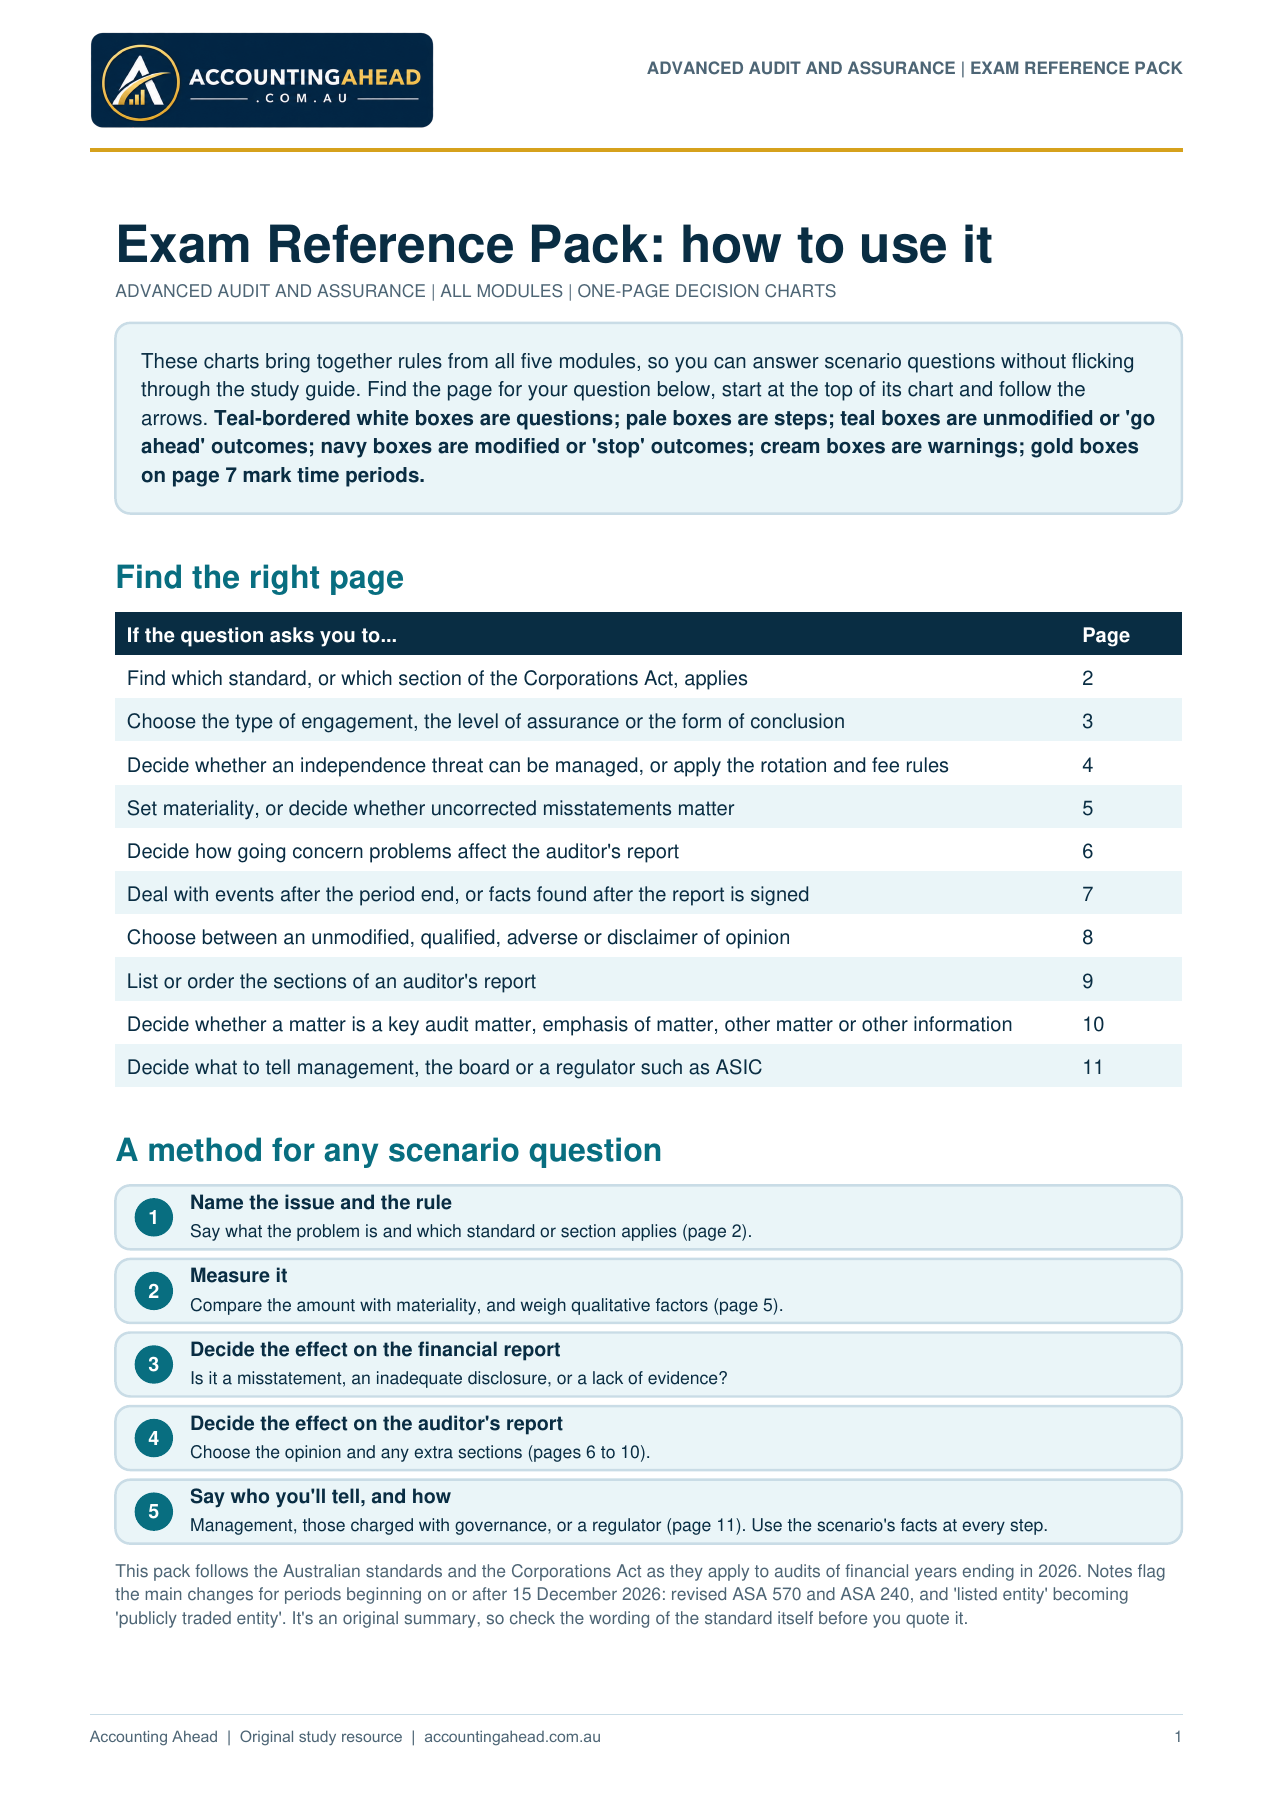
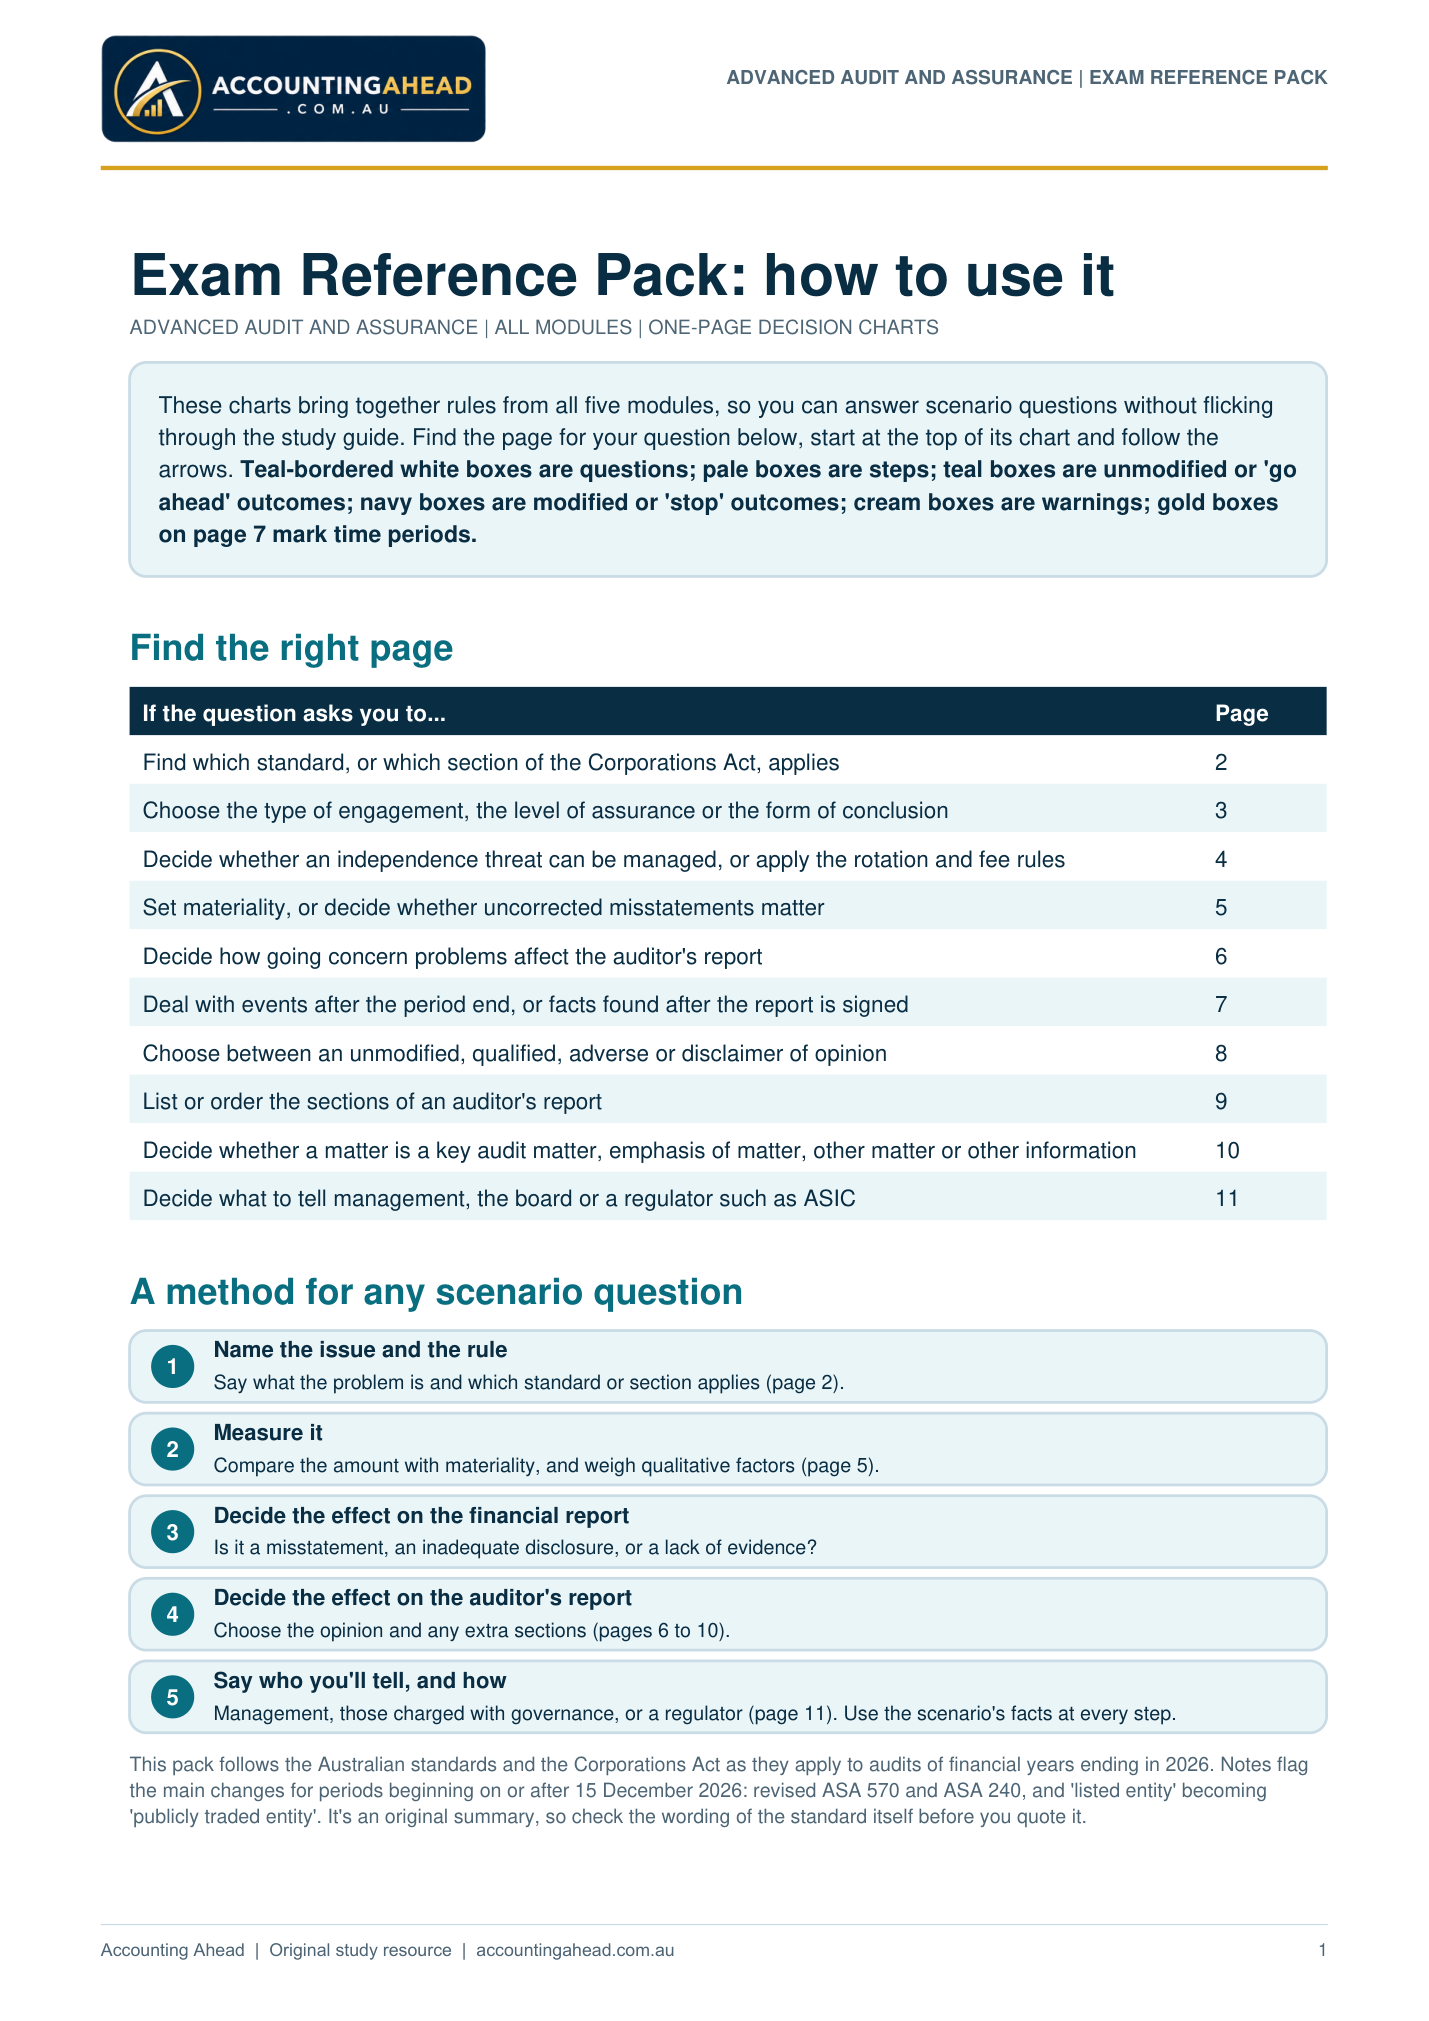
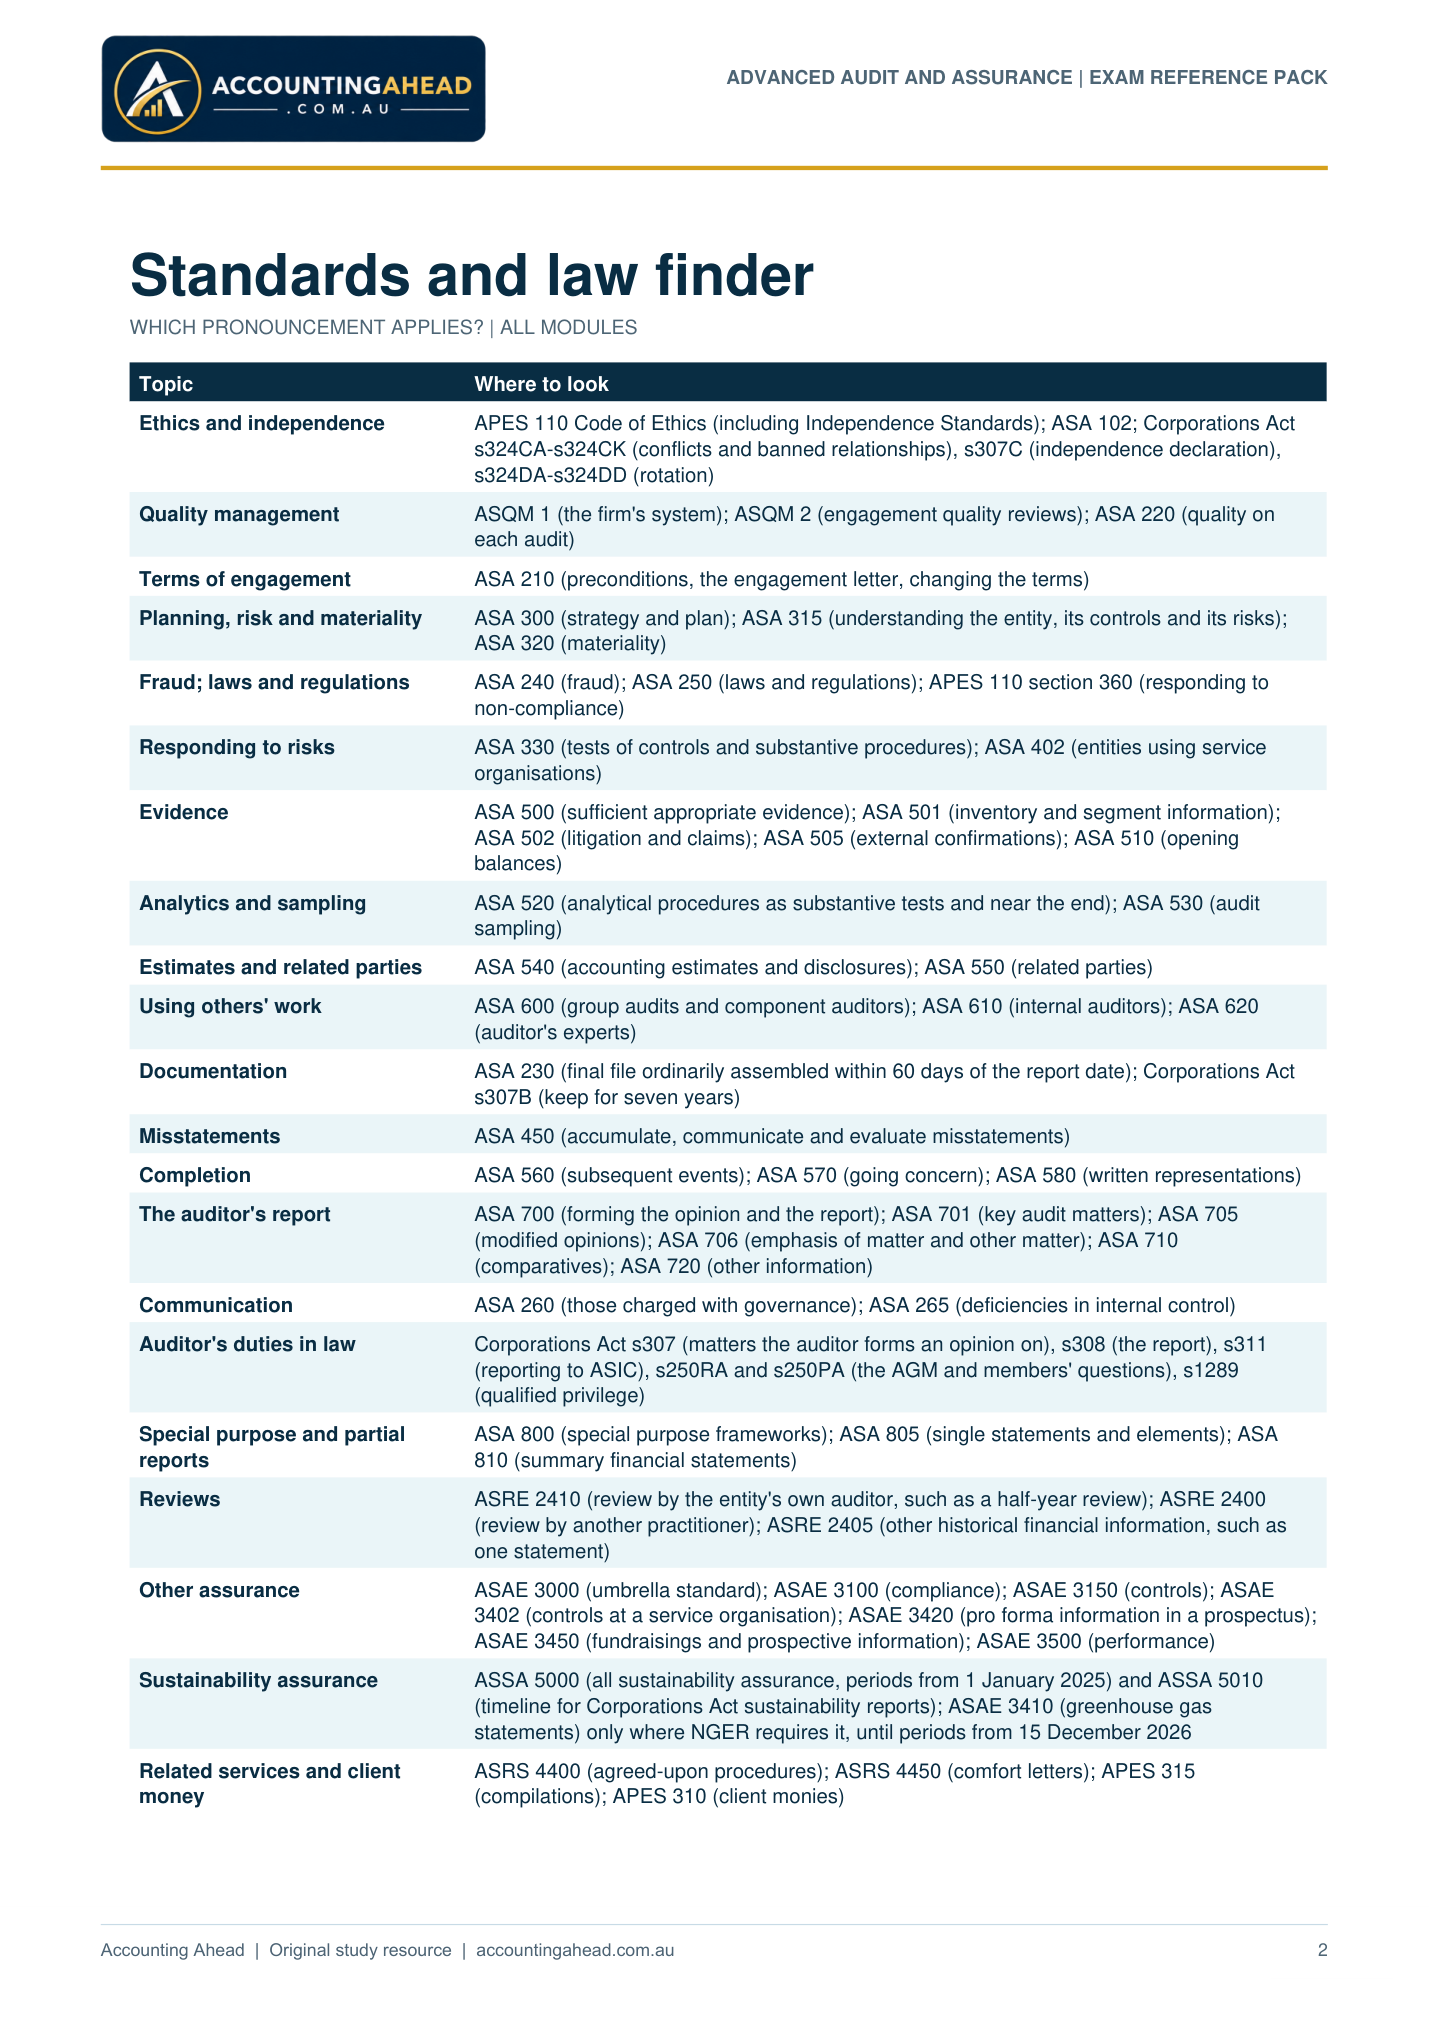
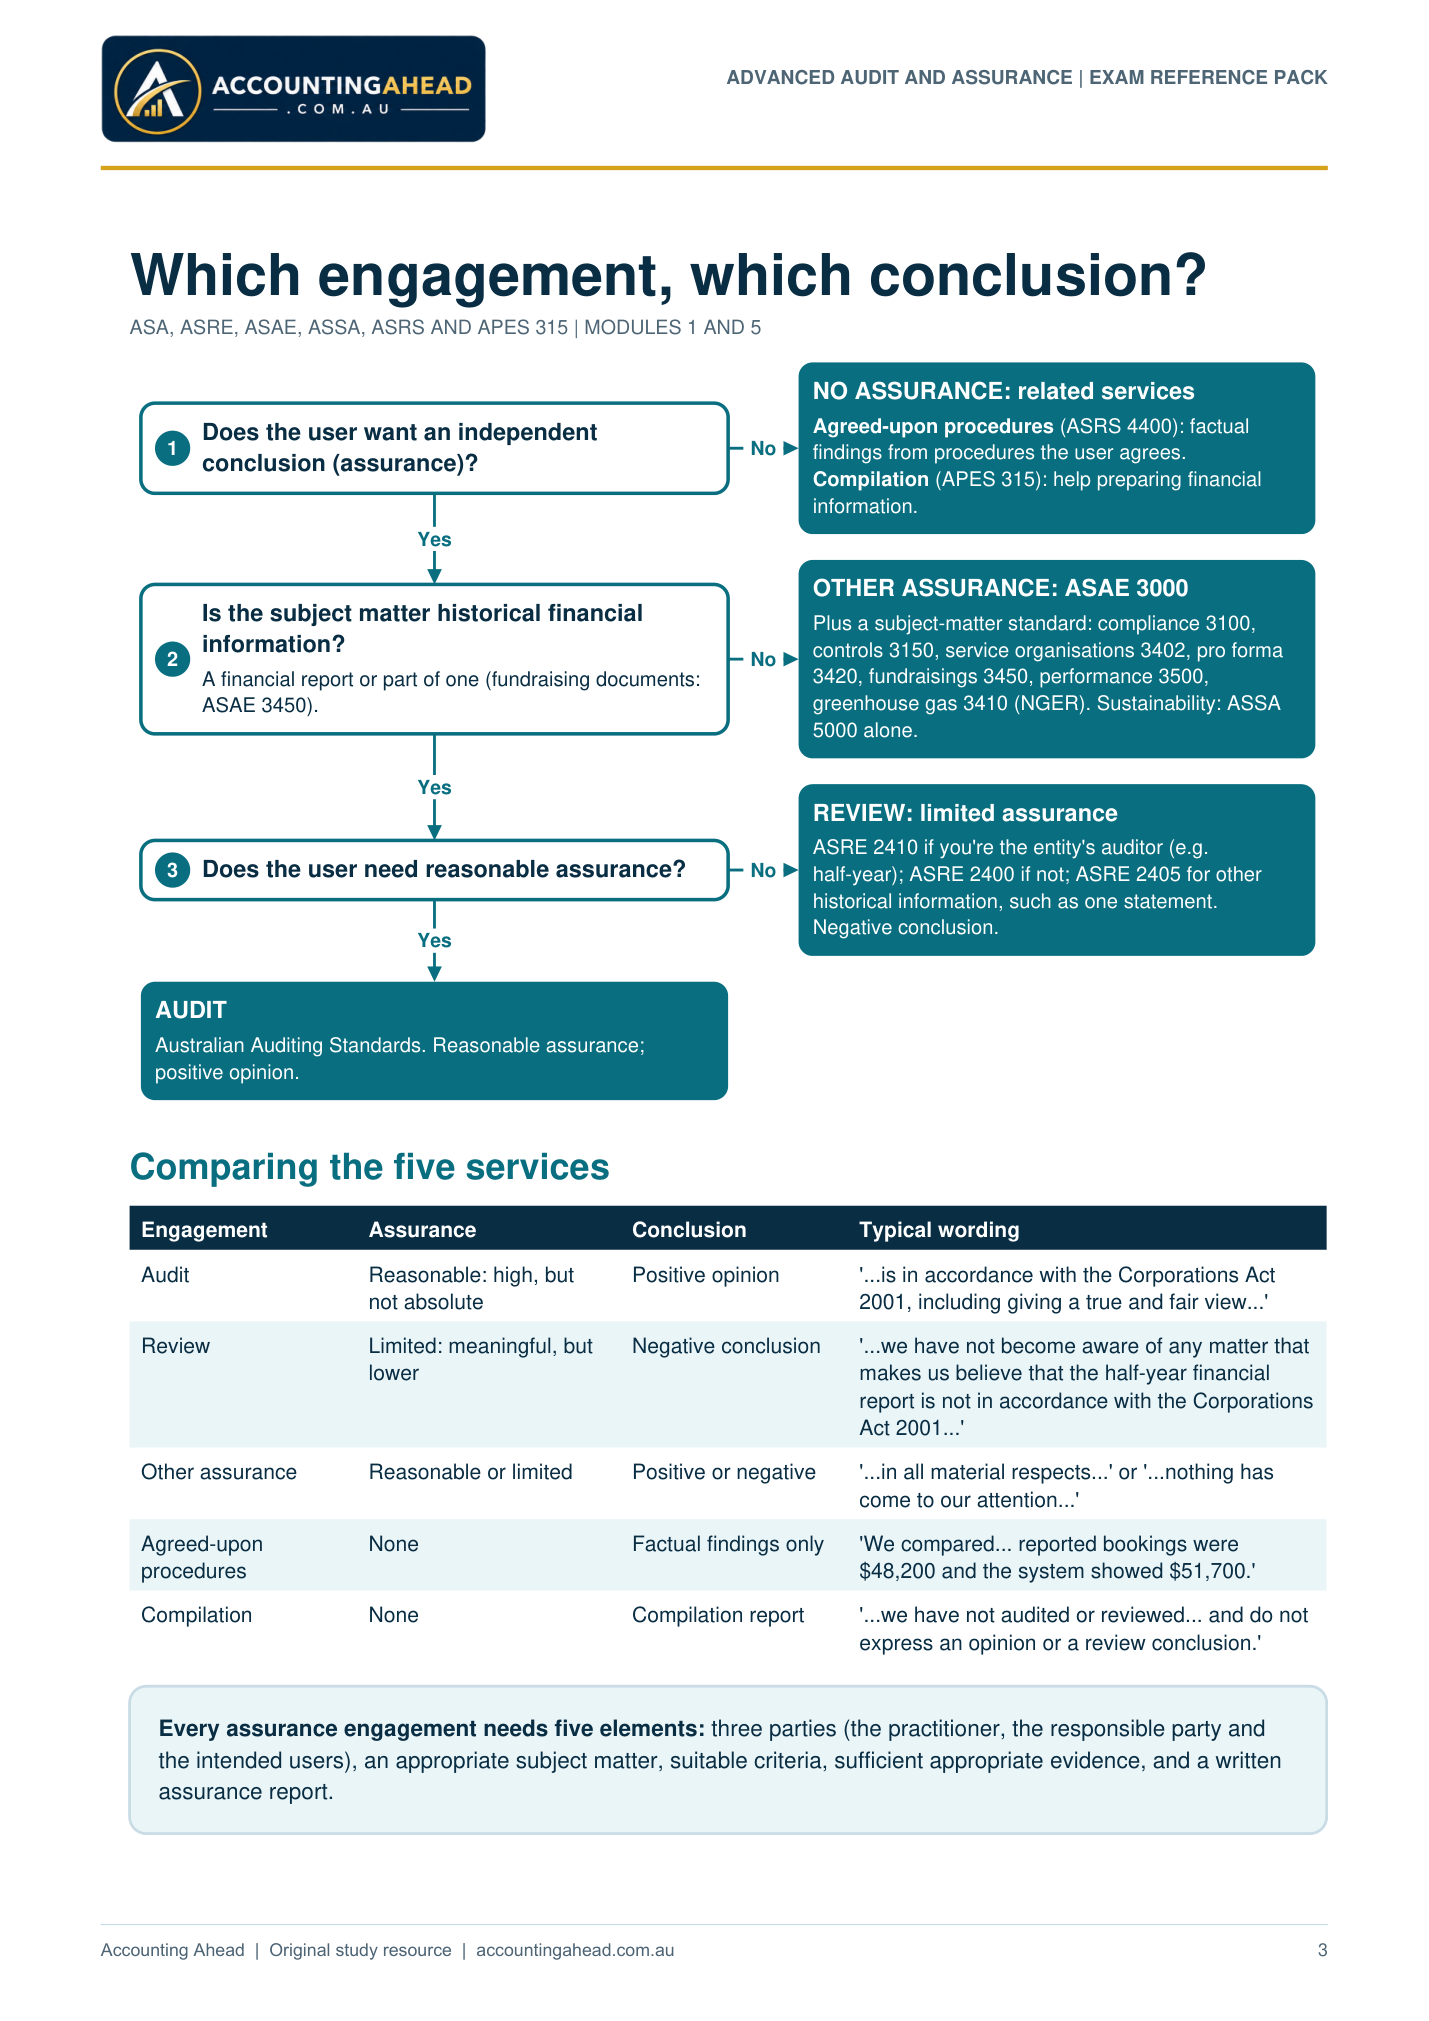
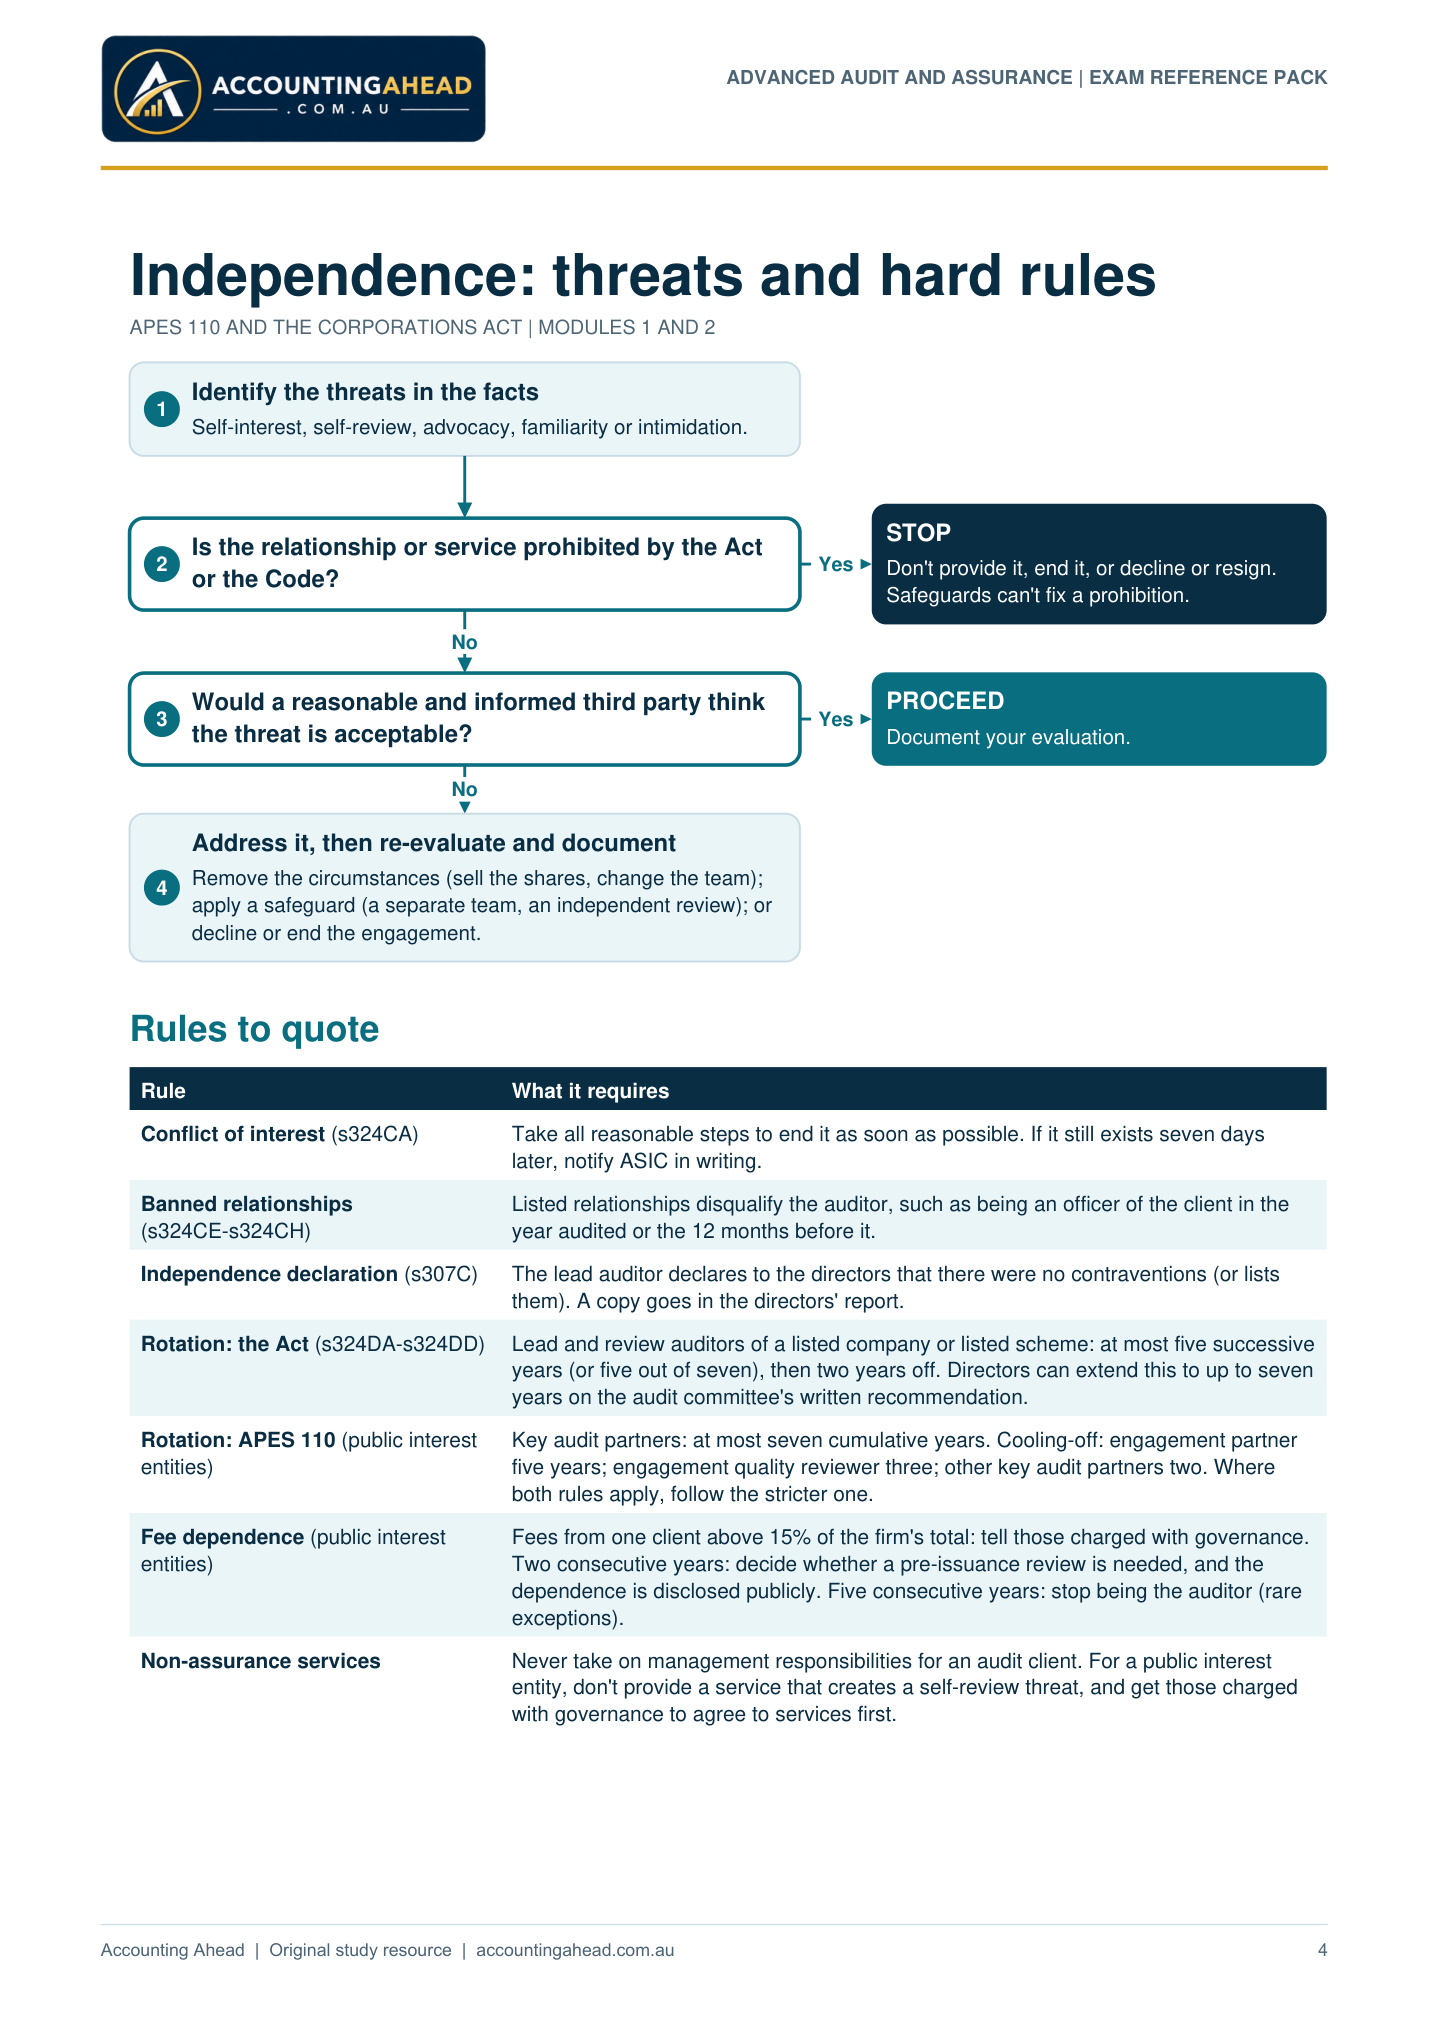
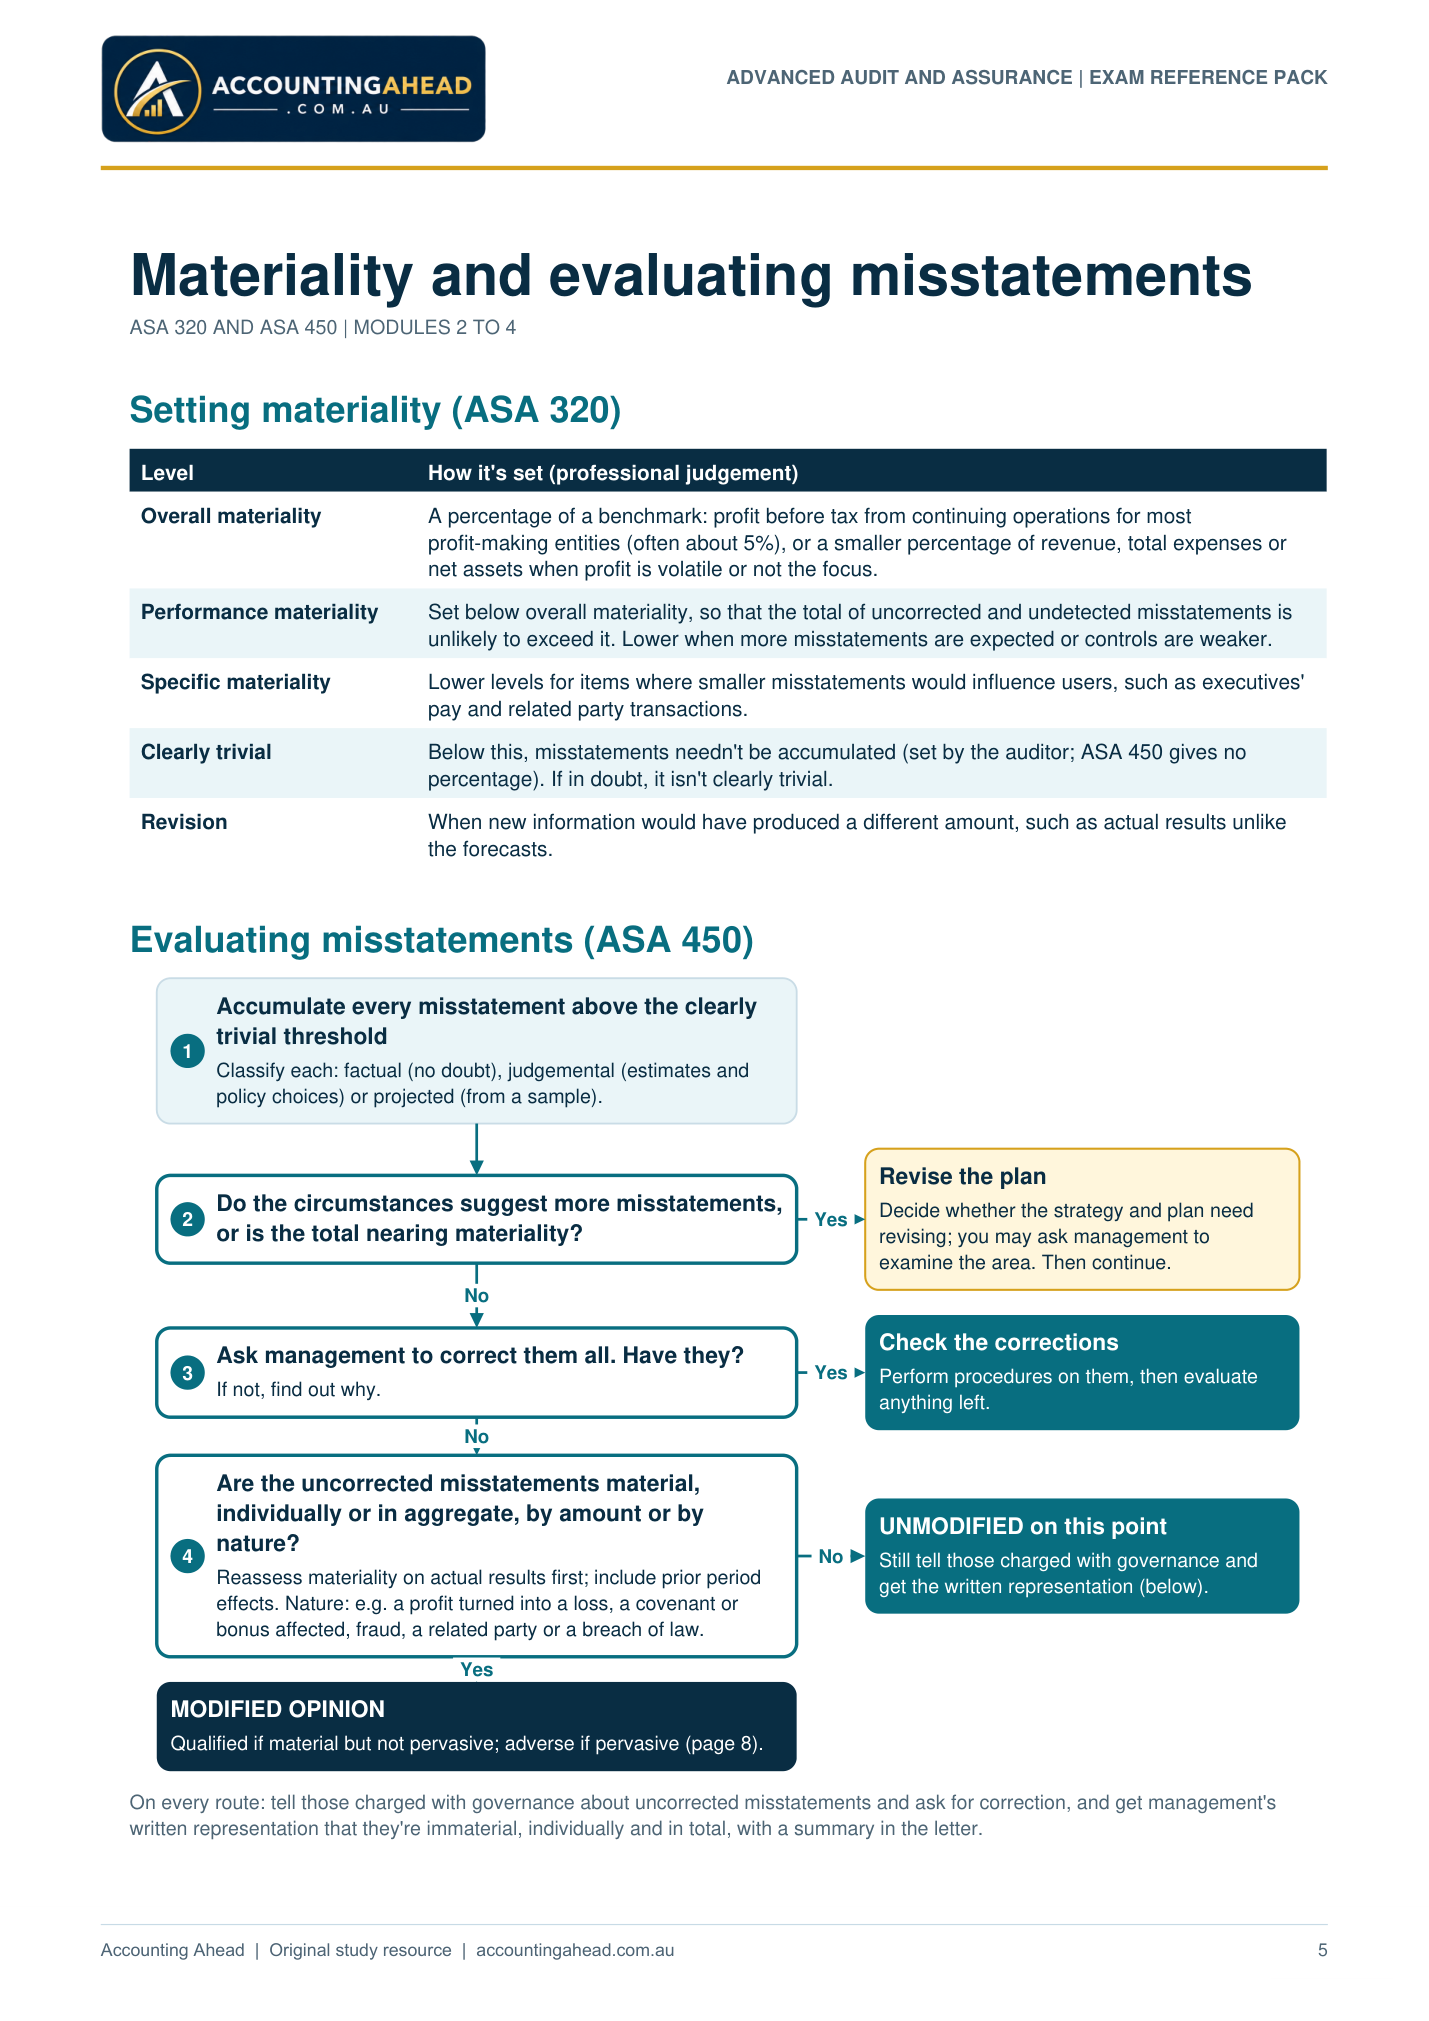
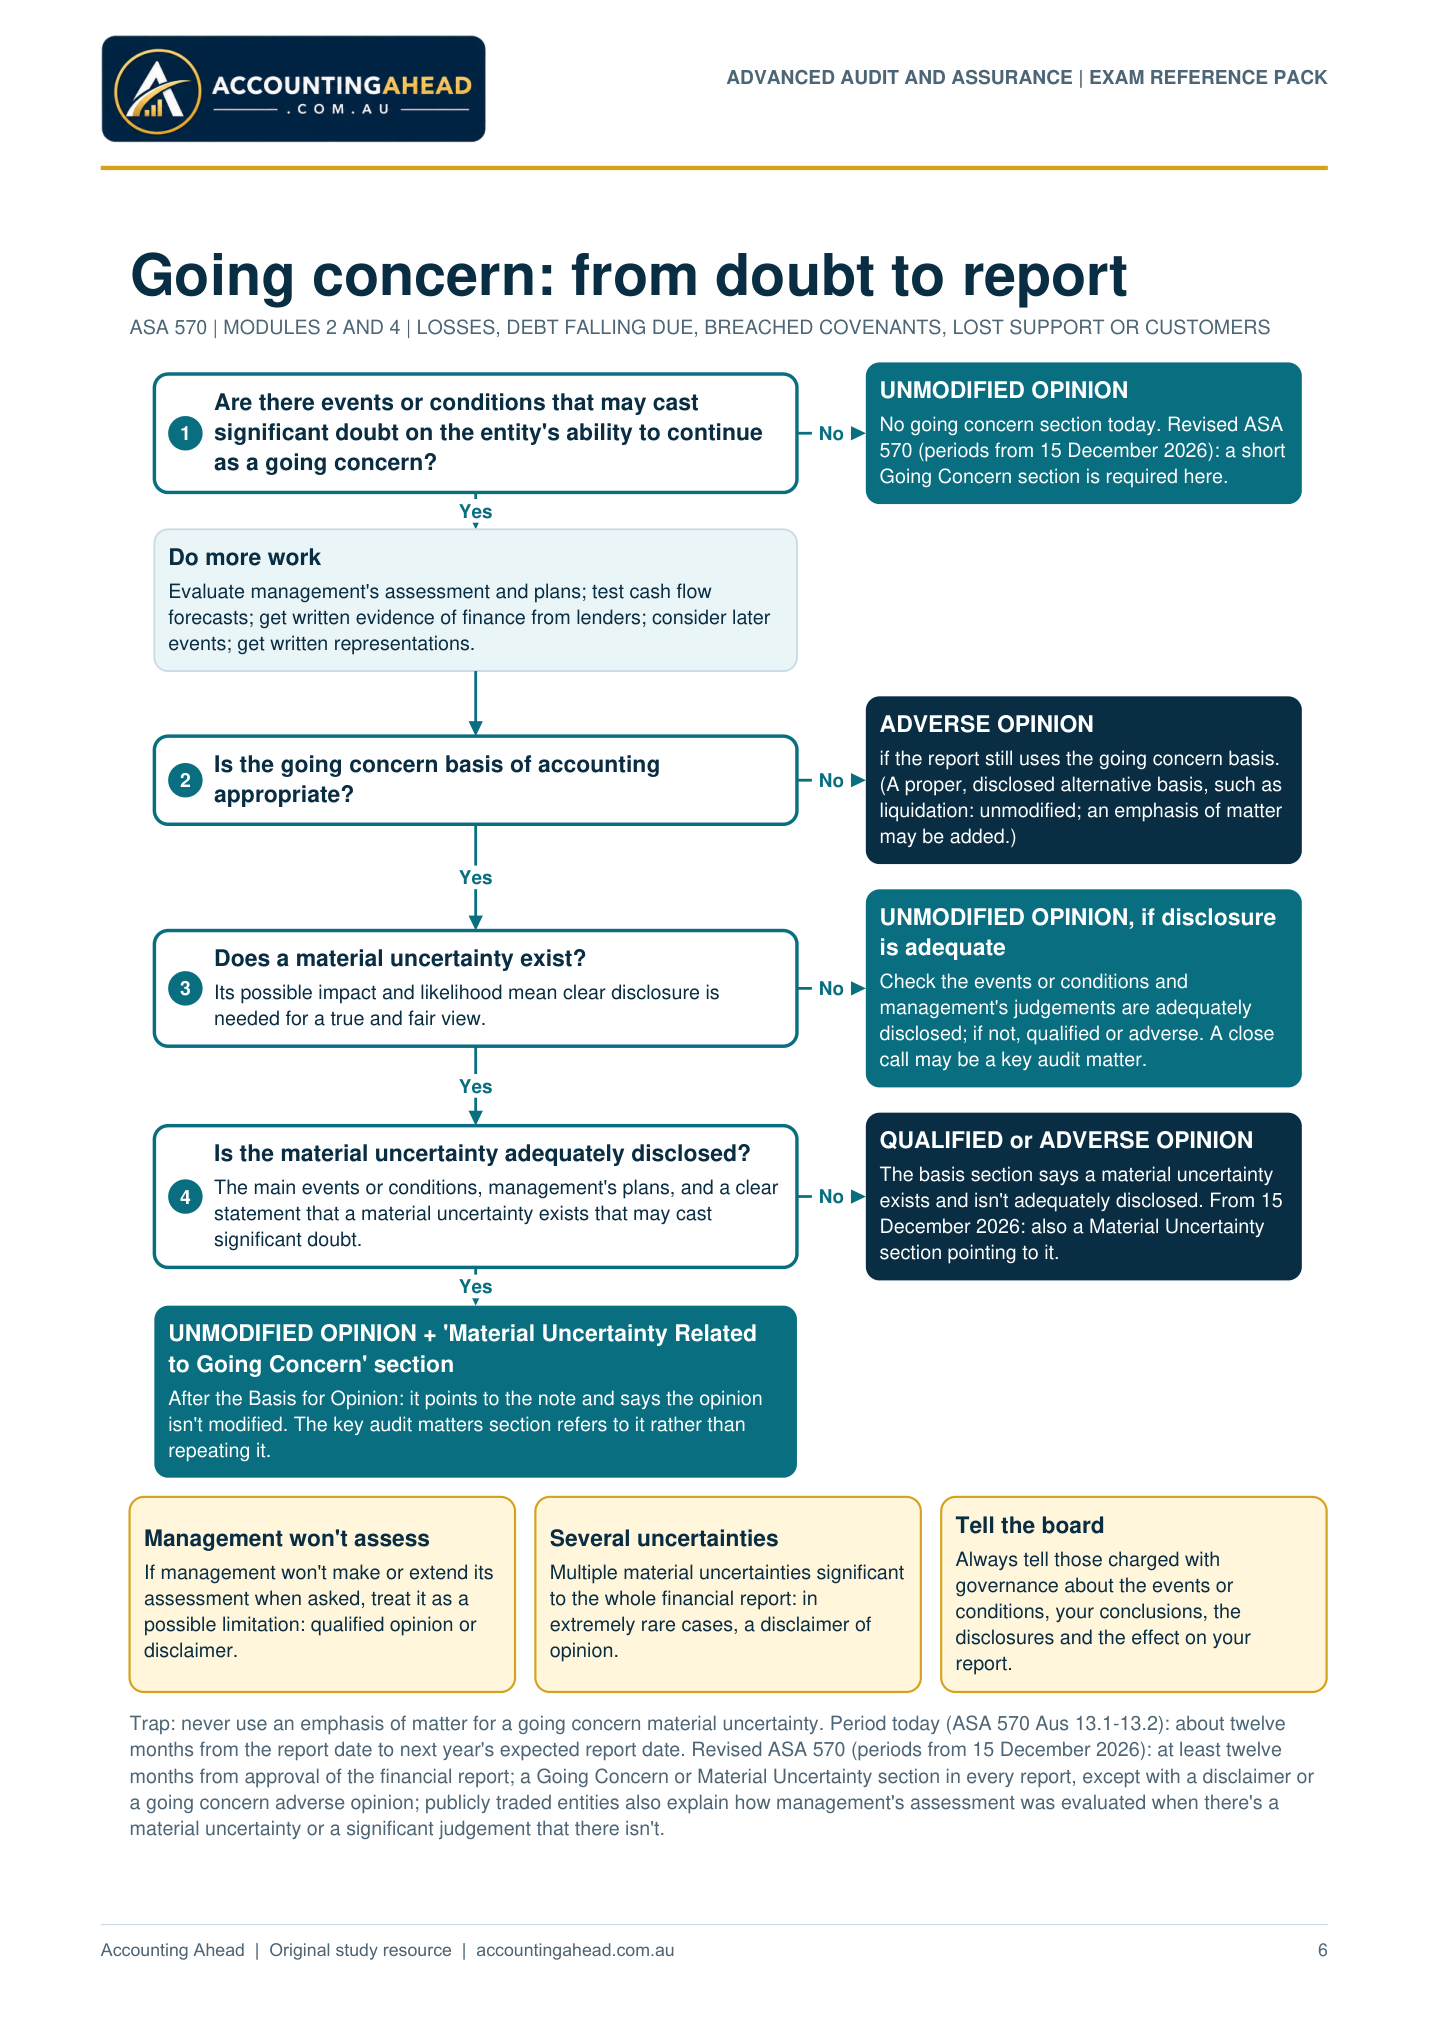
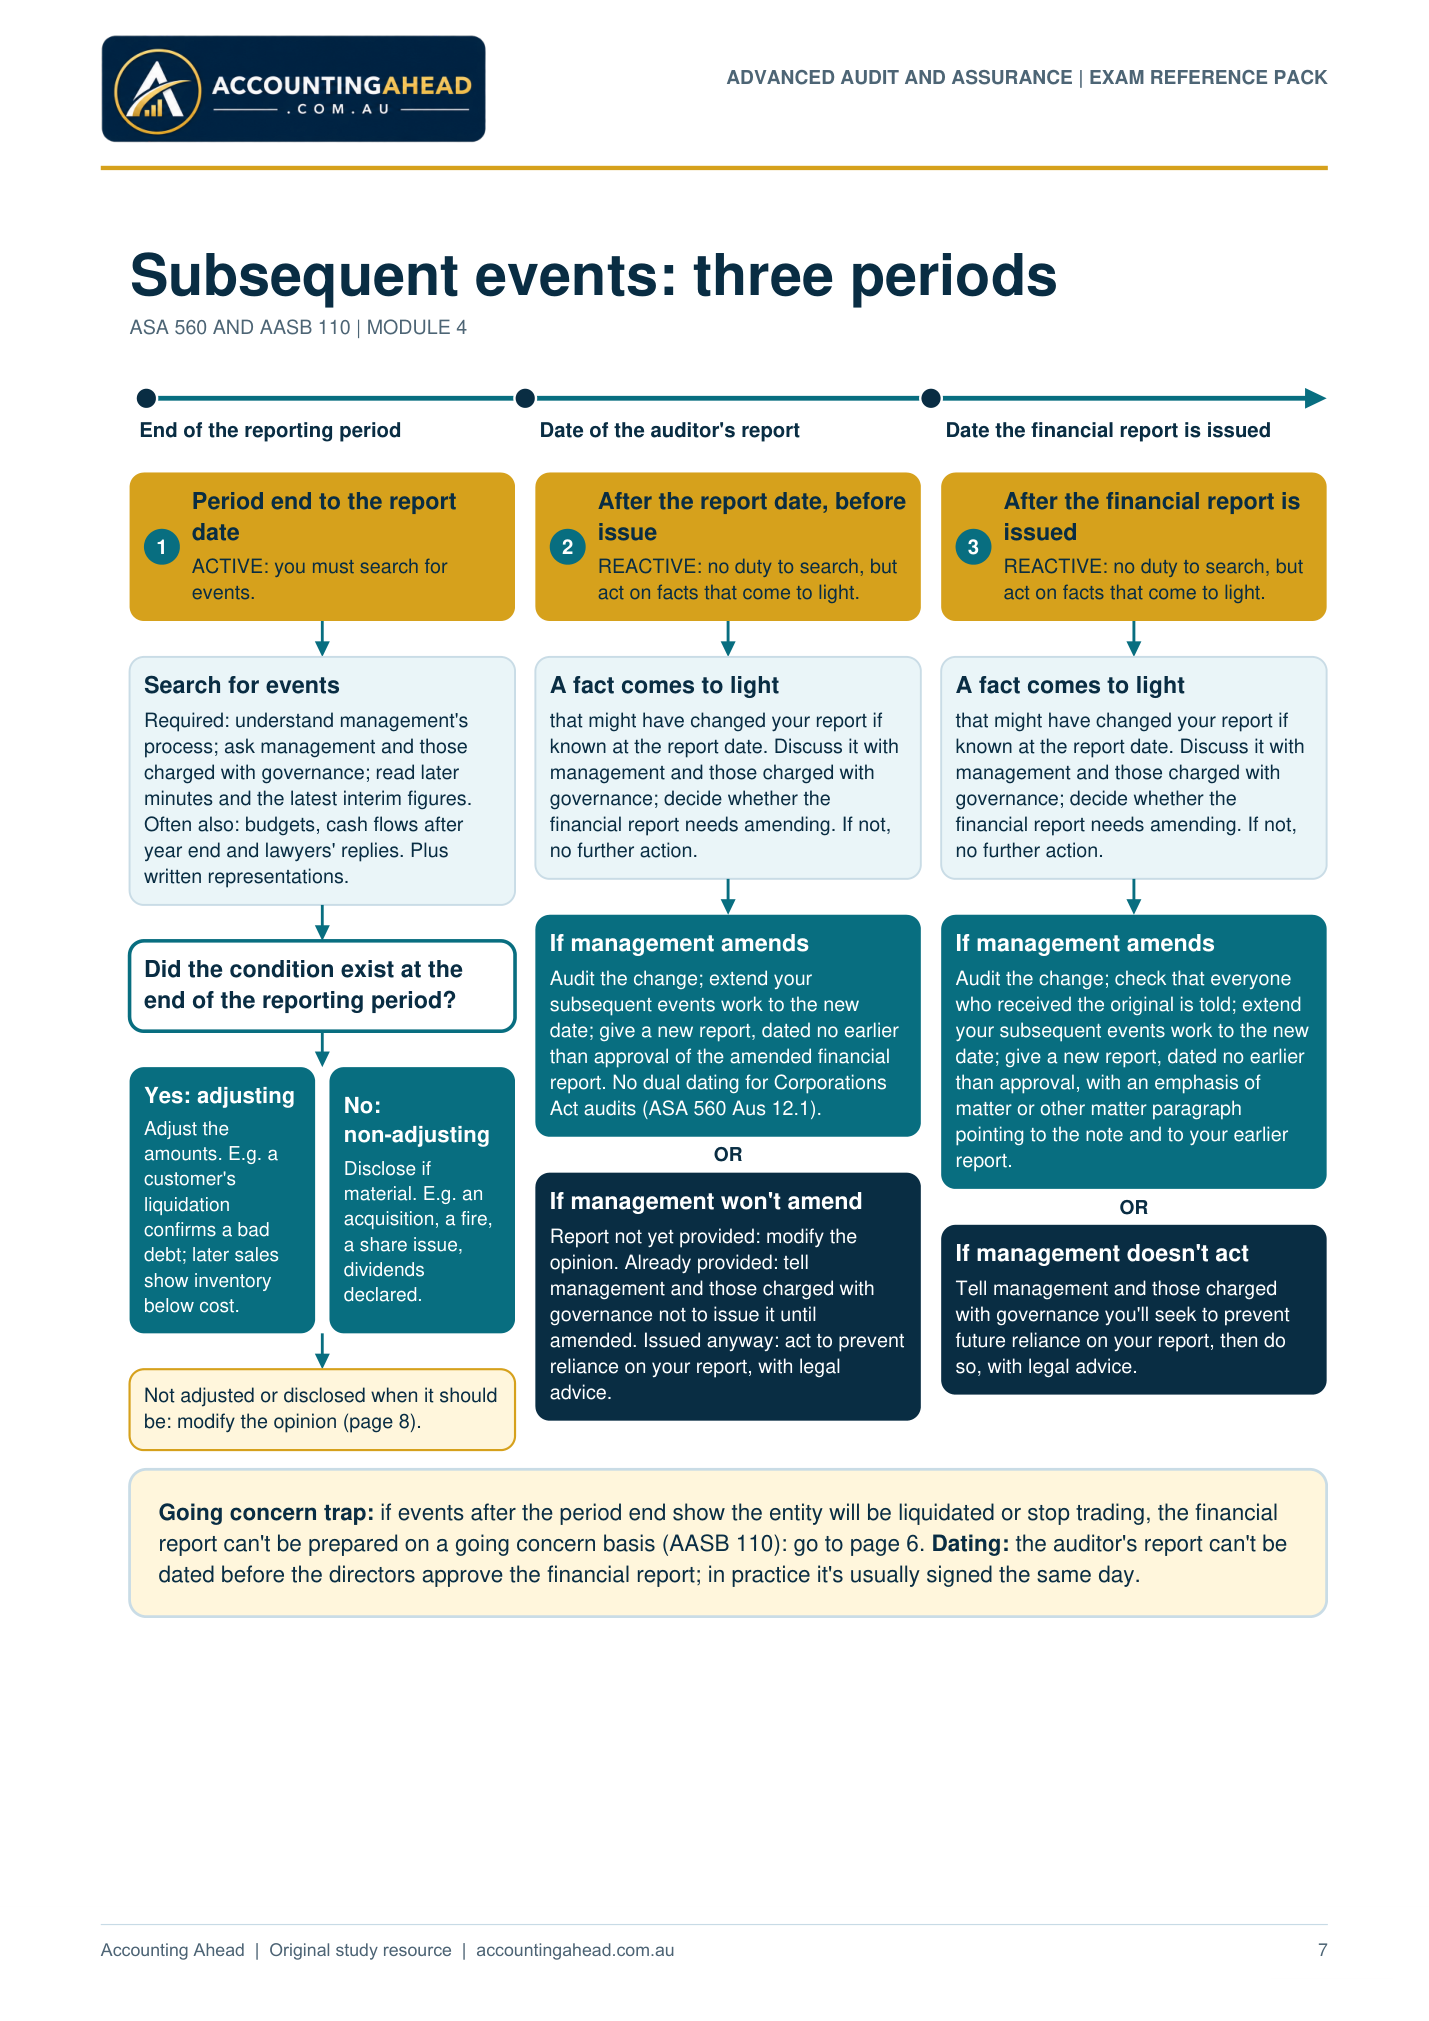
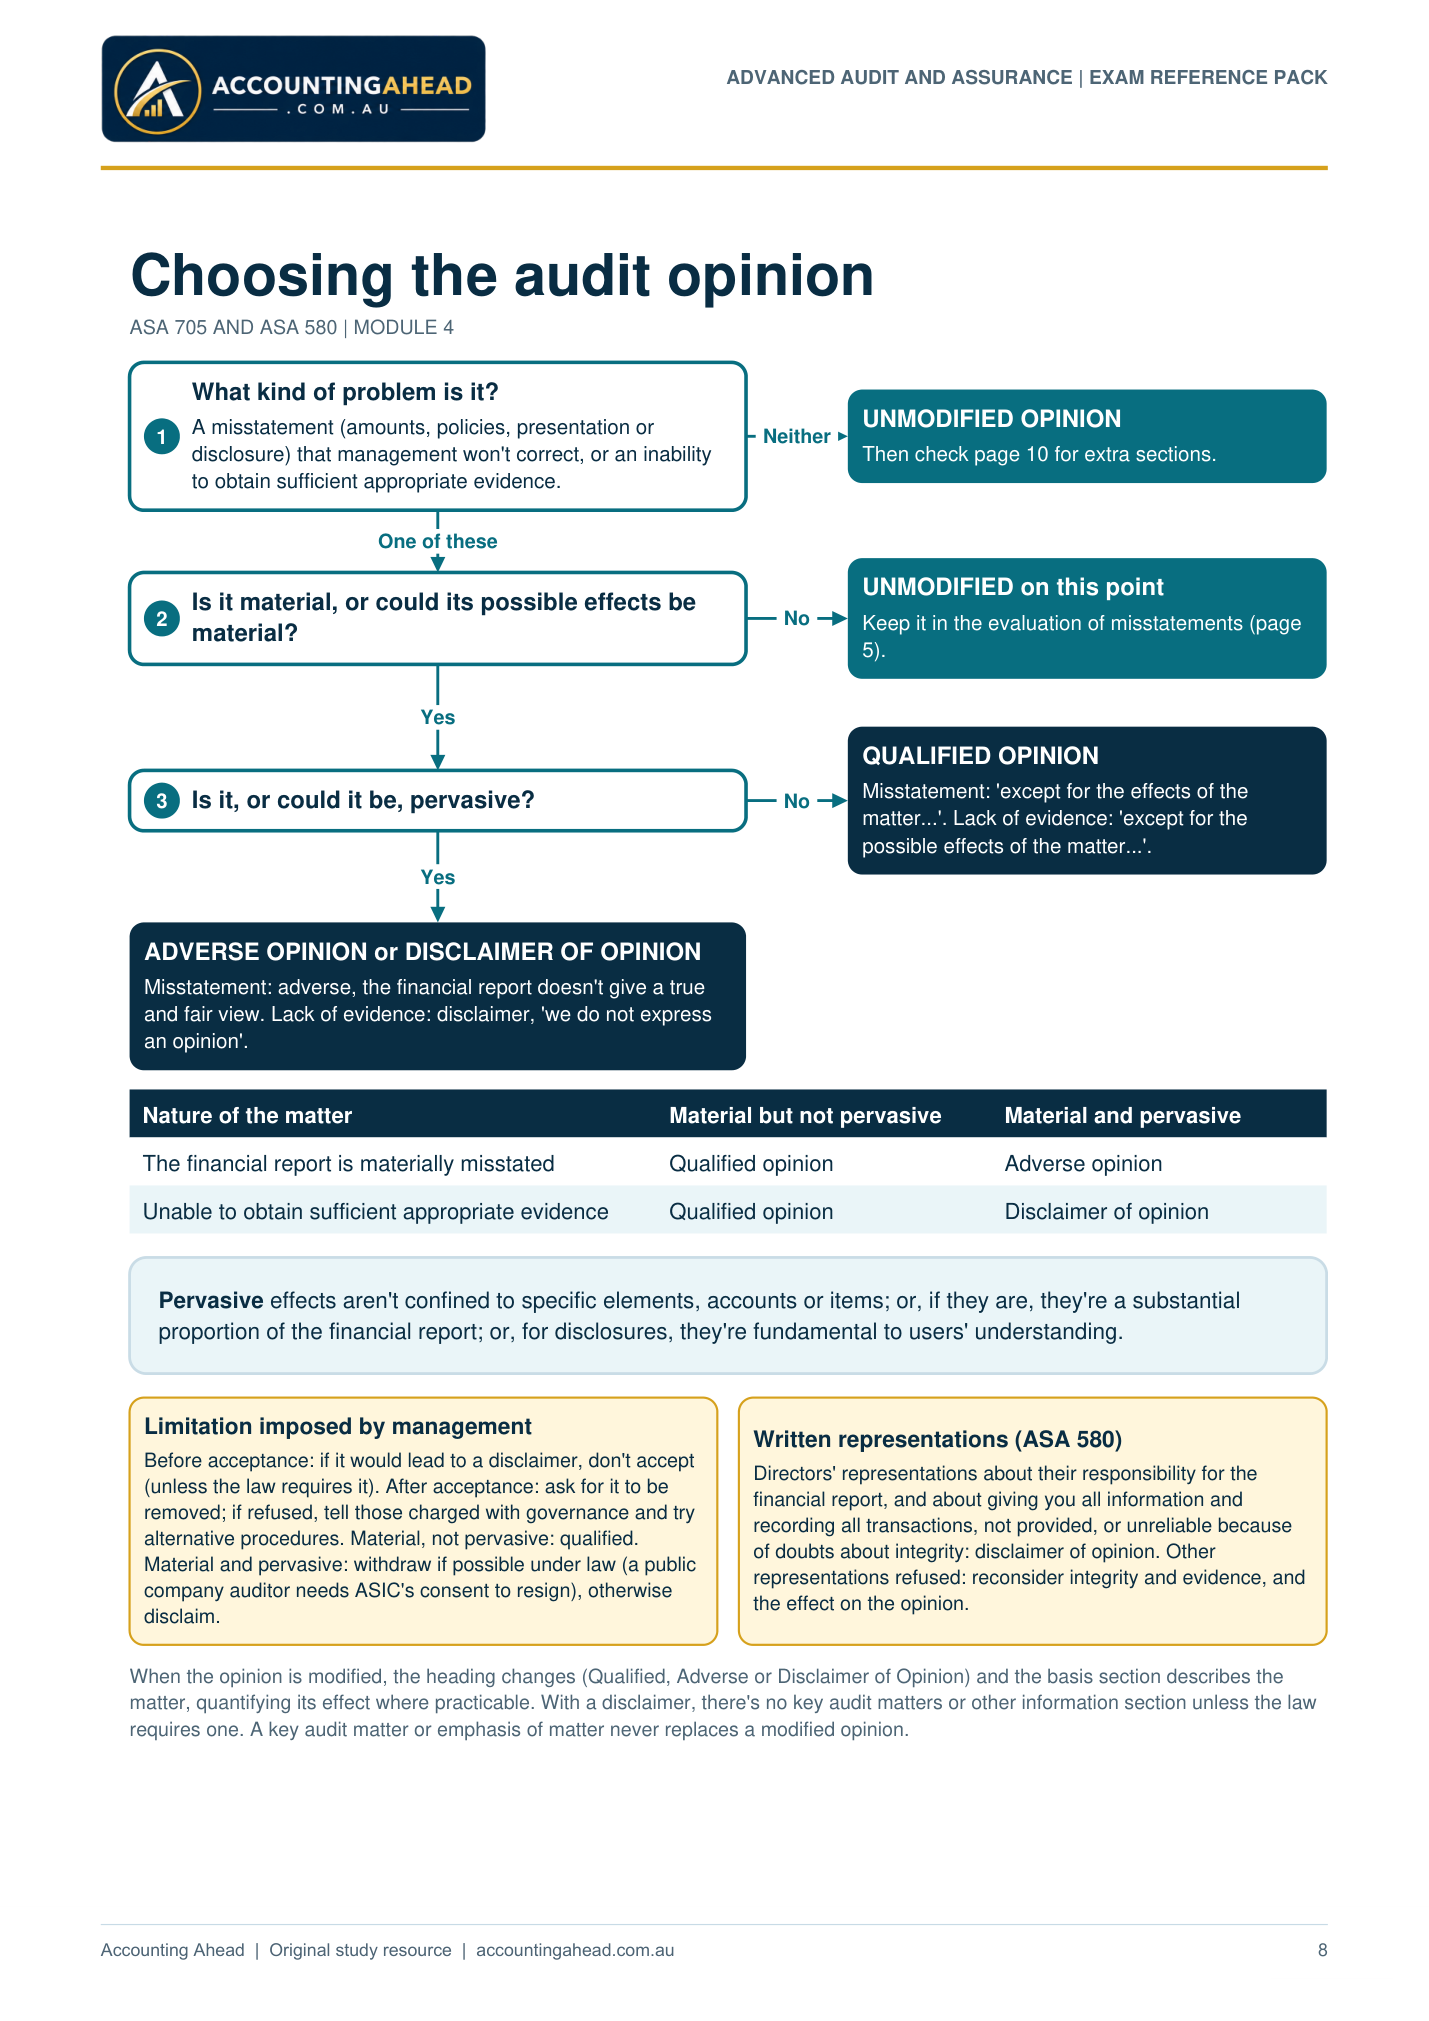
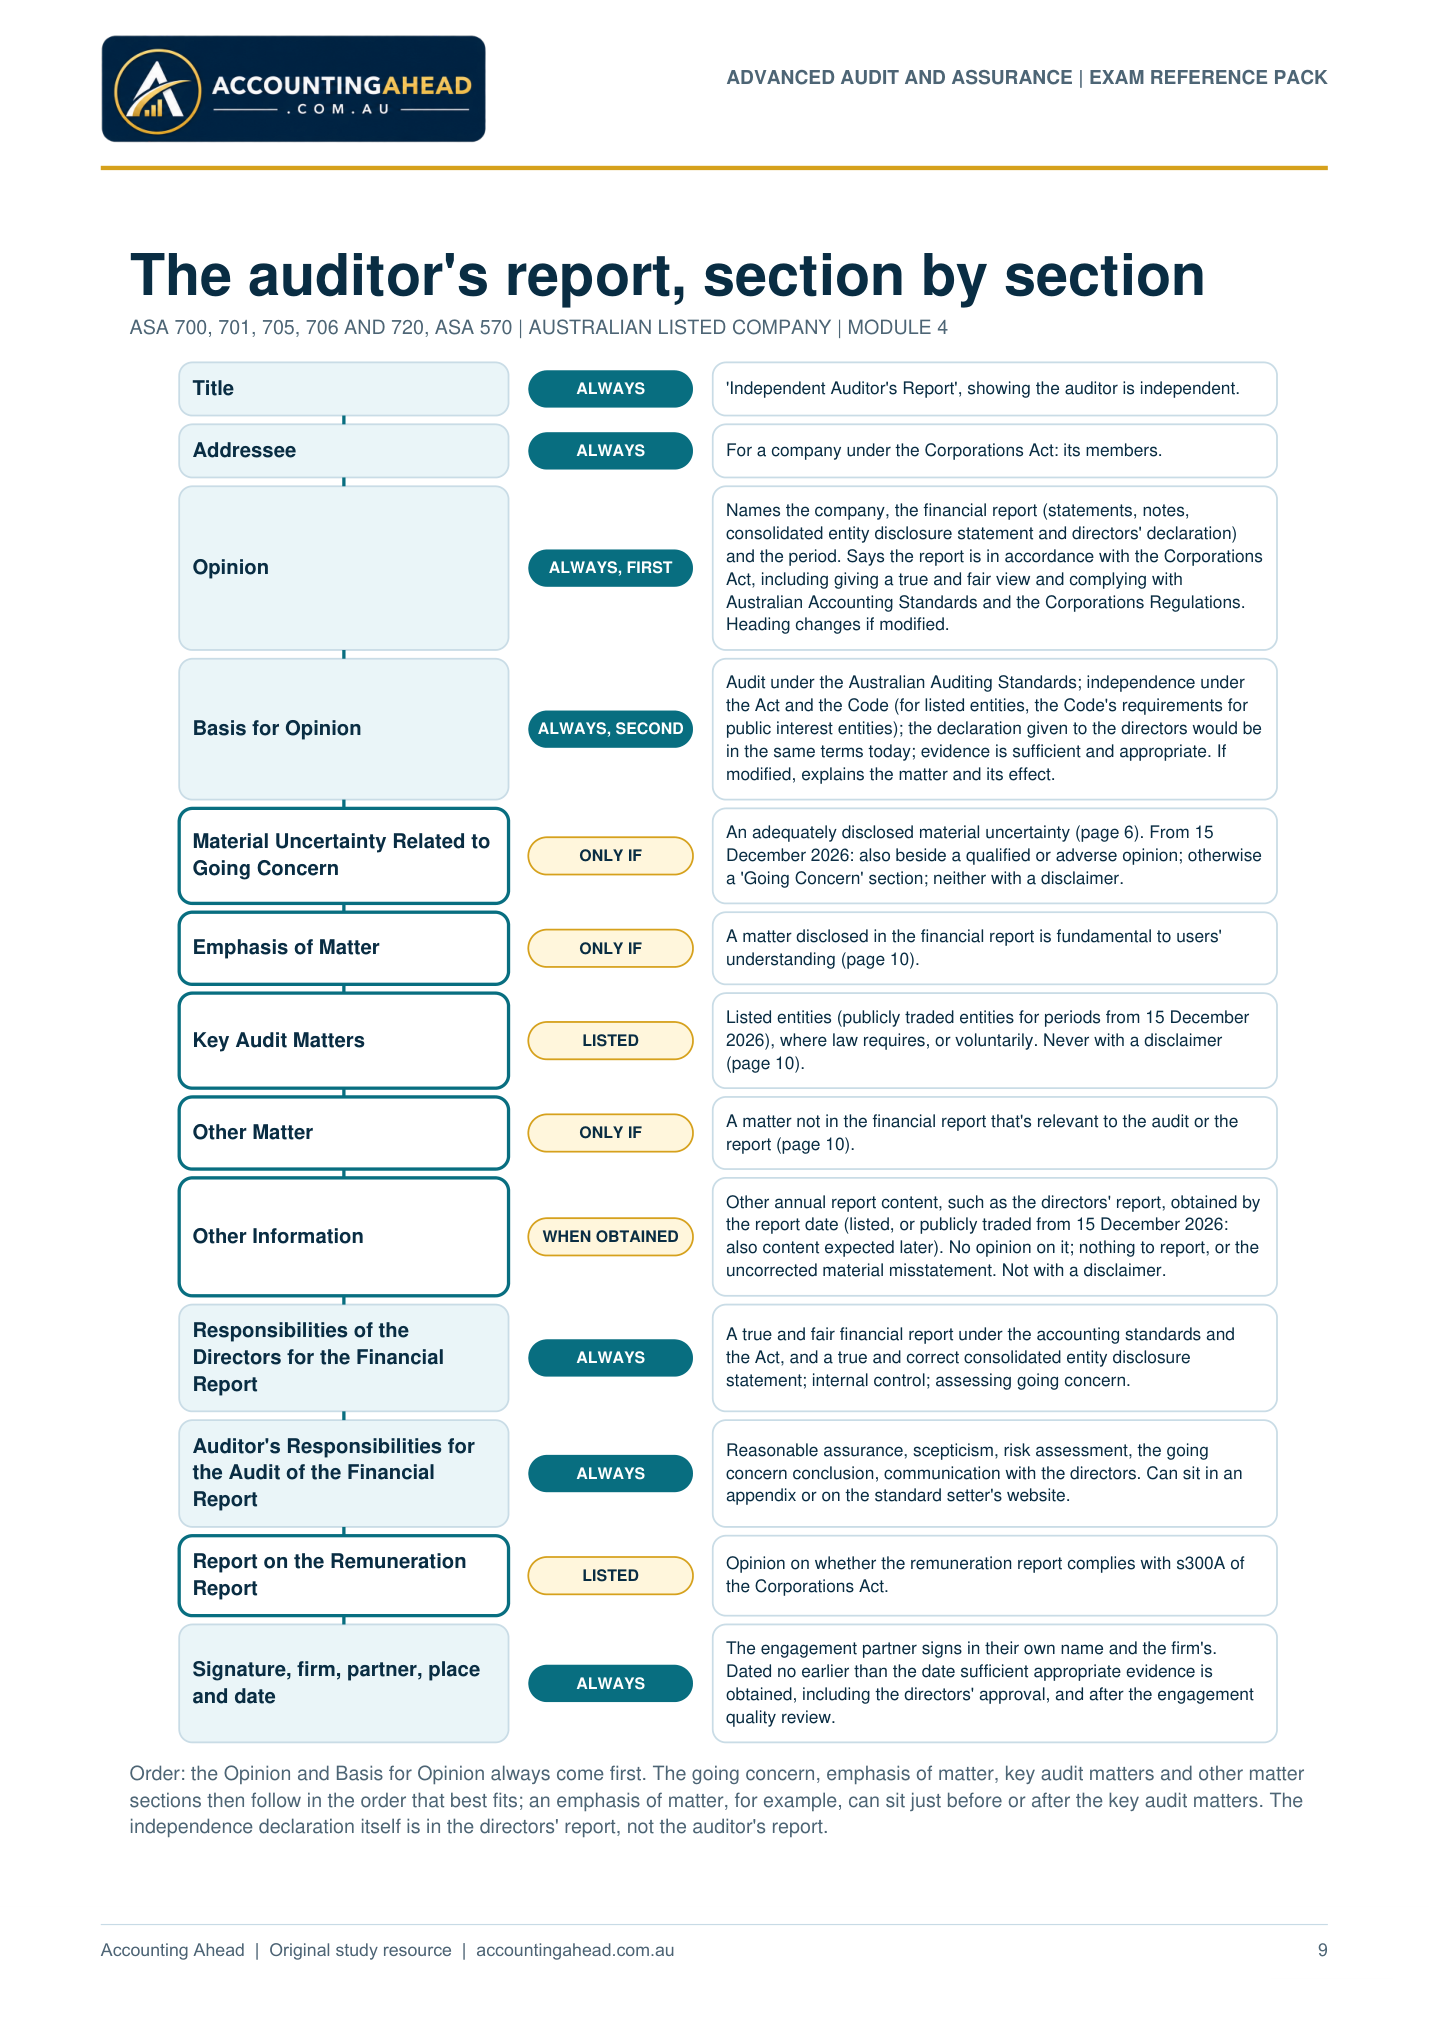
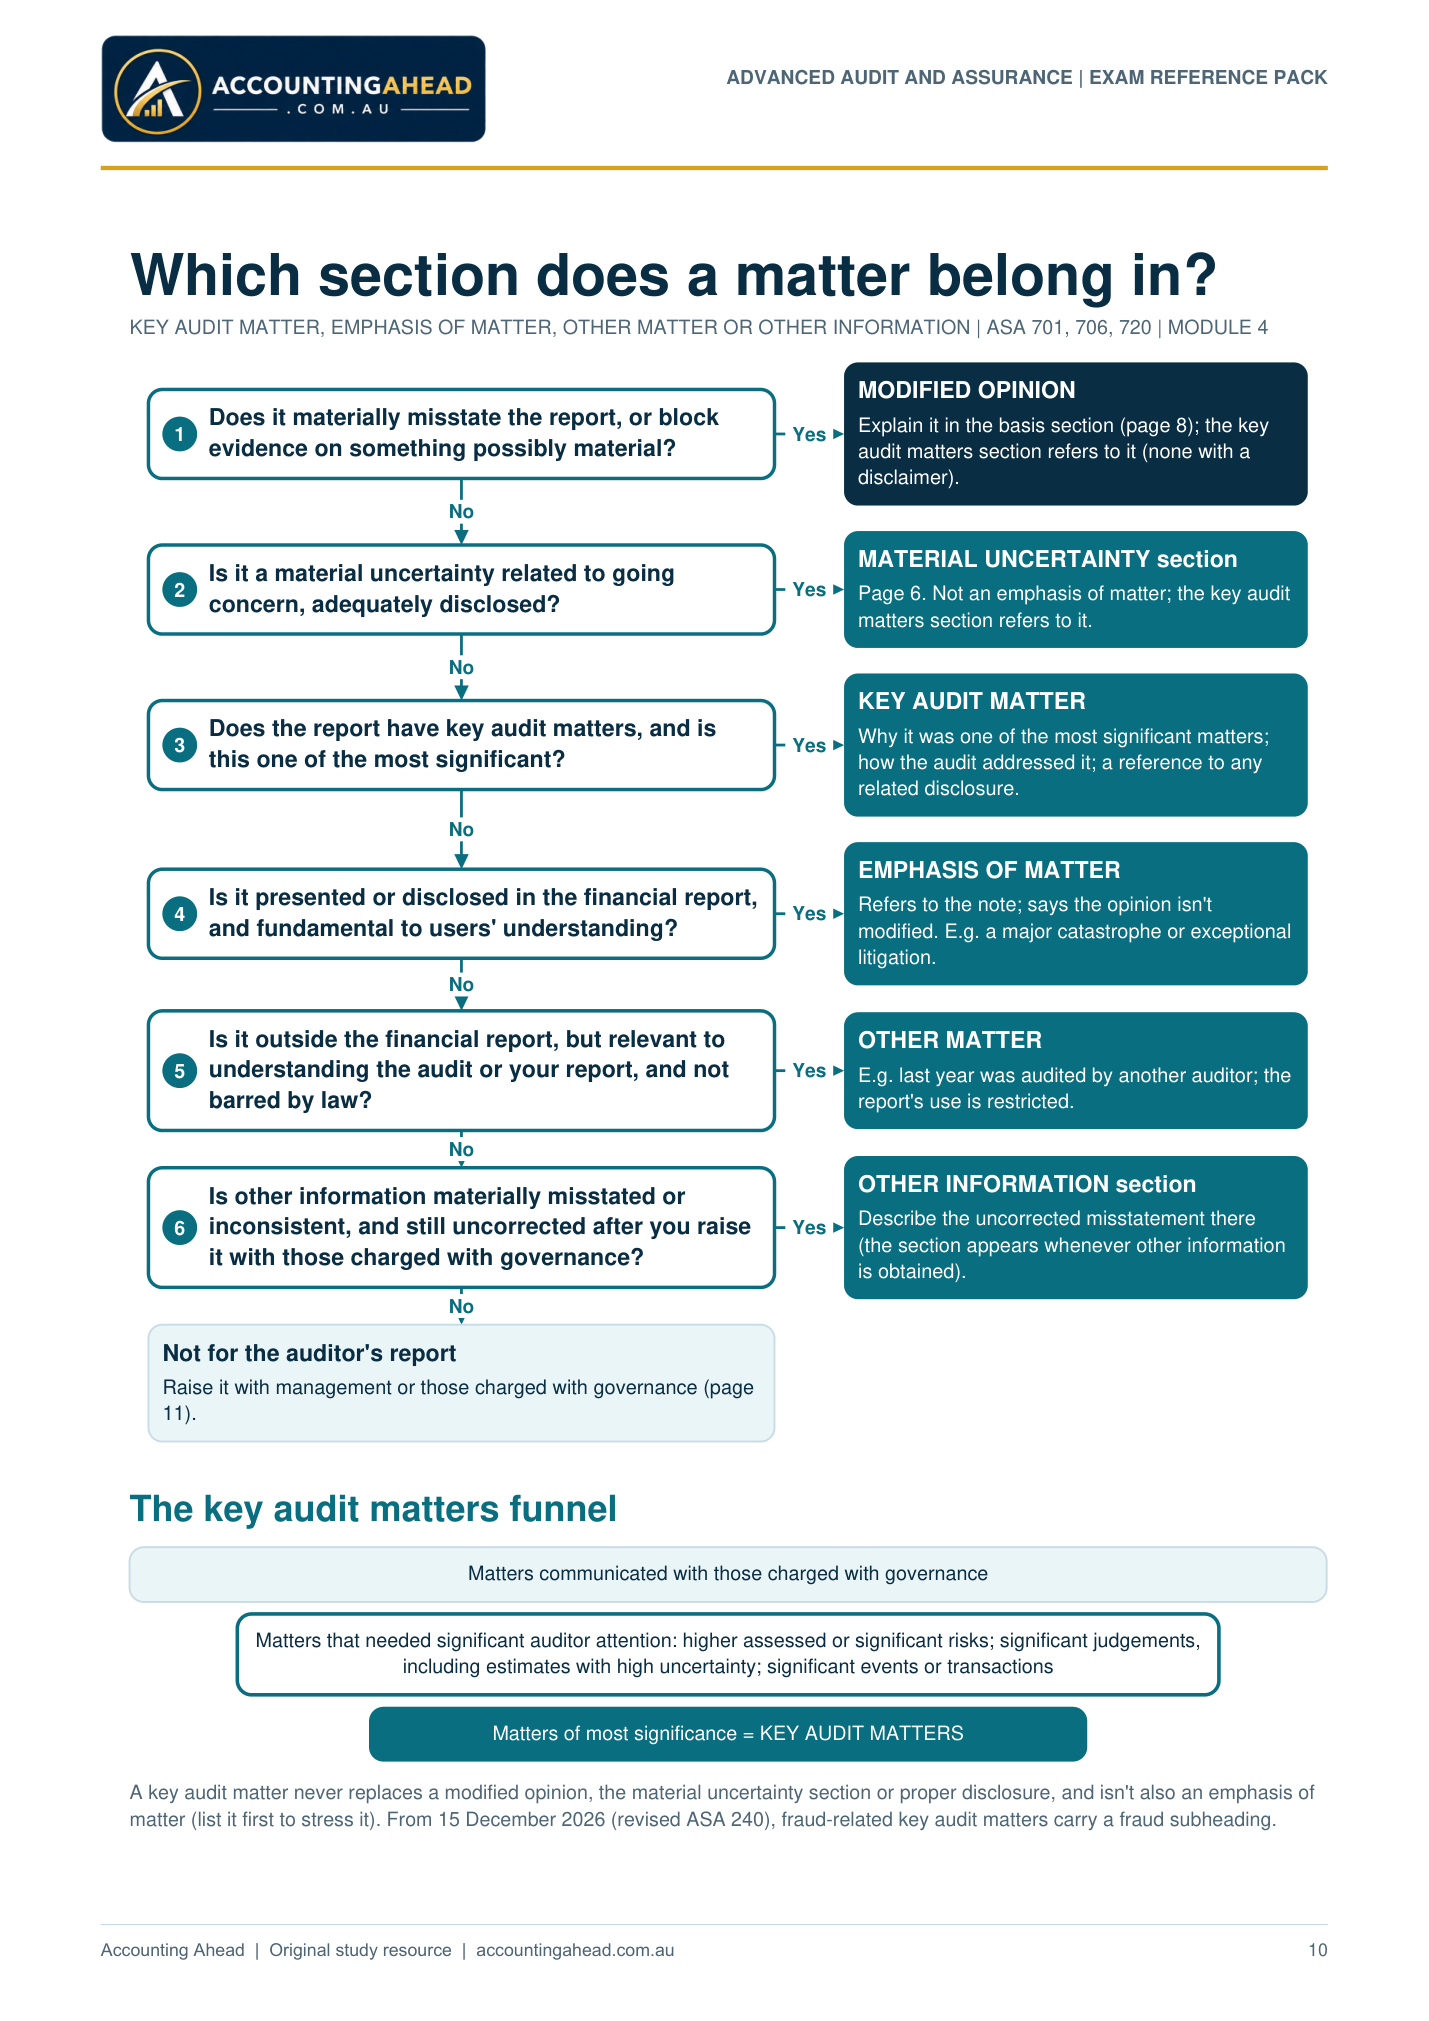
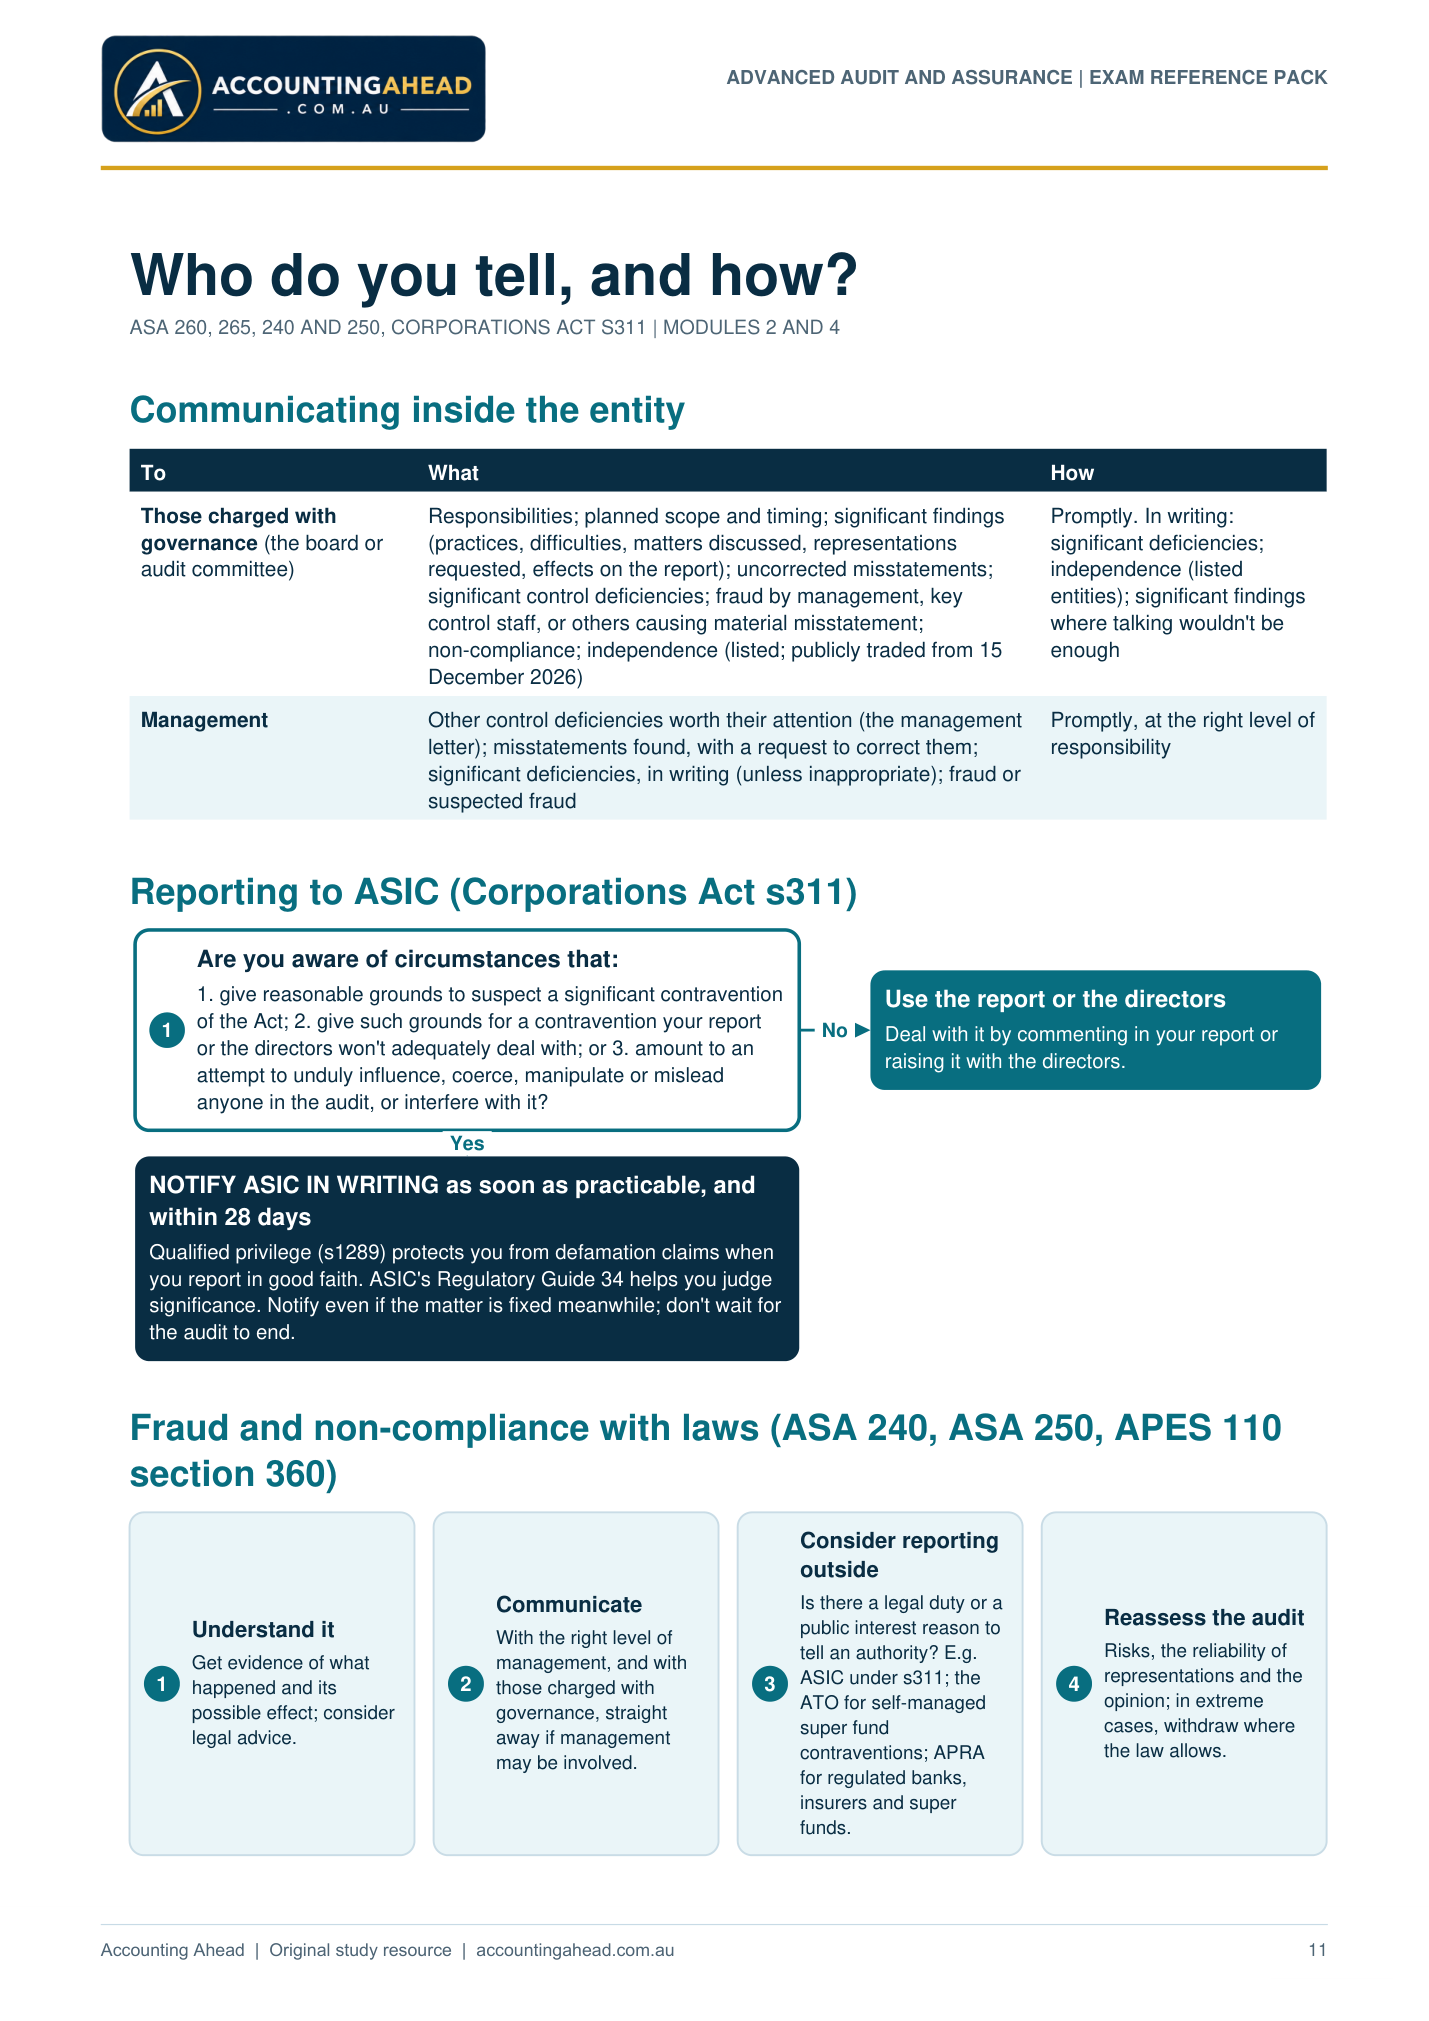
Watch the lectures →AAA exam reference pack · 1 PDF · 11 images →
Module 1 · The auditing and assurance framework
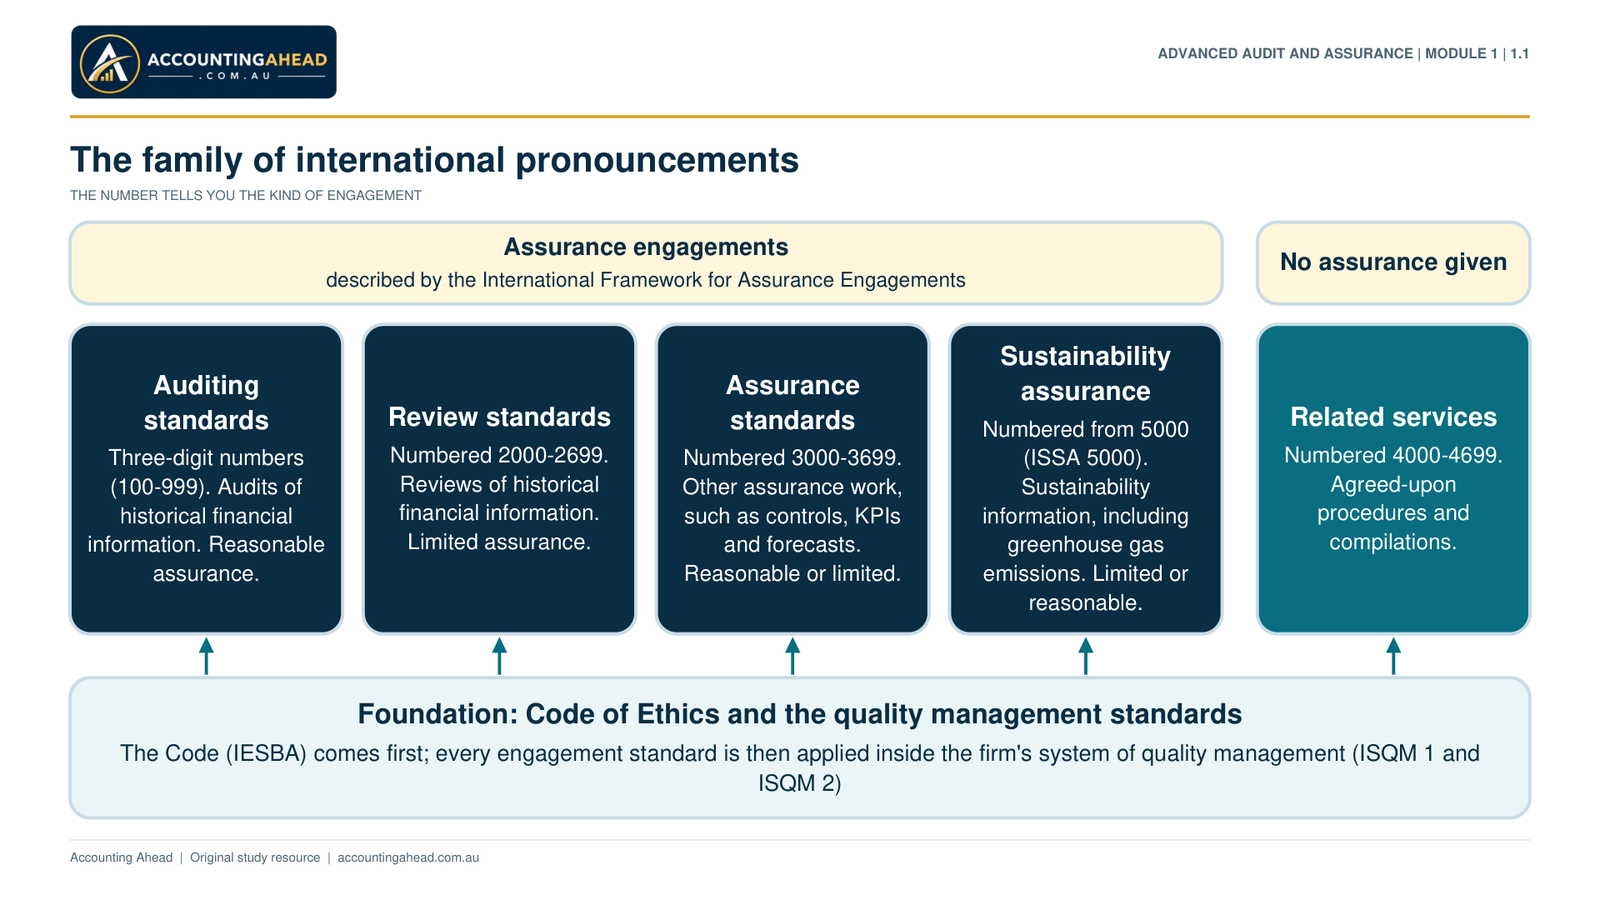
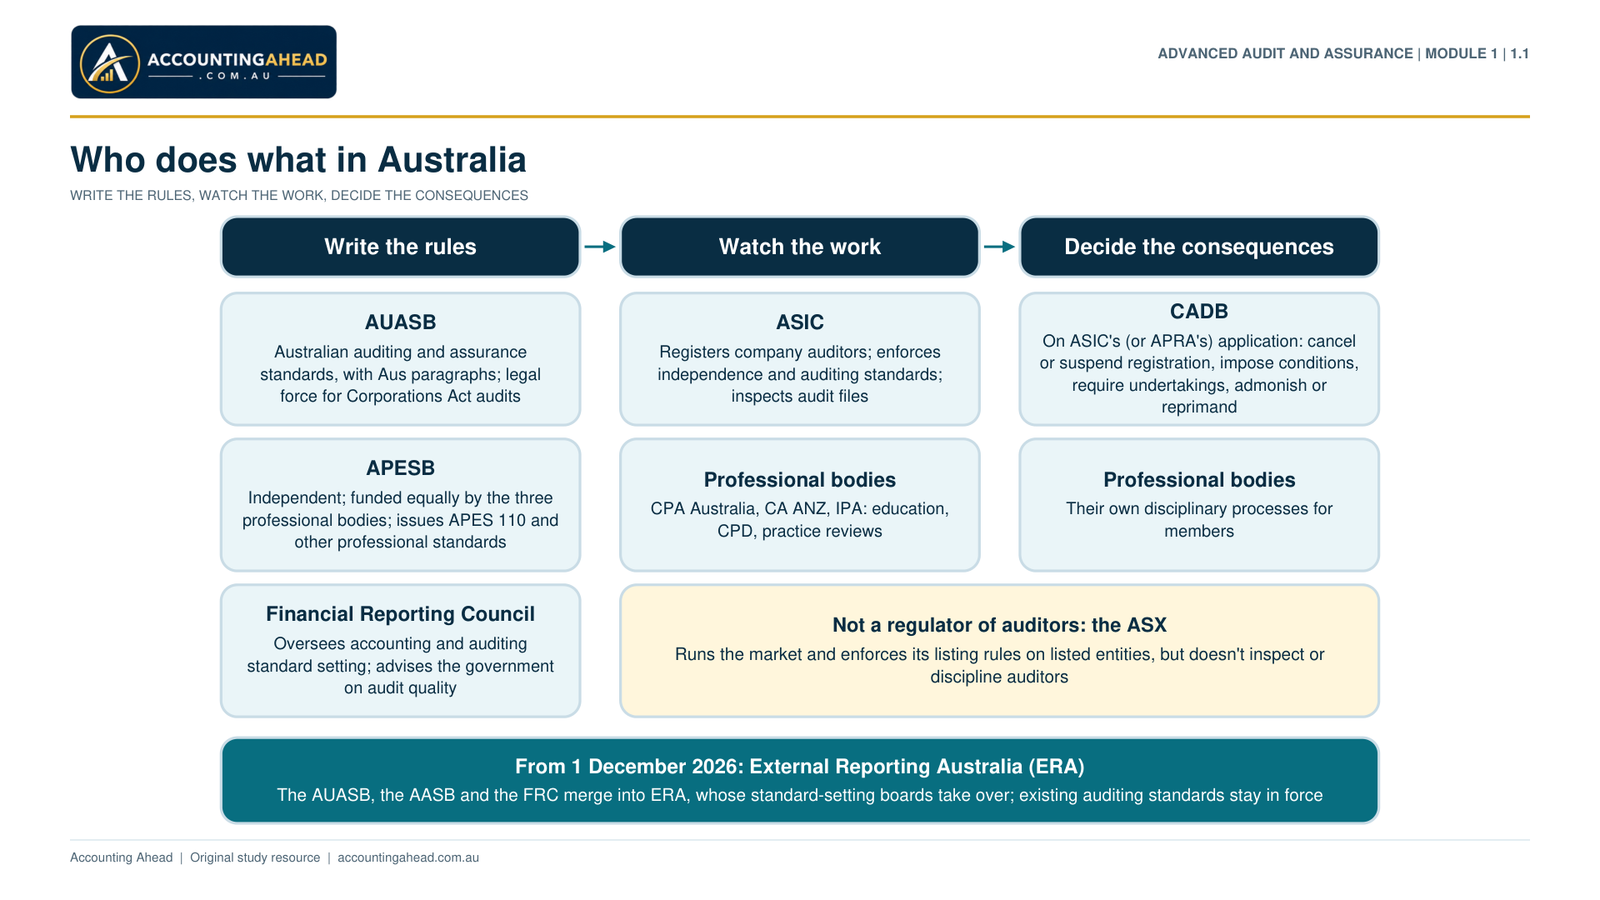
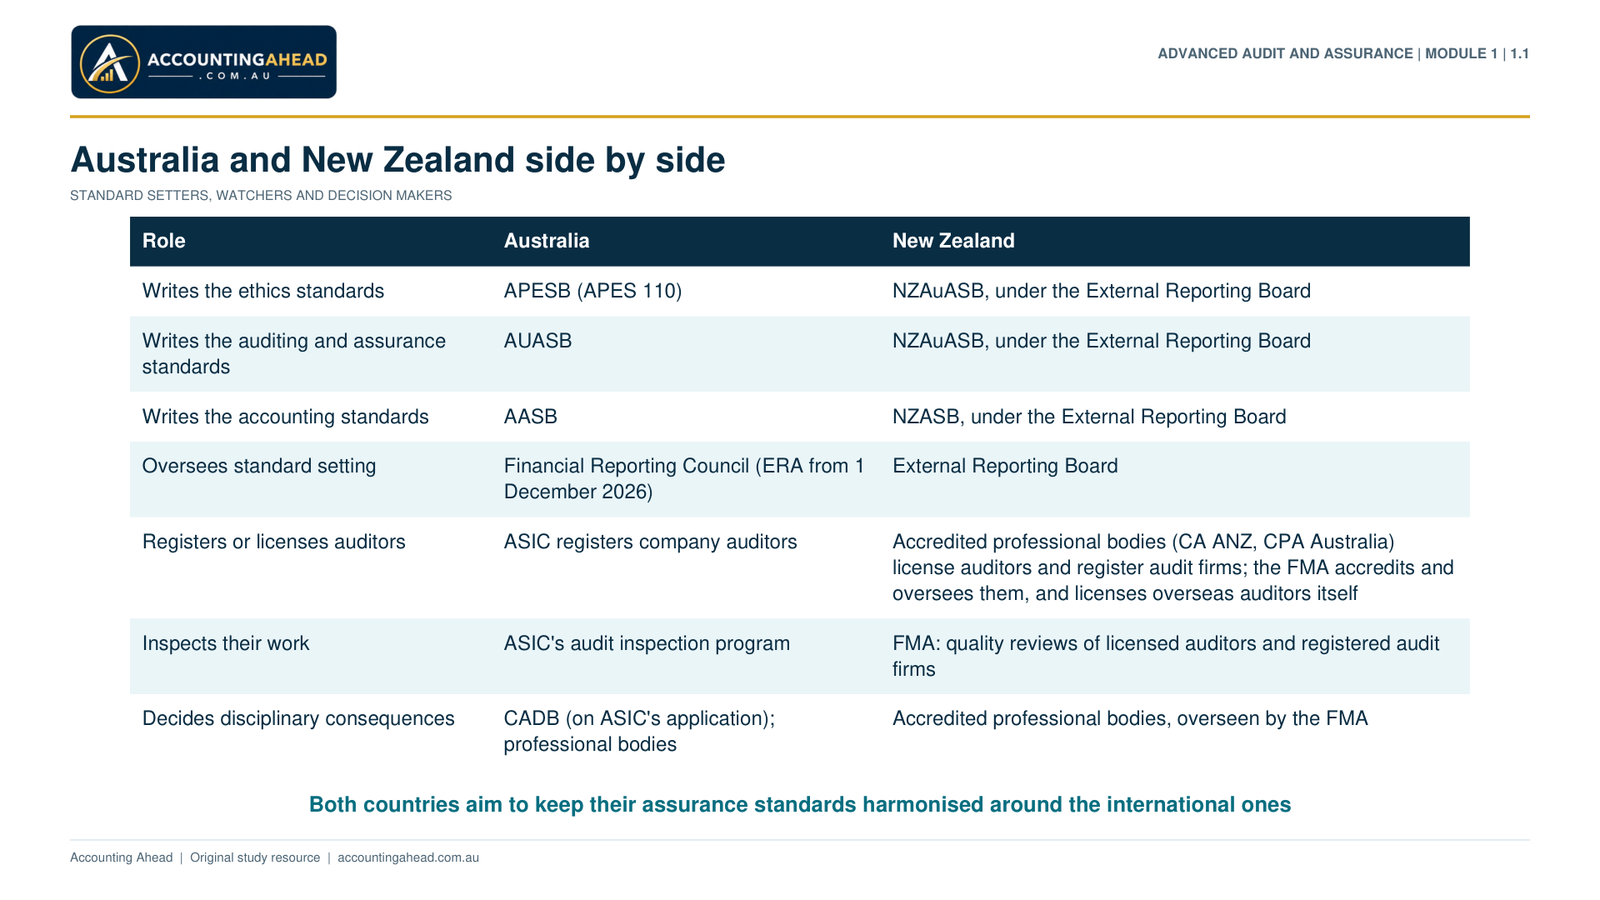
Part 1.1 · The Assurance Environment and Its Regulators
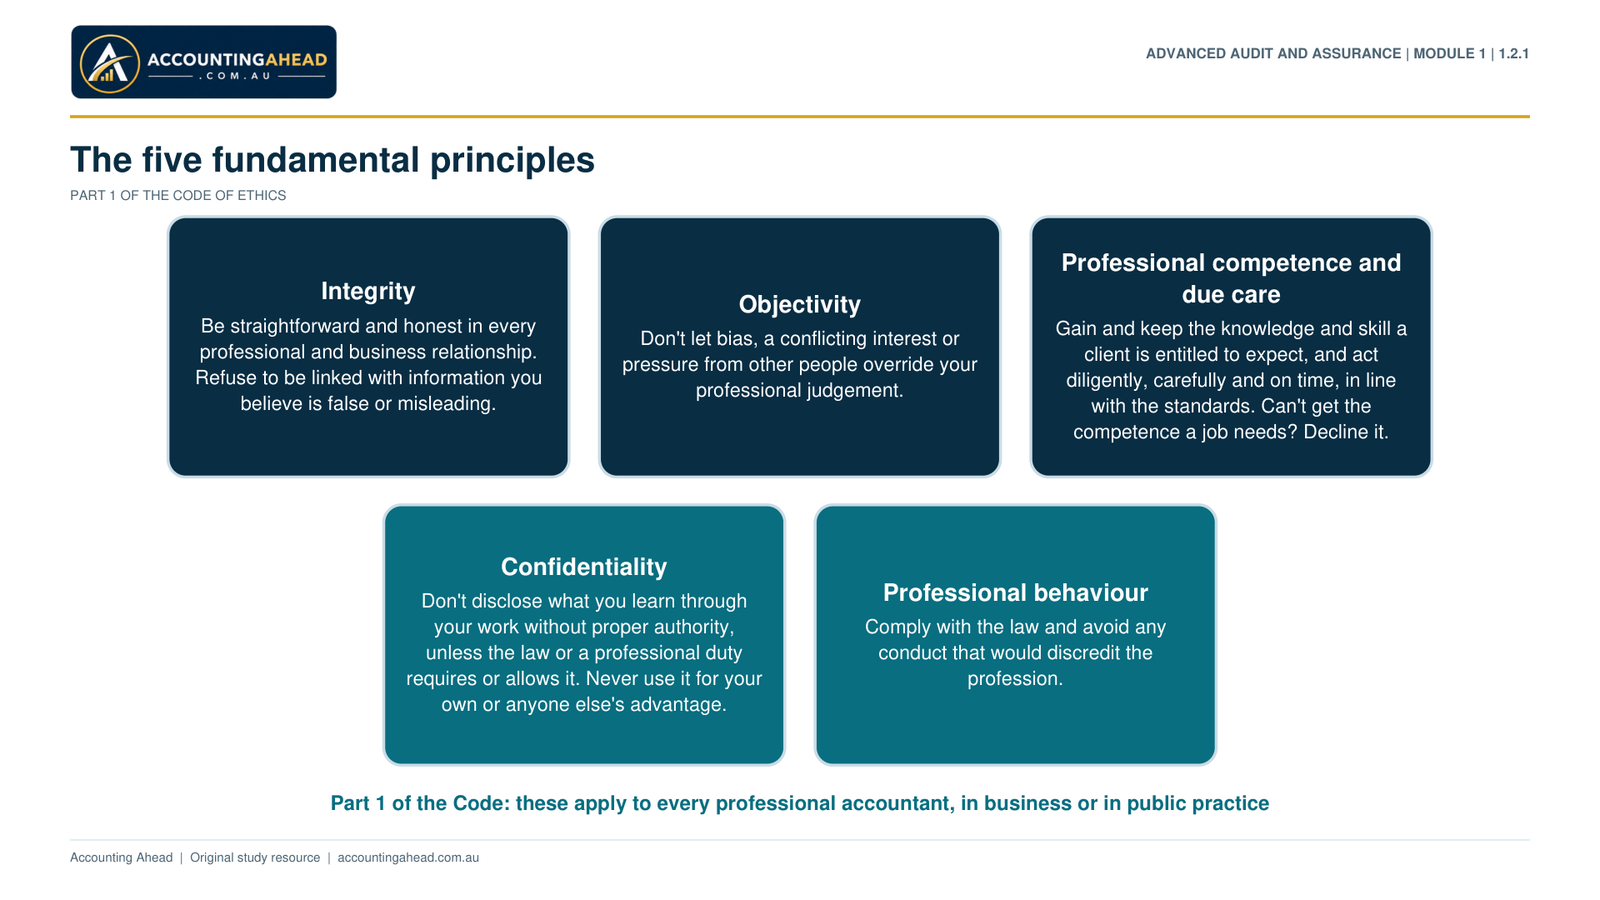
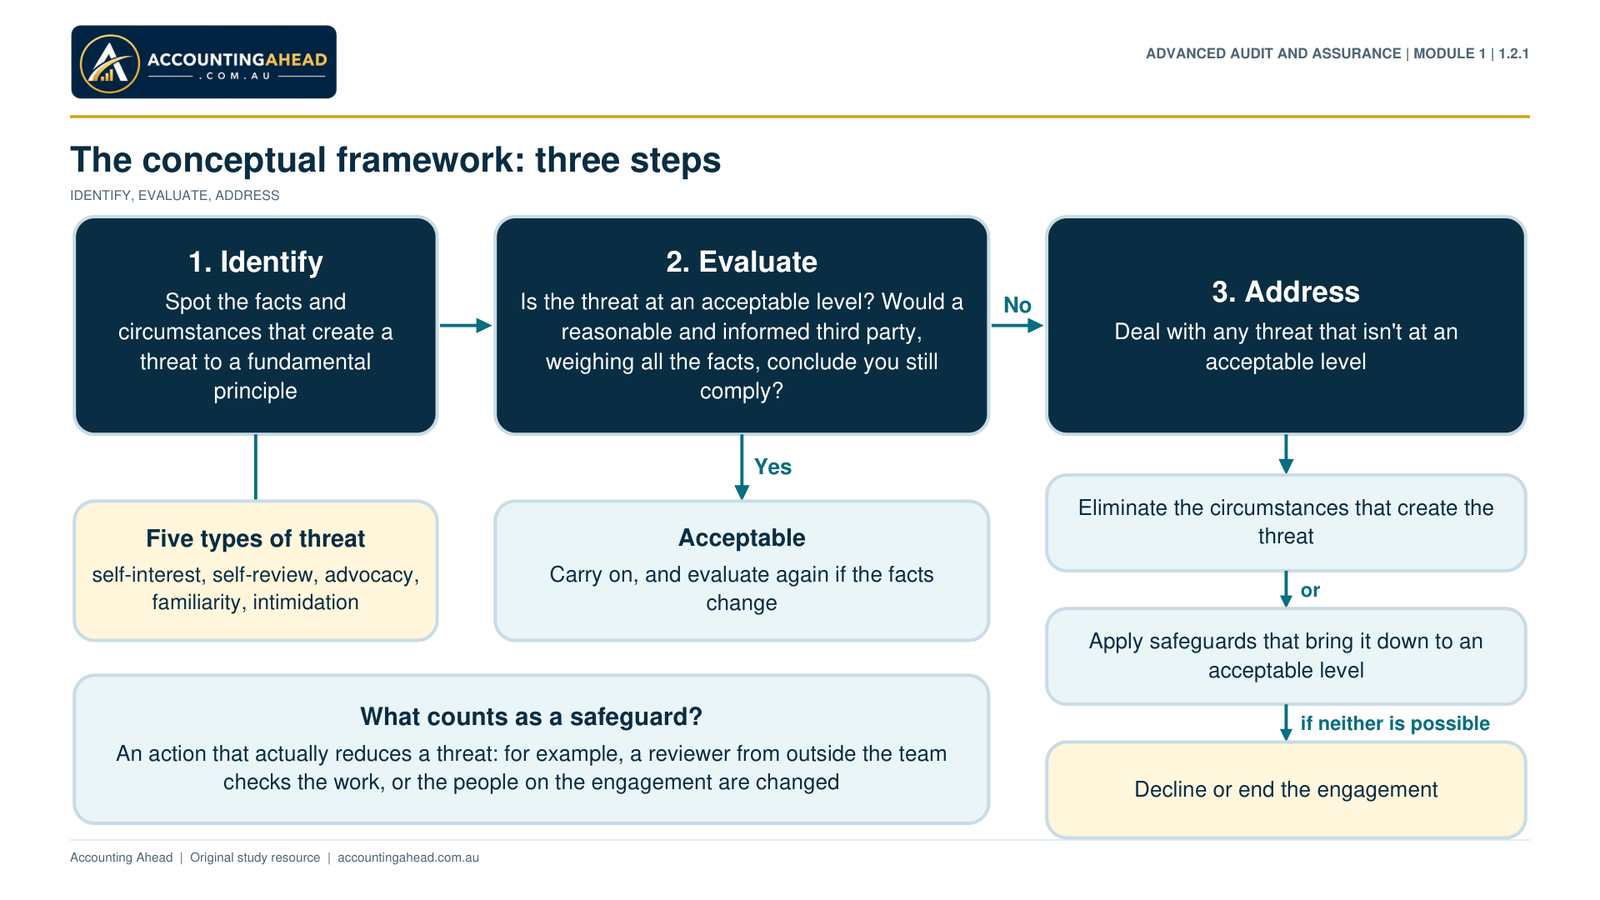
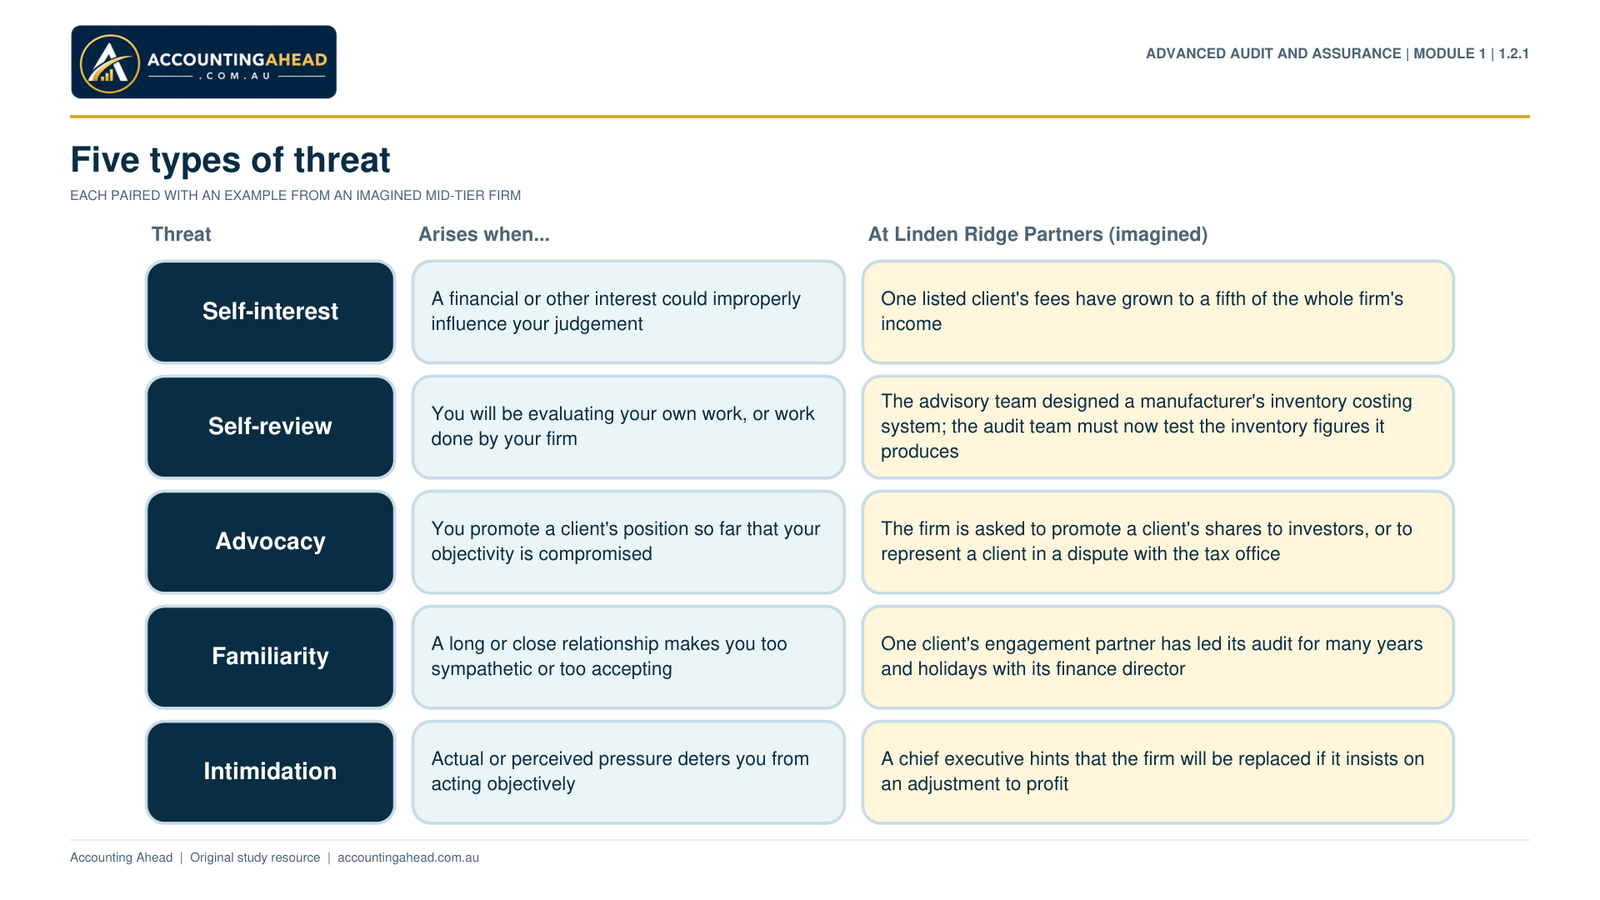
Part 1.2.1 · Fundamental Principles, Threats and Safeguards
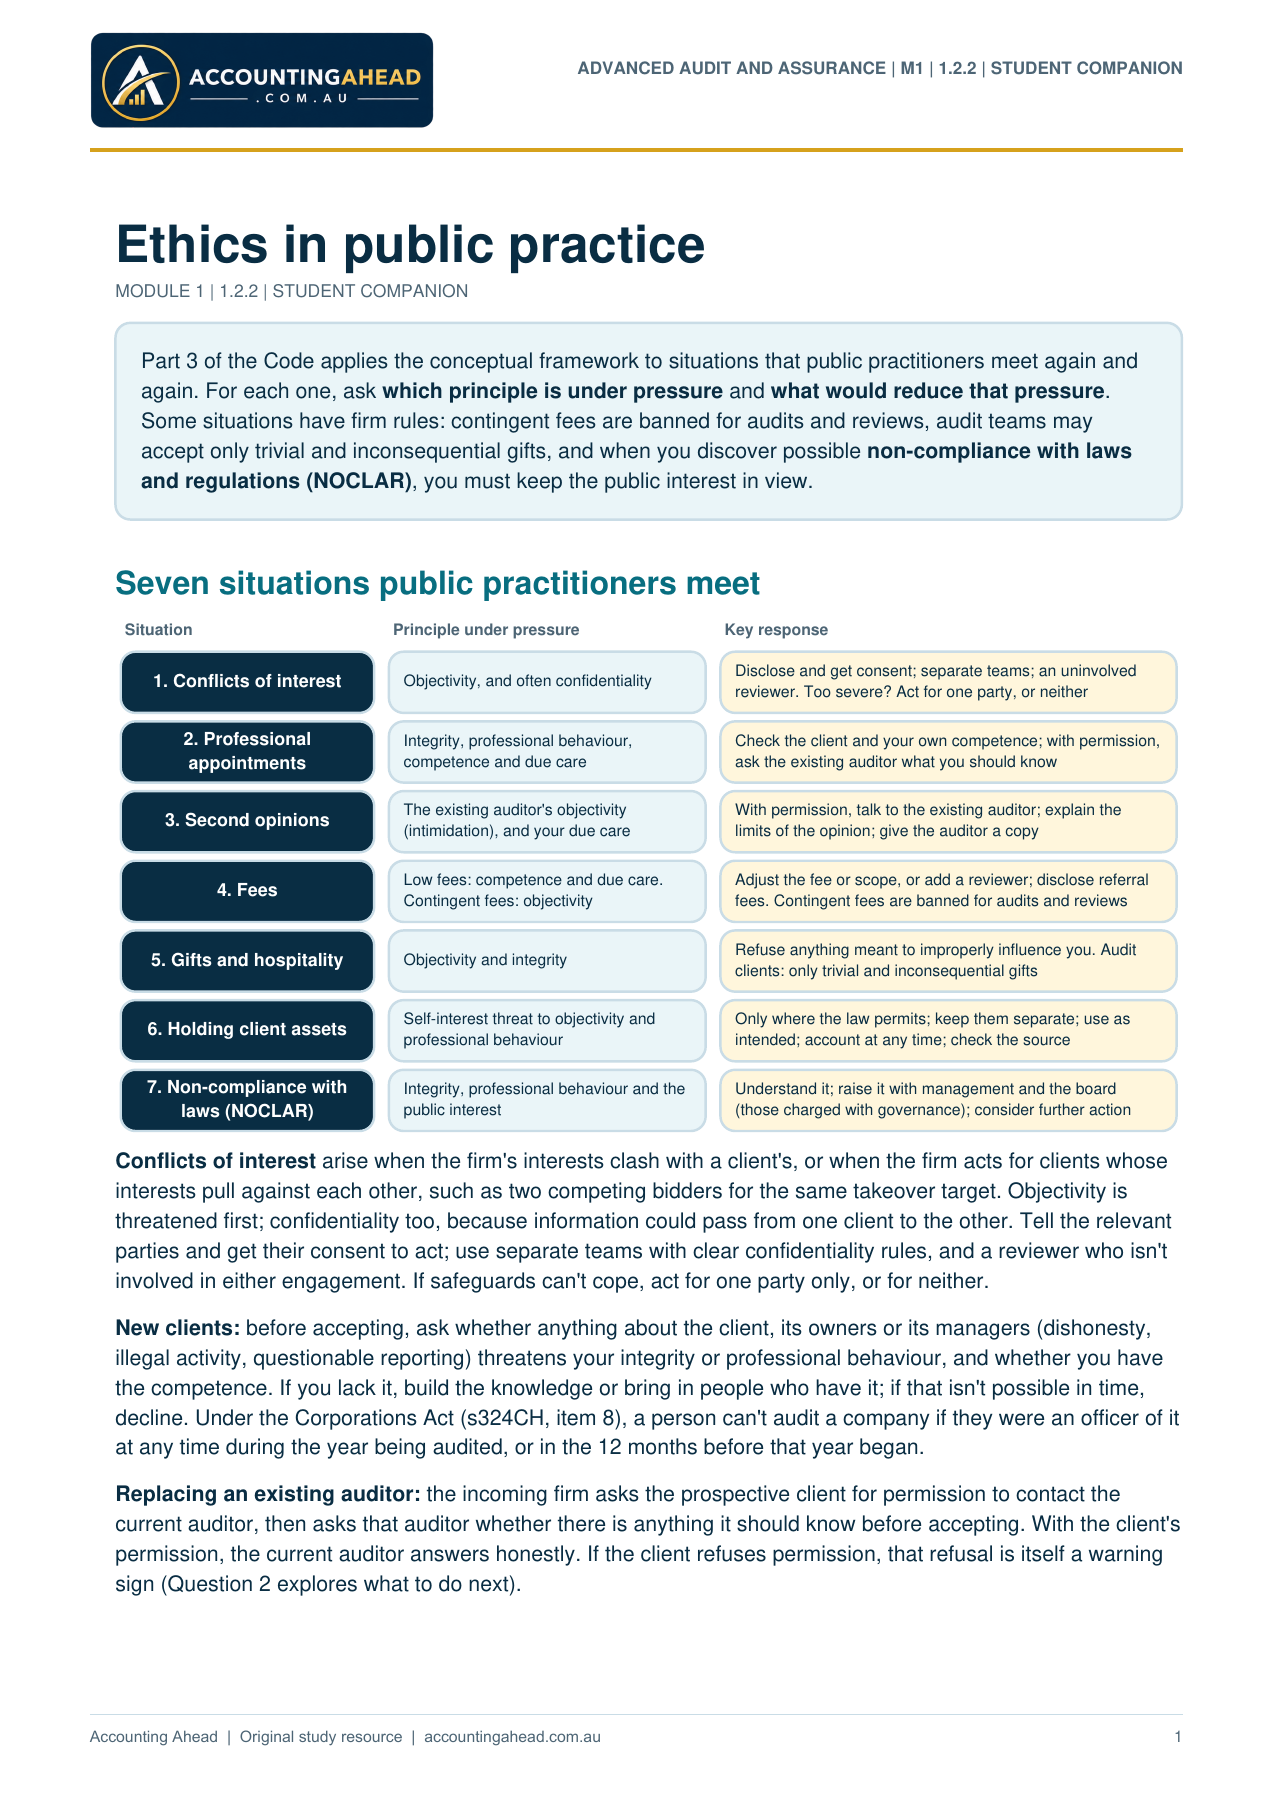
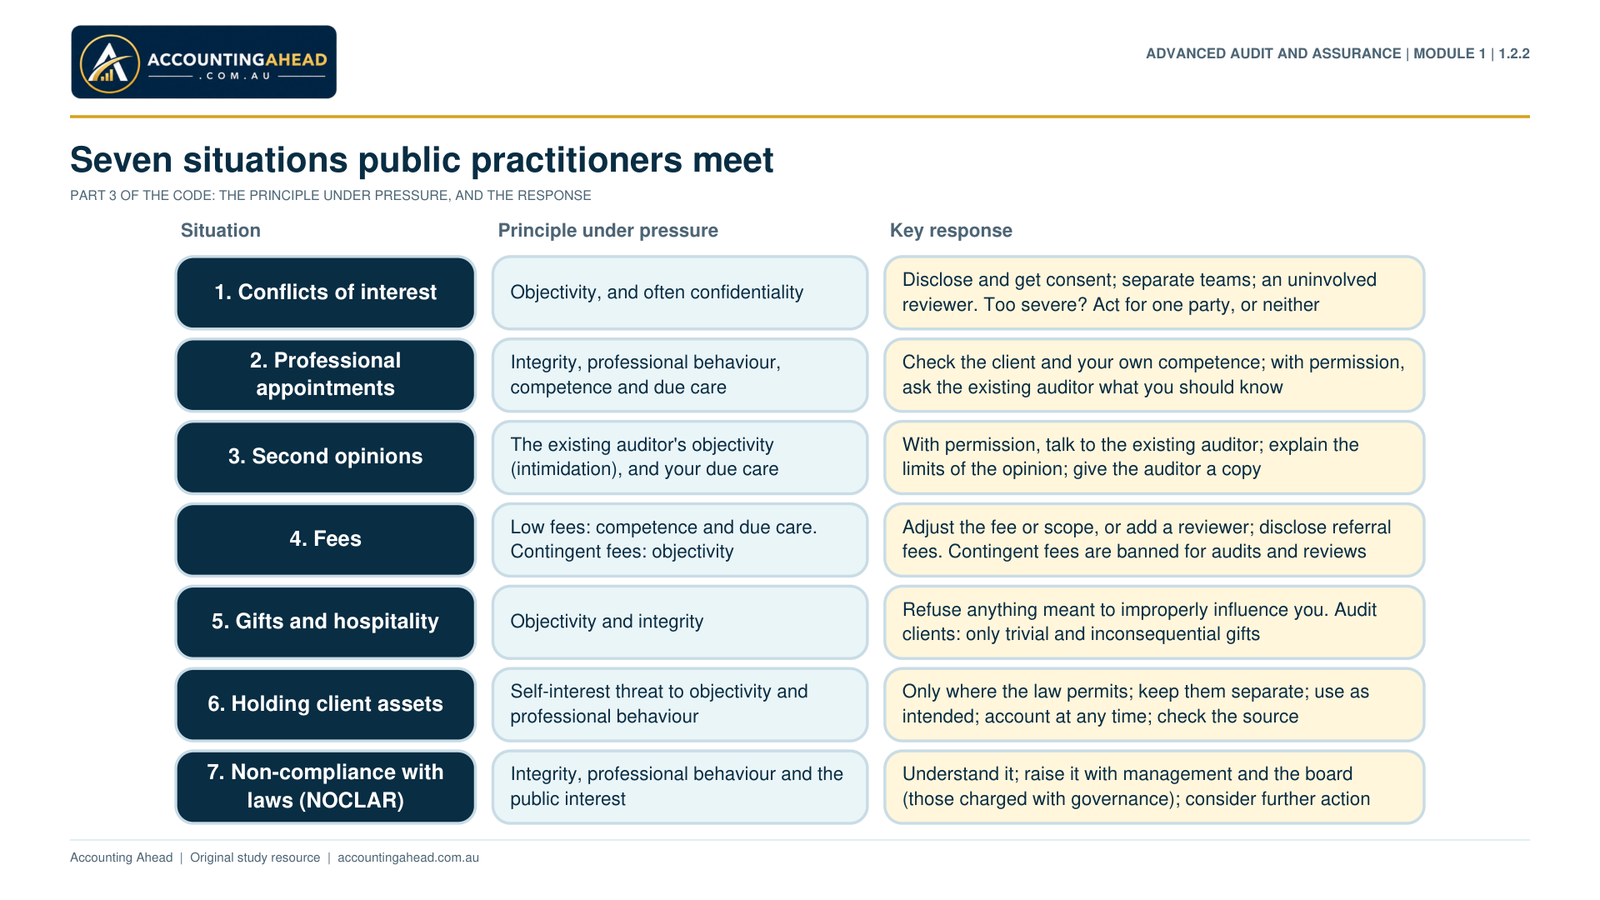
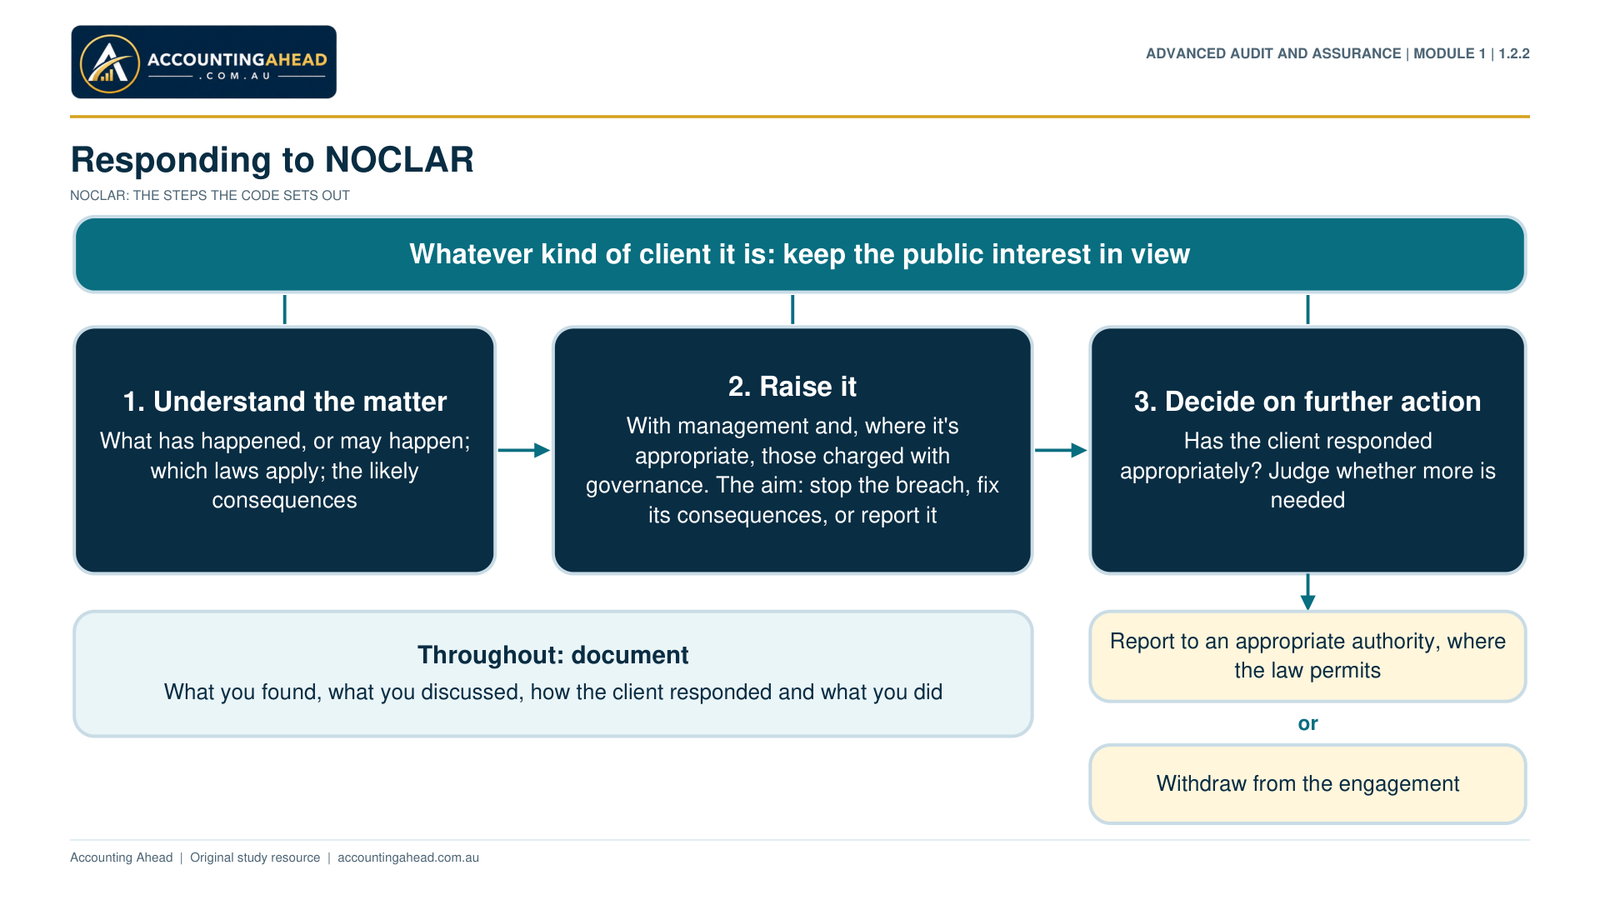
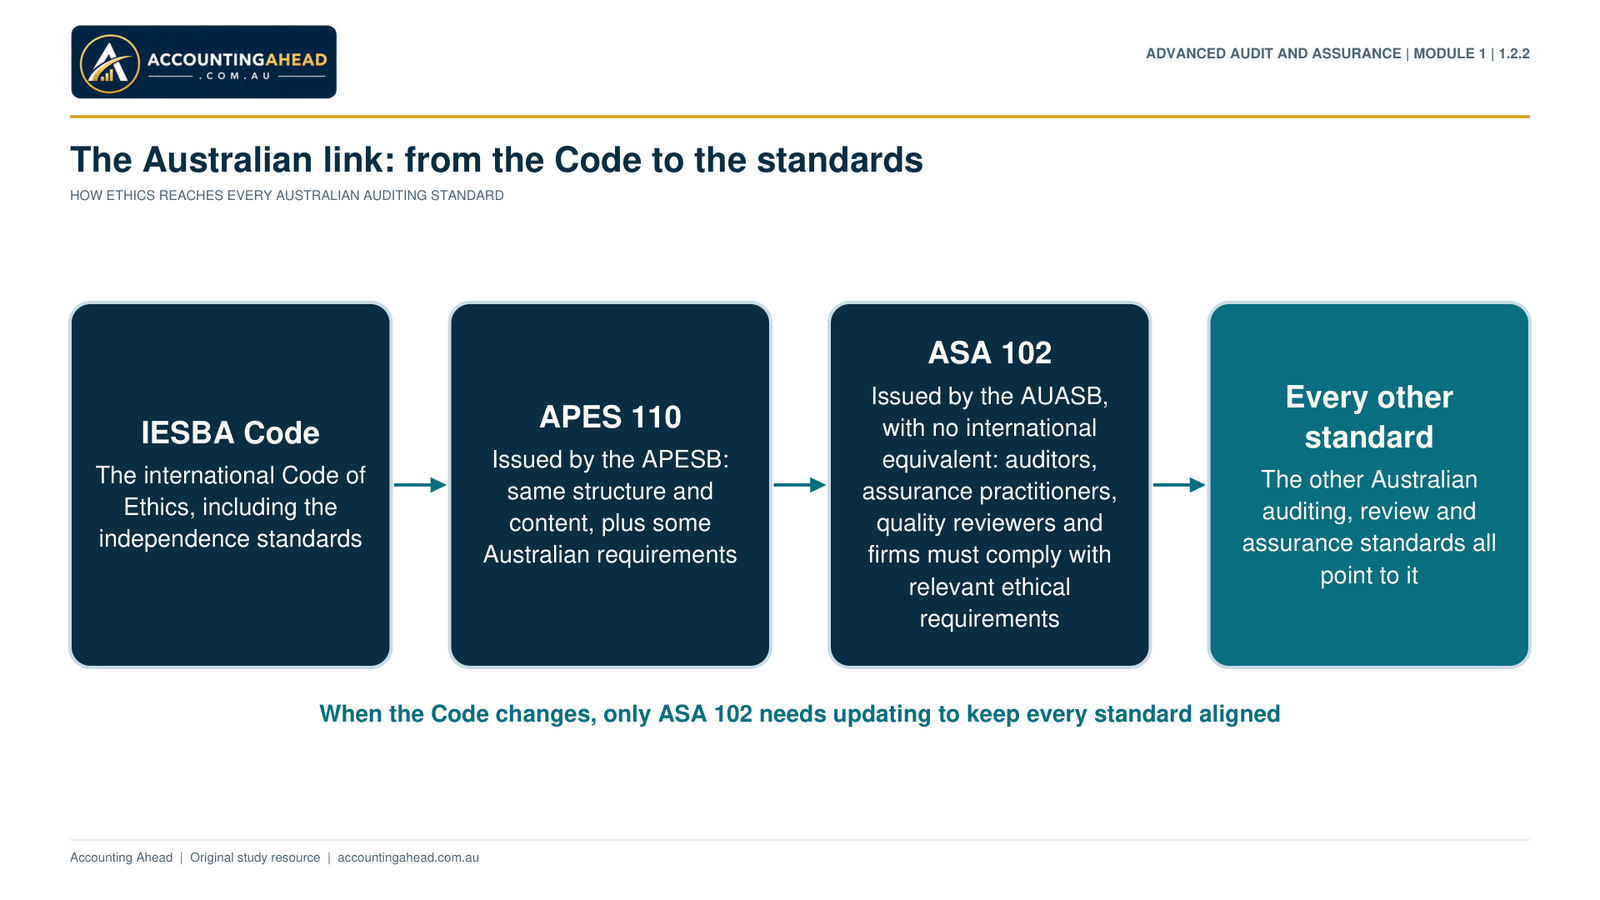
Part 1.2.2 · Ethics in Public Practice
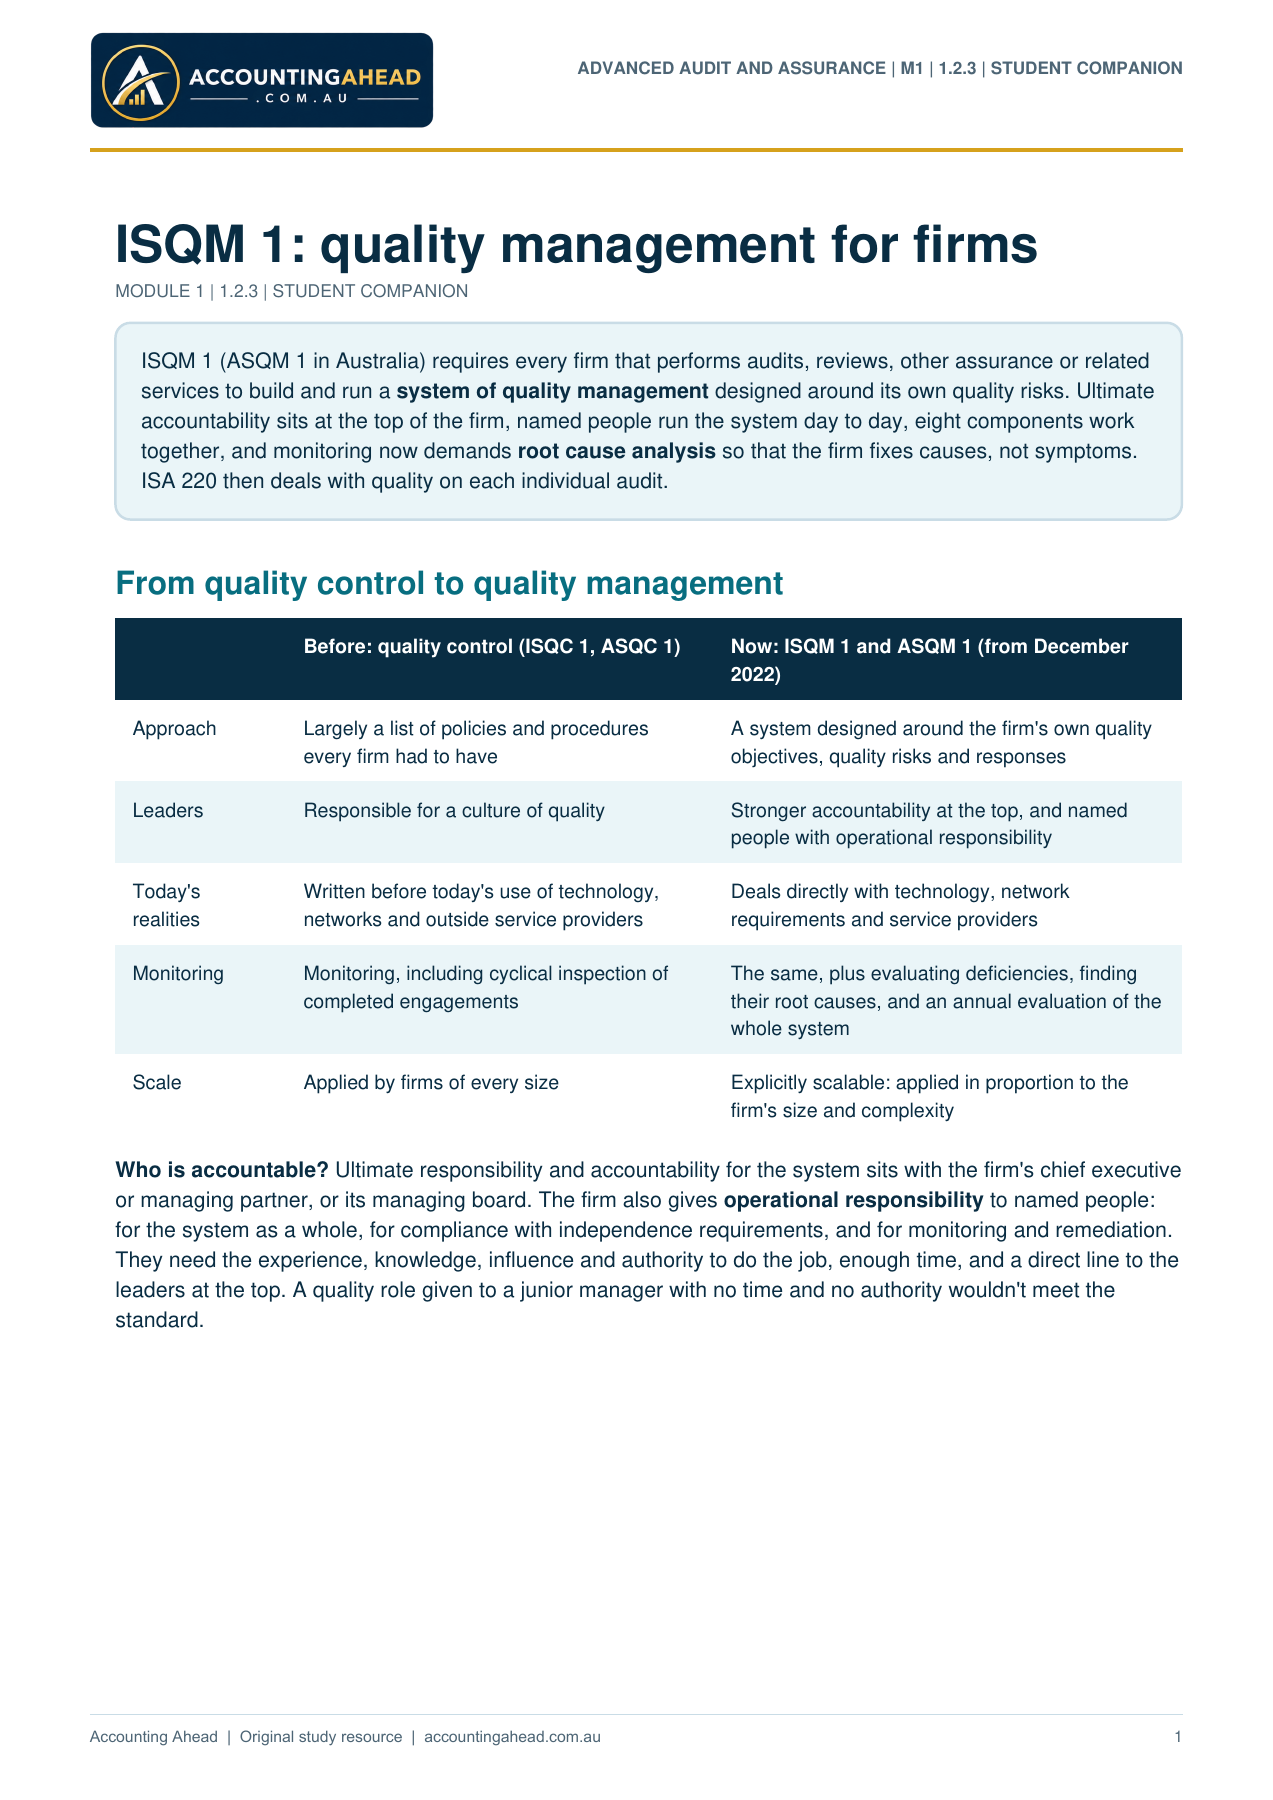
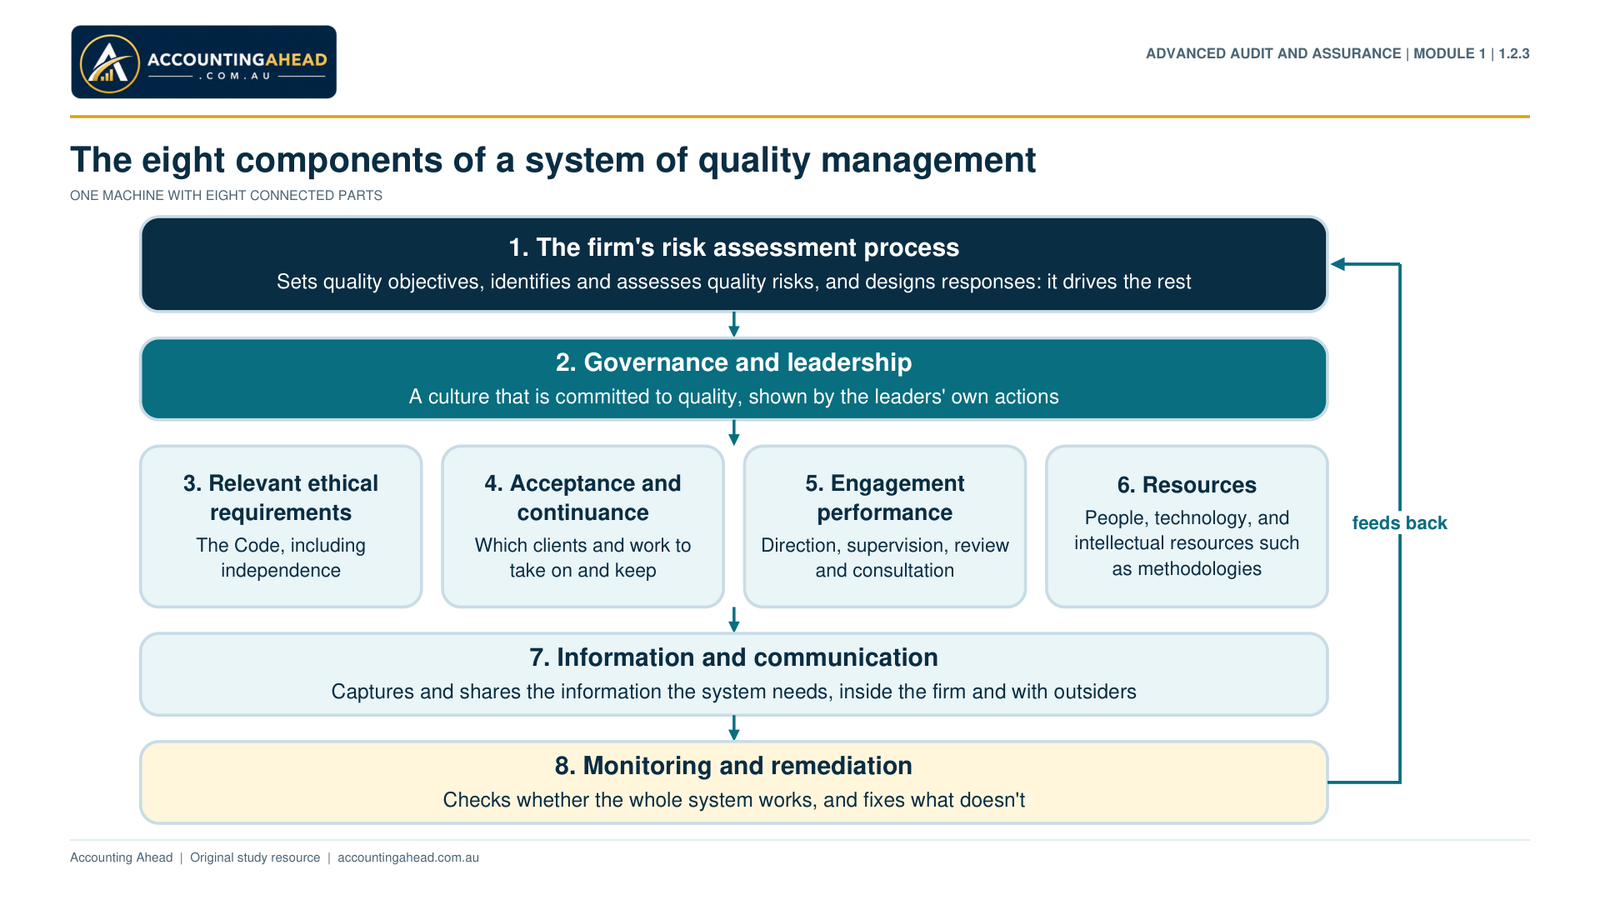
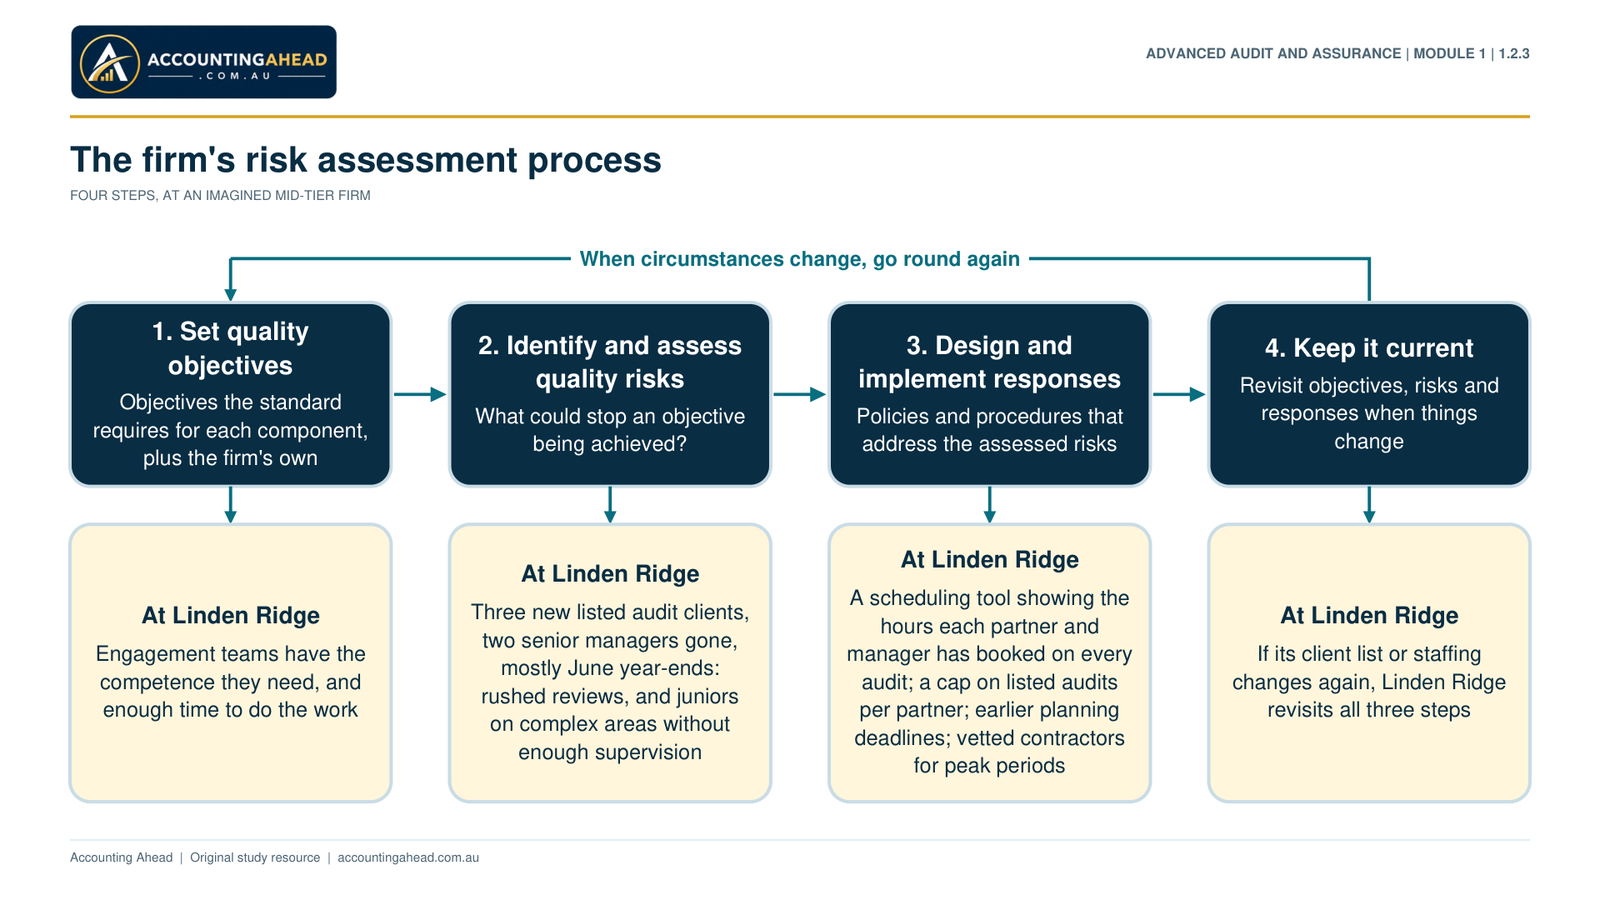
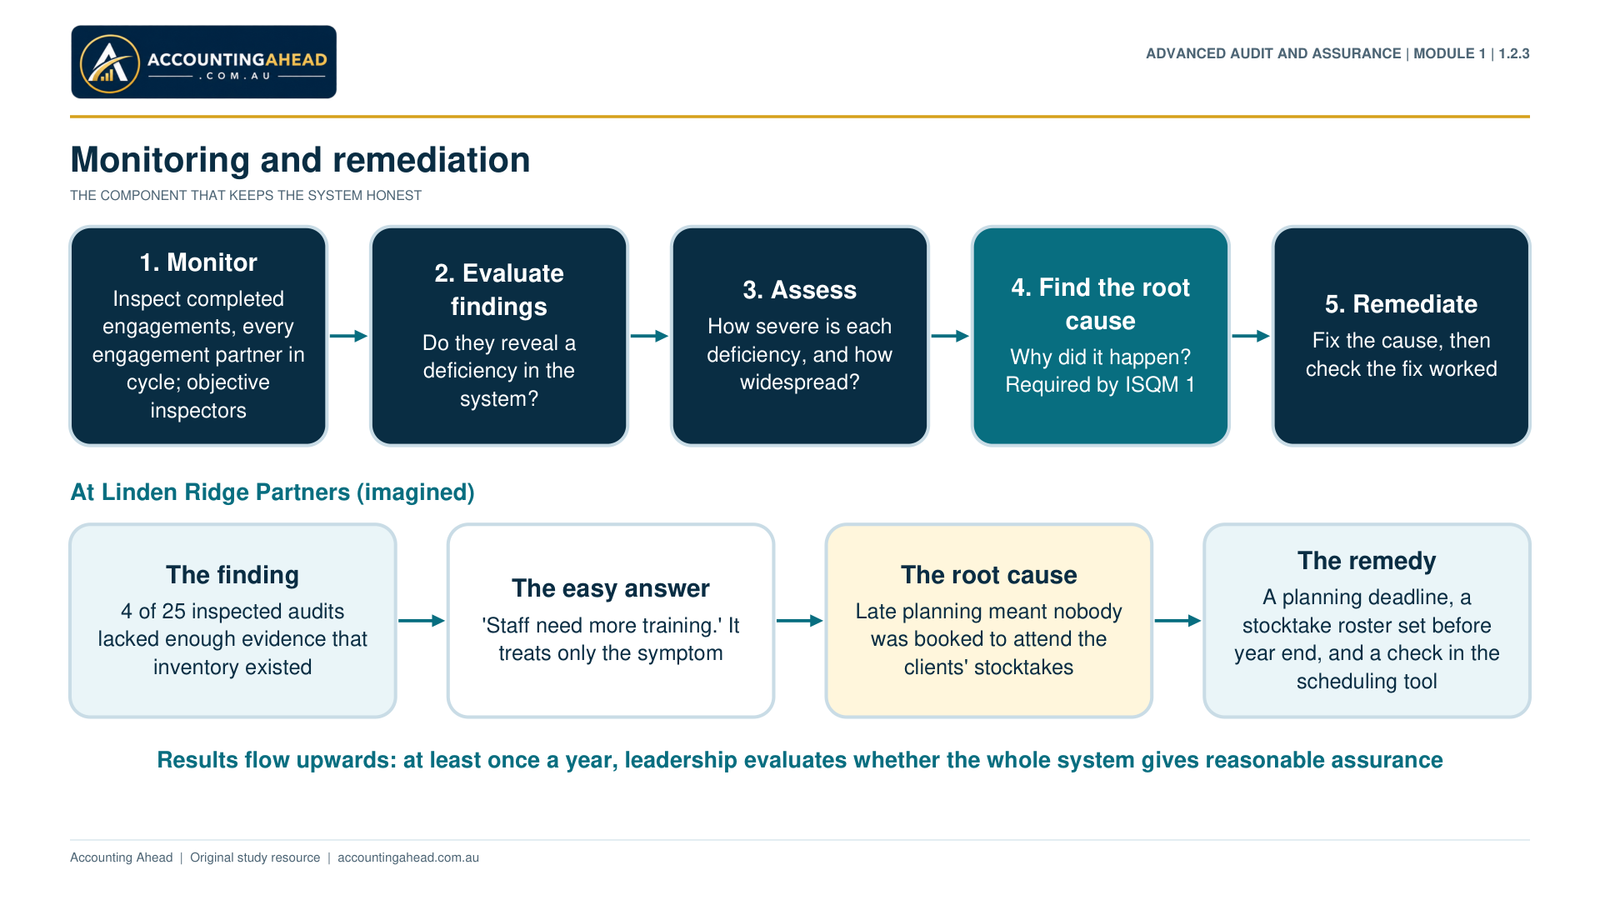
Part 1.2.3 · ISQM 1 - Quality Management for Firms
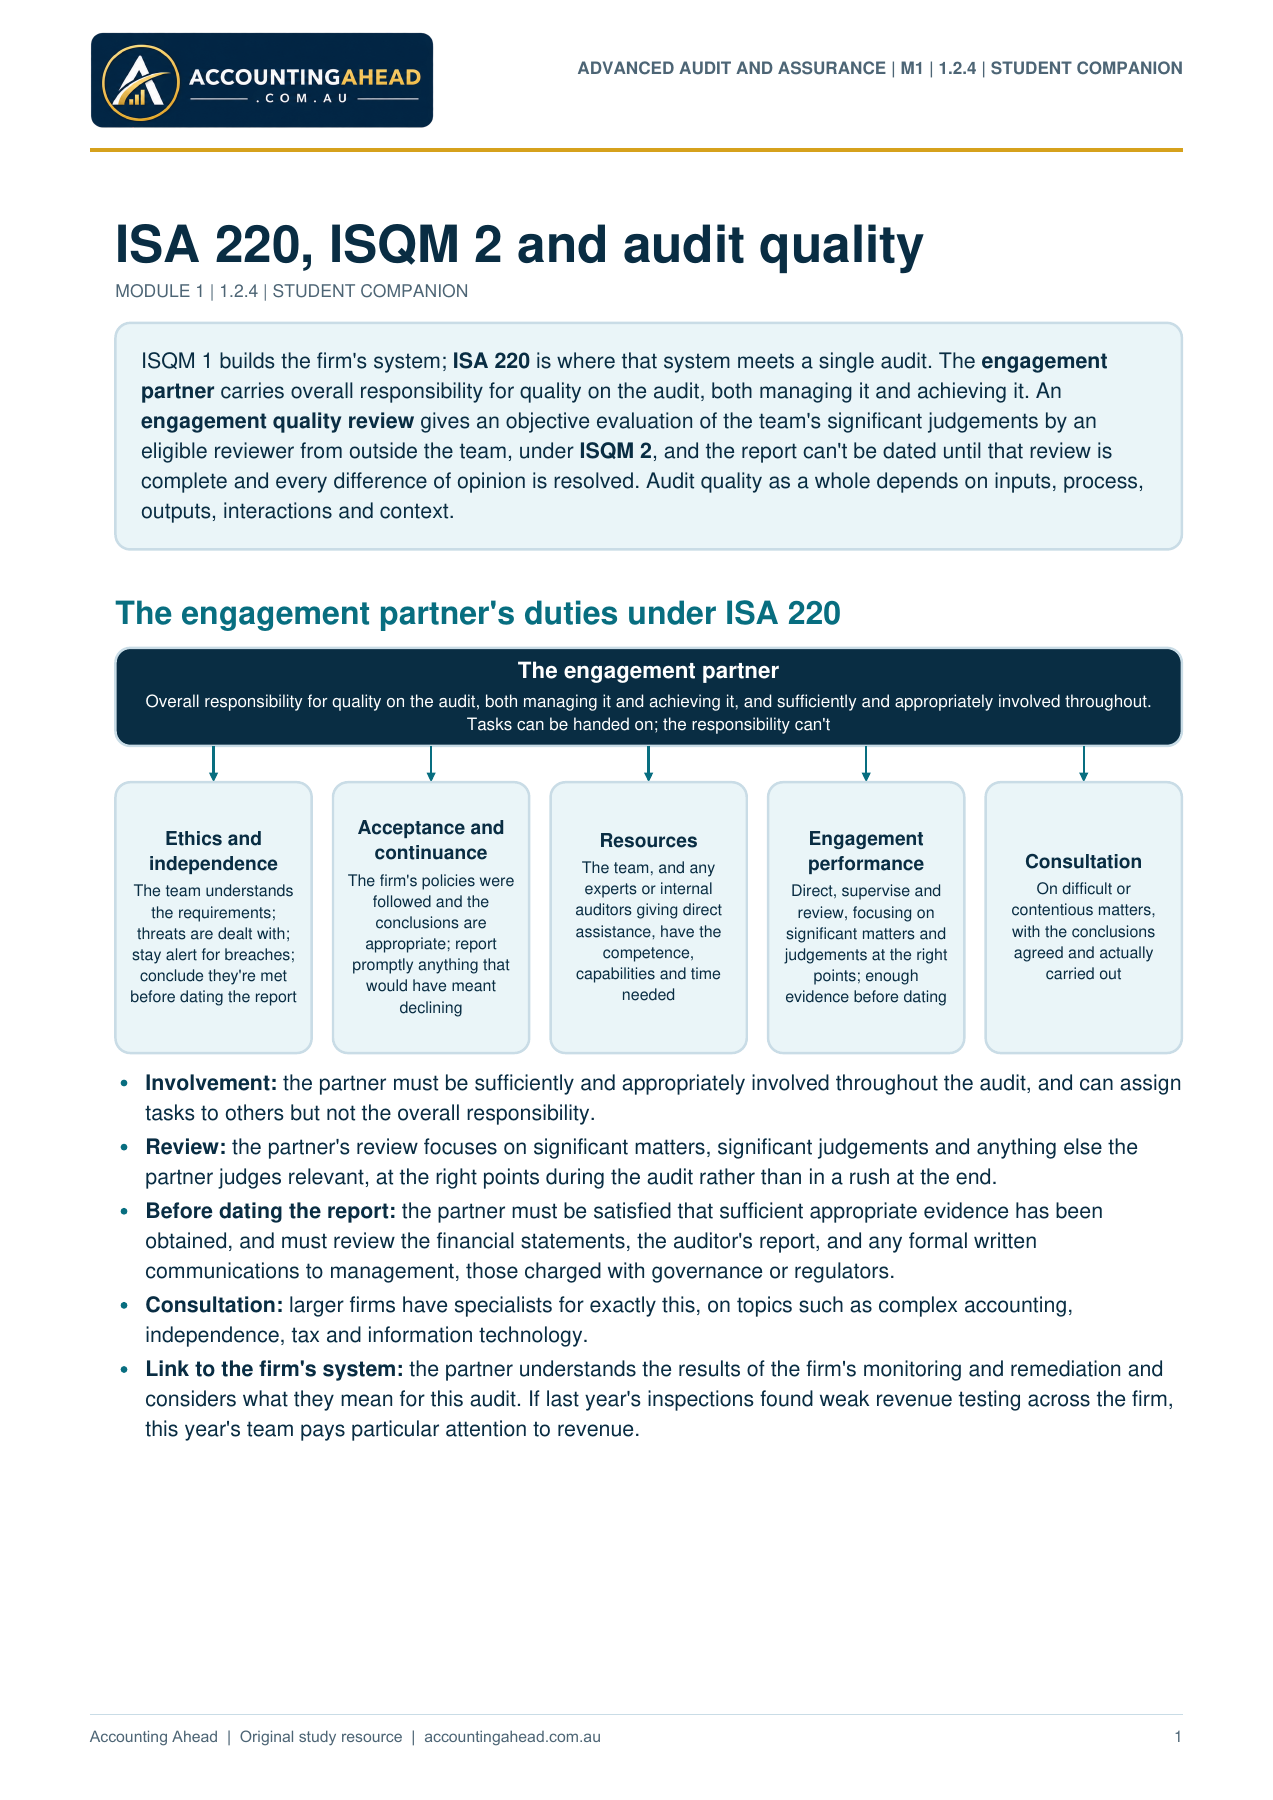
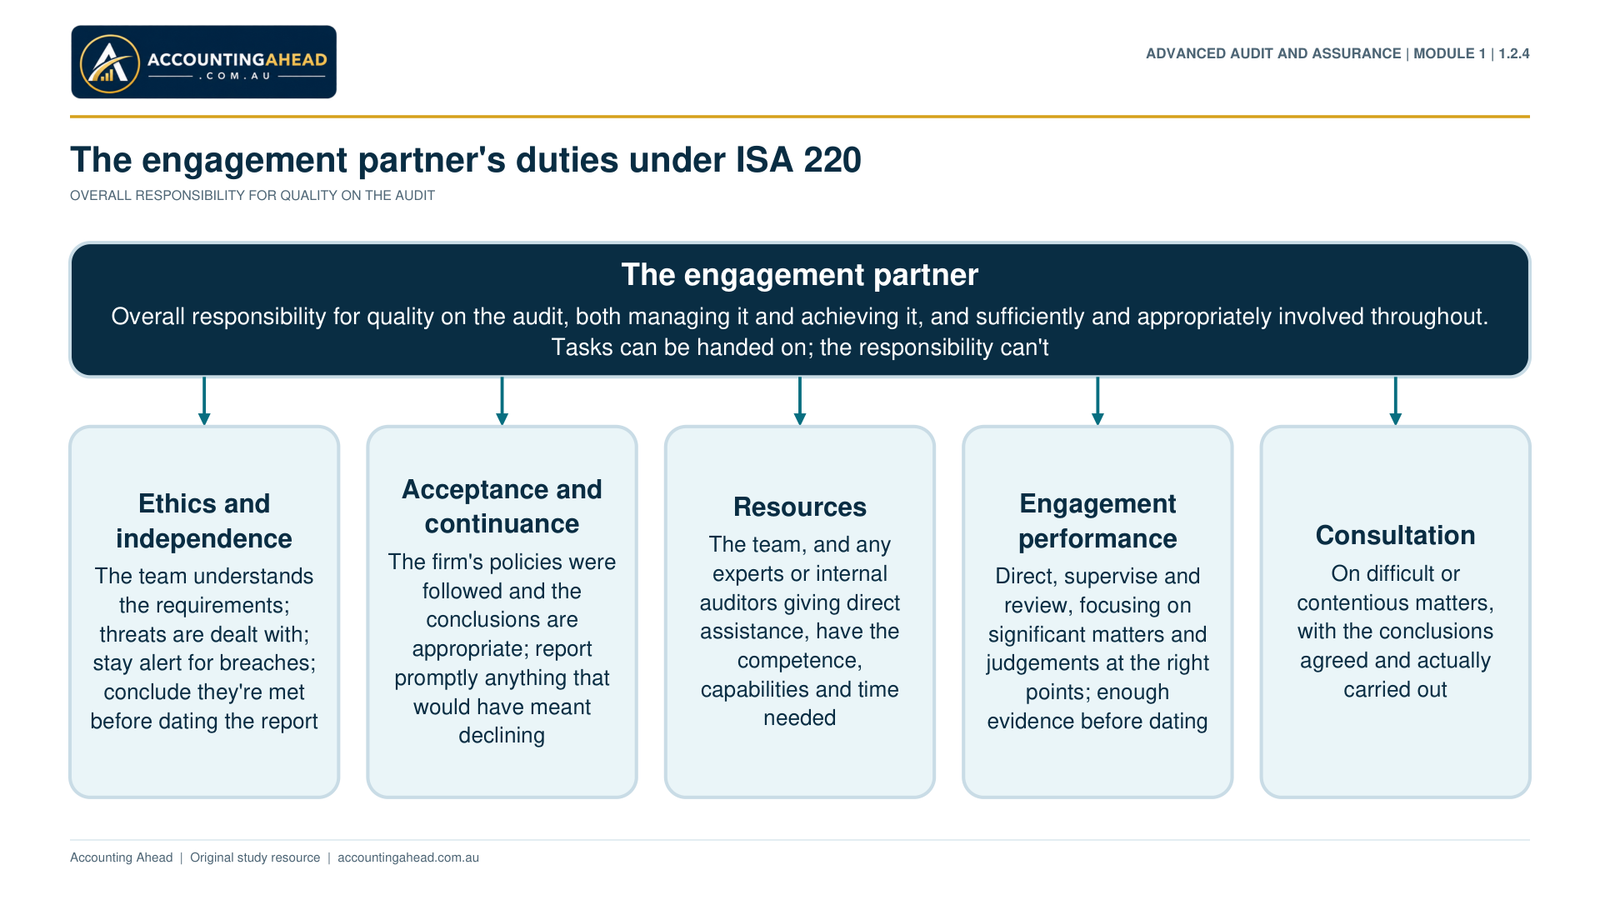
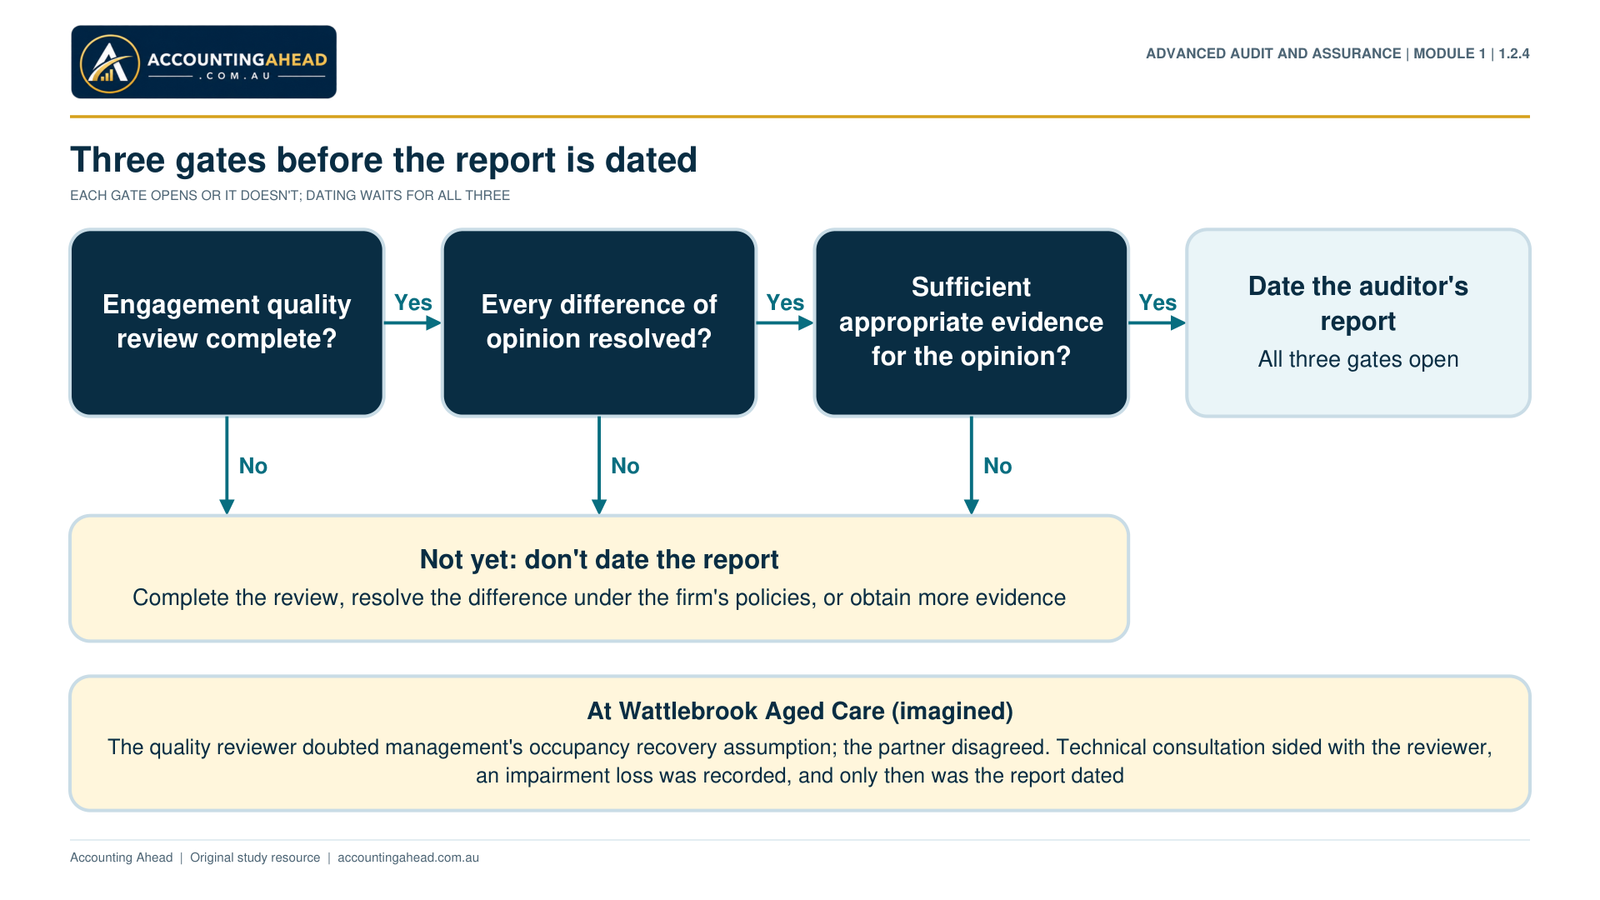
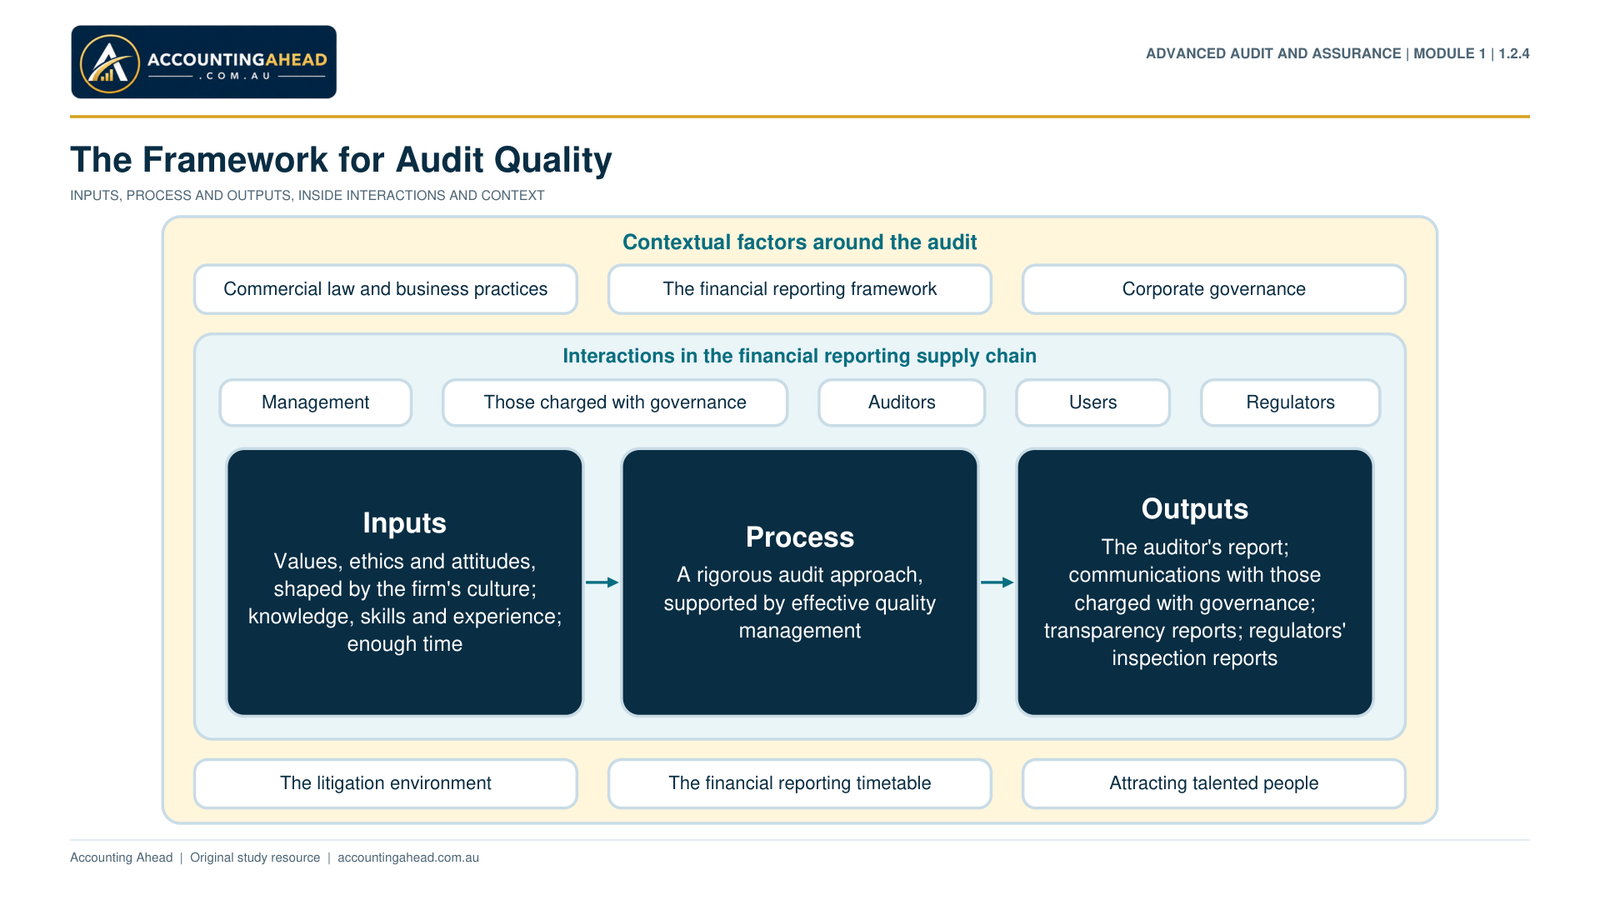
Part 1.2.4 · ISA 220, ISQM 2 and Audit Quality
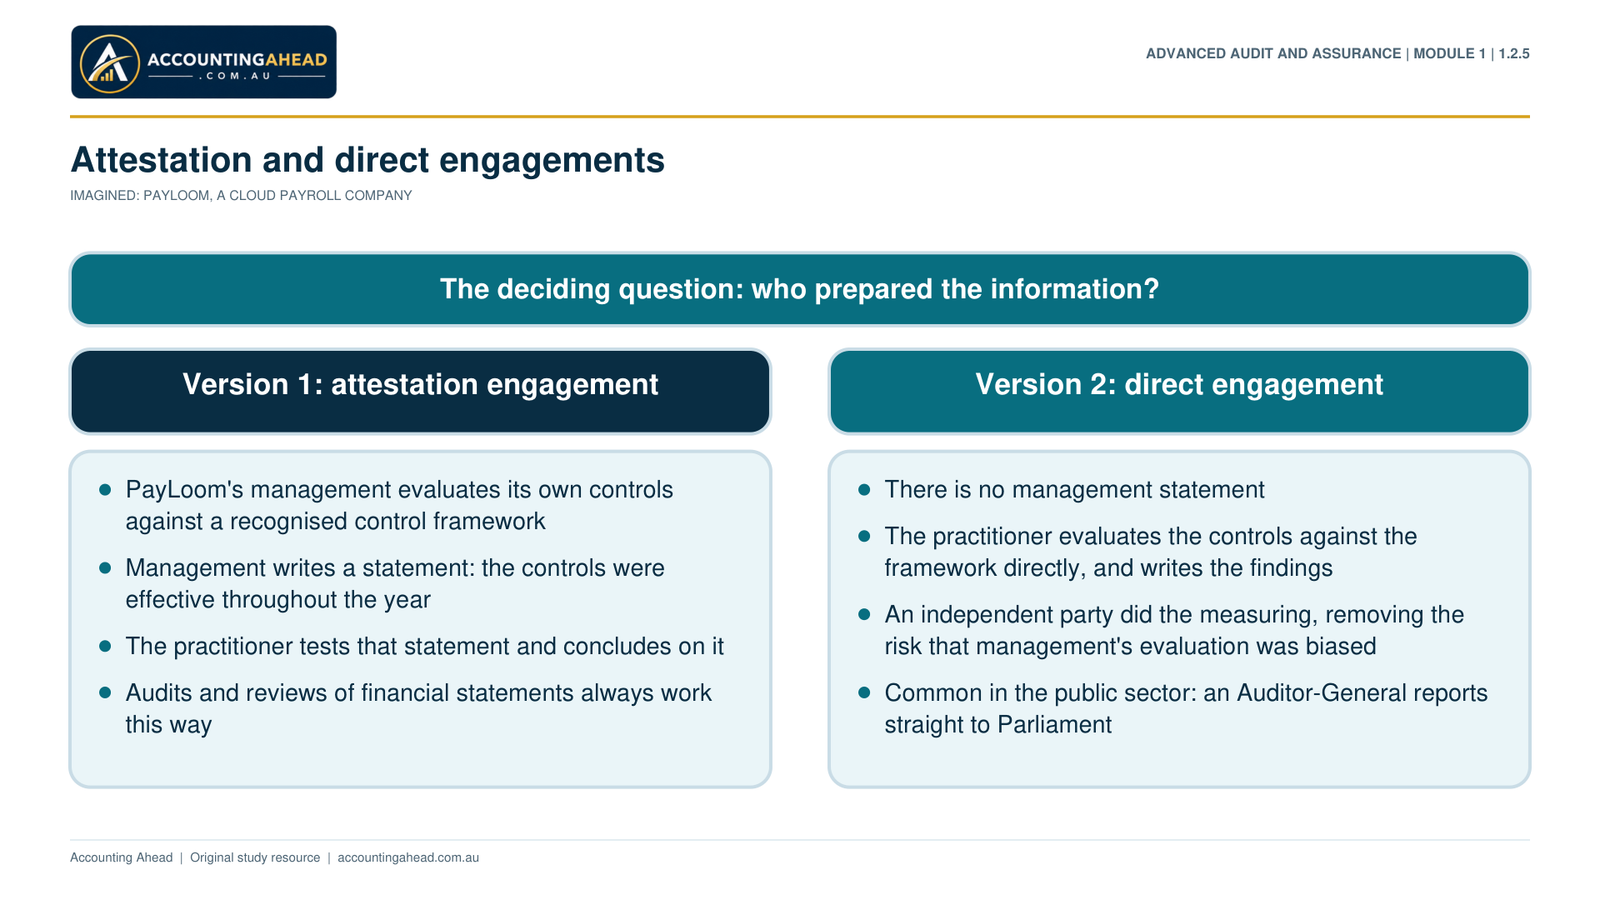
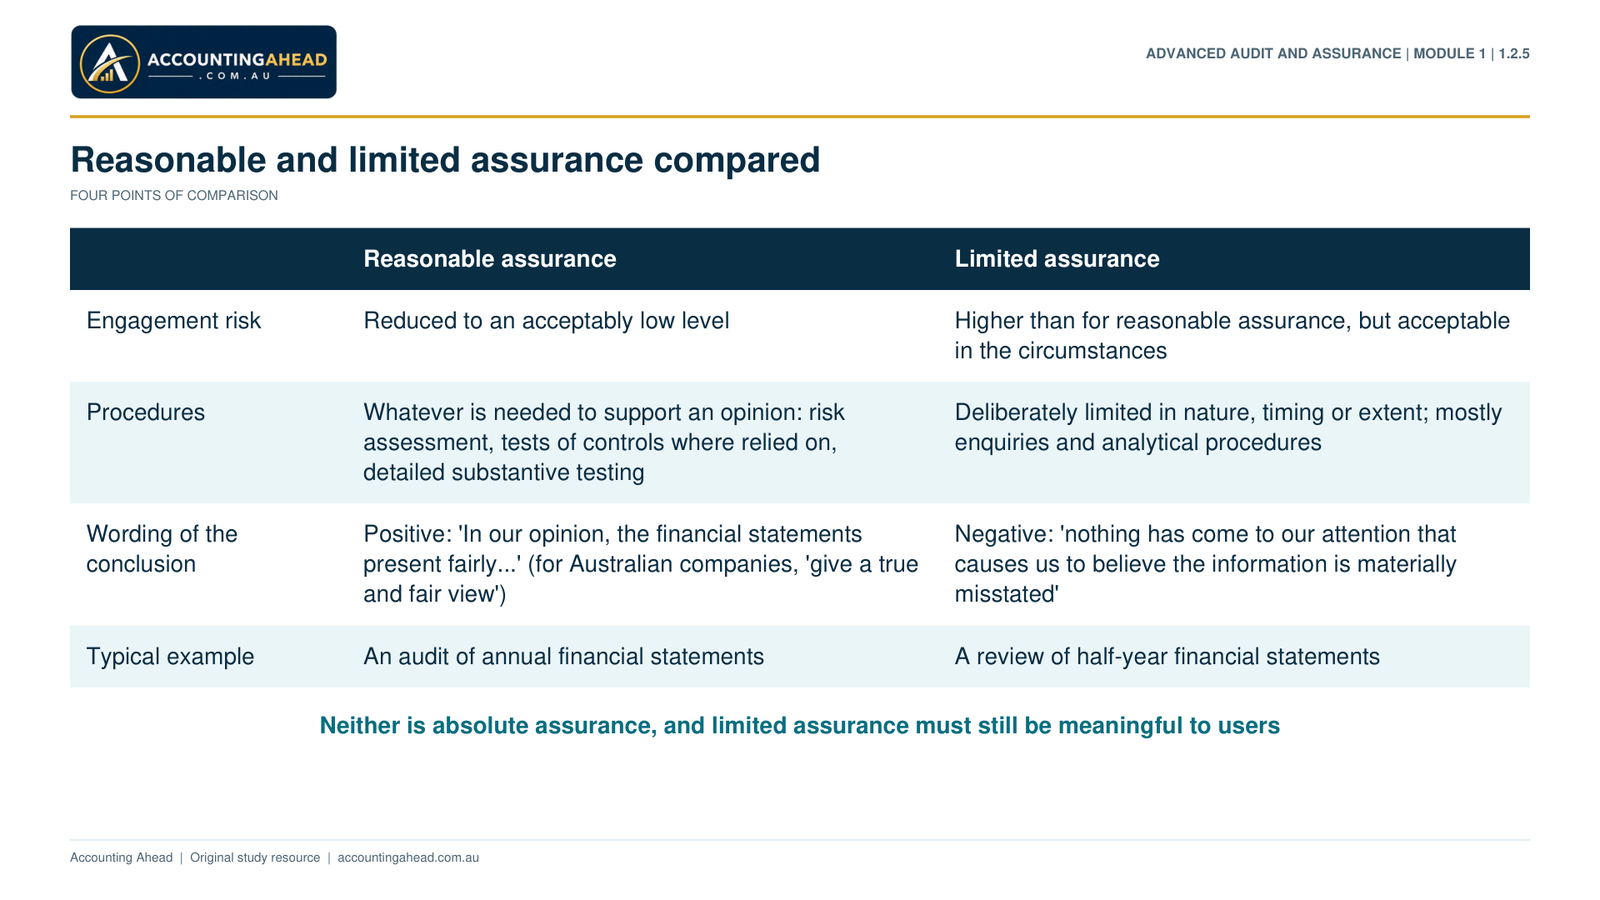
Part 1.2.5 · What Makes an Assurance Engagement
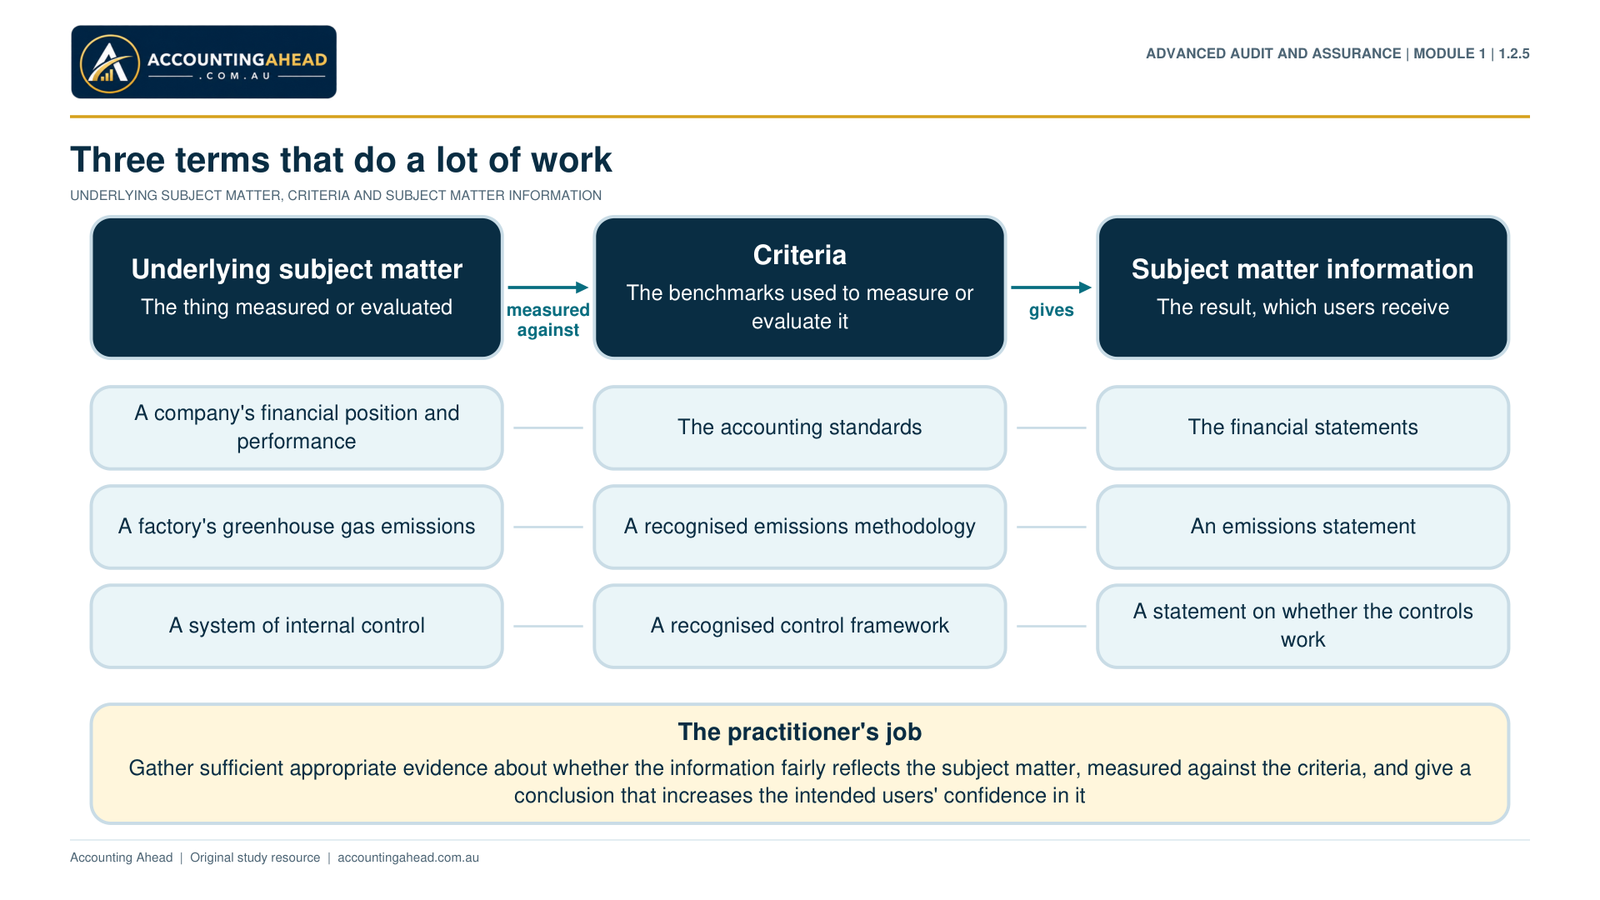
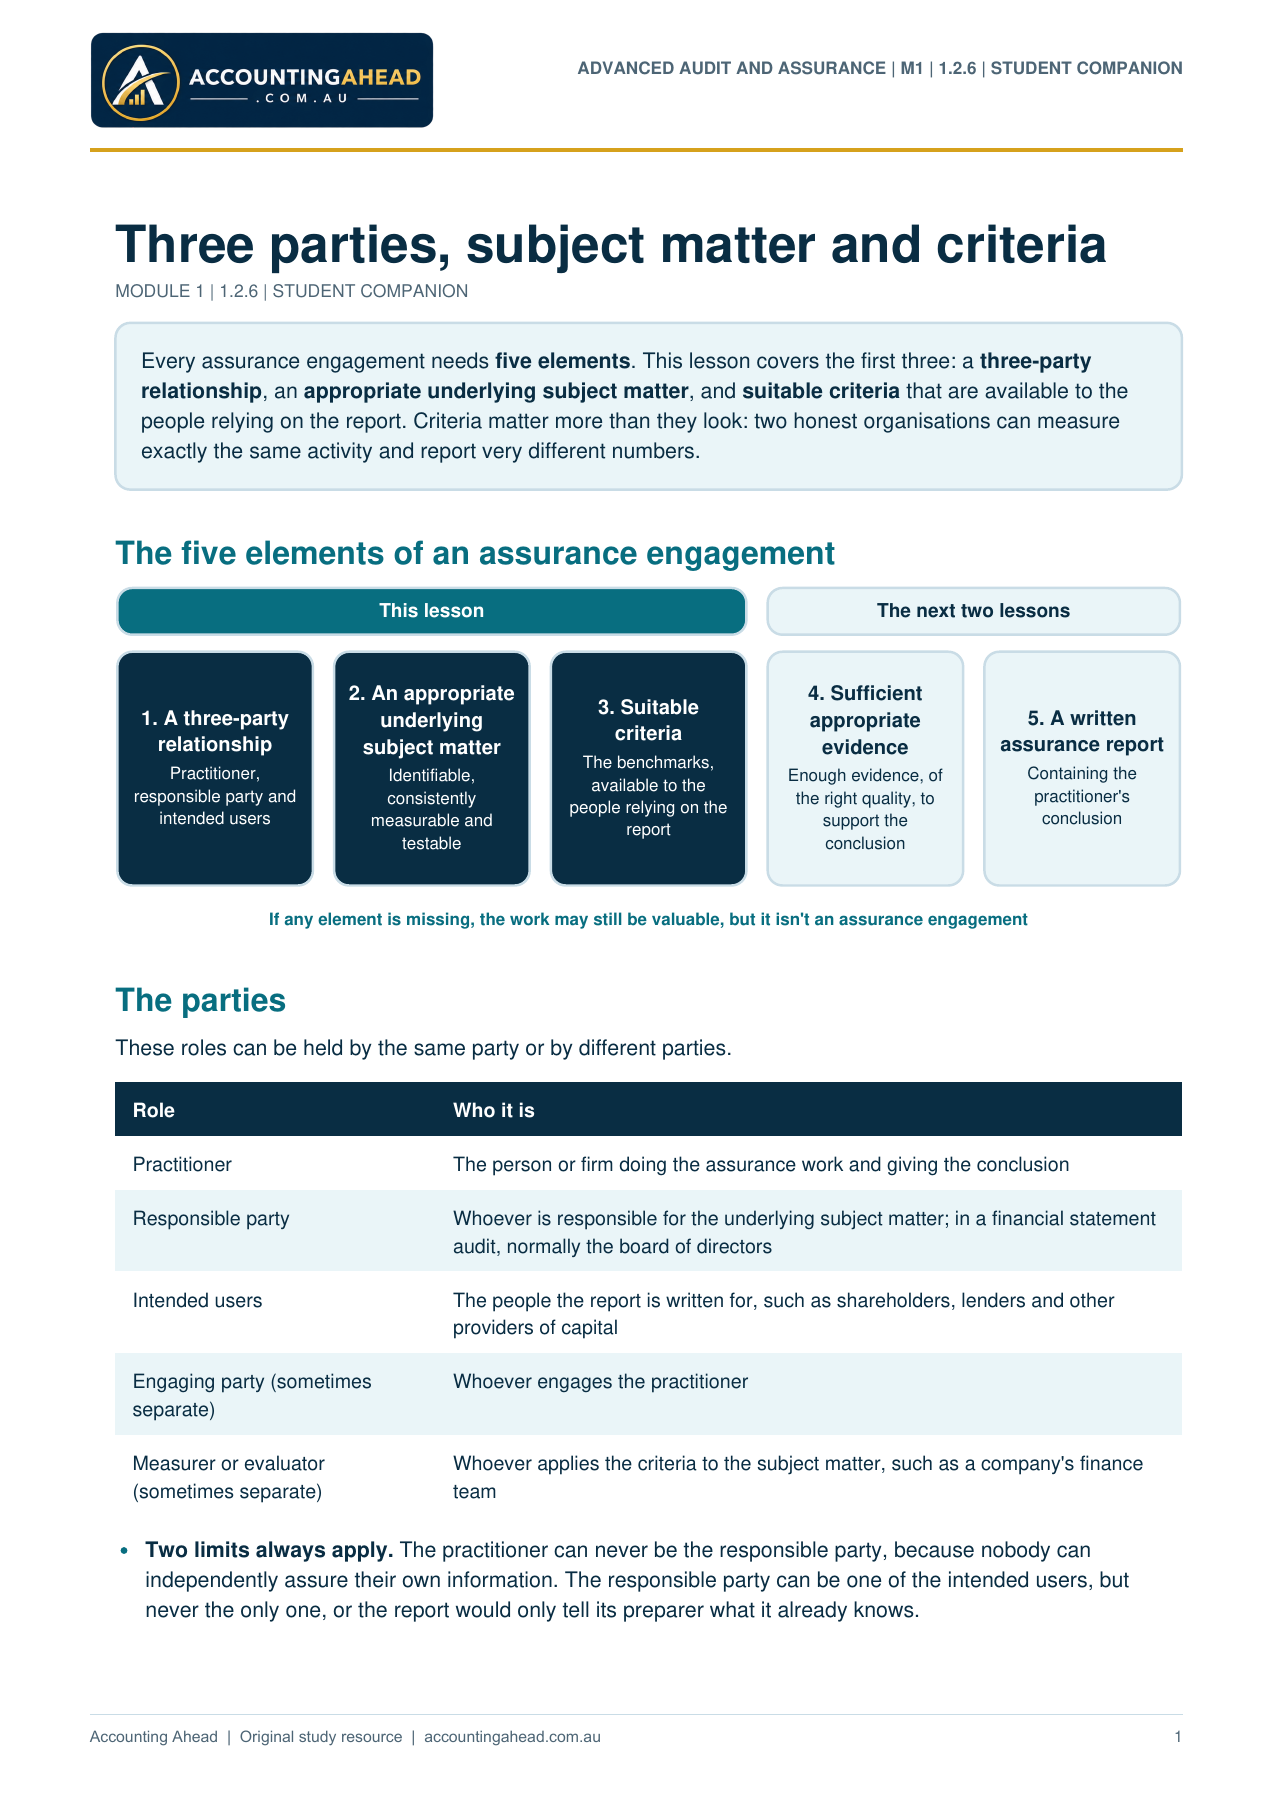
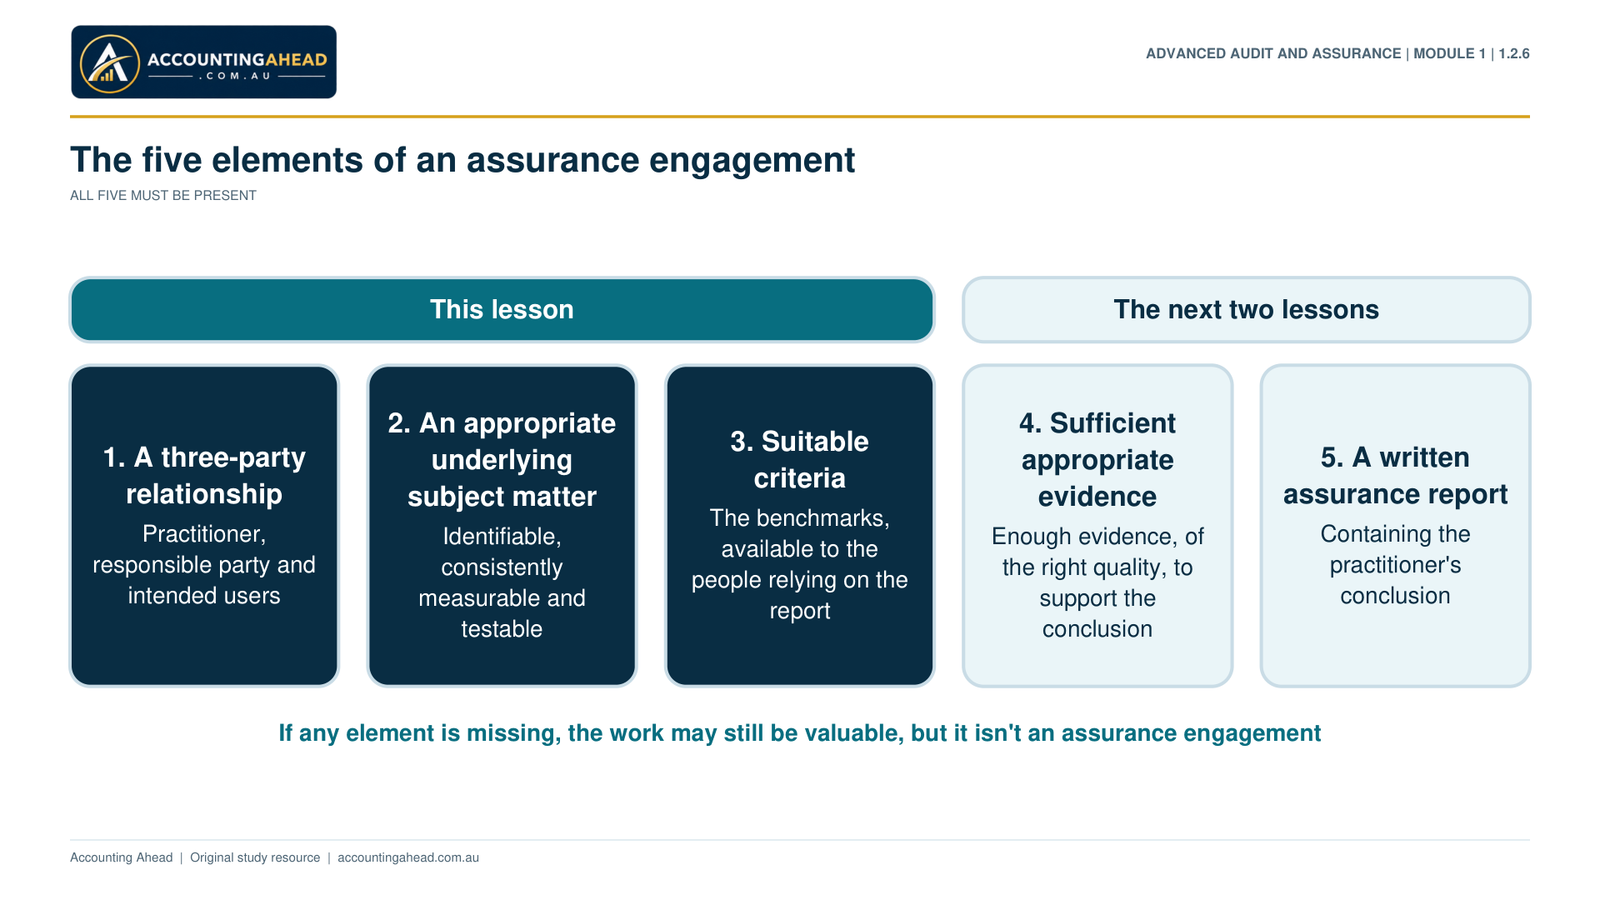
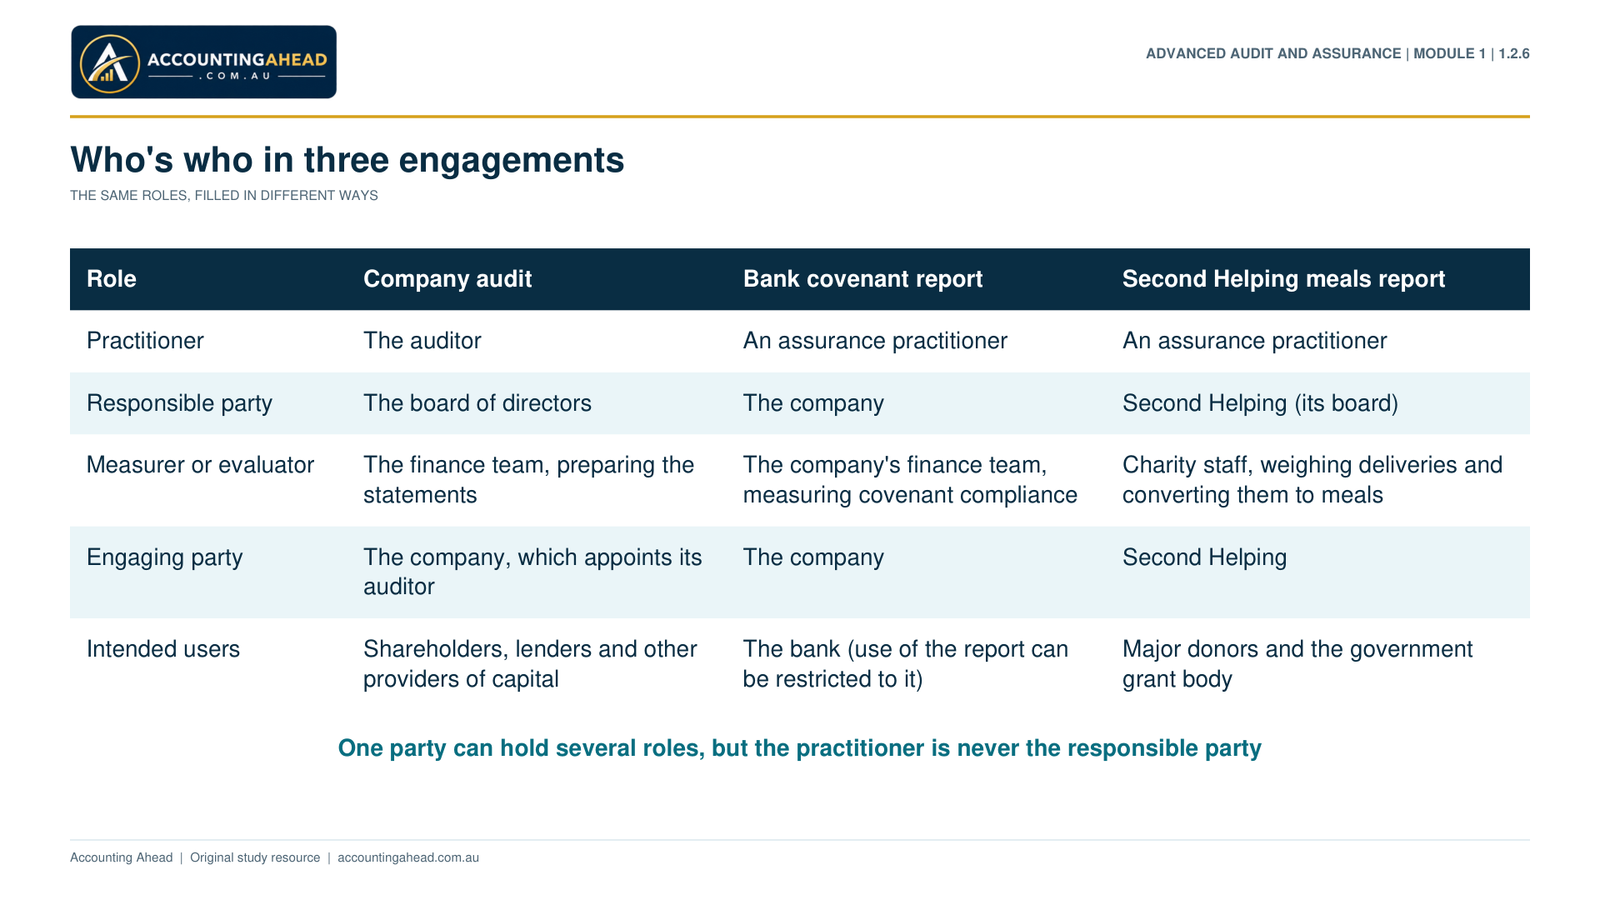
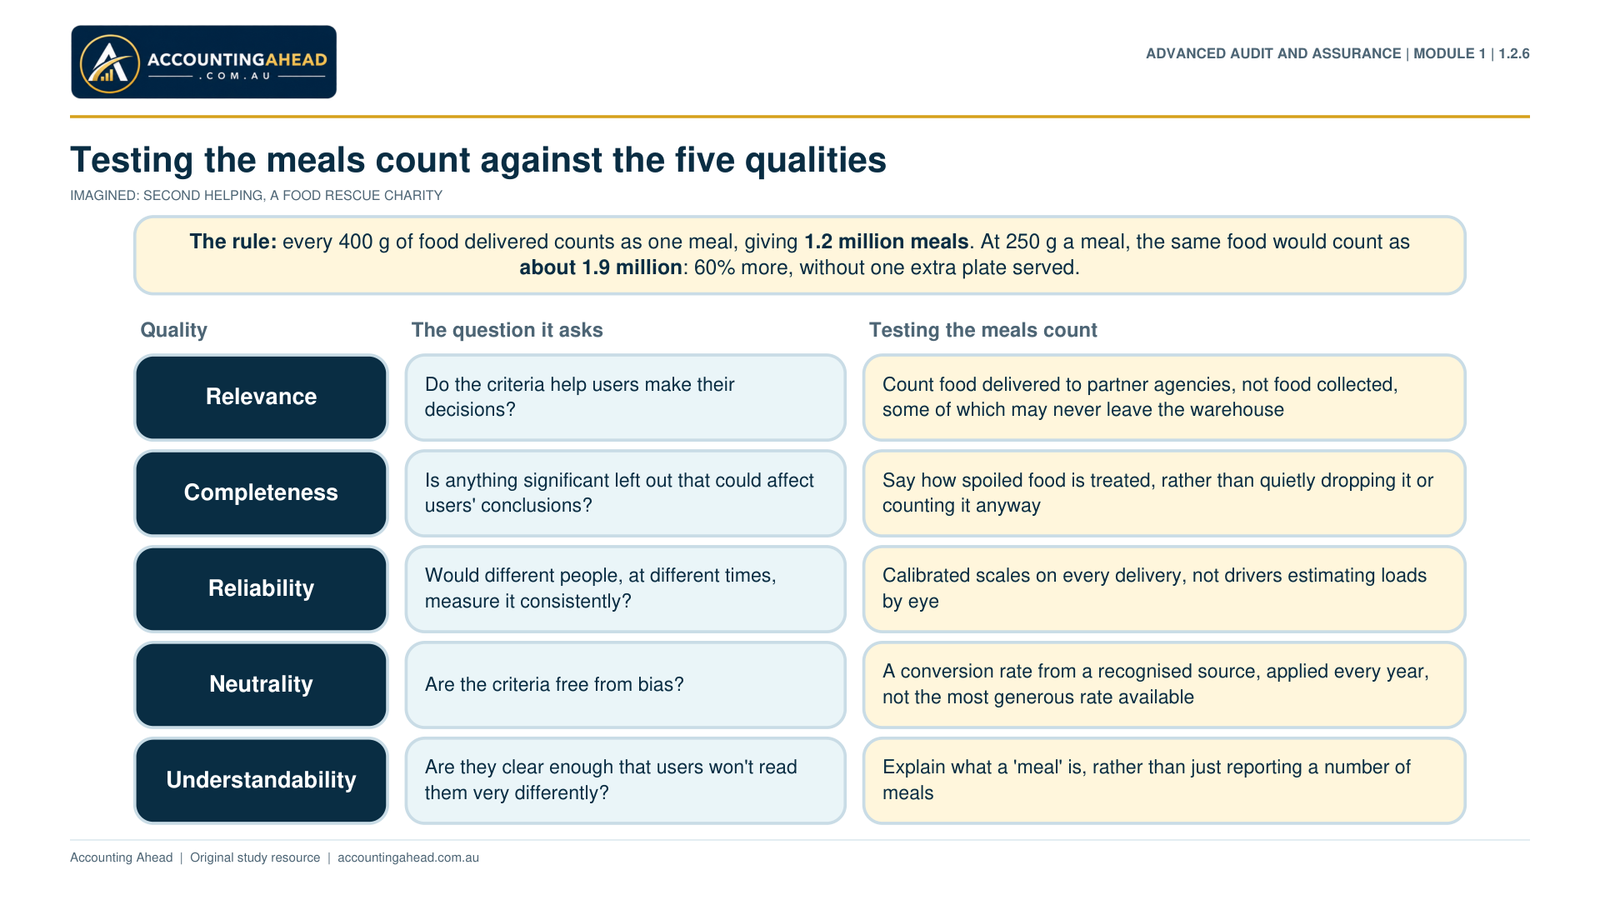
Part 1.2.6 · Three Parties, Subject Matter and Criteria
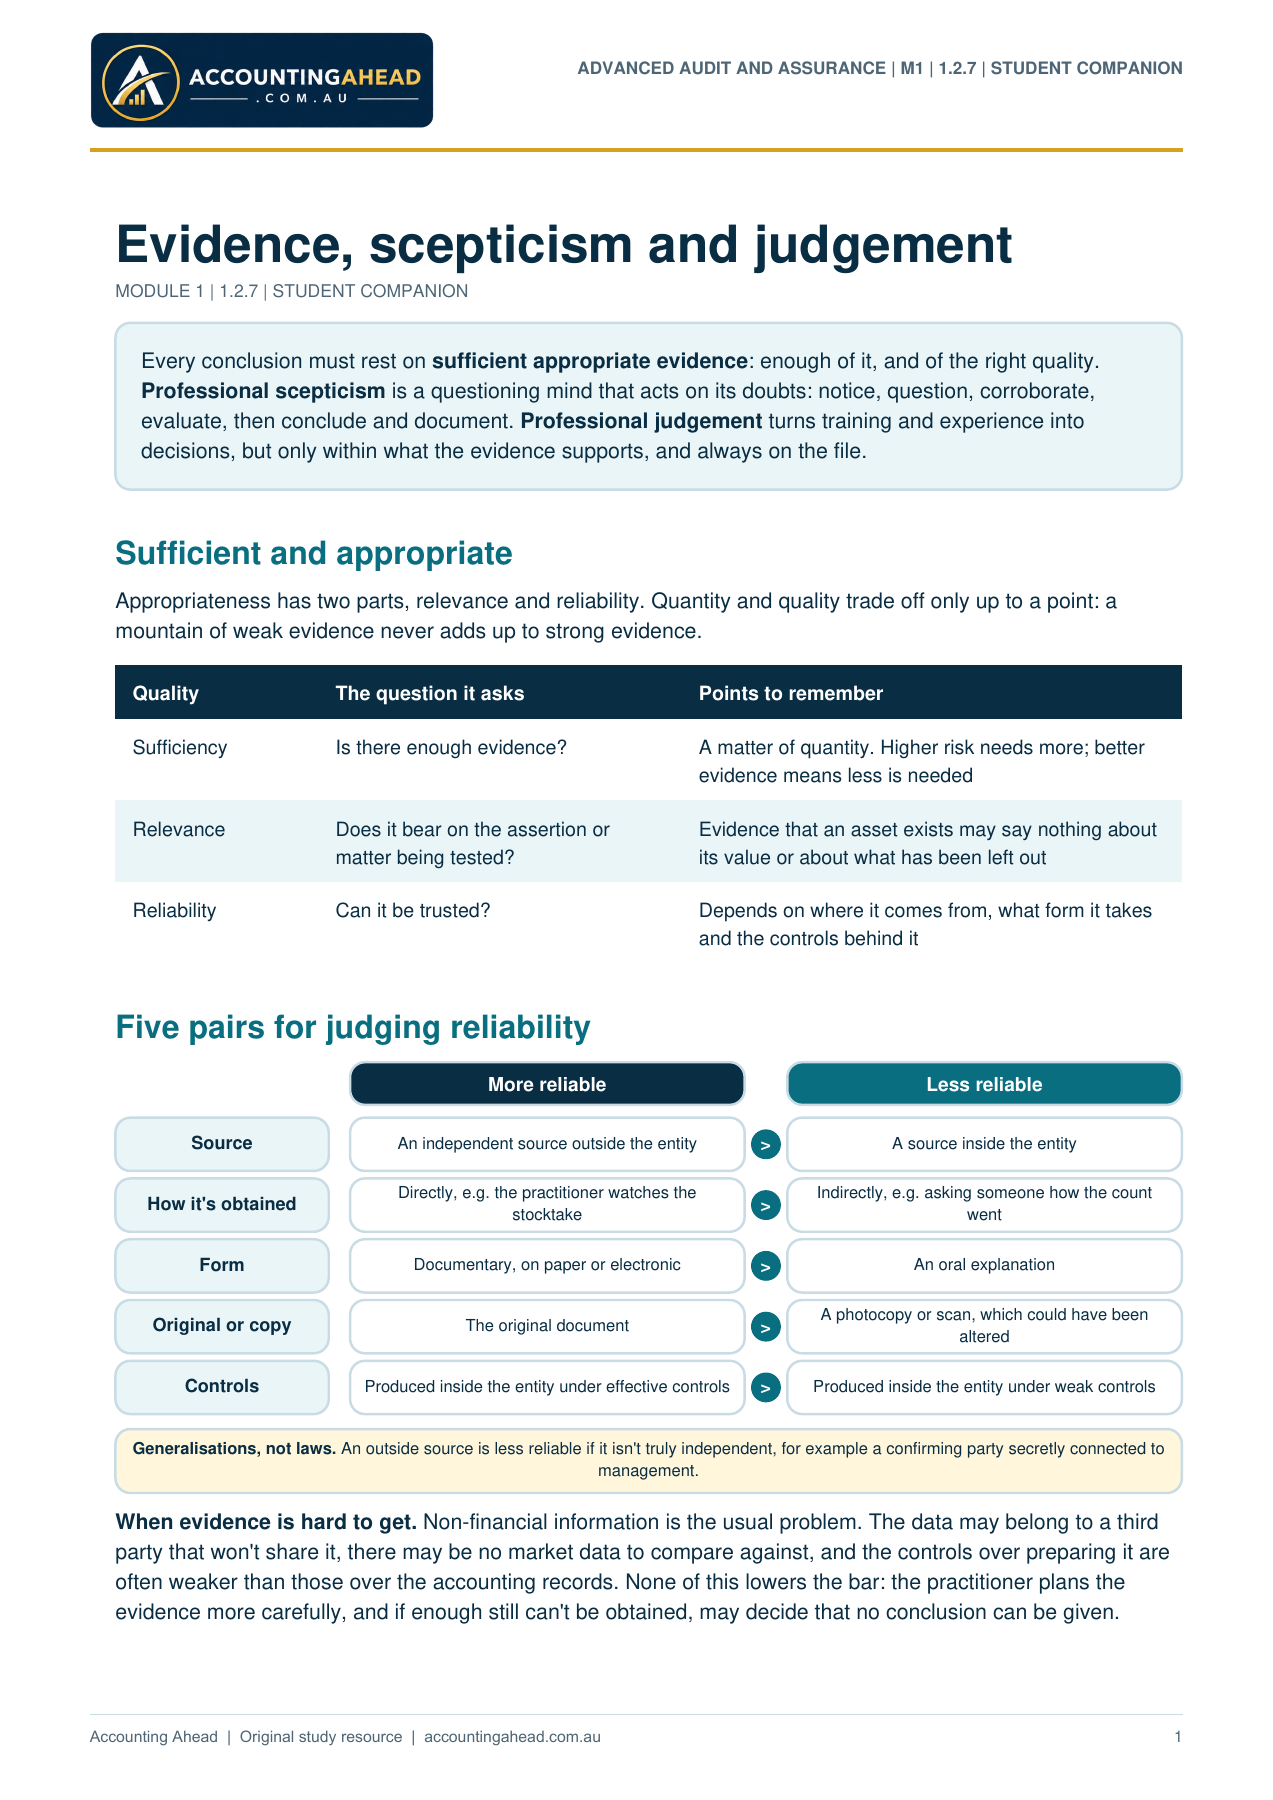
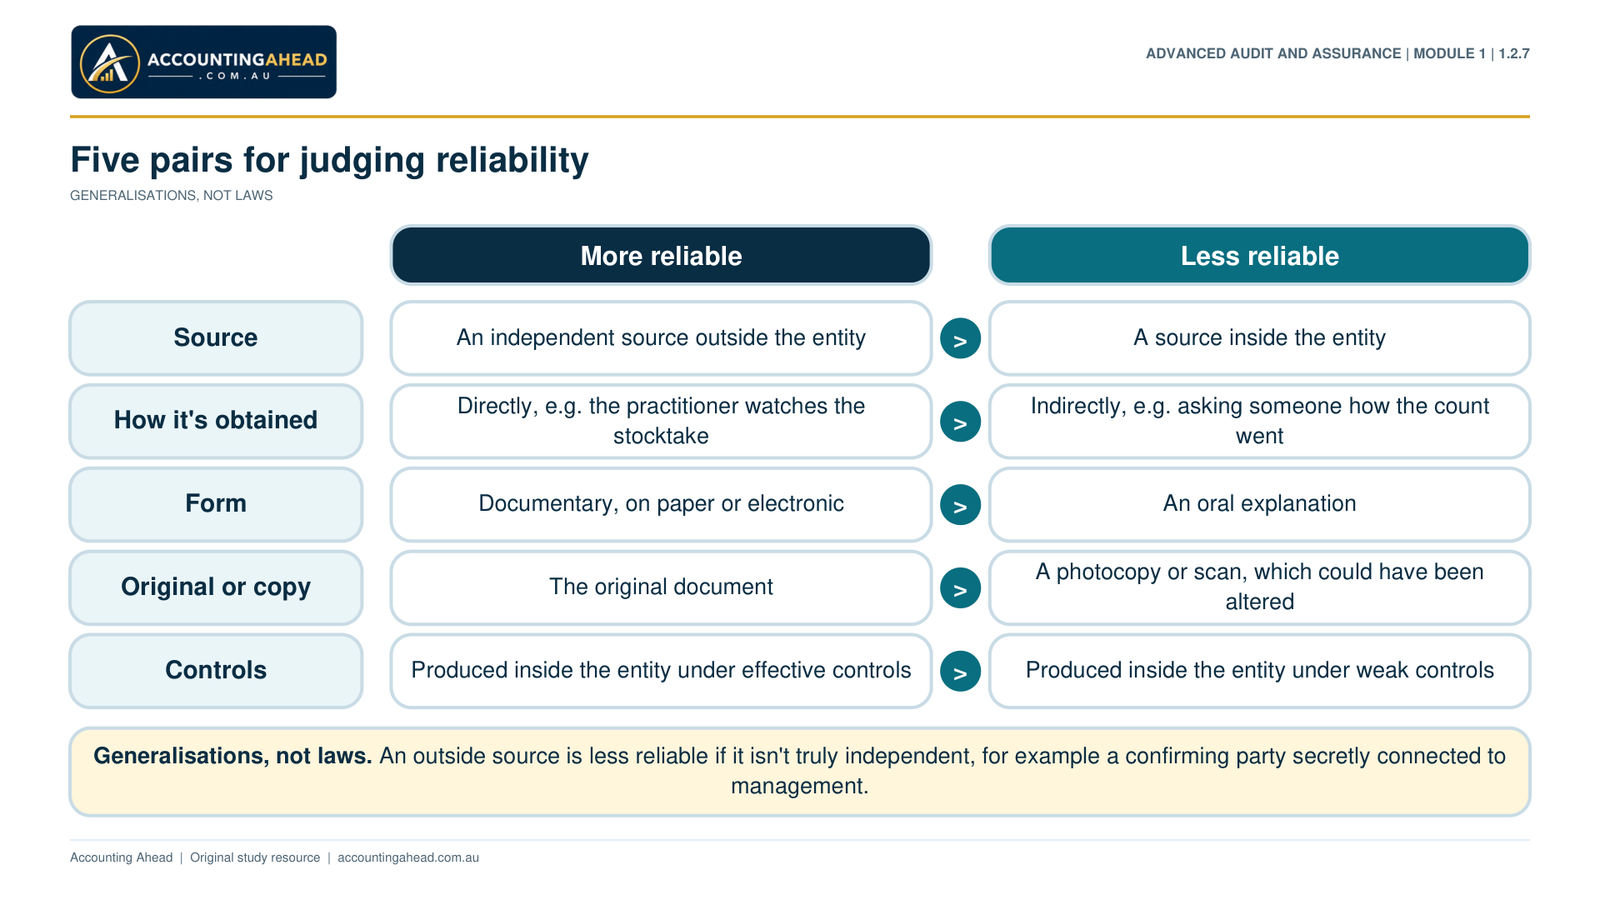
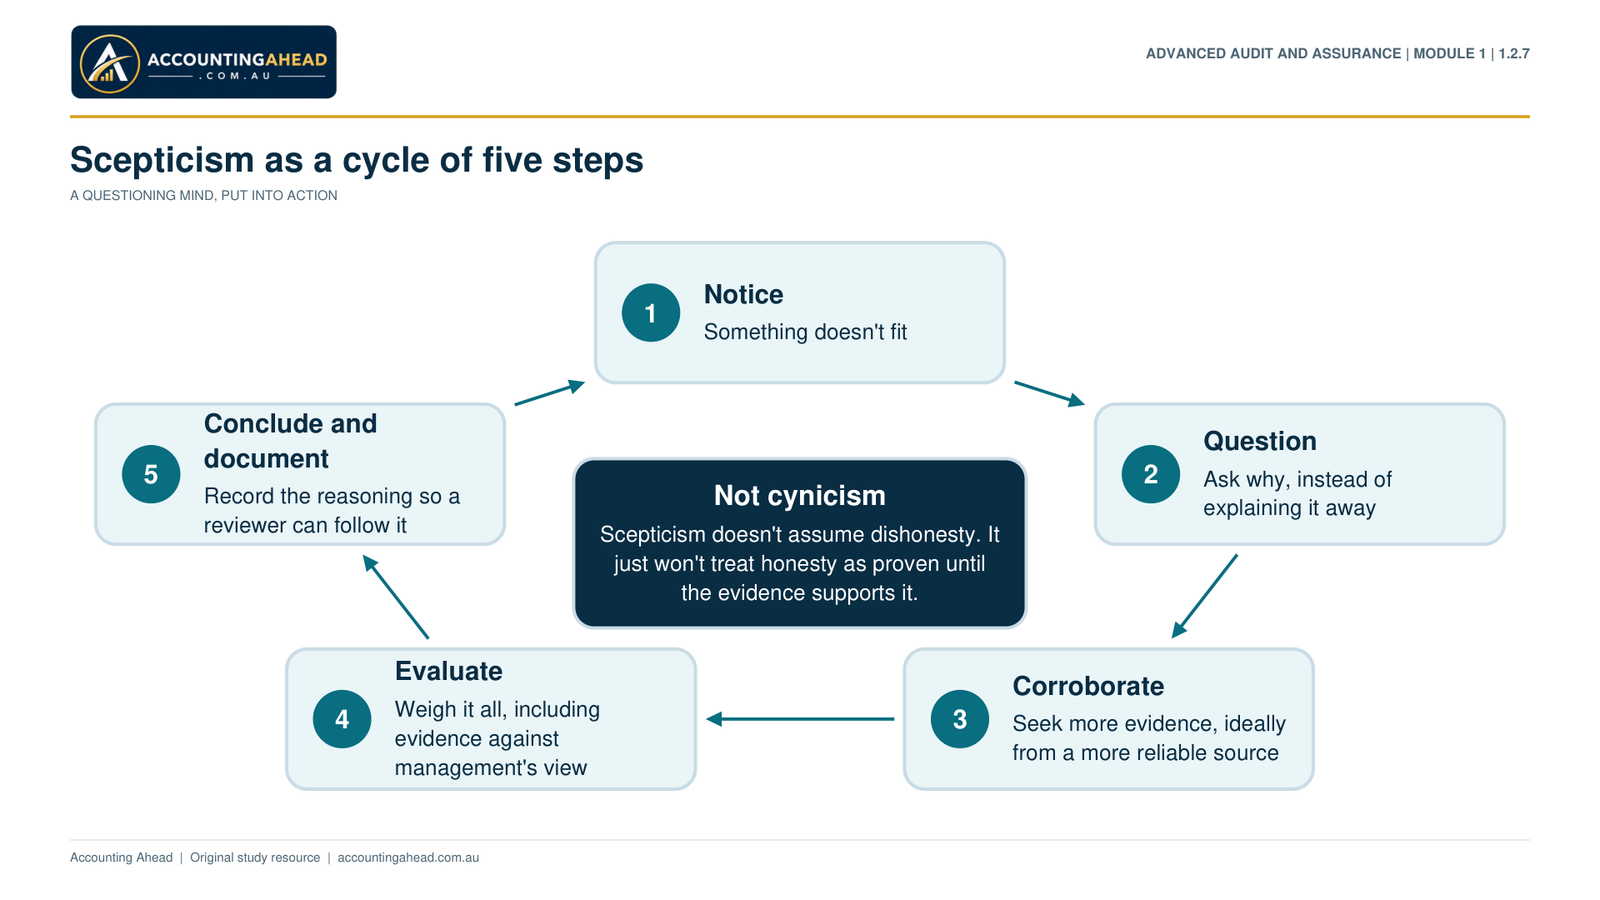
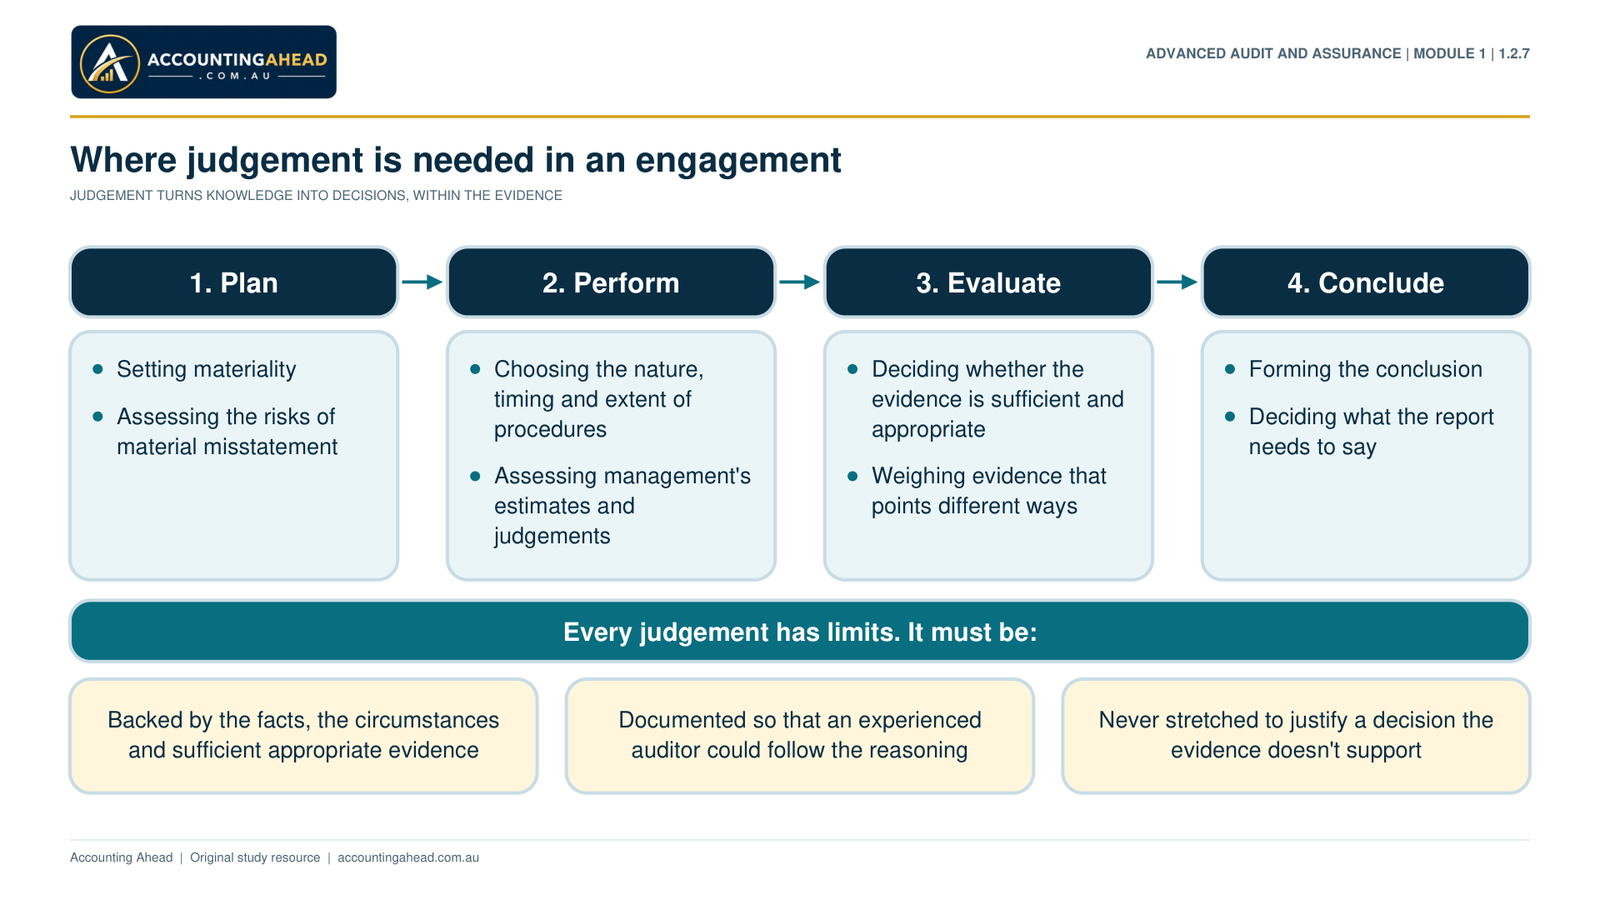
Part 1.2.7 · Evidence, Scepticism and Judgement
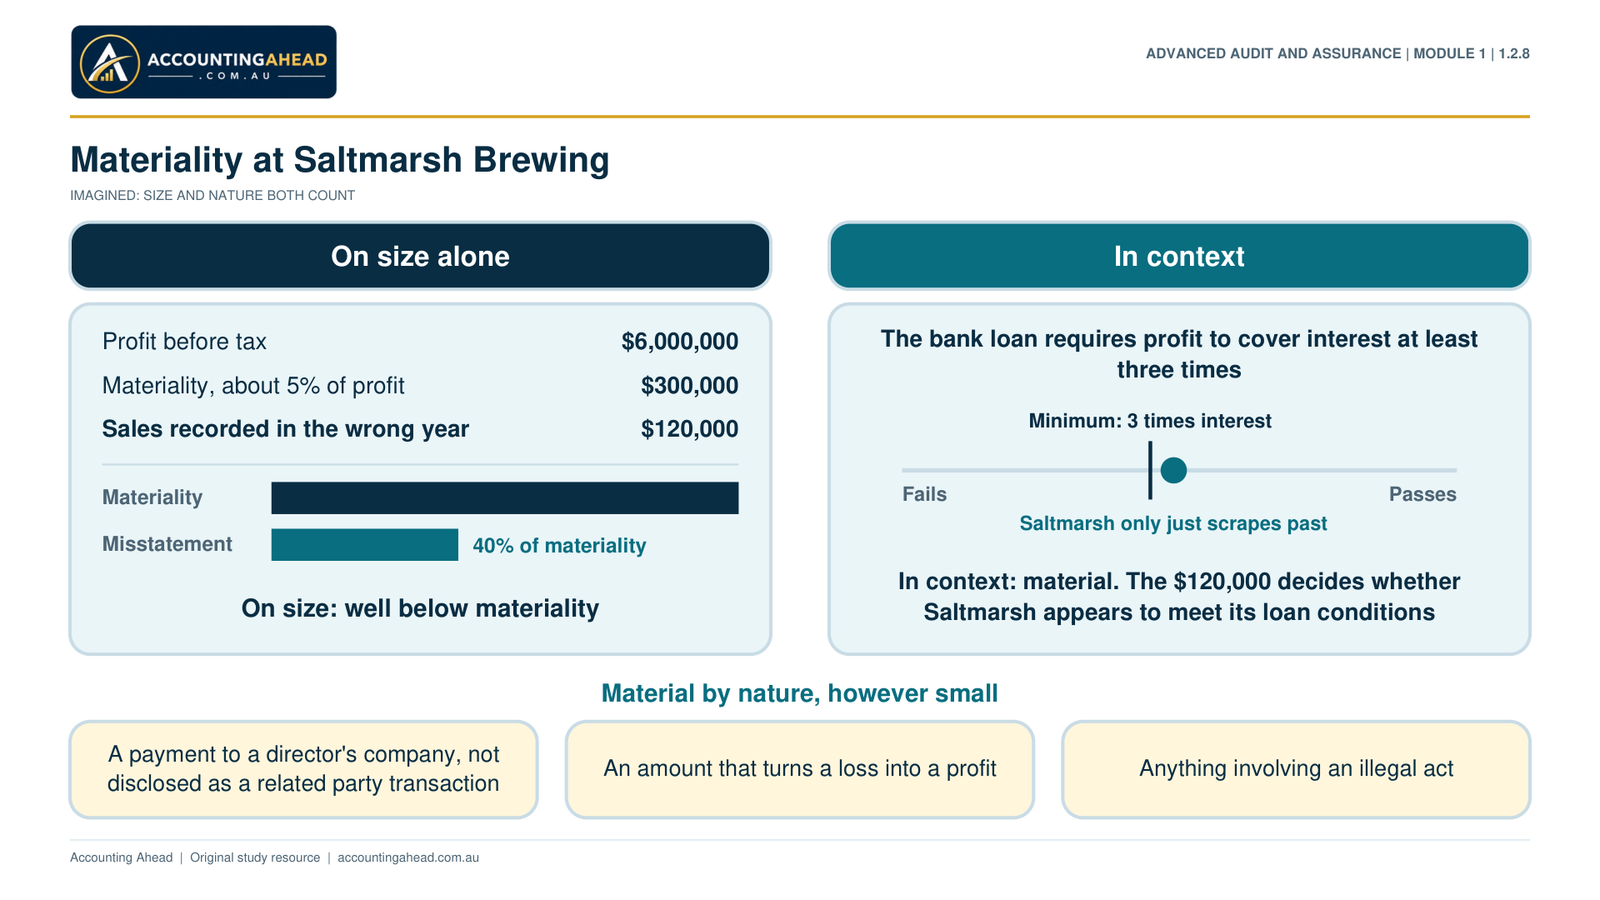
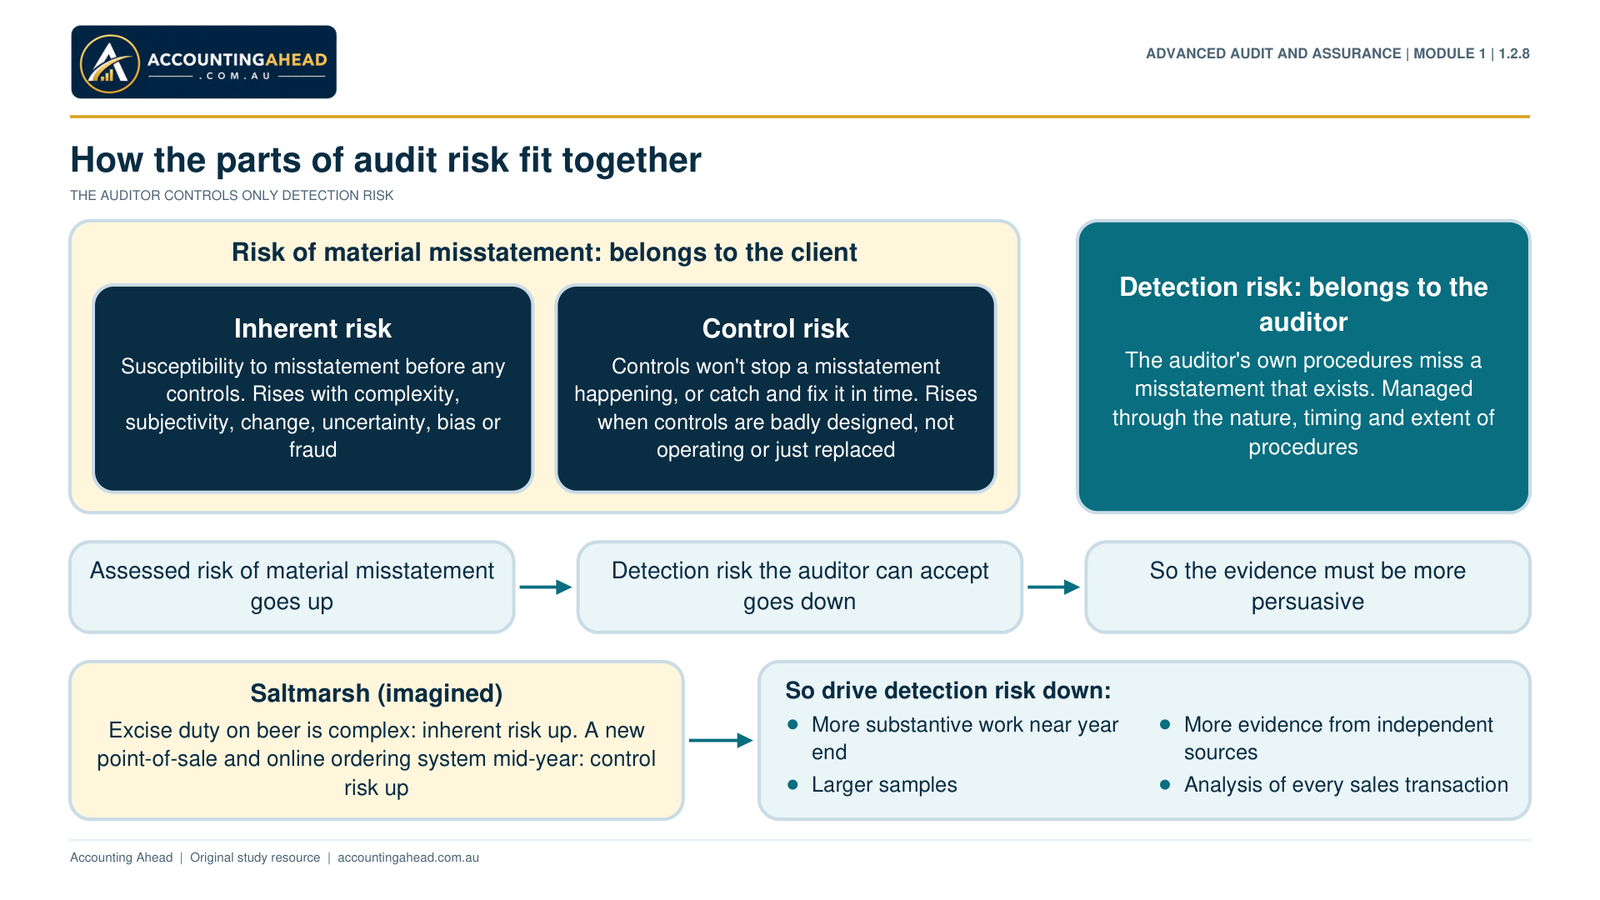
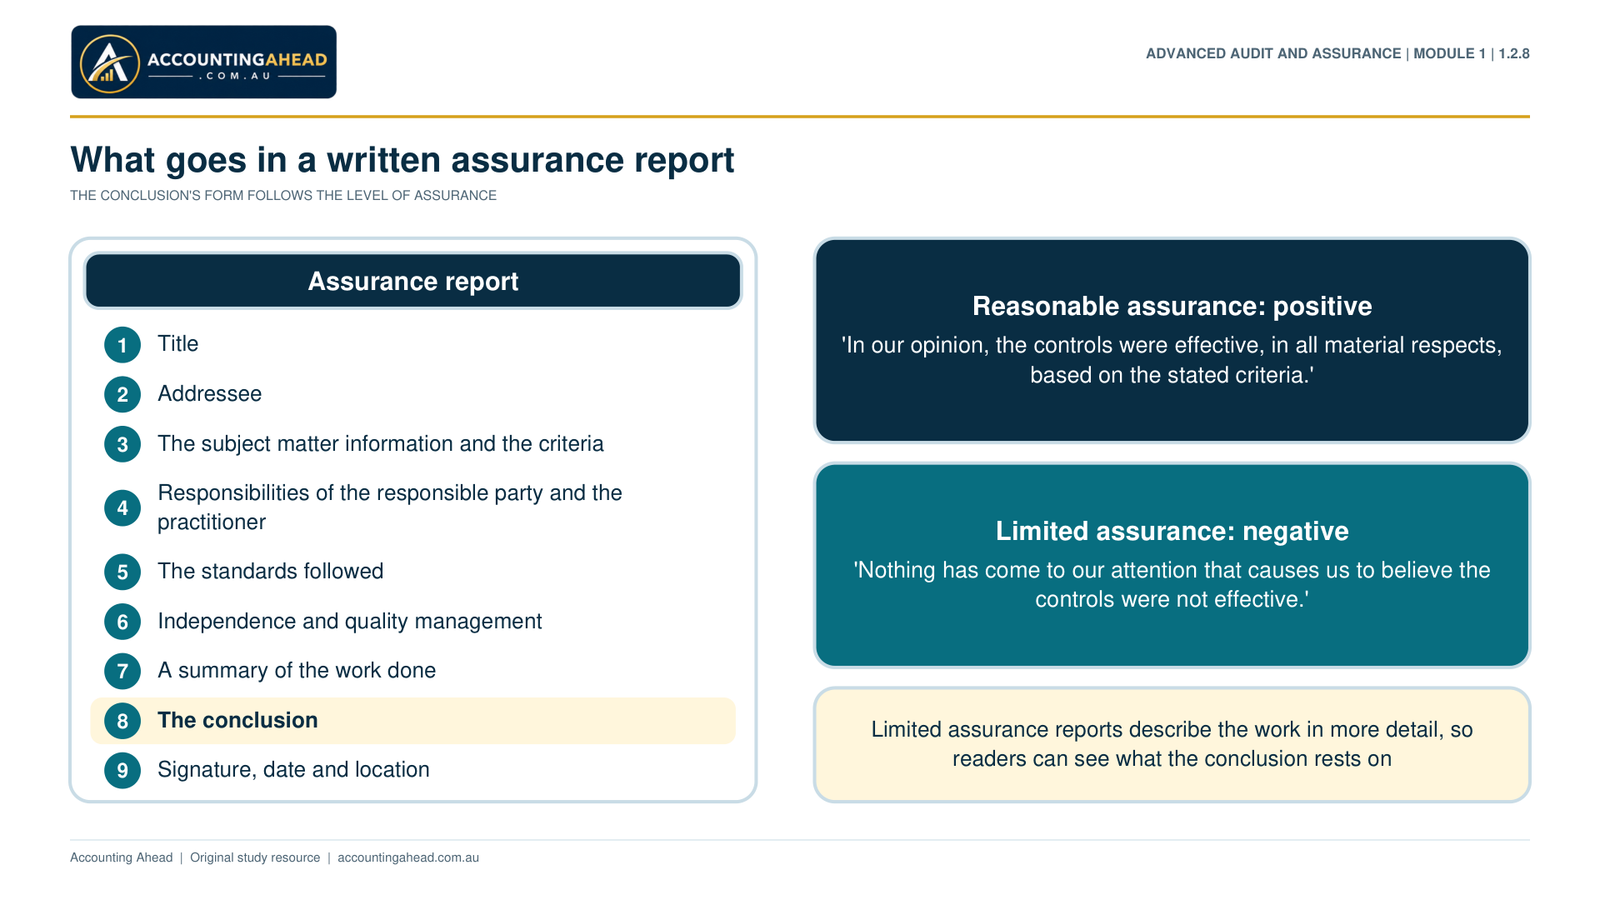
Part 1.2.8 · Materiality, Engagement Risk and Reporting
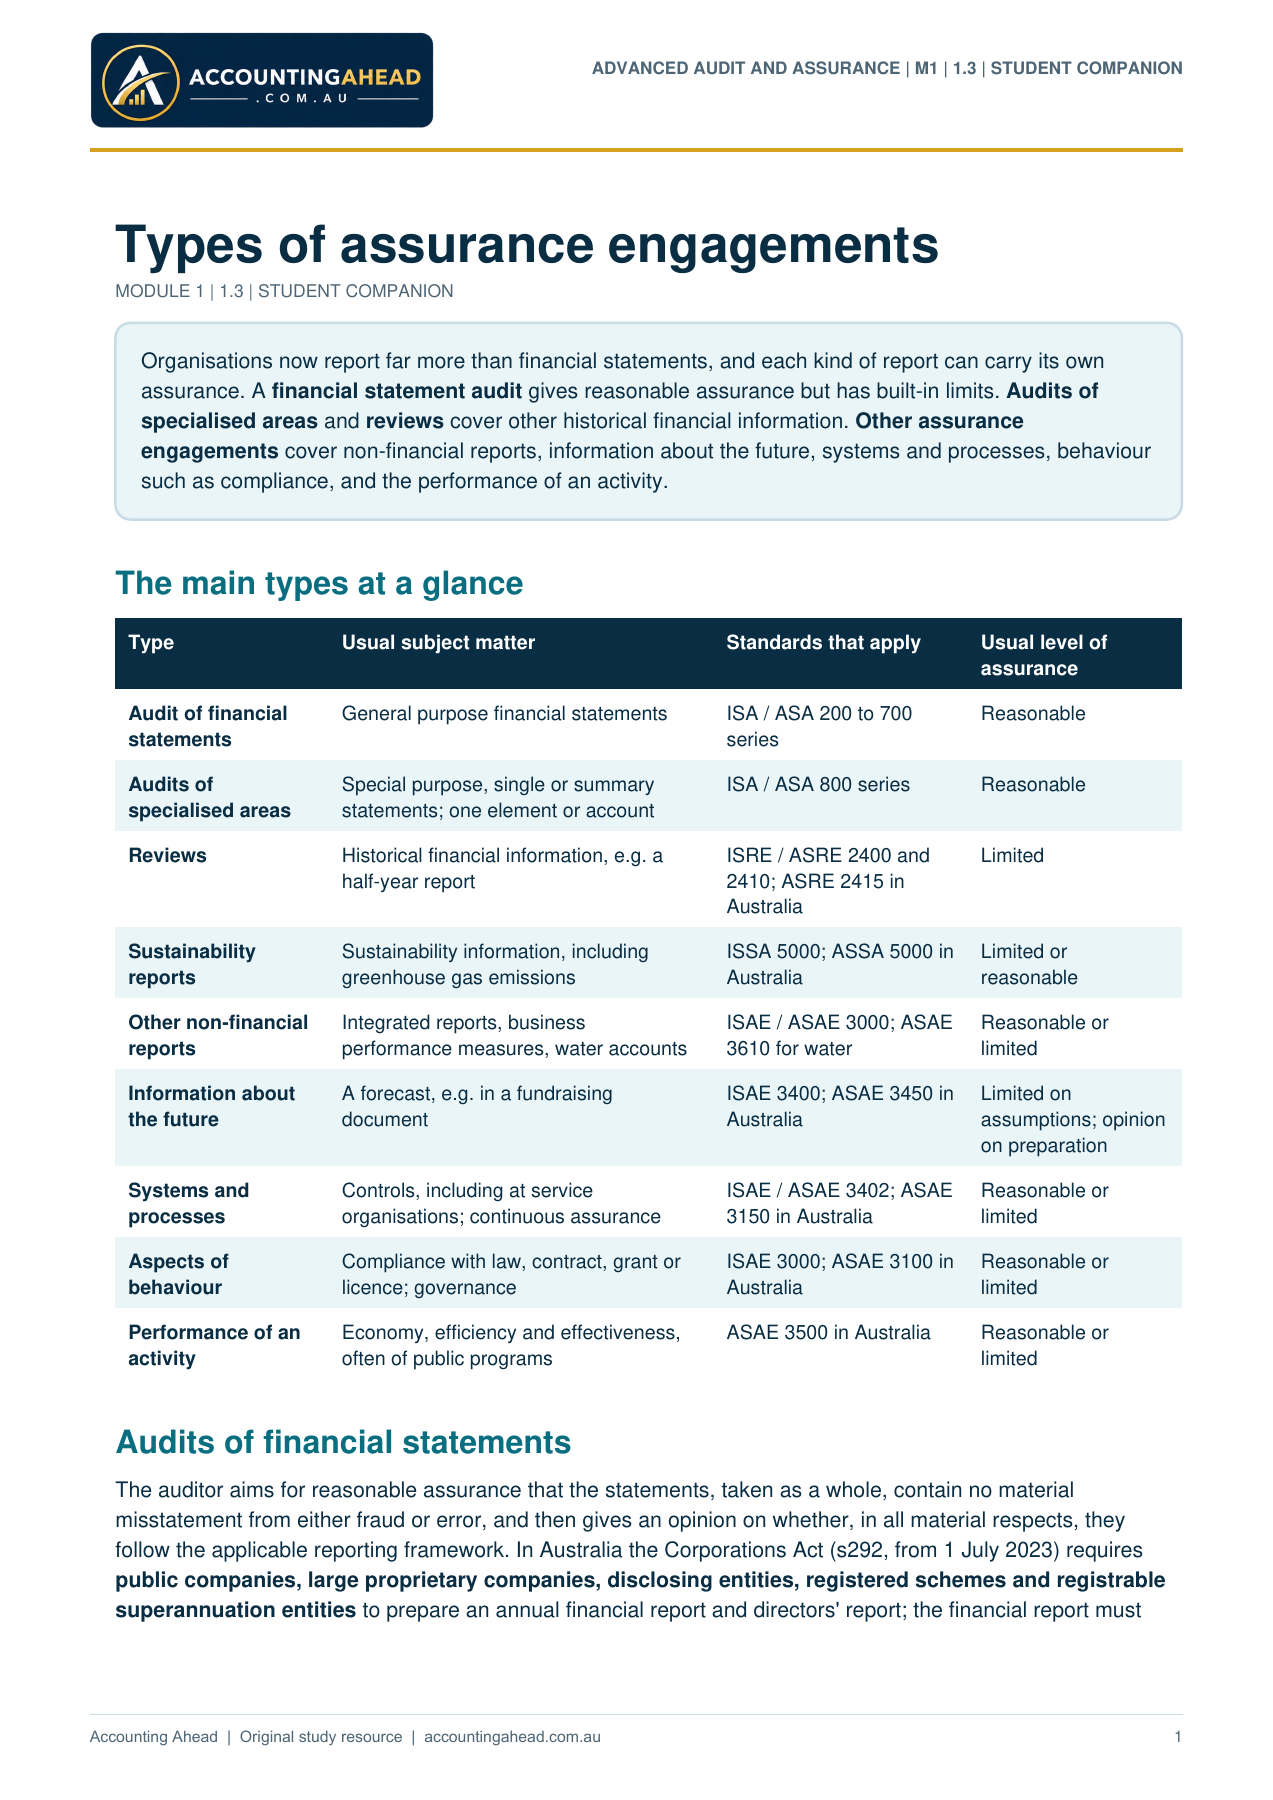
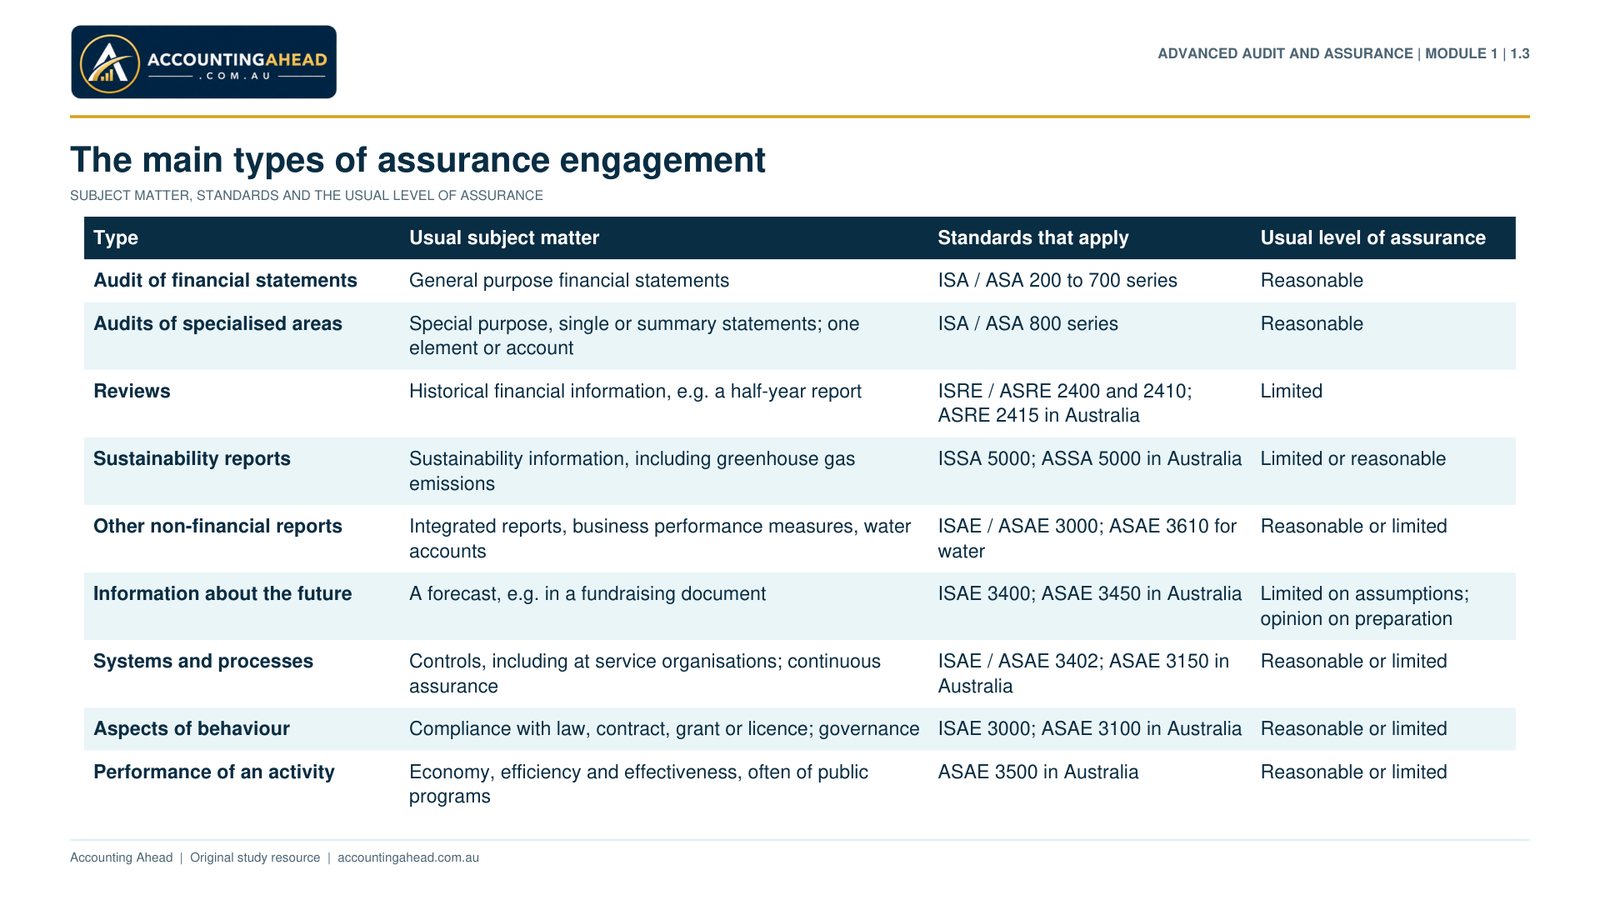
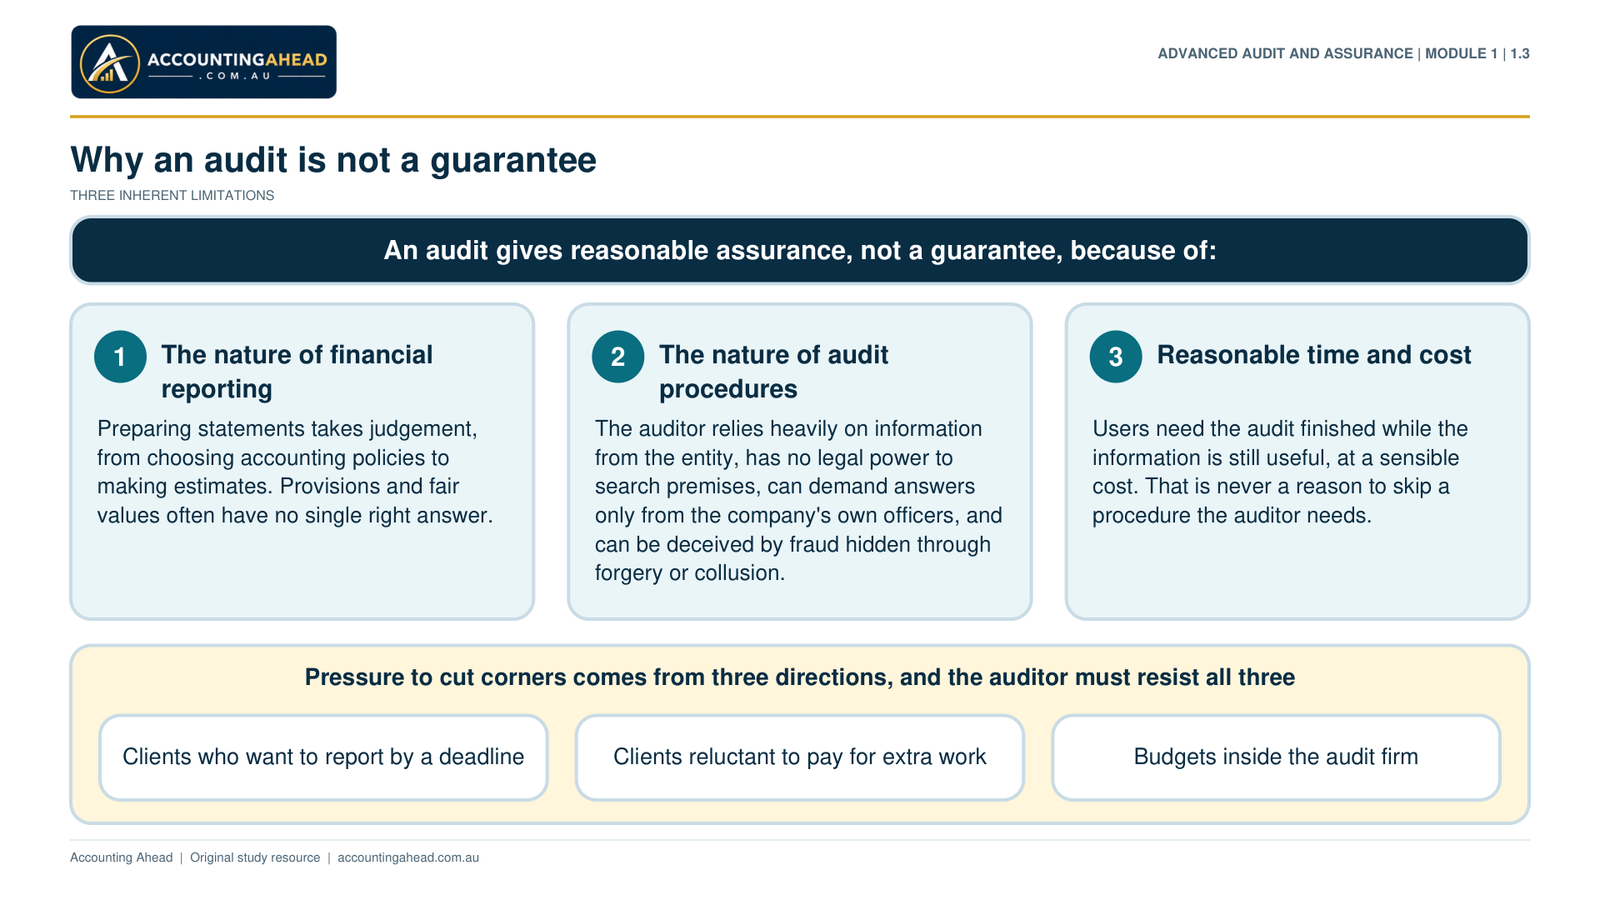
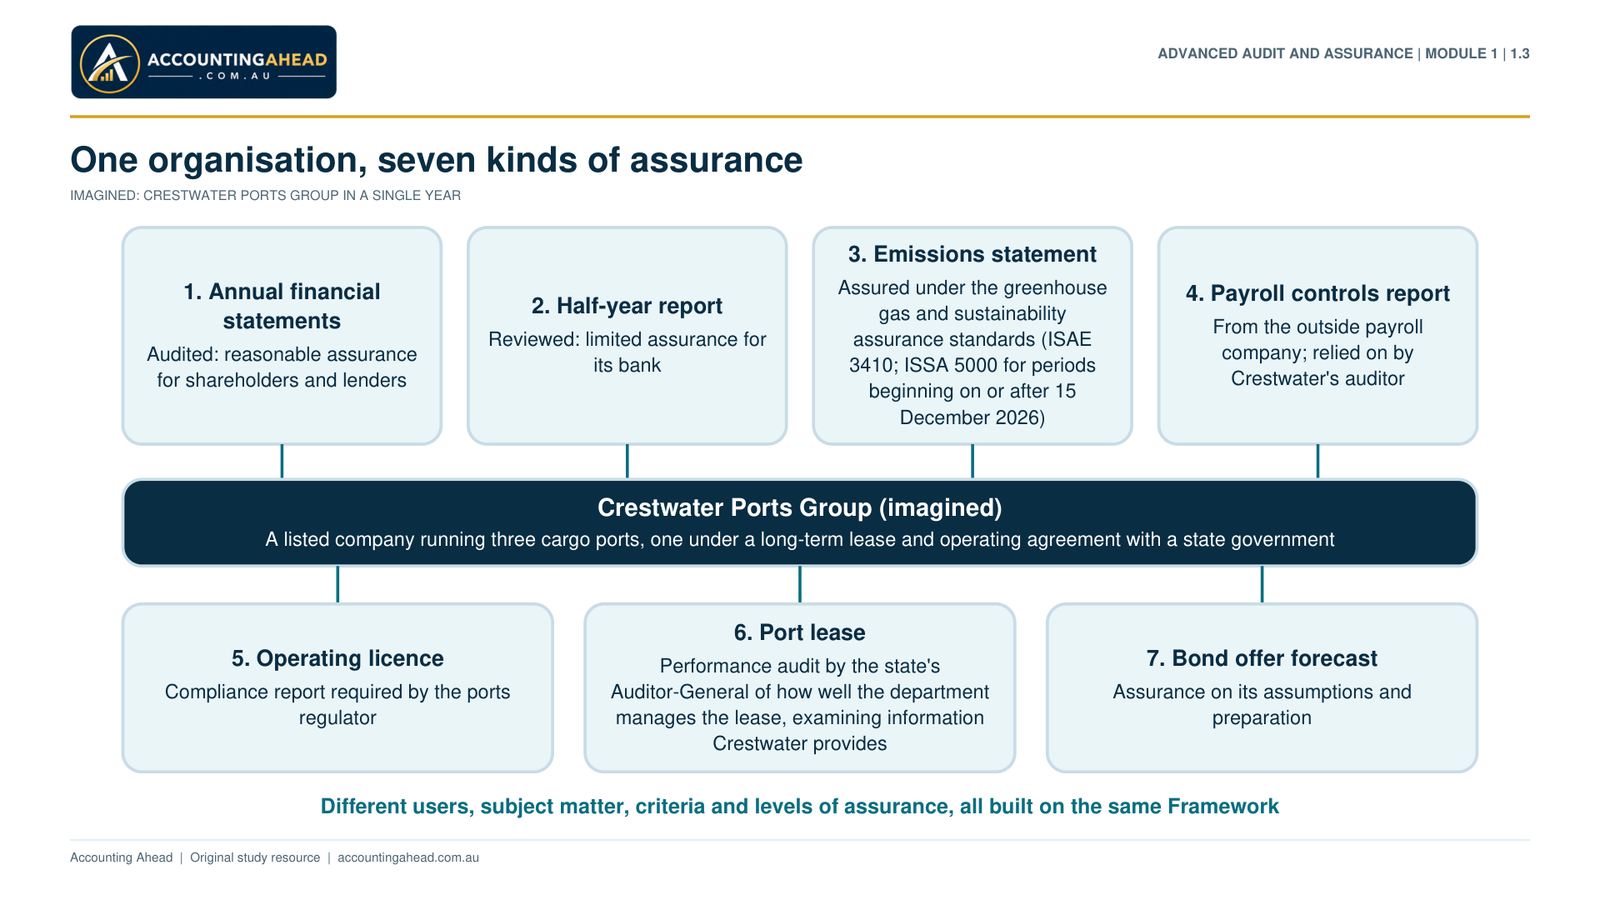
Part 1.3 · Types of Assurance Engagements
Part 1.4 · Applying the Standards
Part 1.5.1 · Business Models and Climate-Risk Disclosure
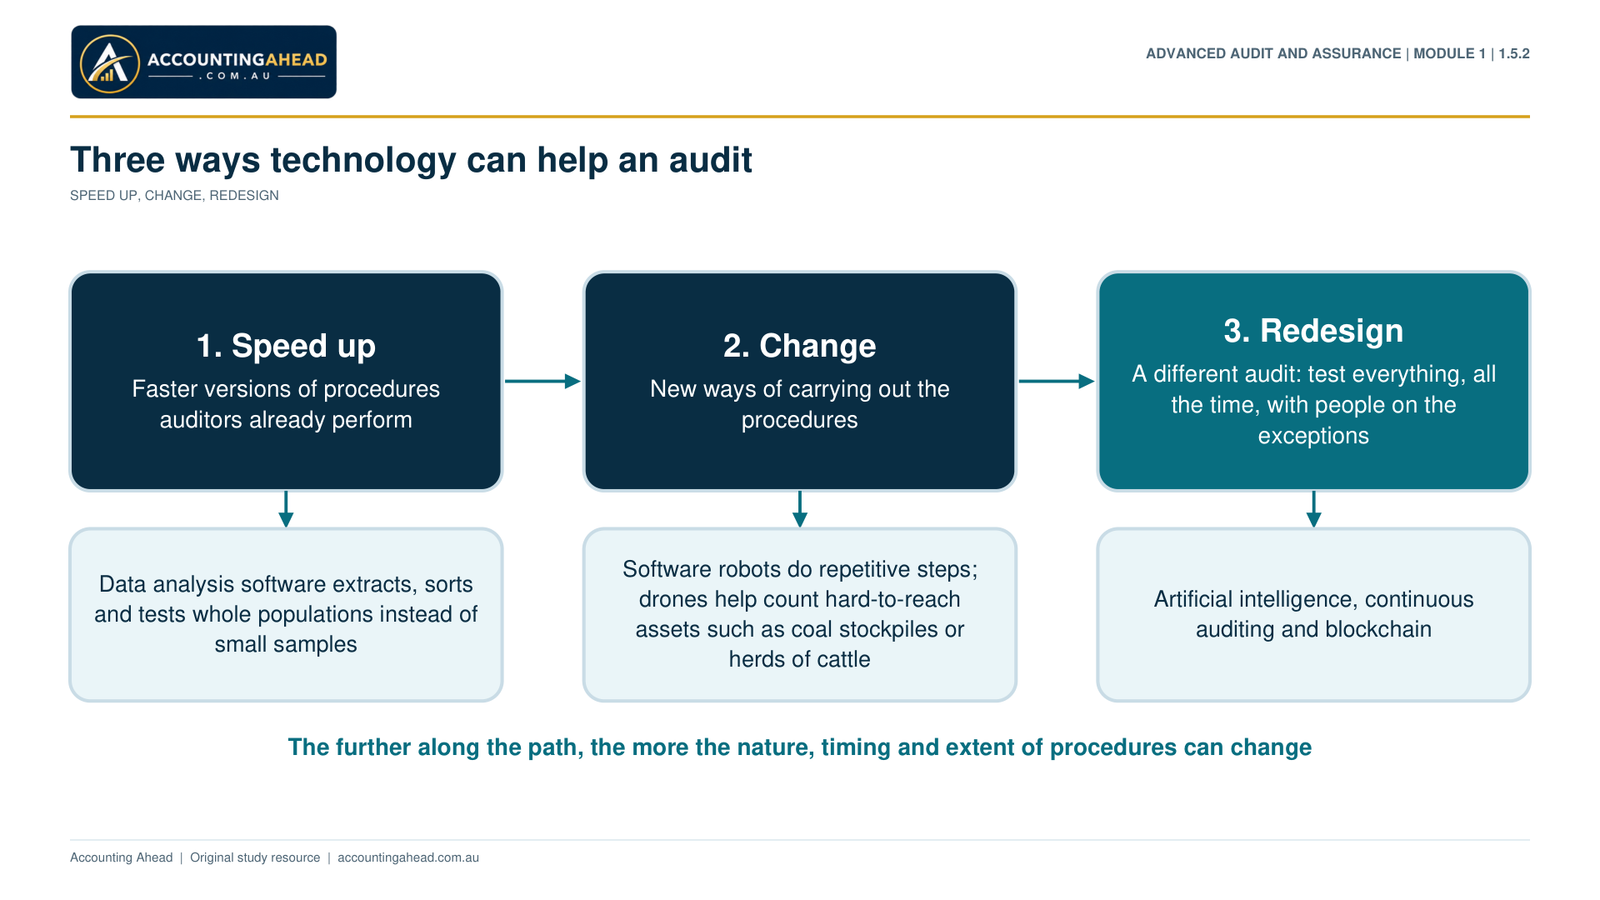
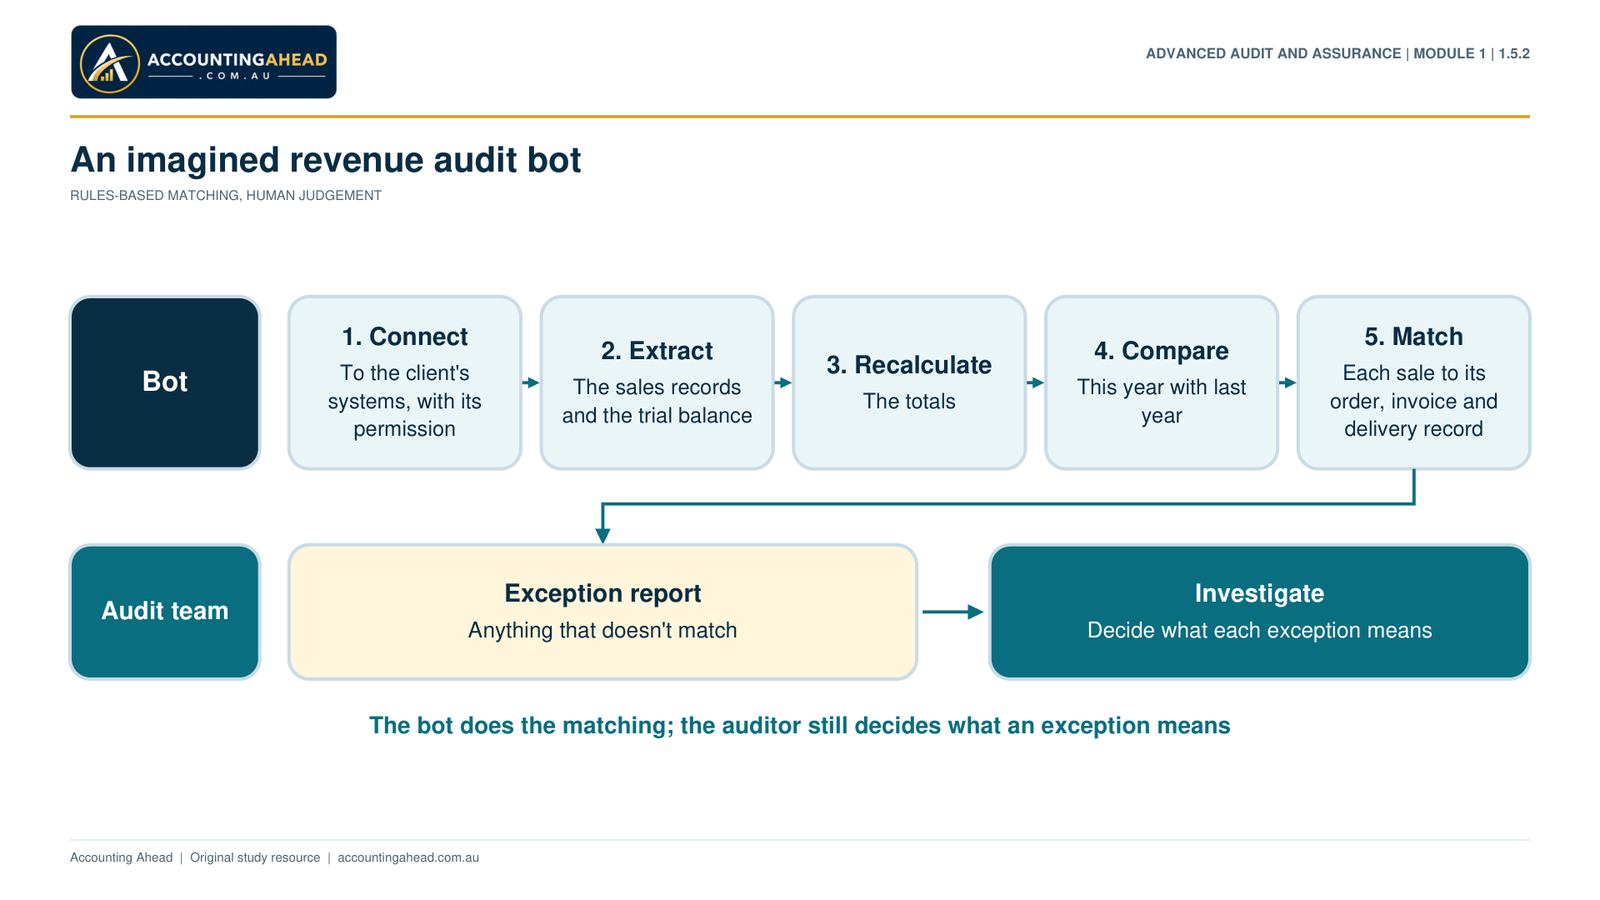
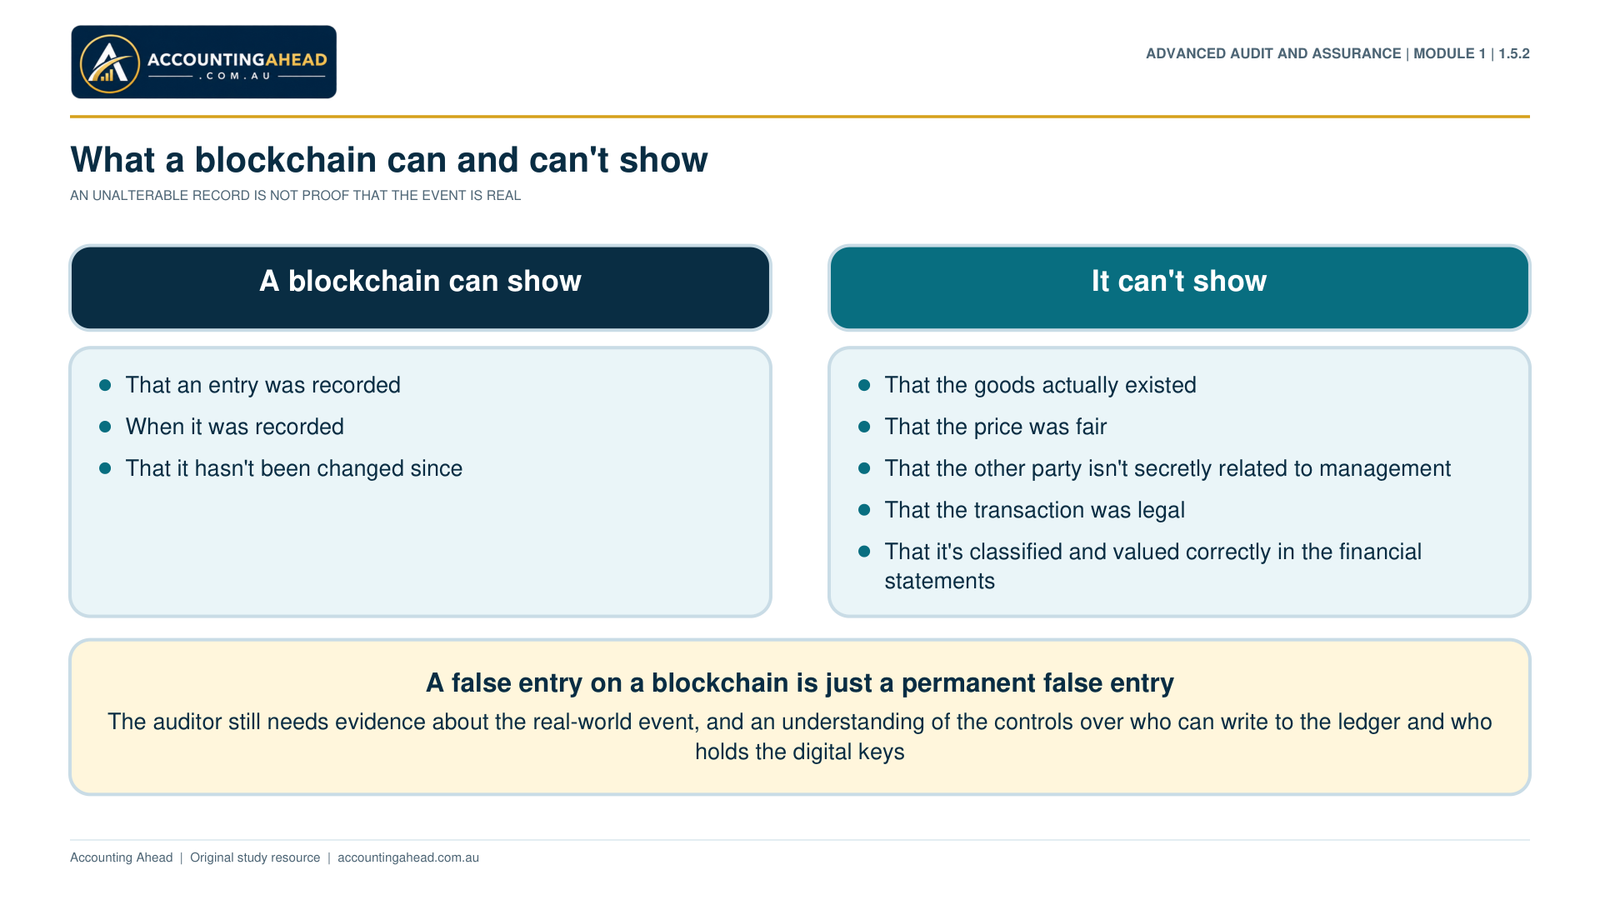
Part 1.5.2 · Technology and the Audit
Module 2 · Planning the audit of historical financial information
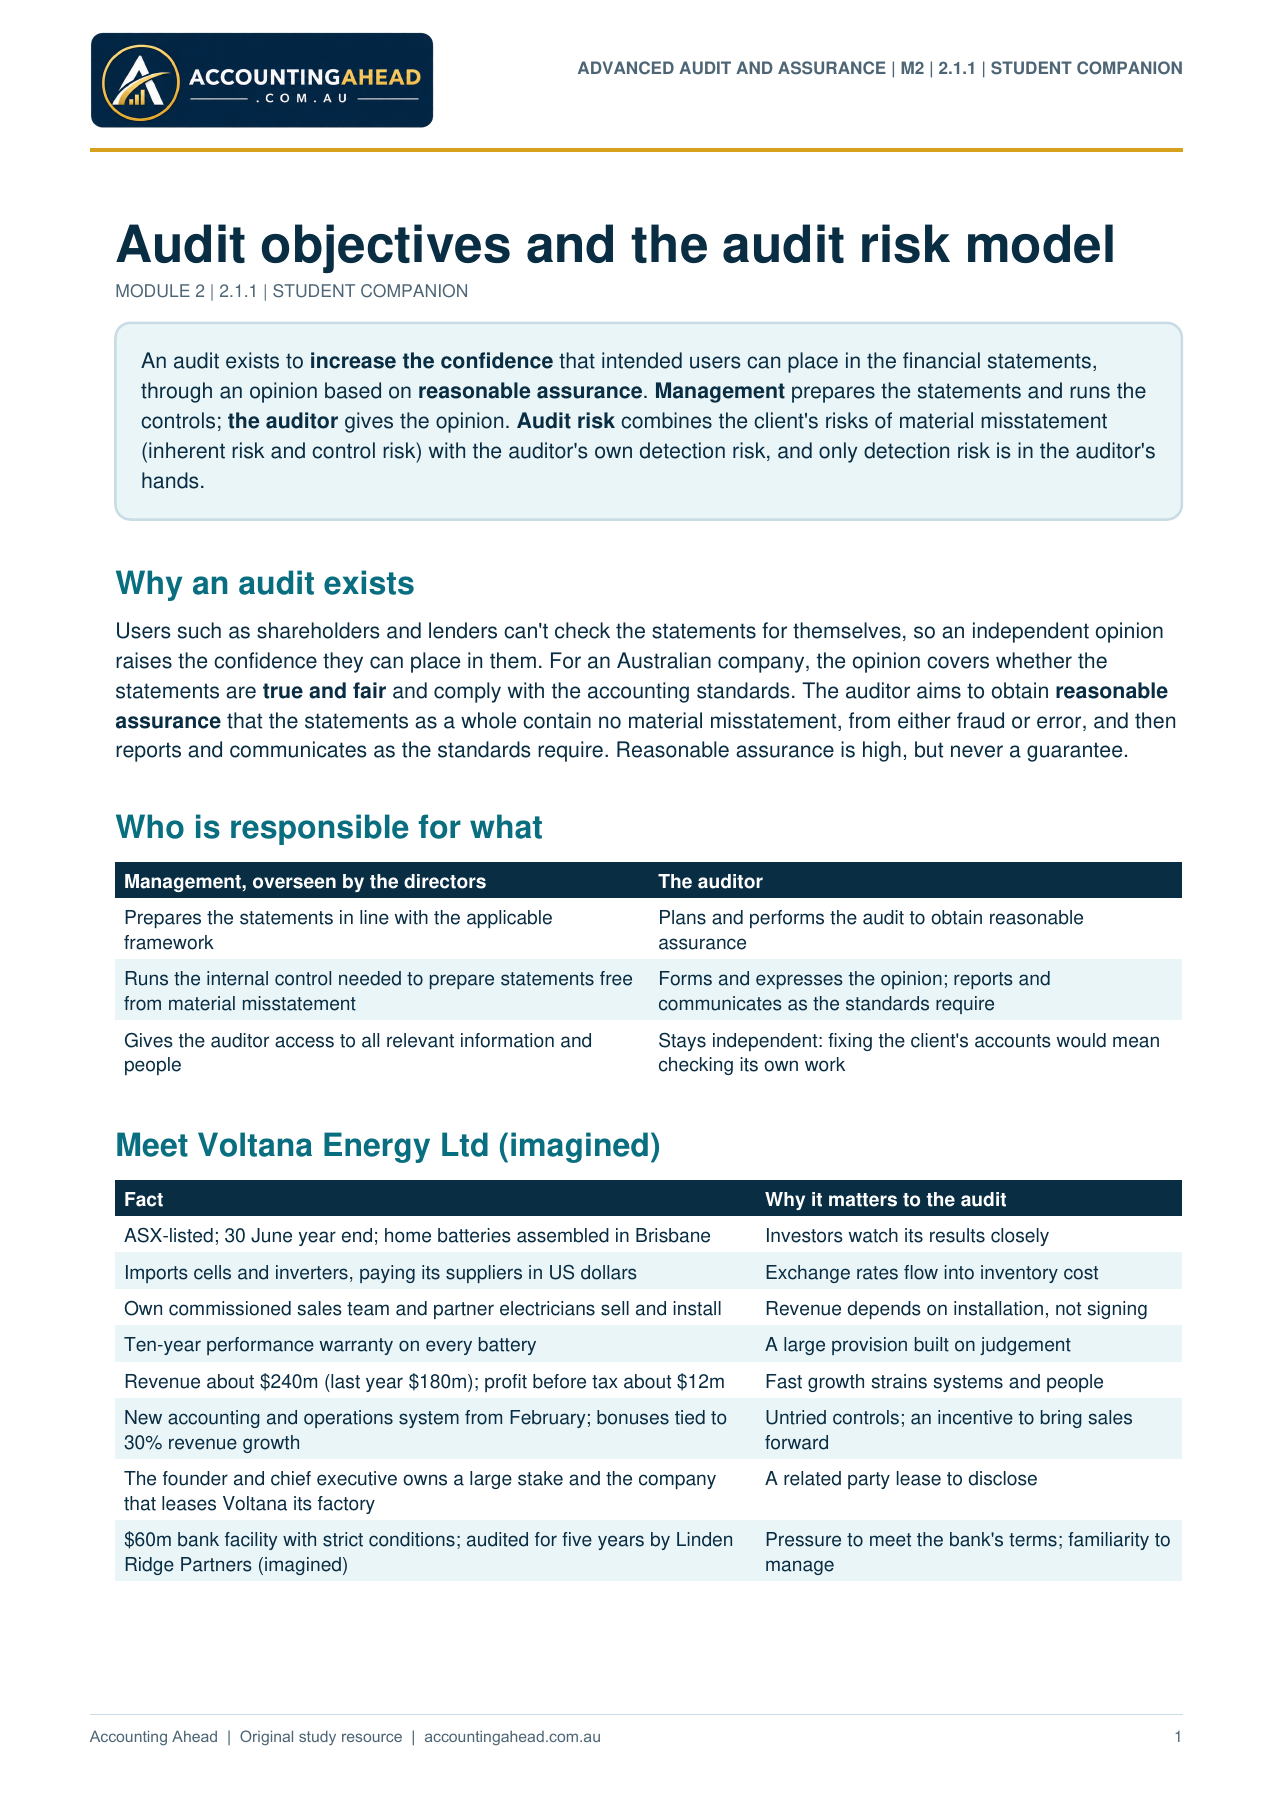
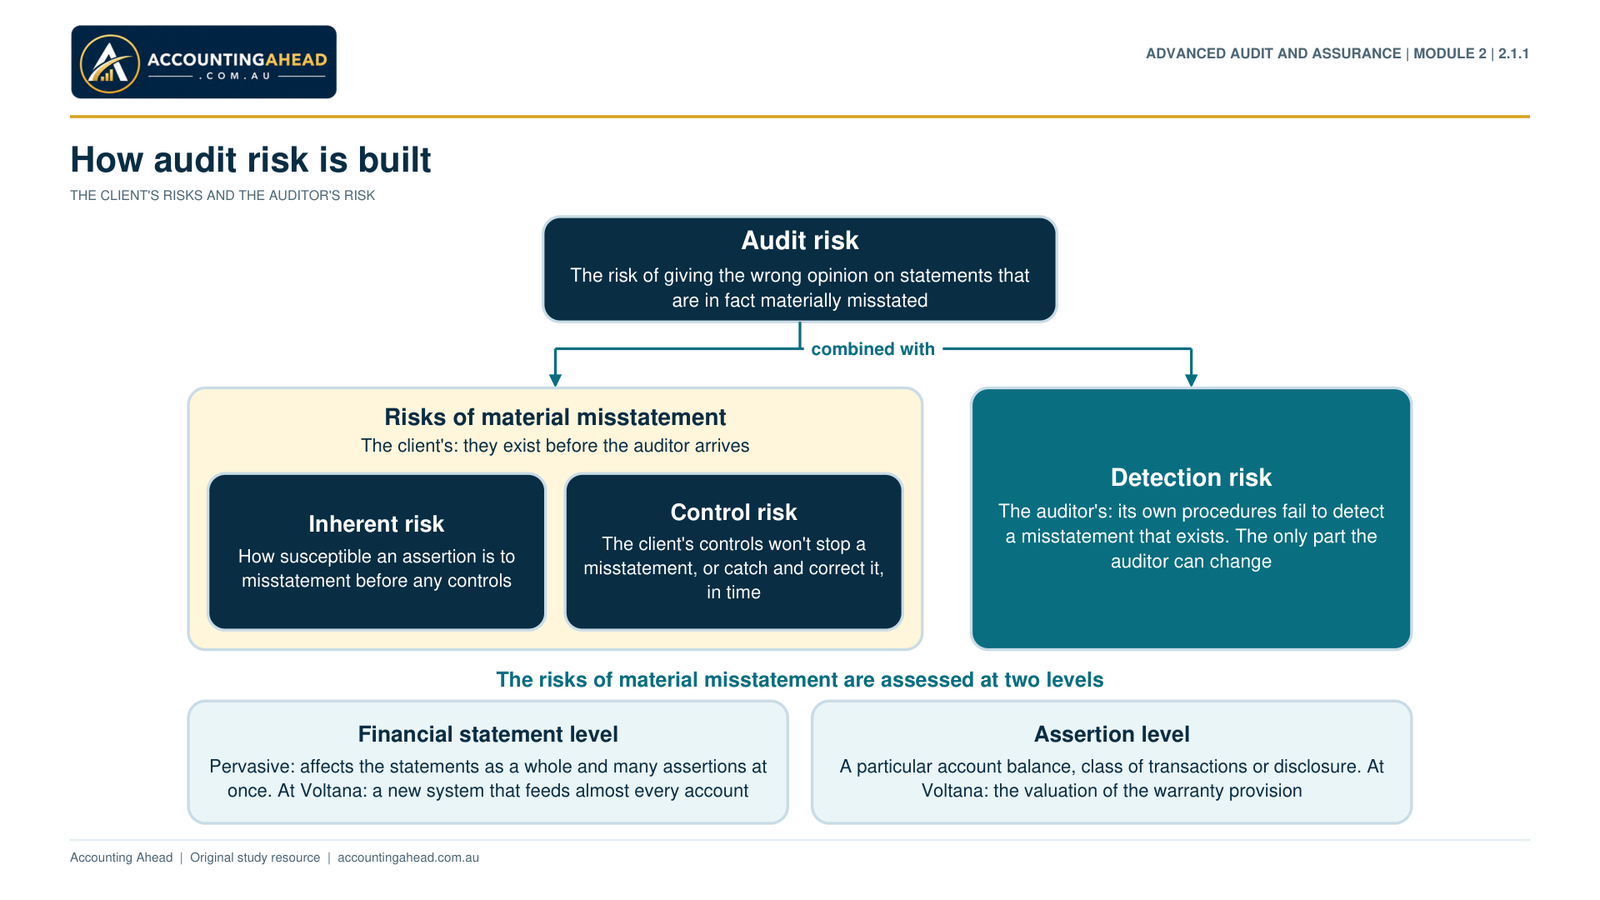
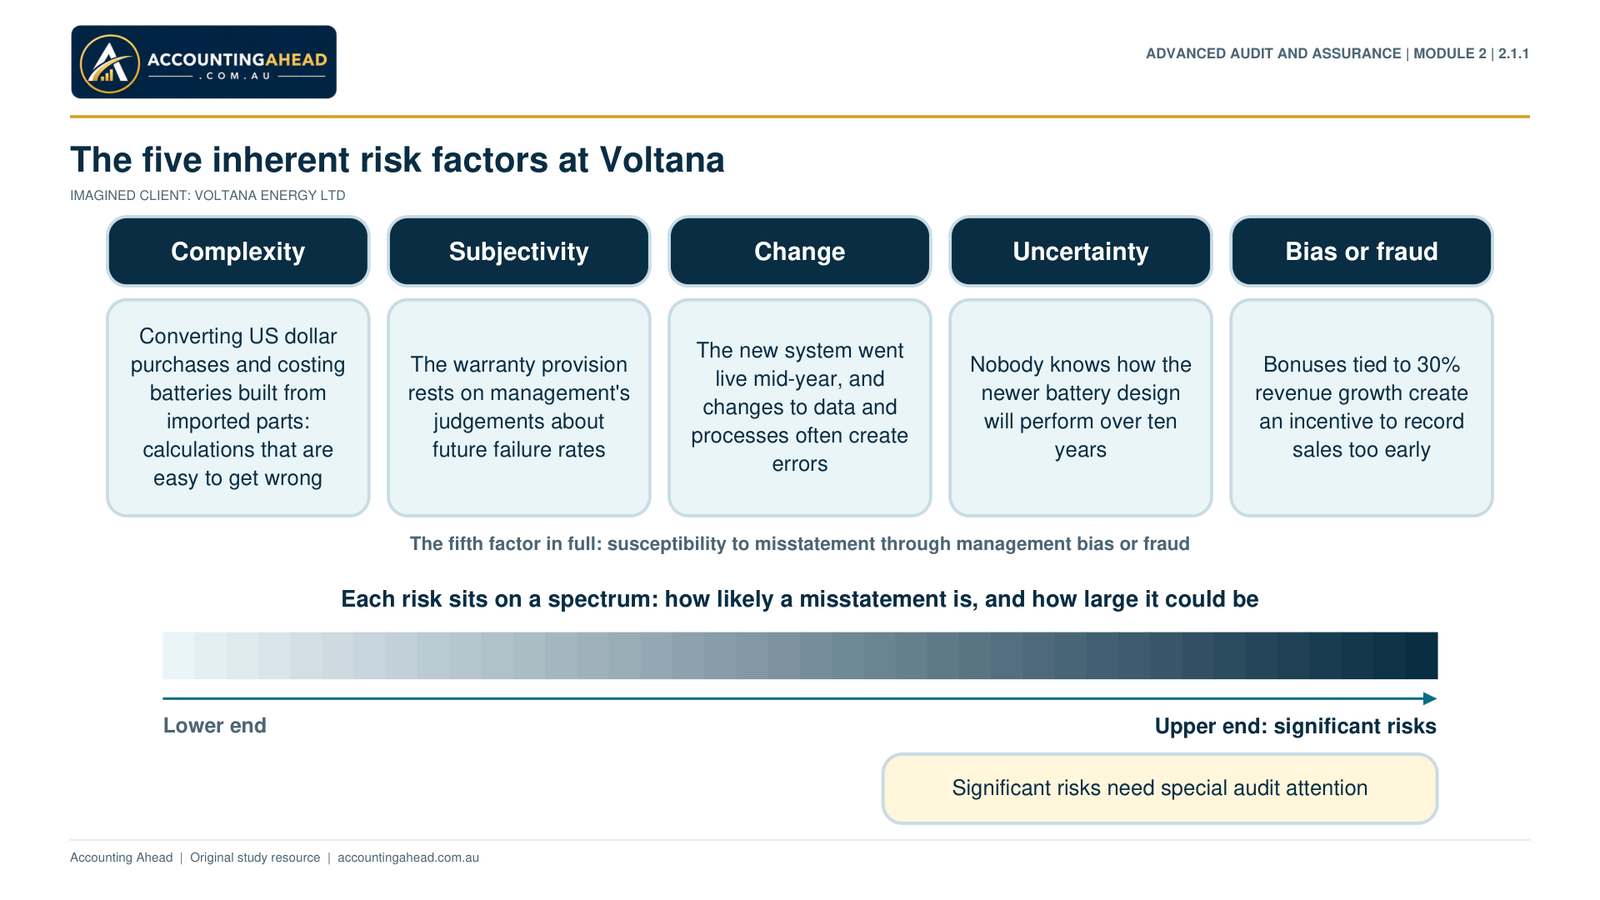
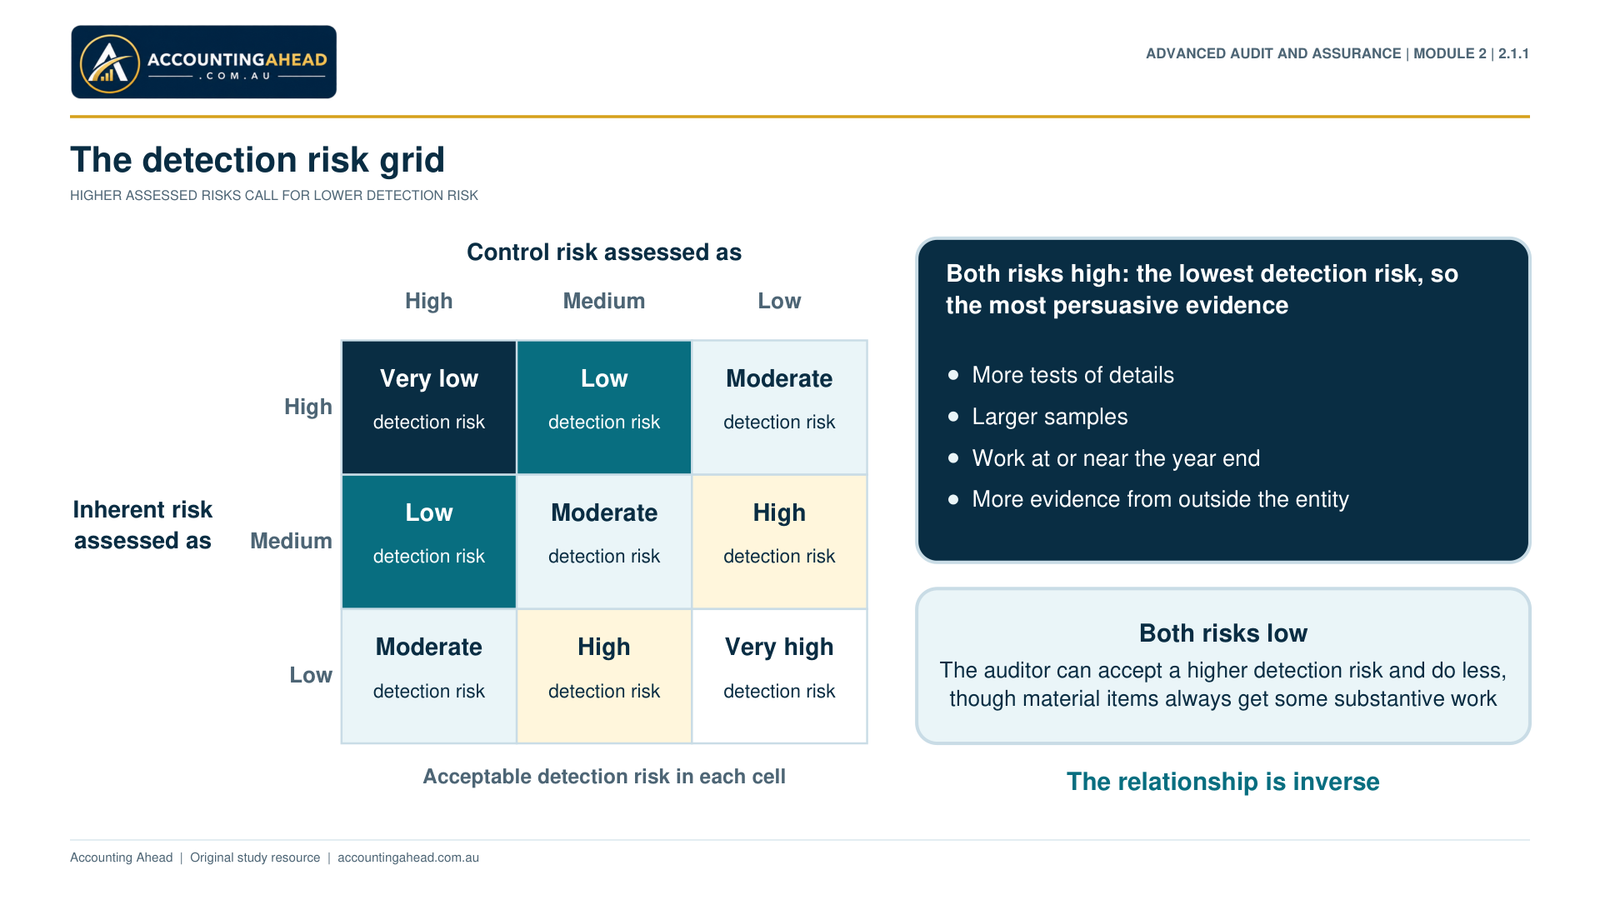
Part 2.1.1 · Audit Objectives and the Audit Risk Model
Part 2.1.2 · Independence, Rotation and the Law
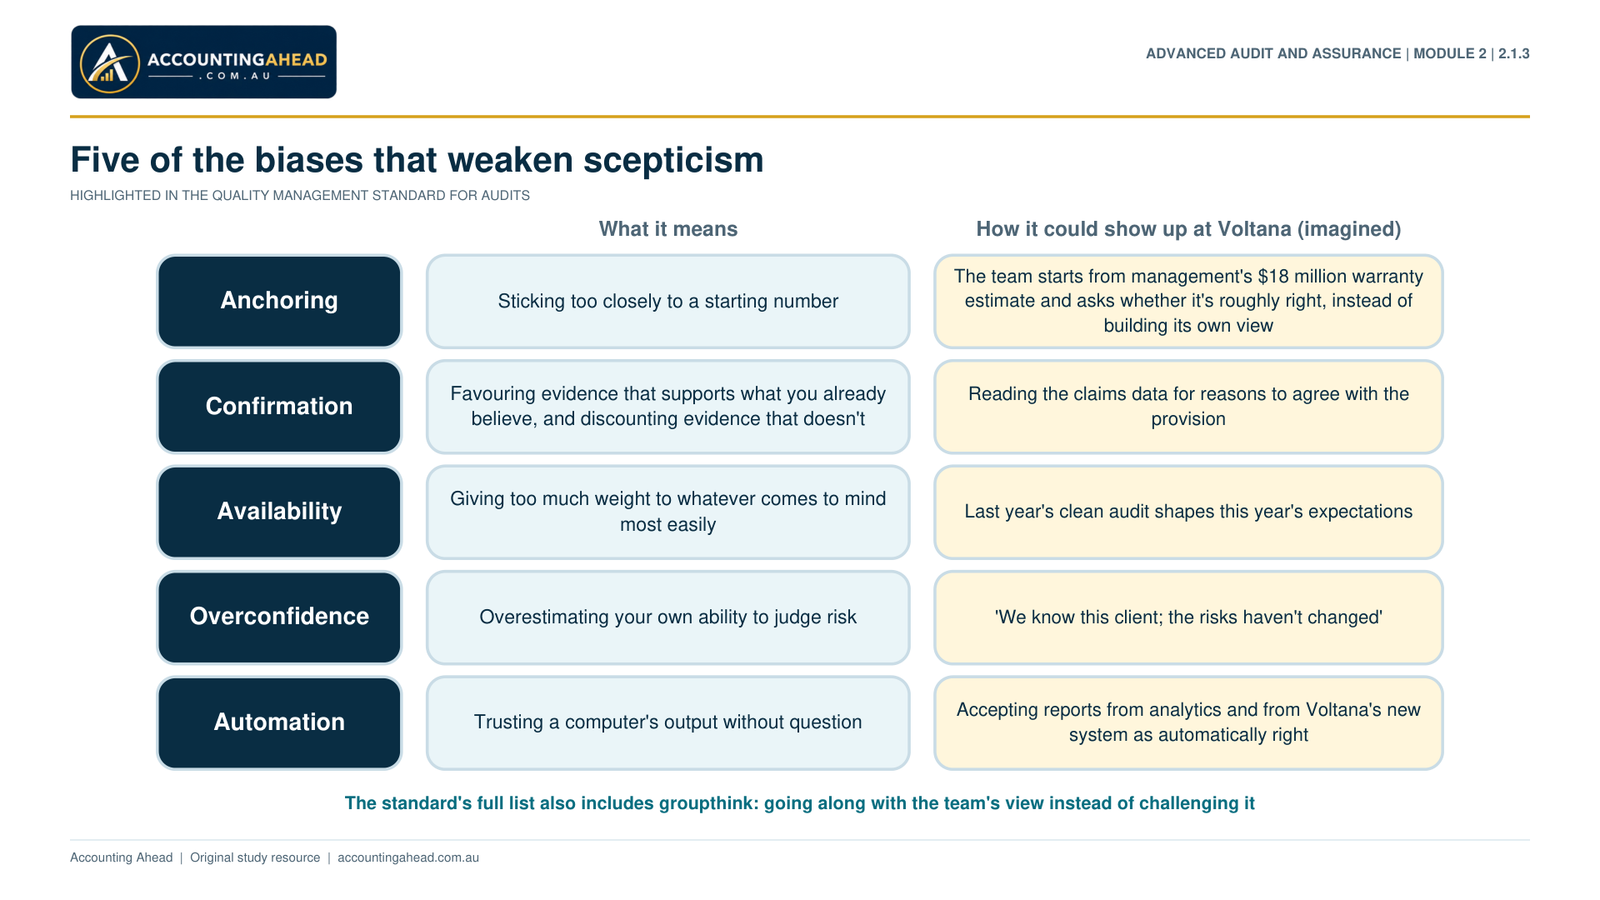
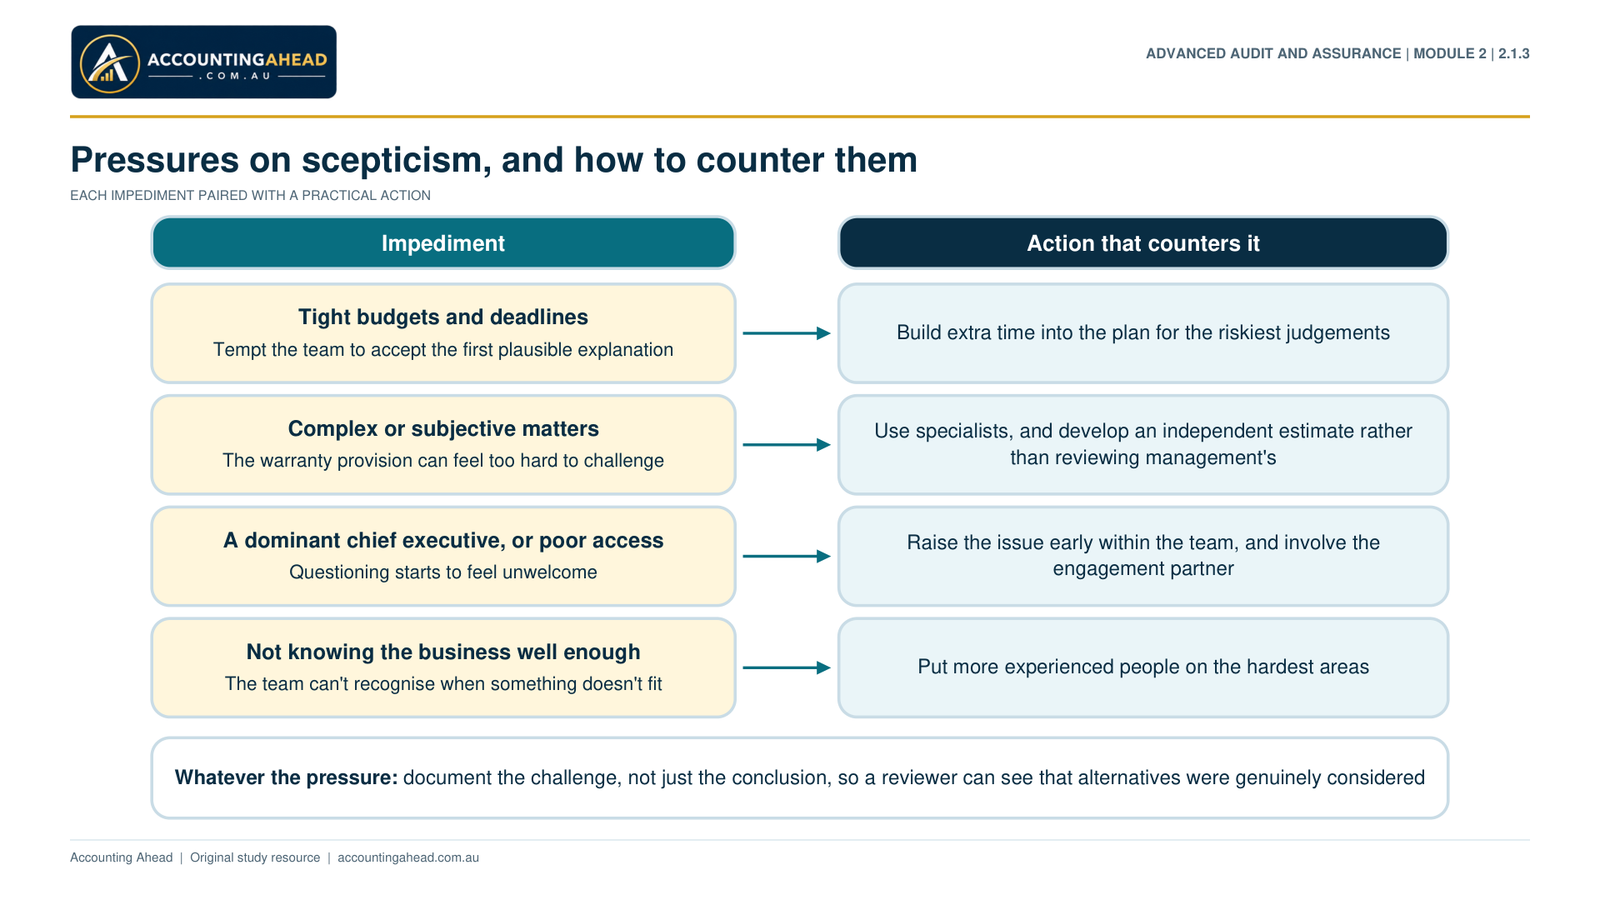
Part 2.1.3 · Scepticism and Judgement in Practice
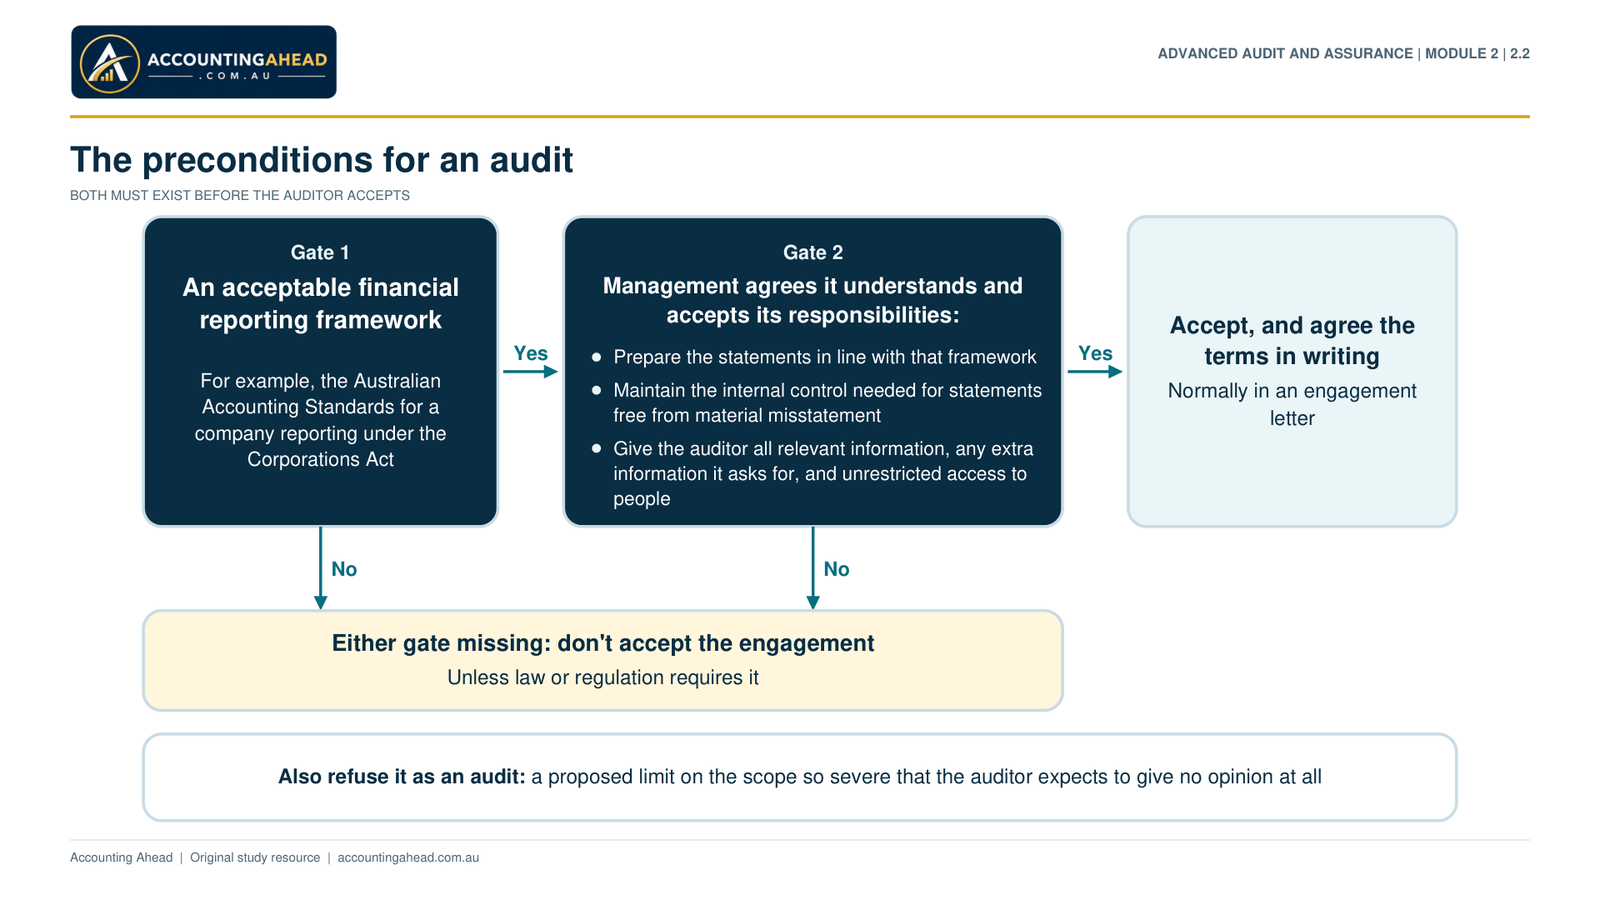
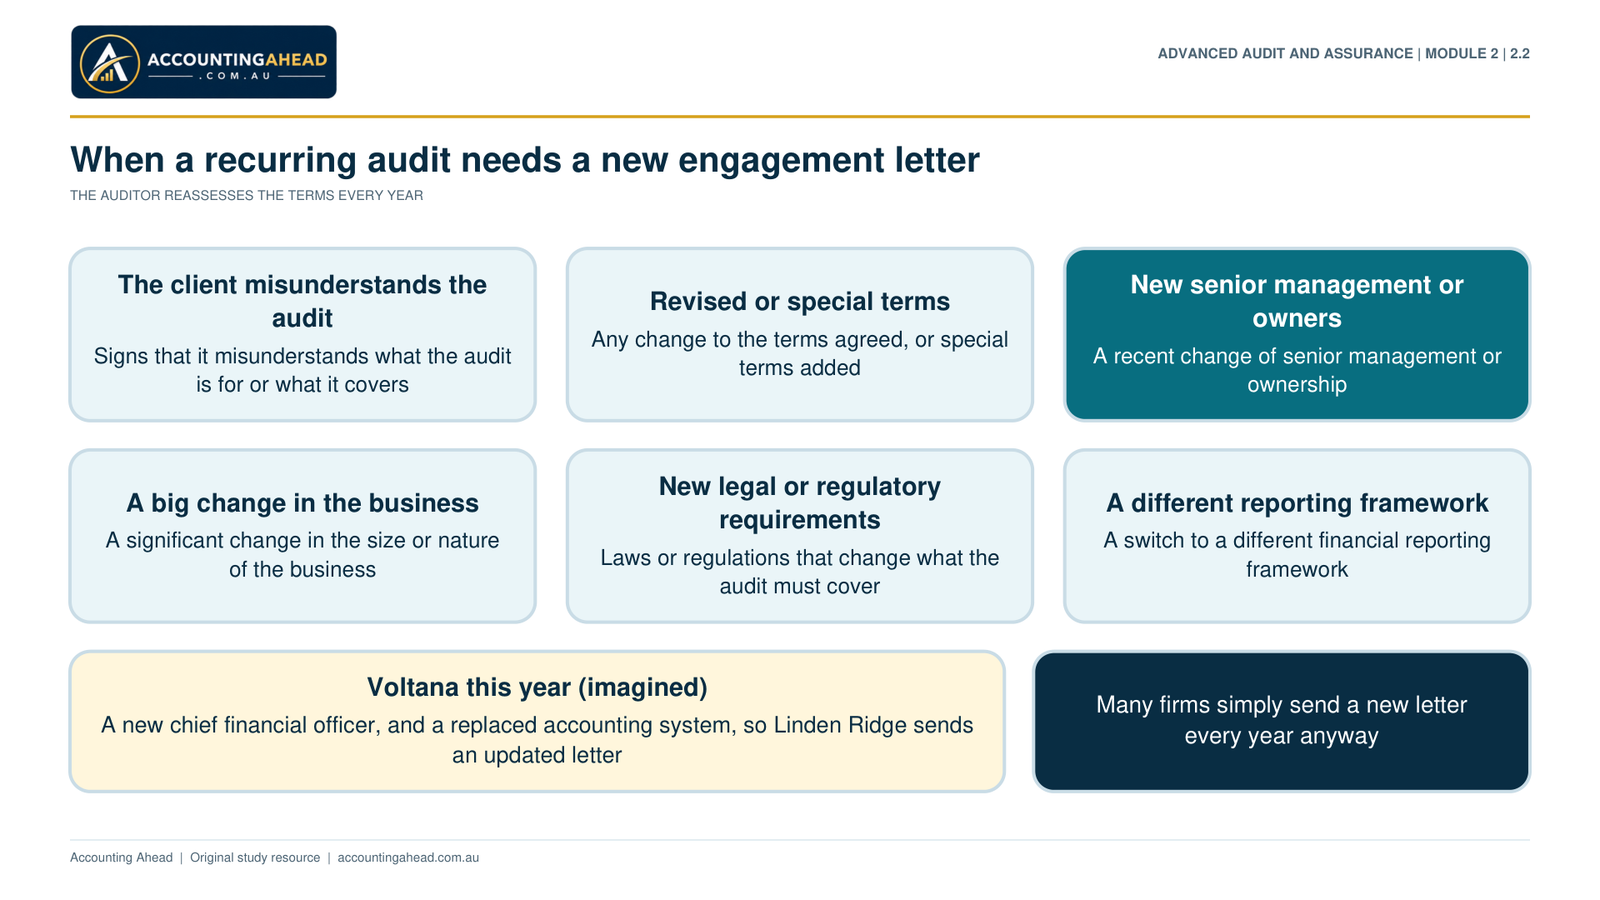
Part 2.2 · Preconditions and Terms of Engagement
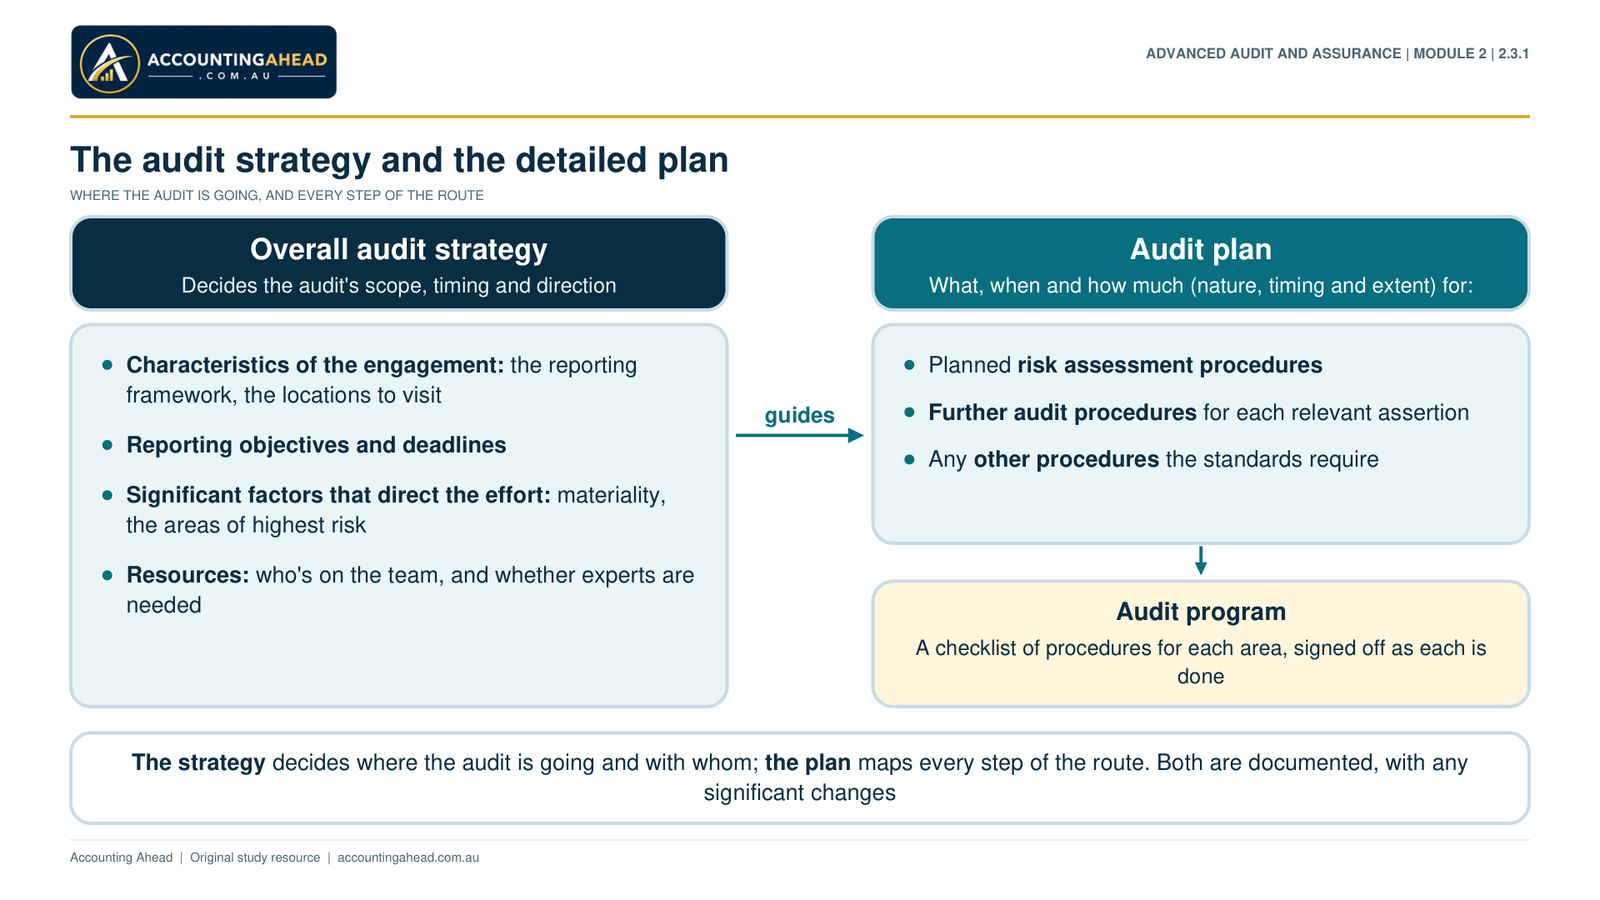
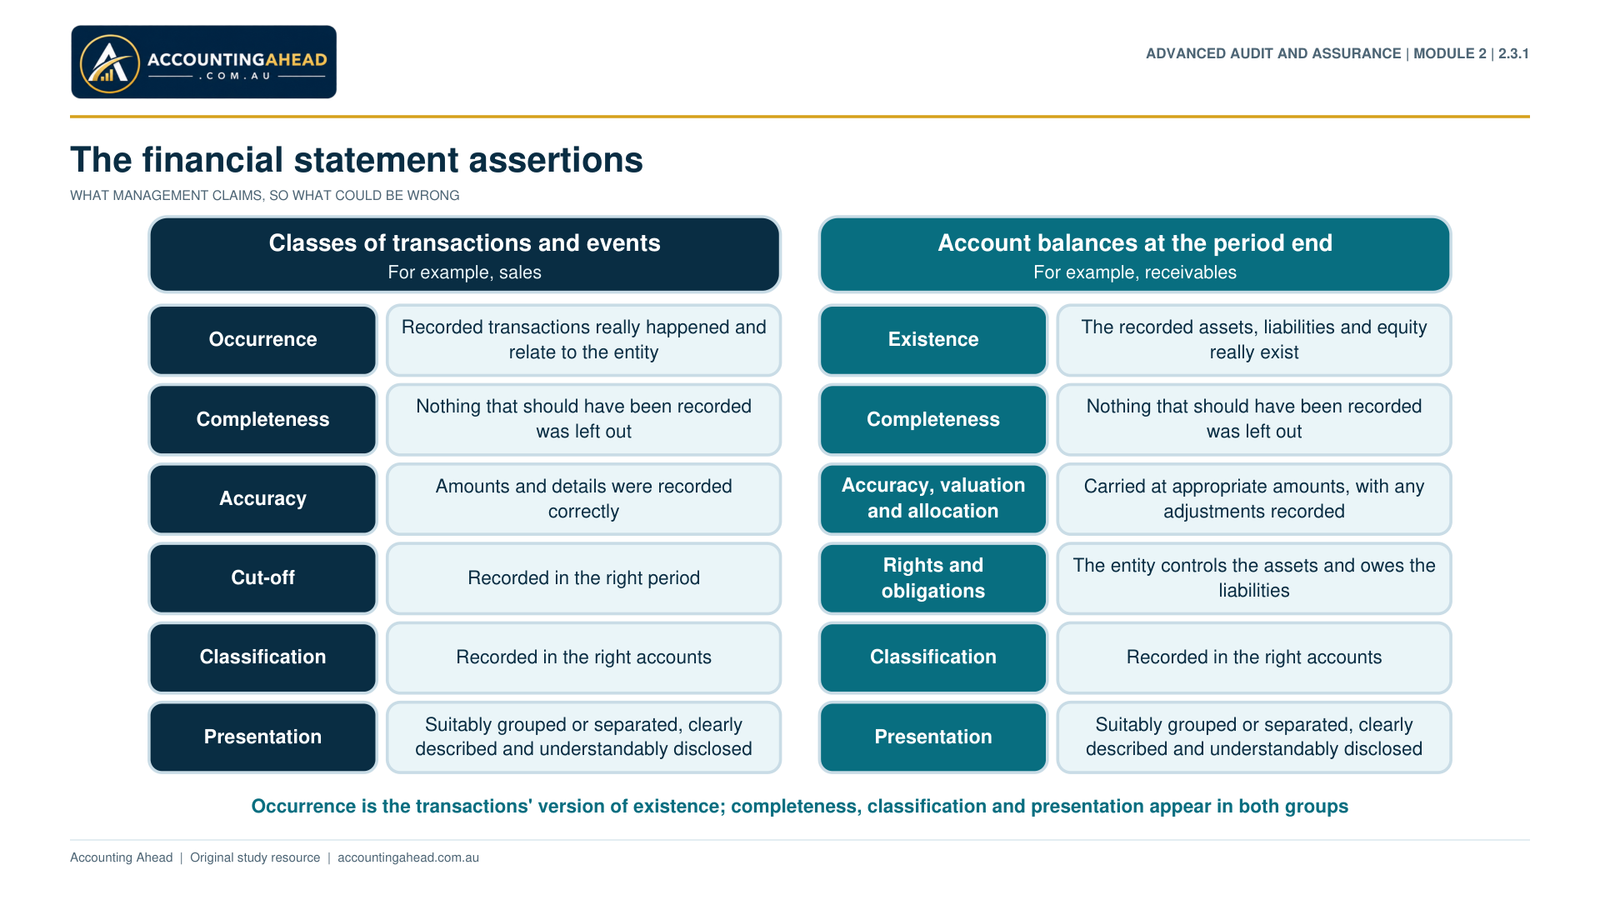
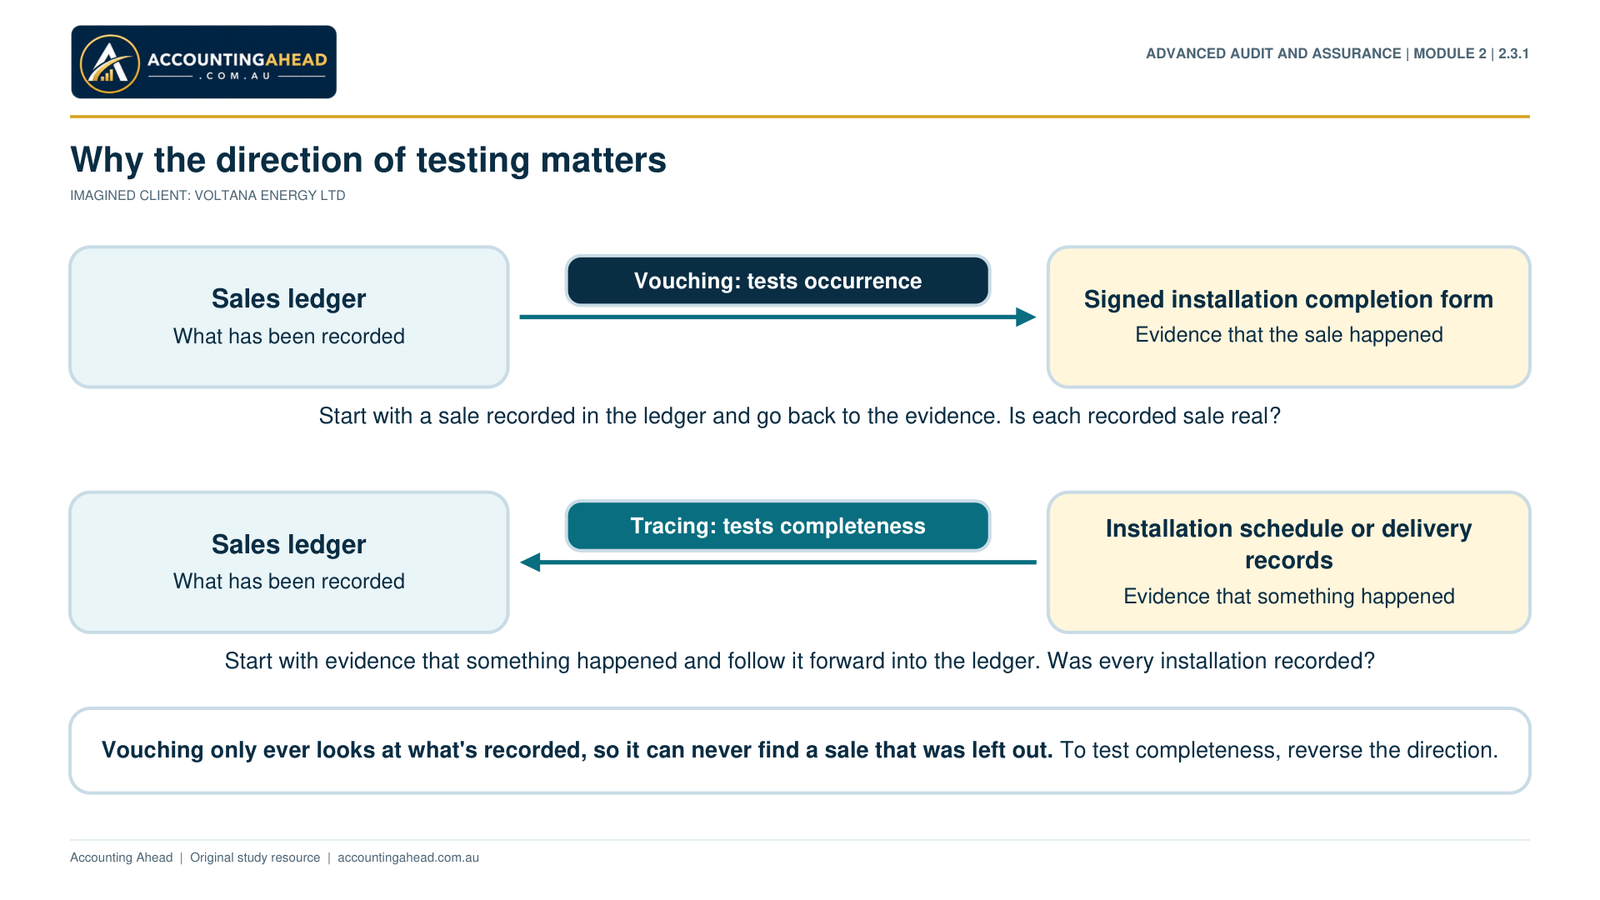
Part 2.3.1 · Audit Strategy, Audit Plan and Assertions
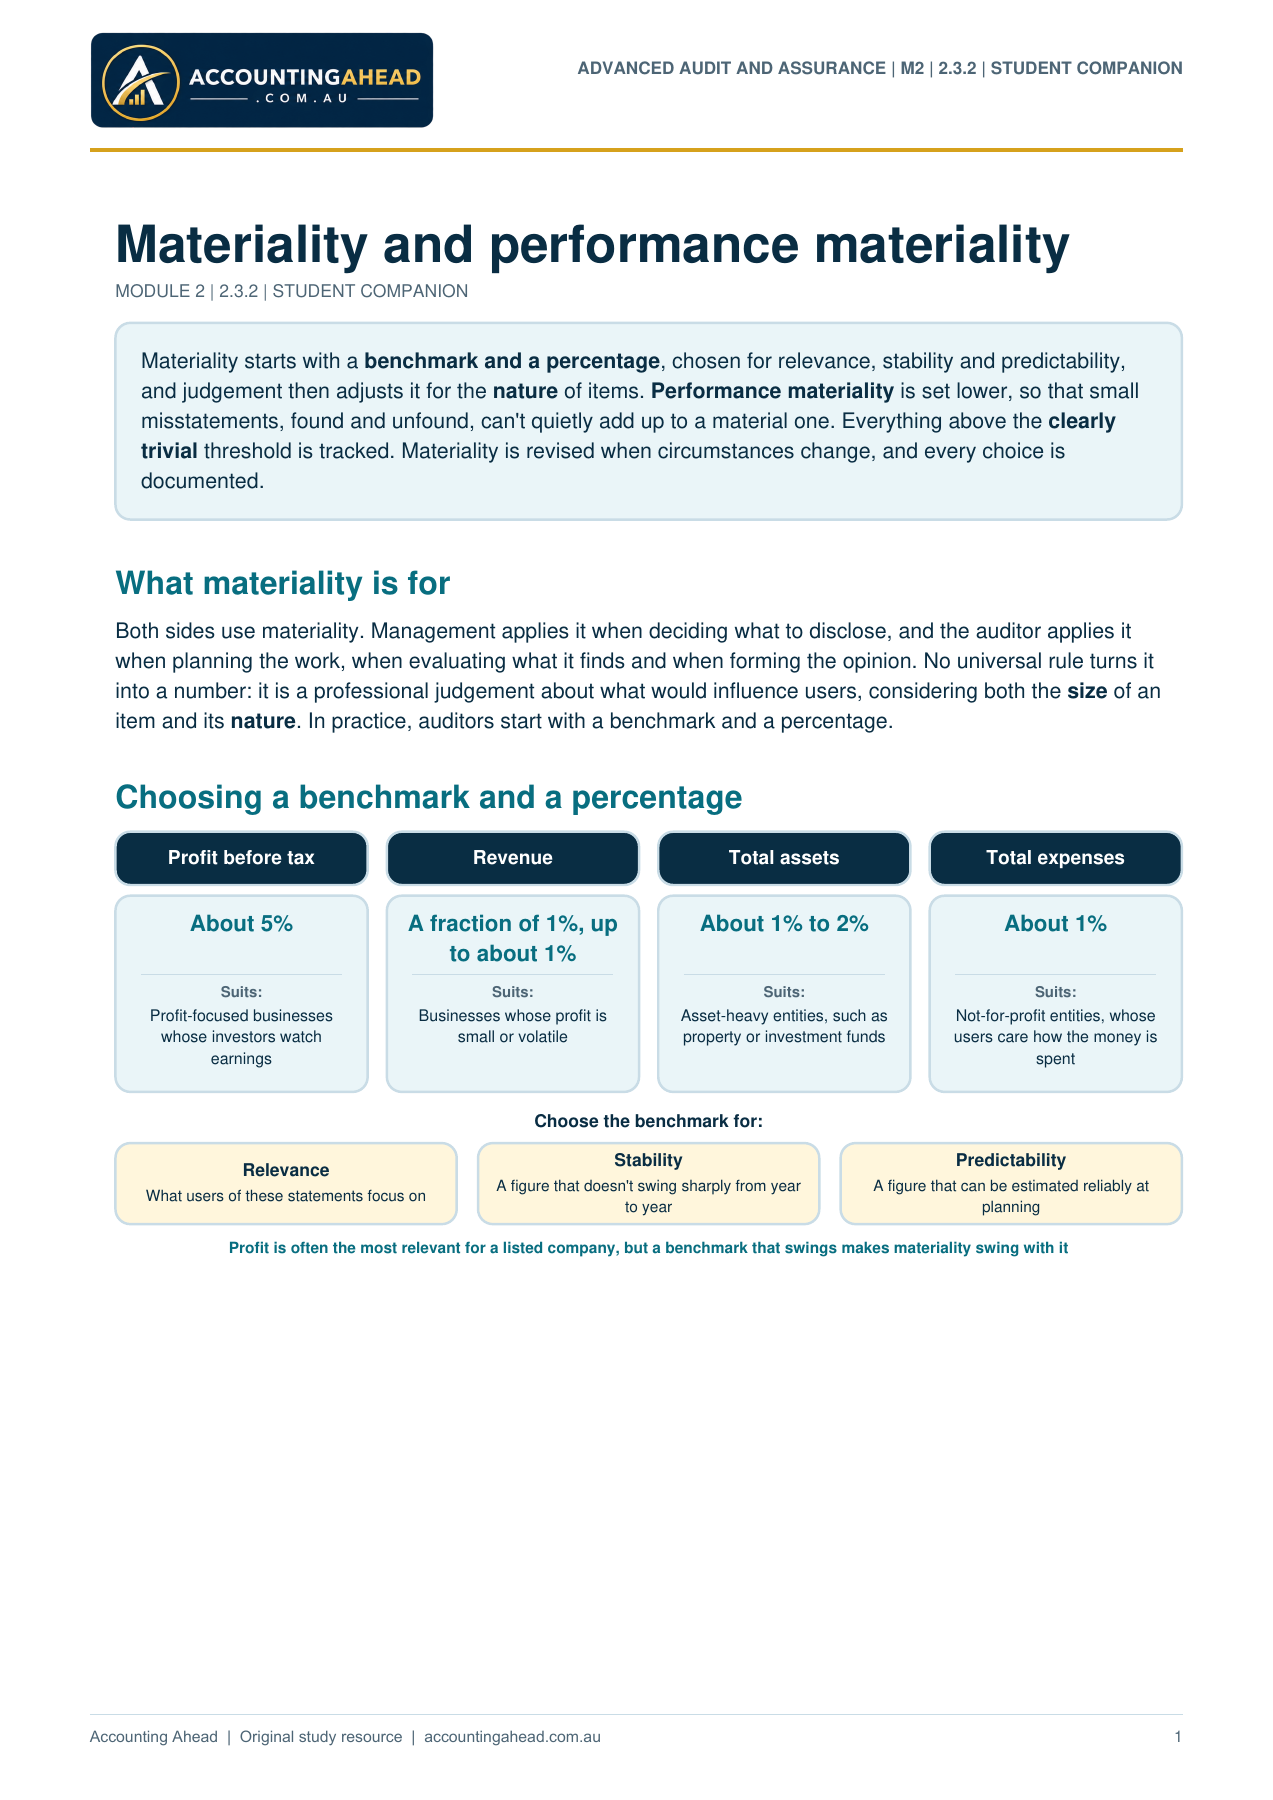
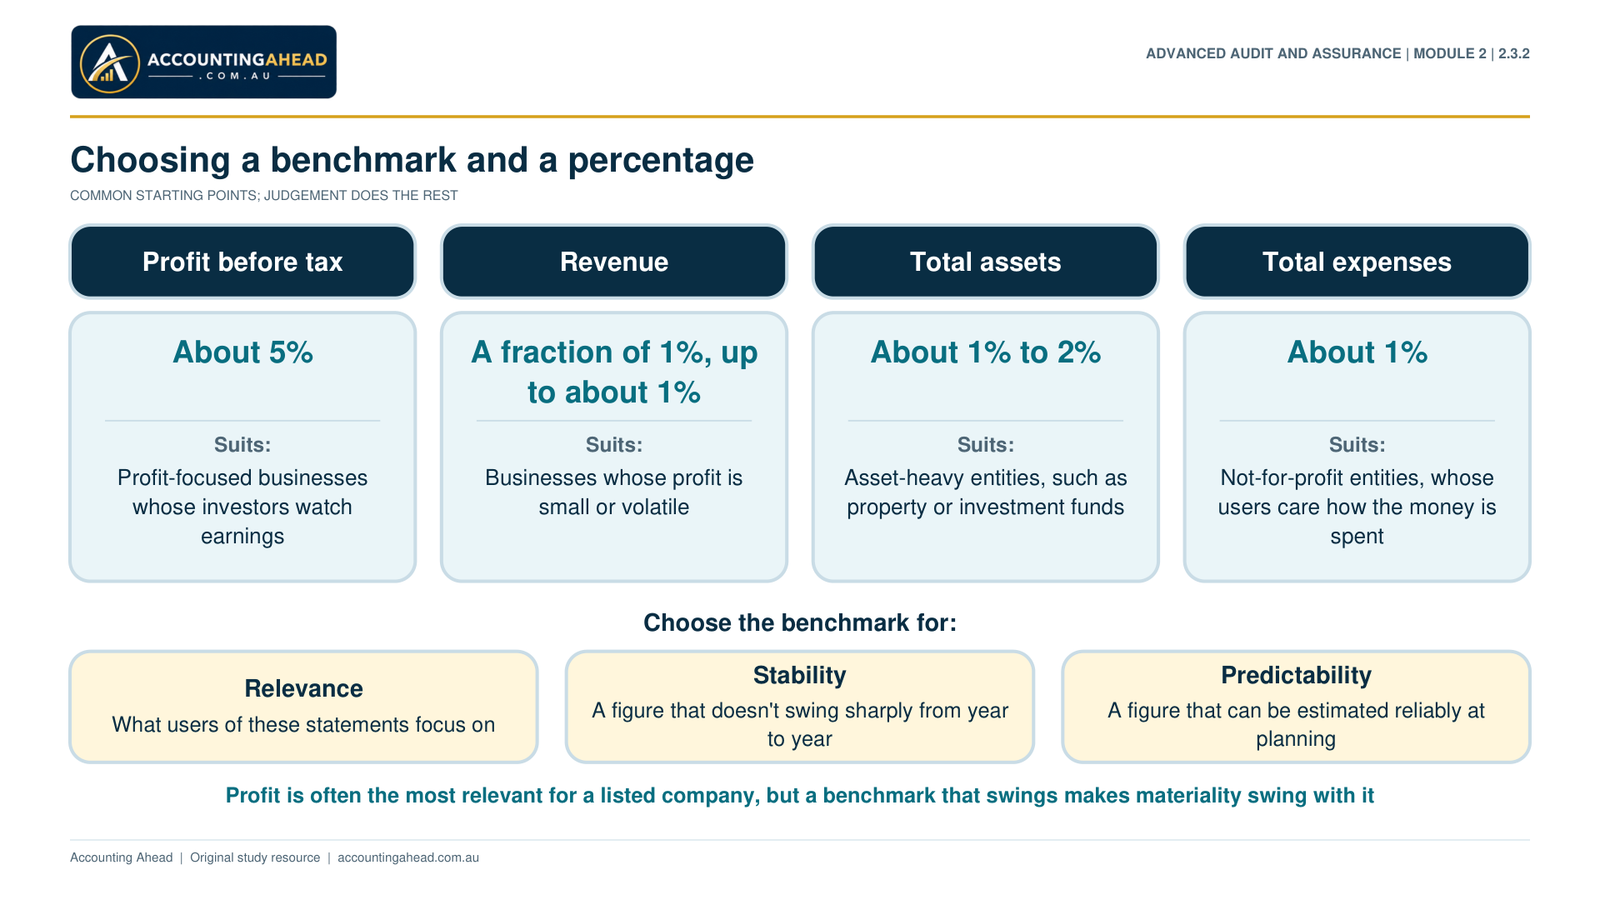
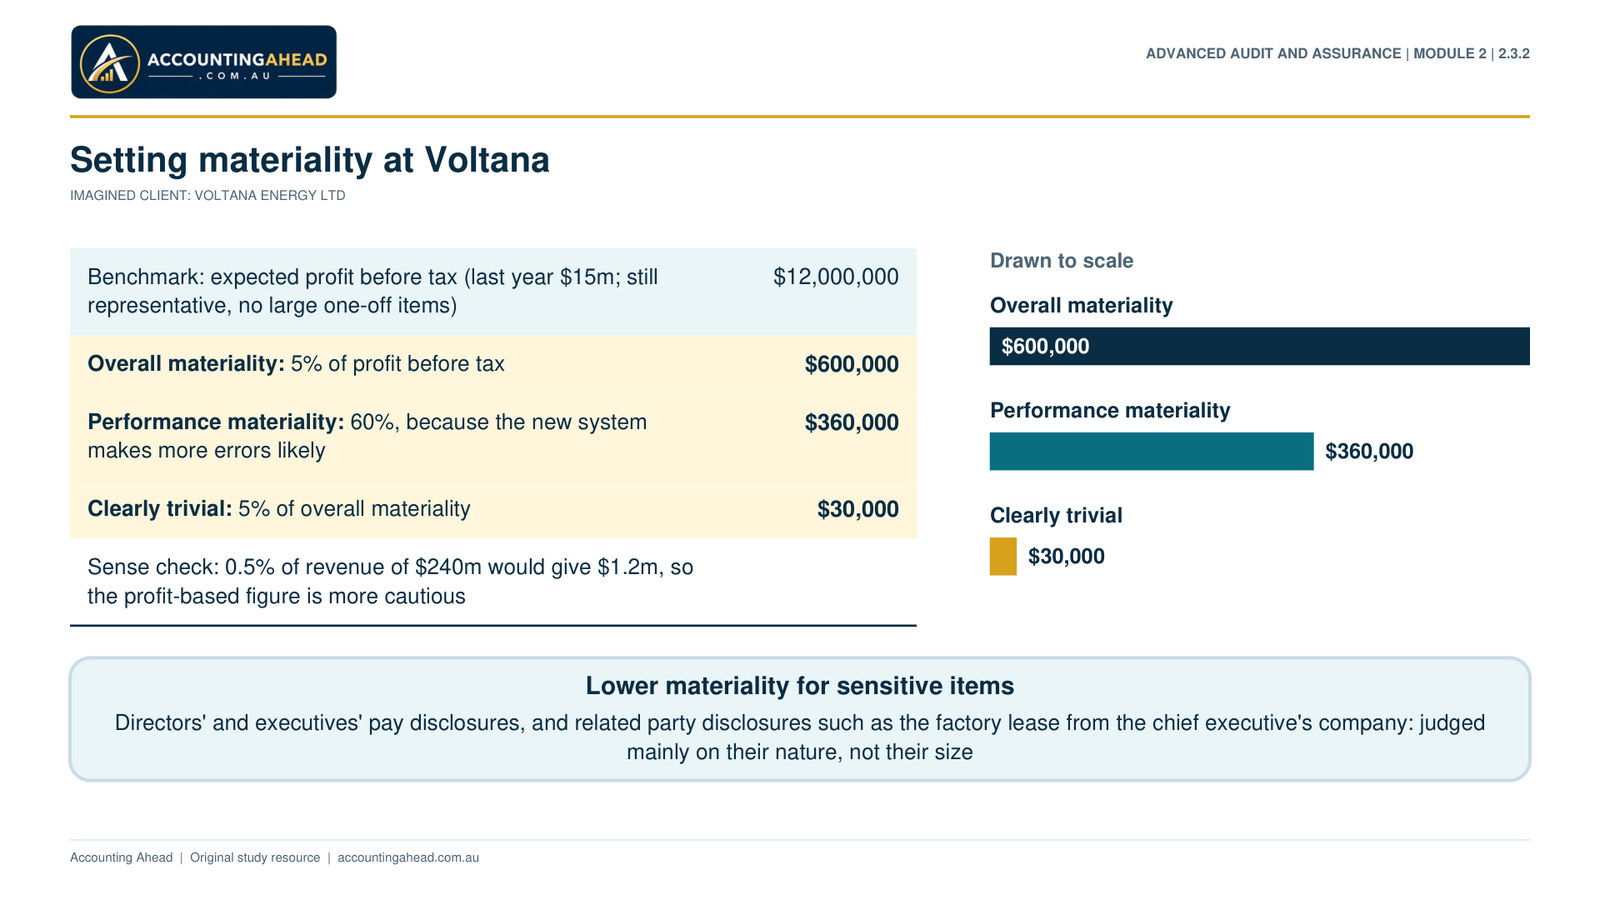
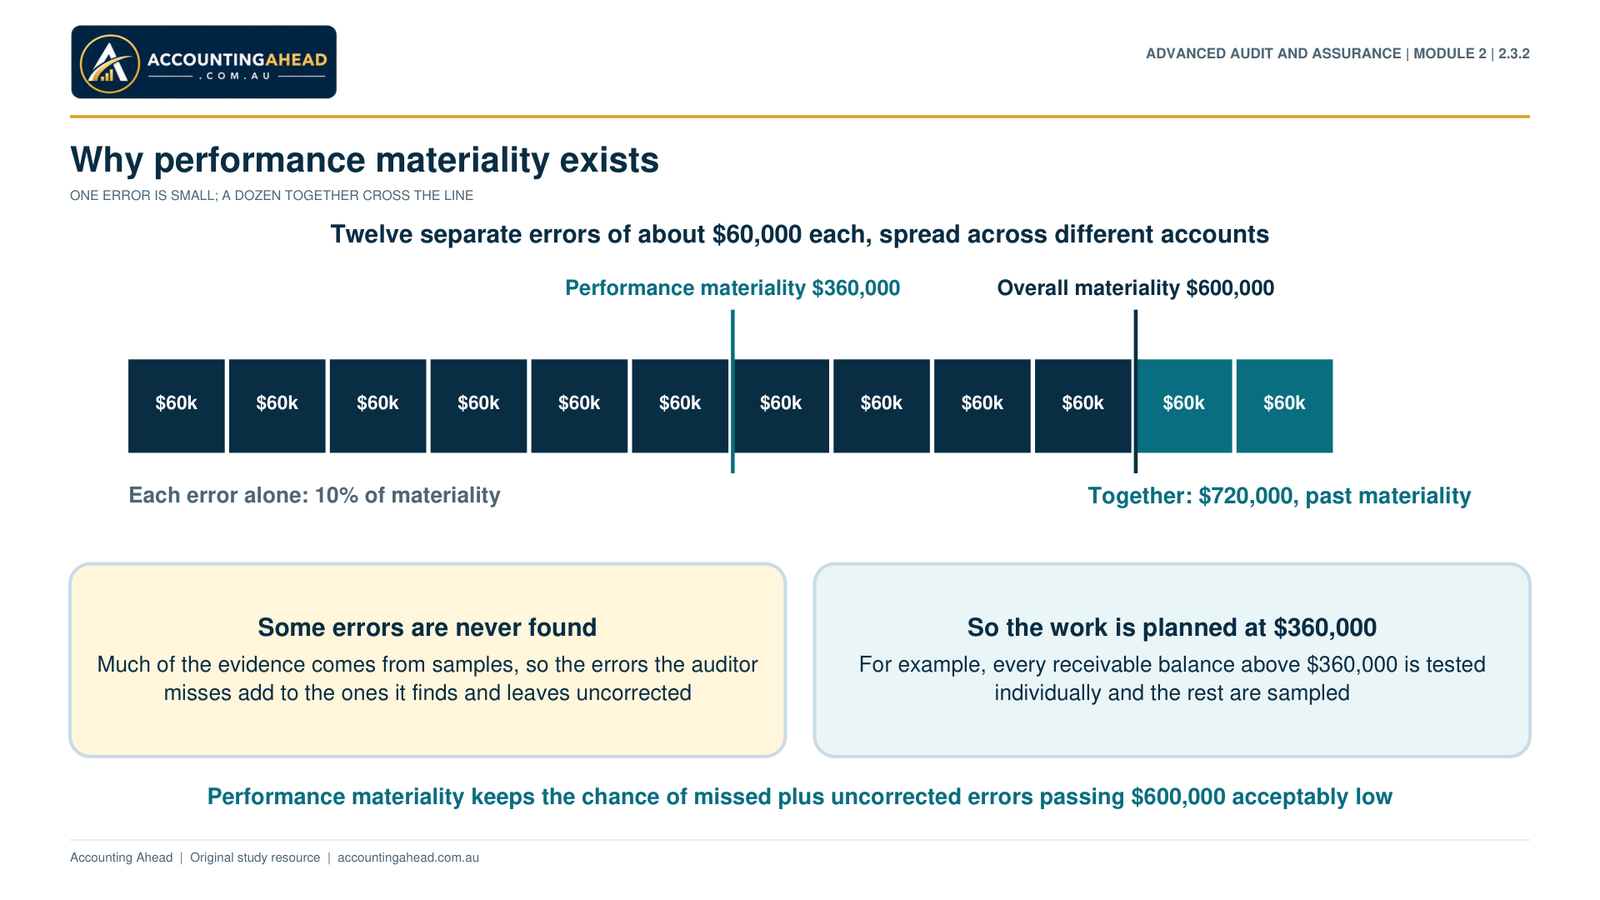
Part 2.3.2 · Materiality and Performance Materiality
Part 2.3.3 · Documentation, Team Discussion and Phases
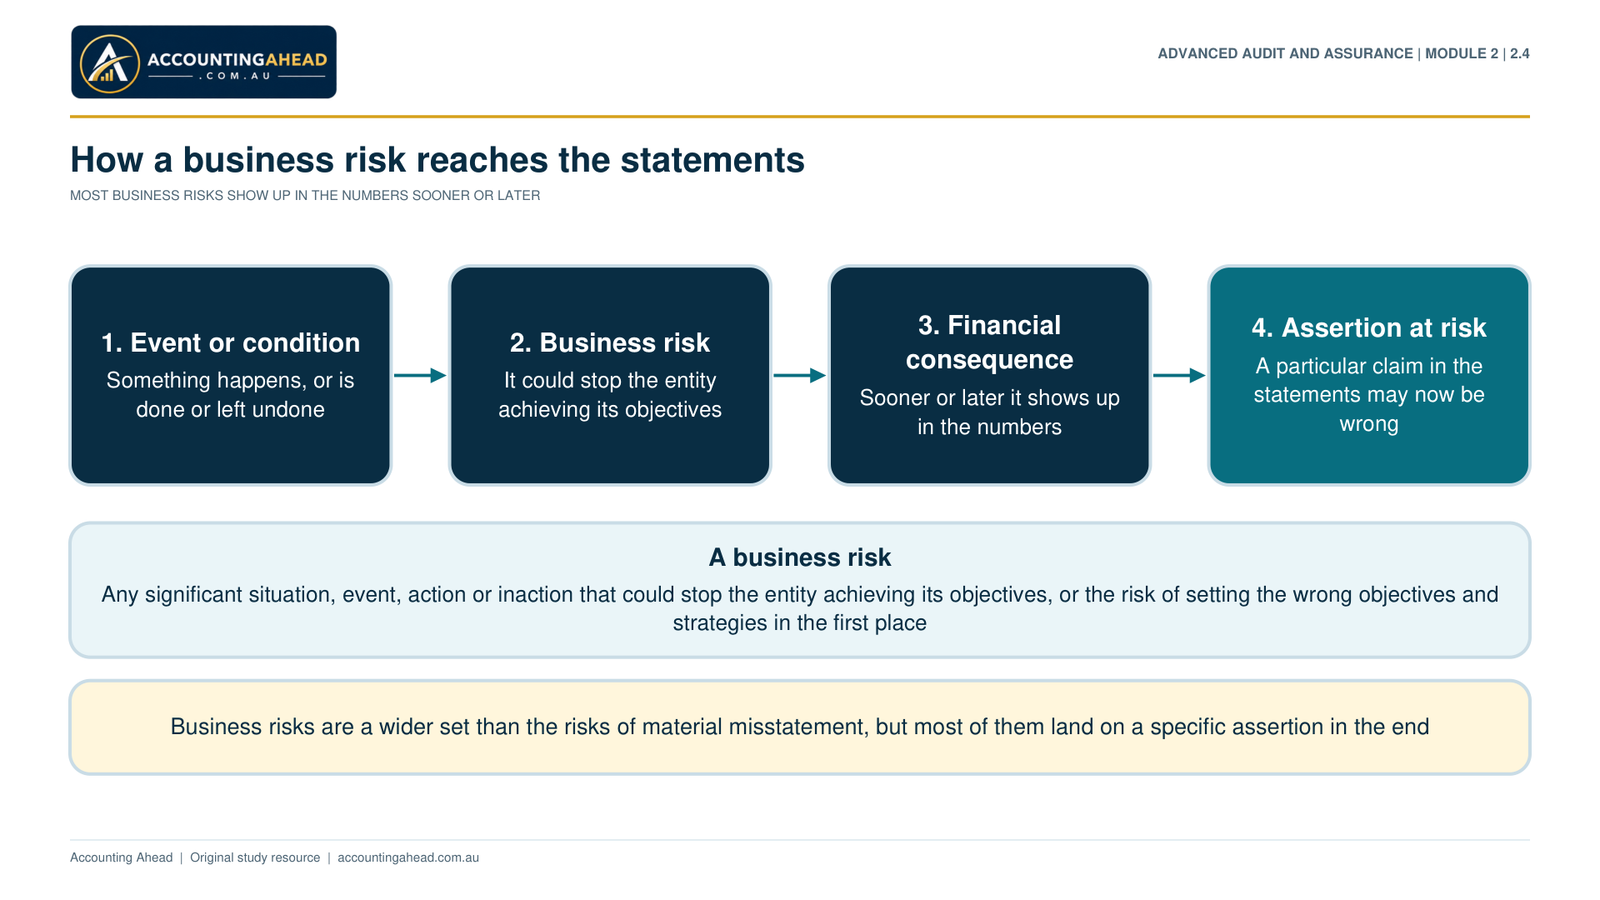
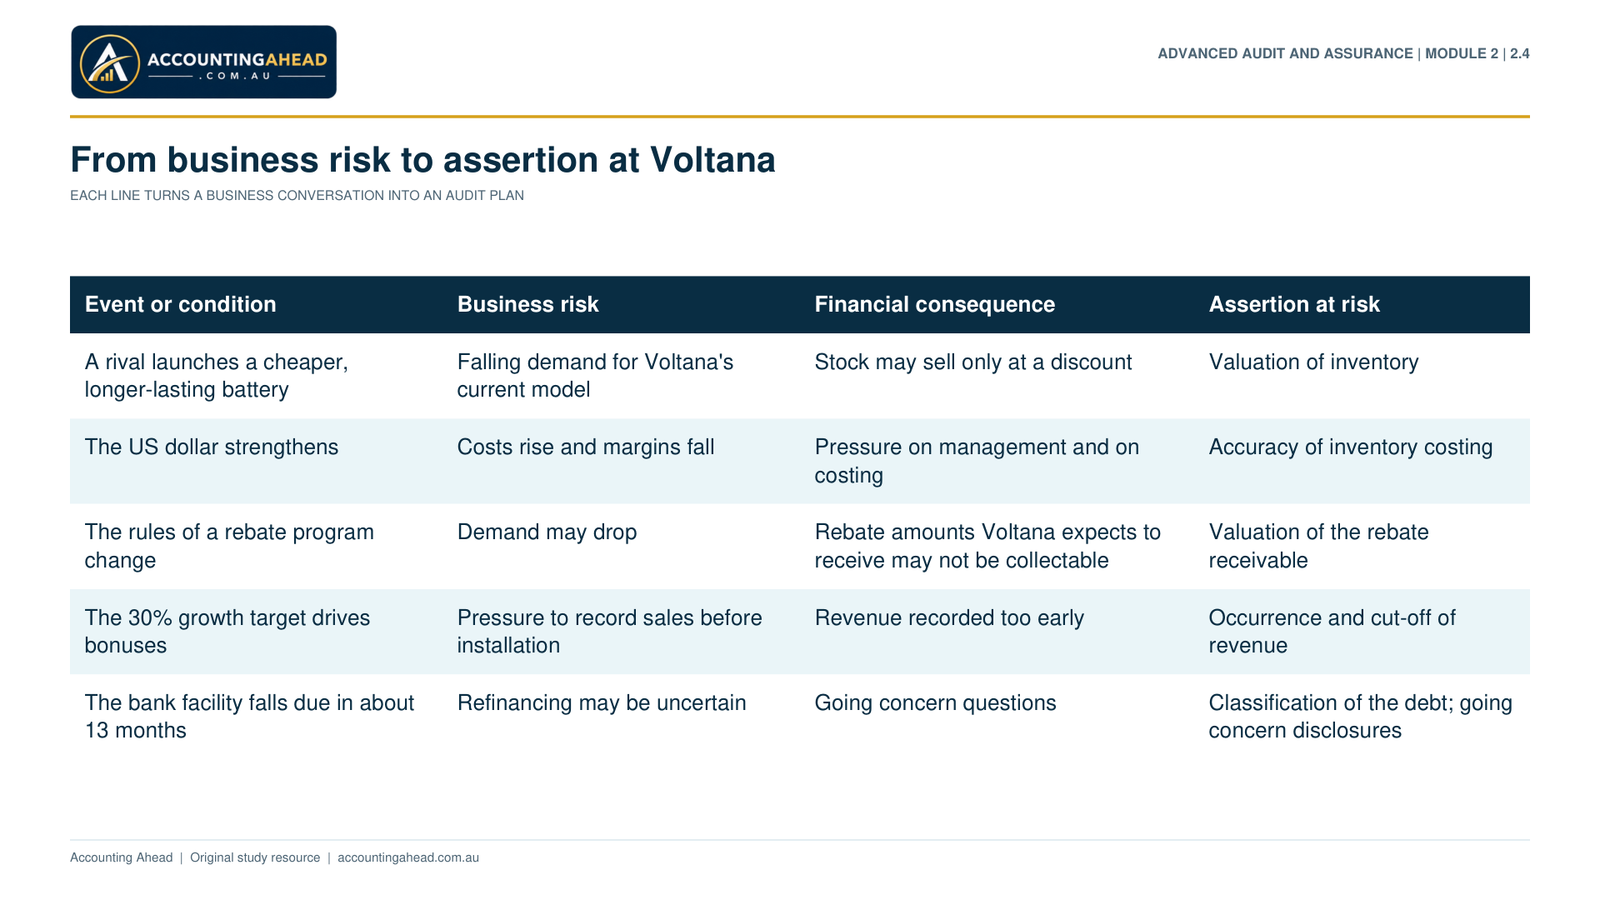
Part 2.4 · Understanding the Entity and Its Environment
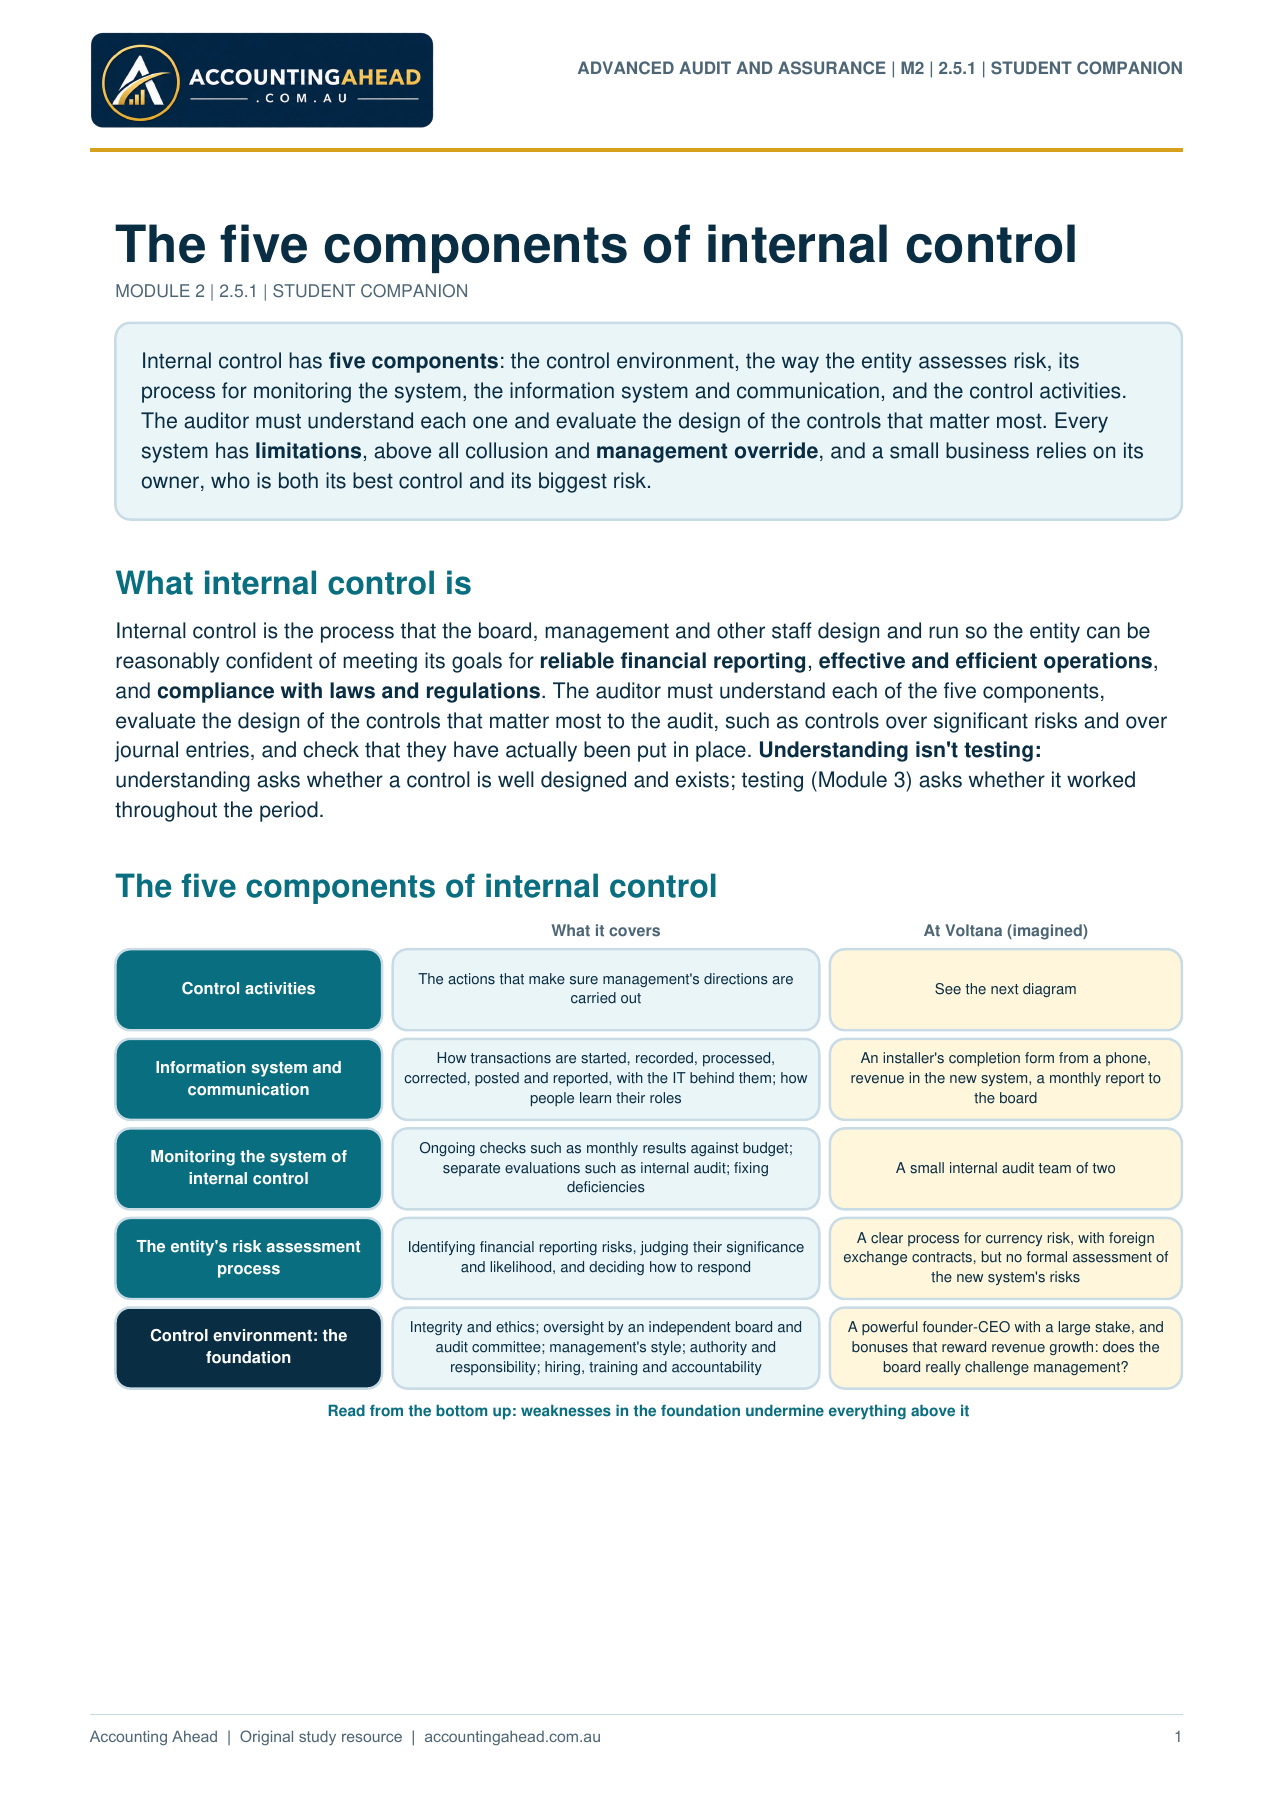
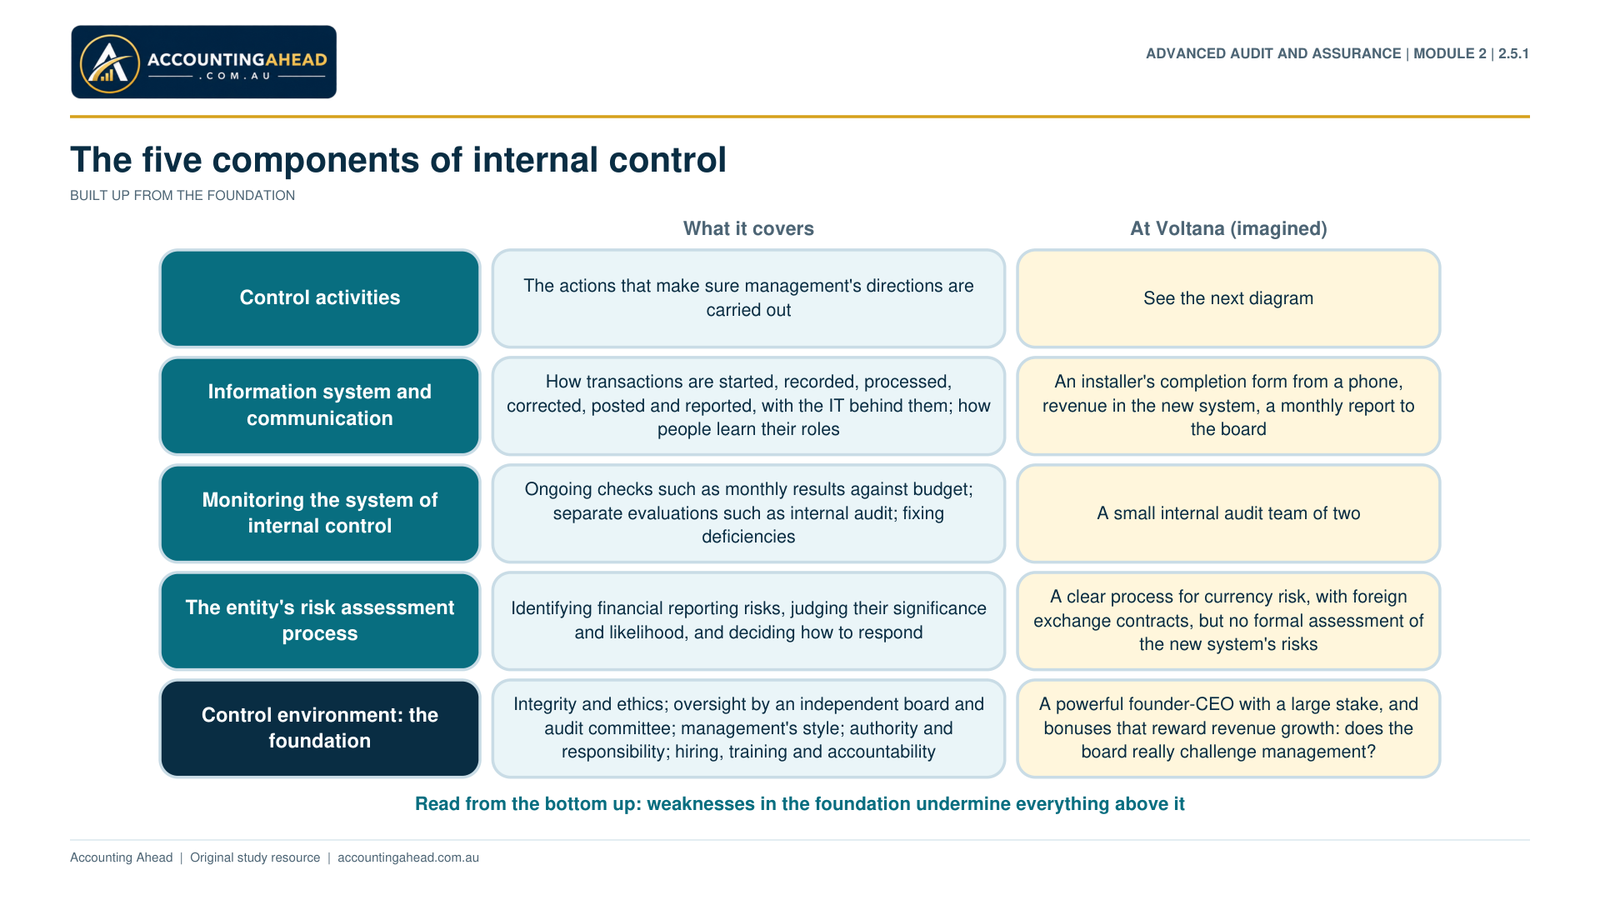
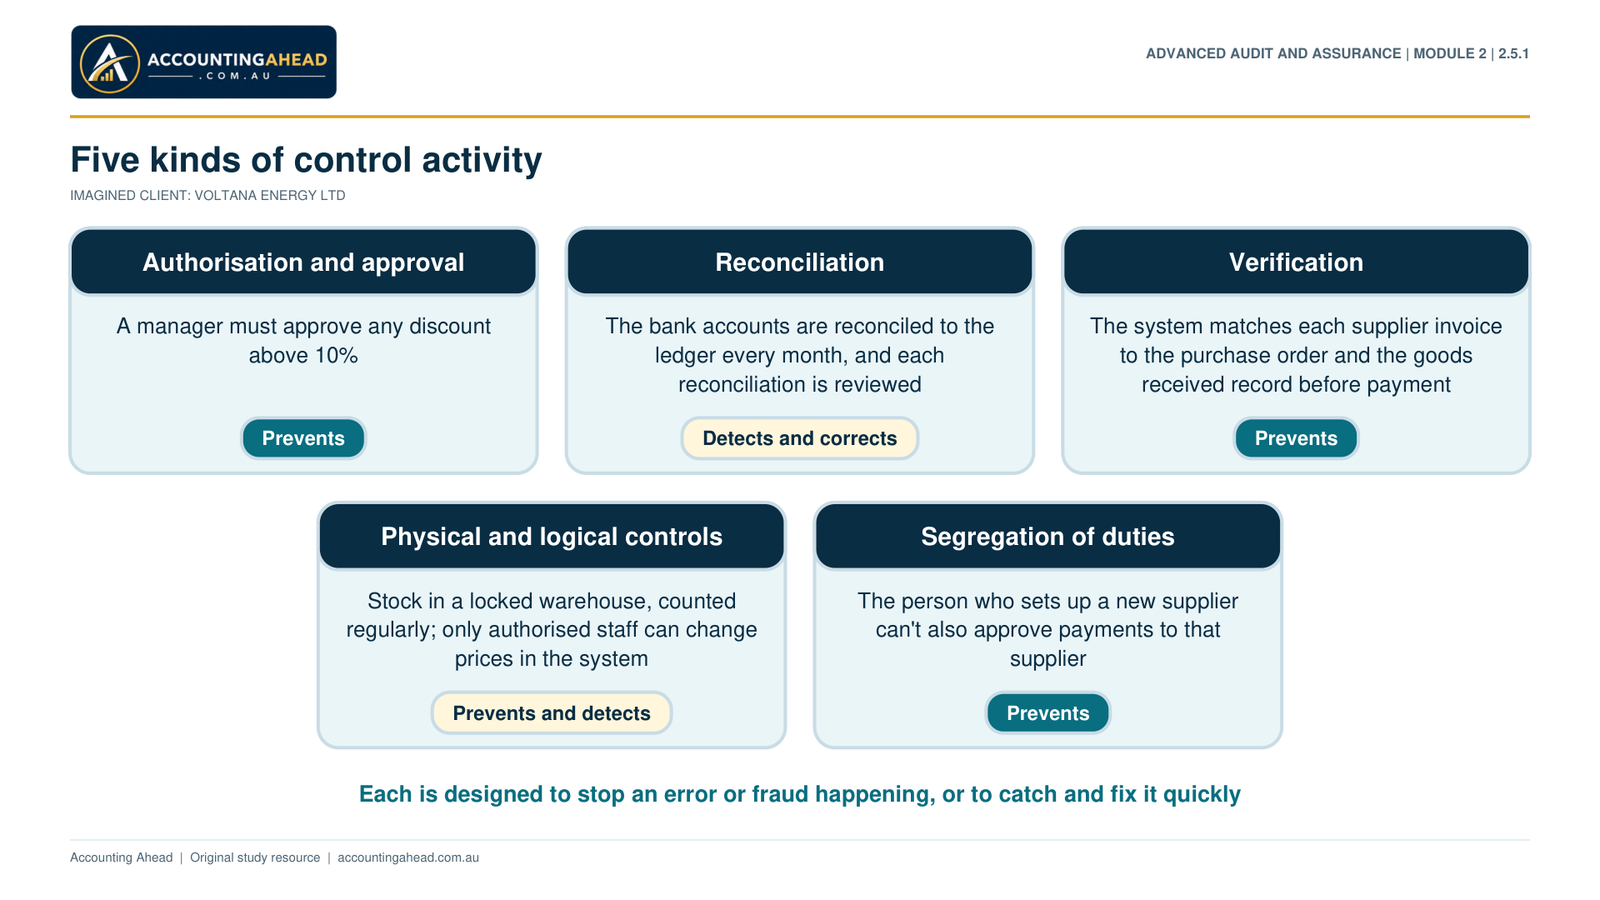
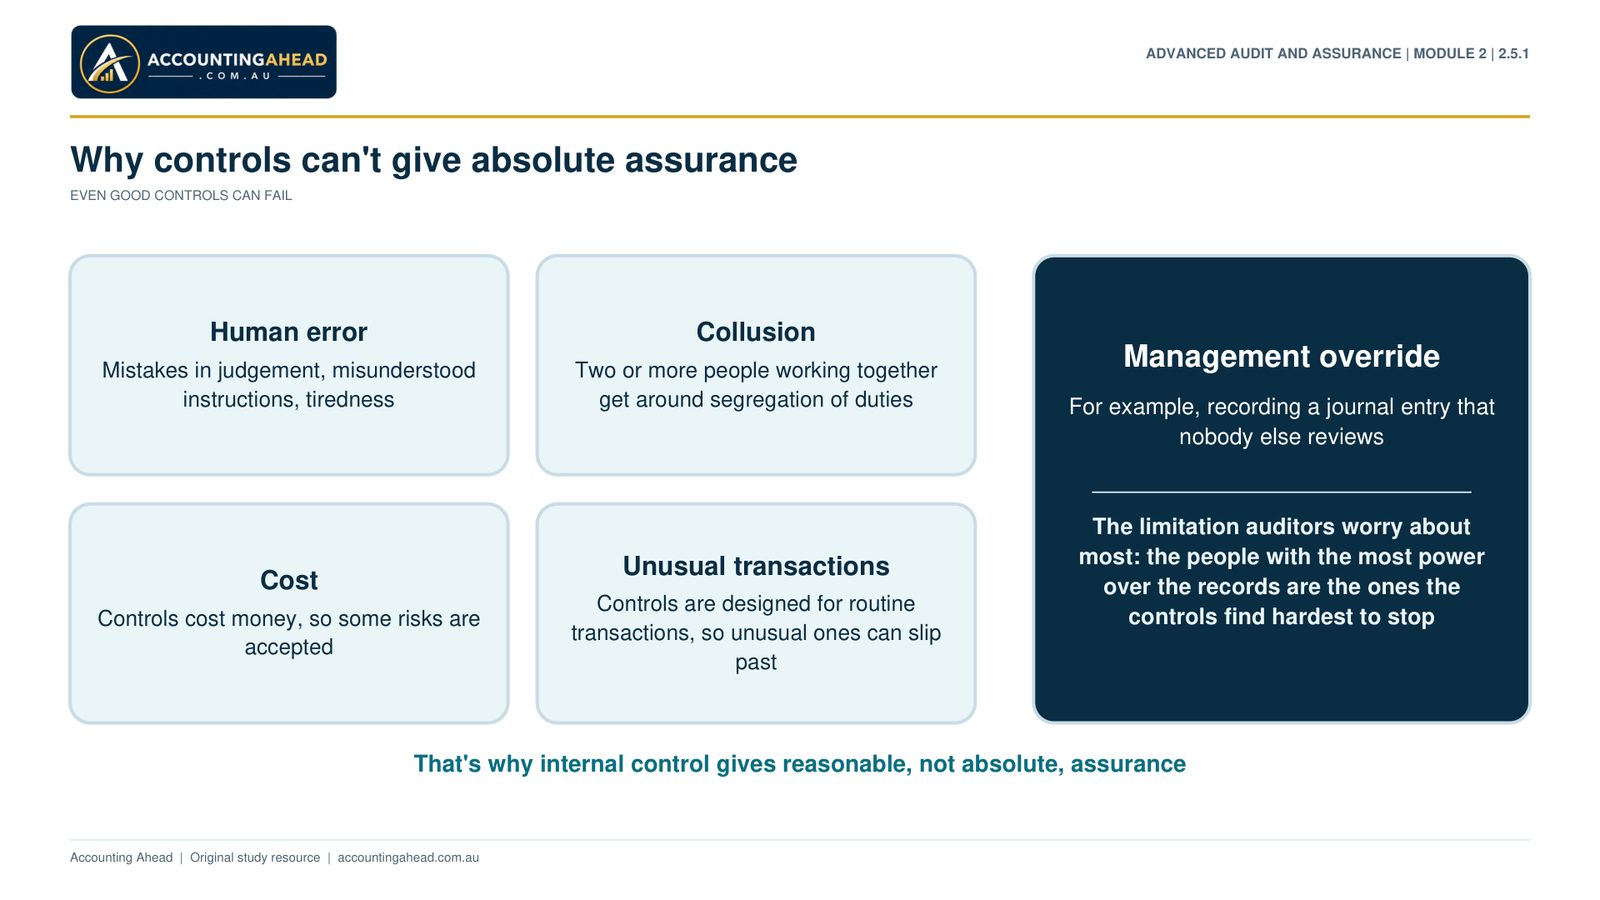
Part 2.5.1 · The Five Components of Internal Control
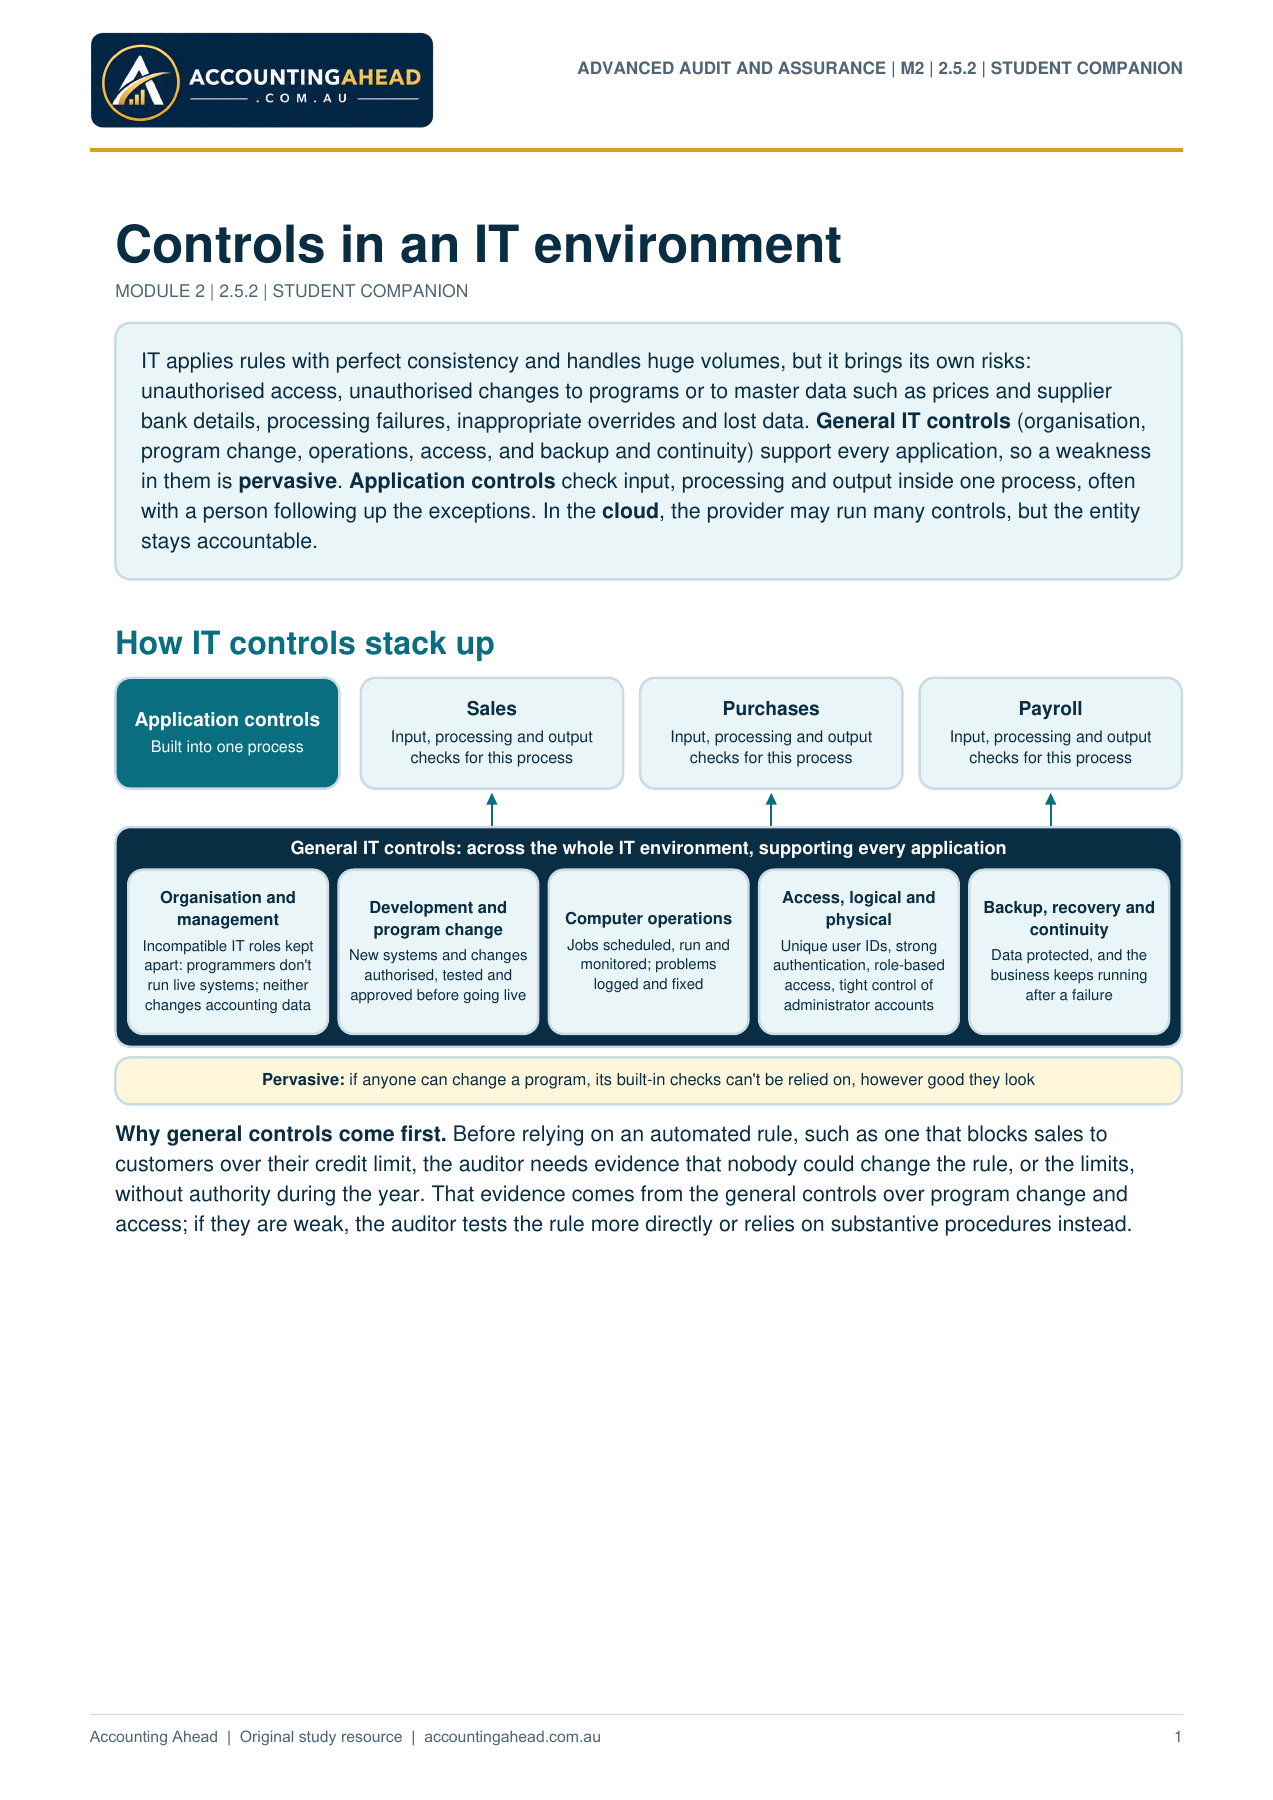
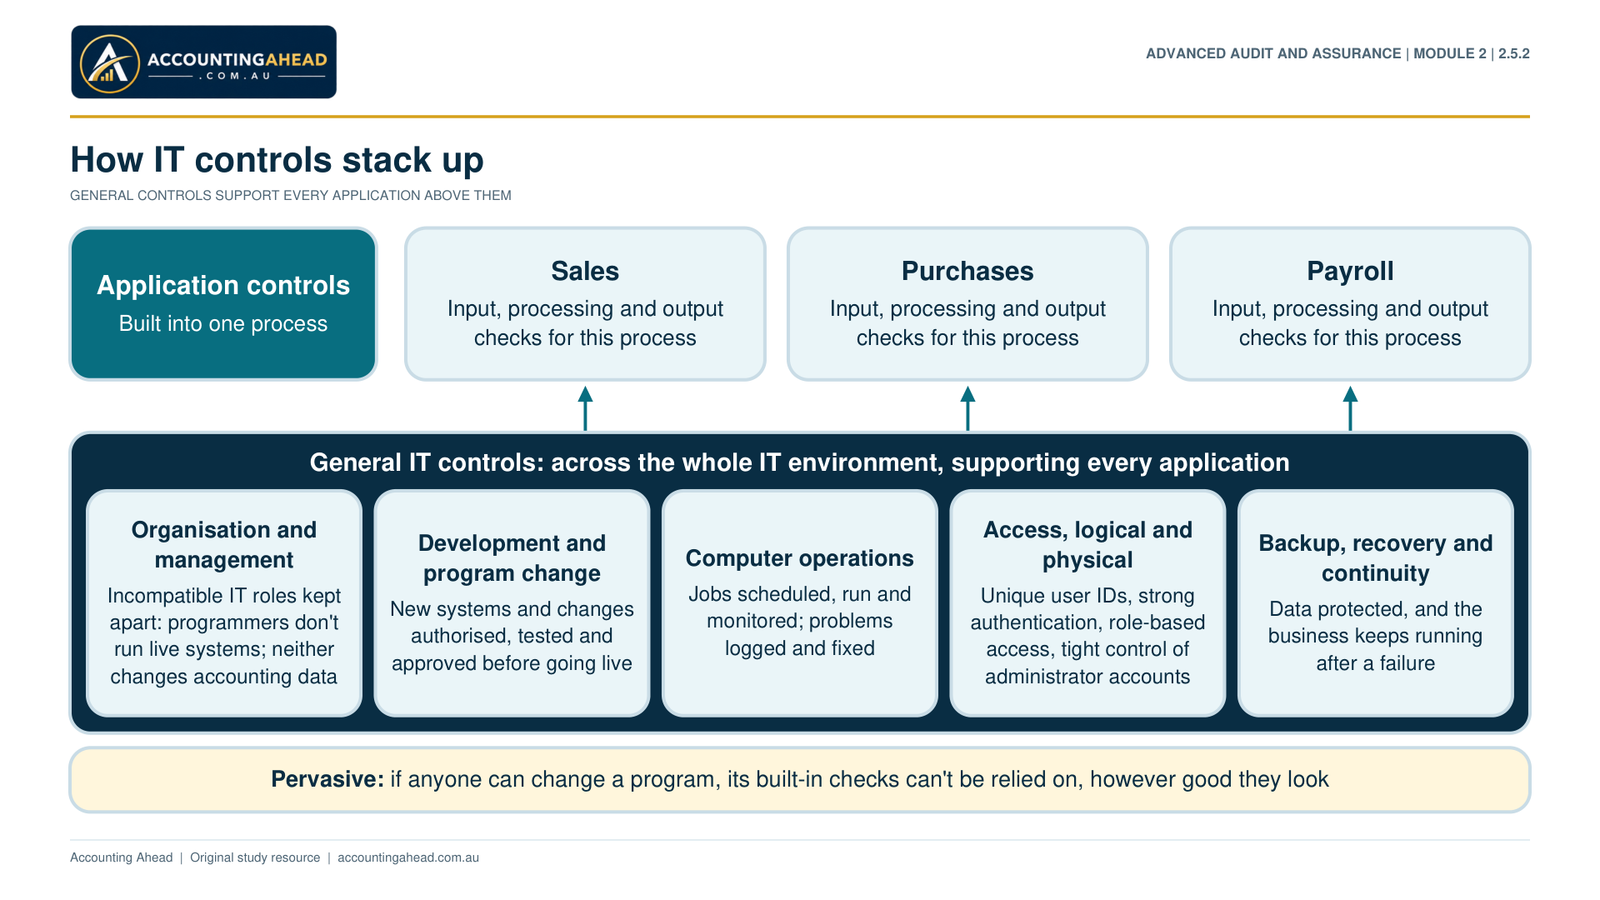
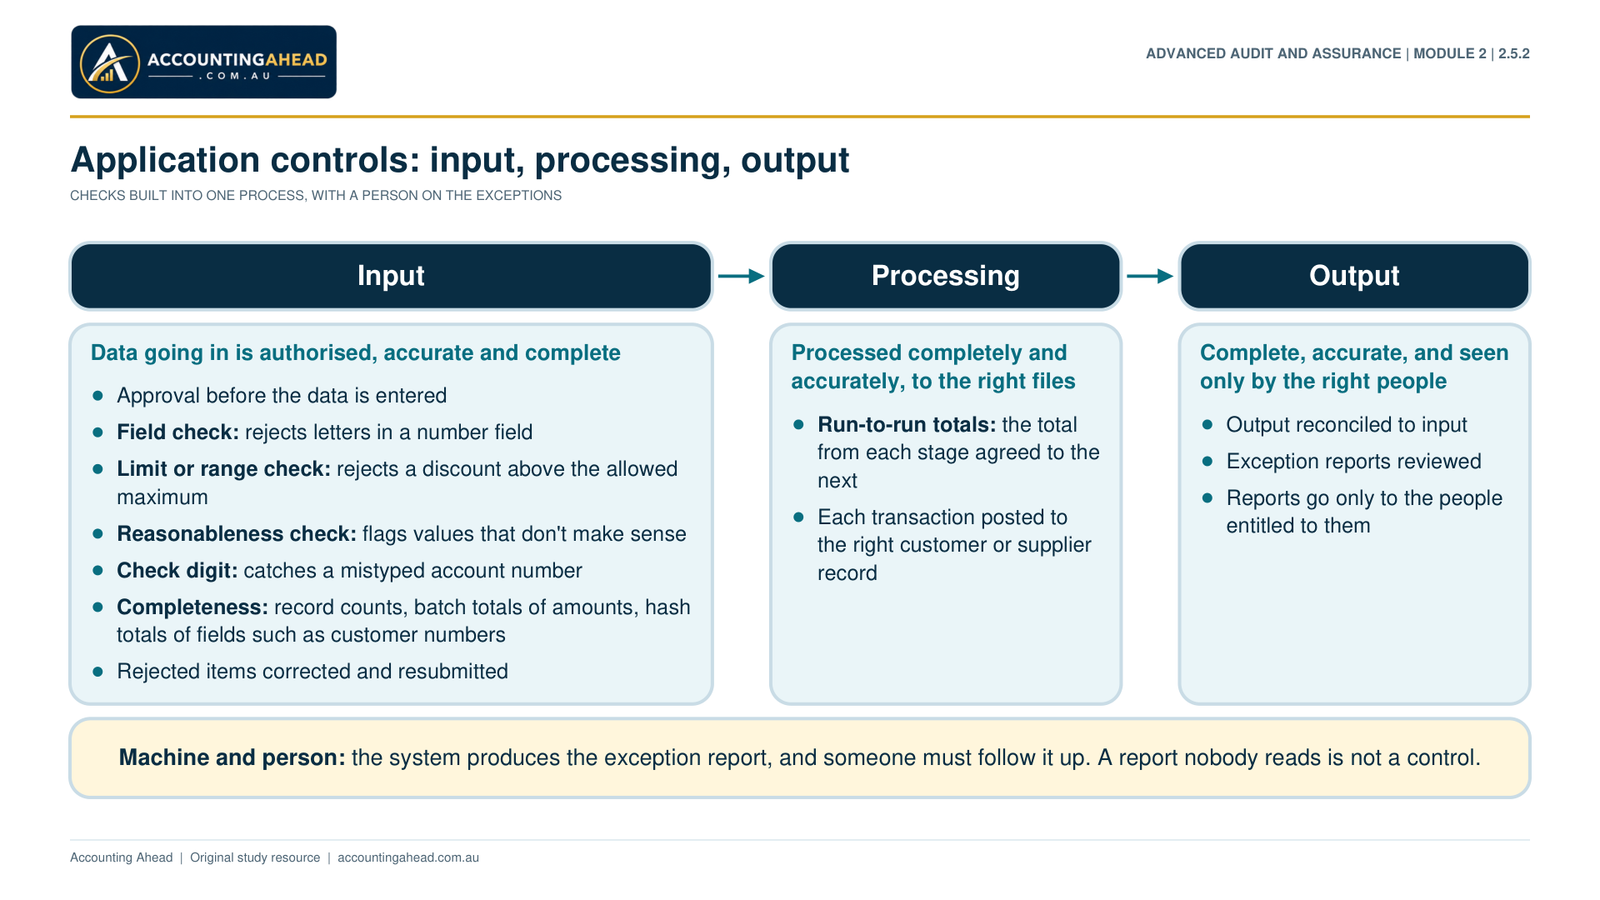
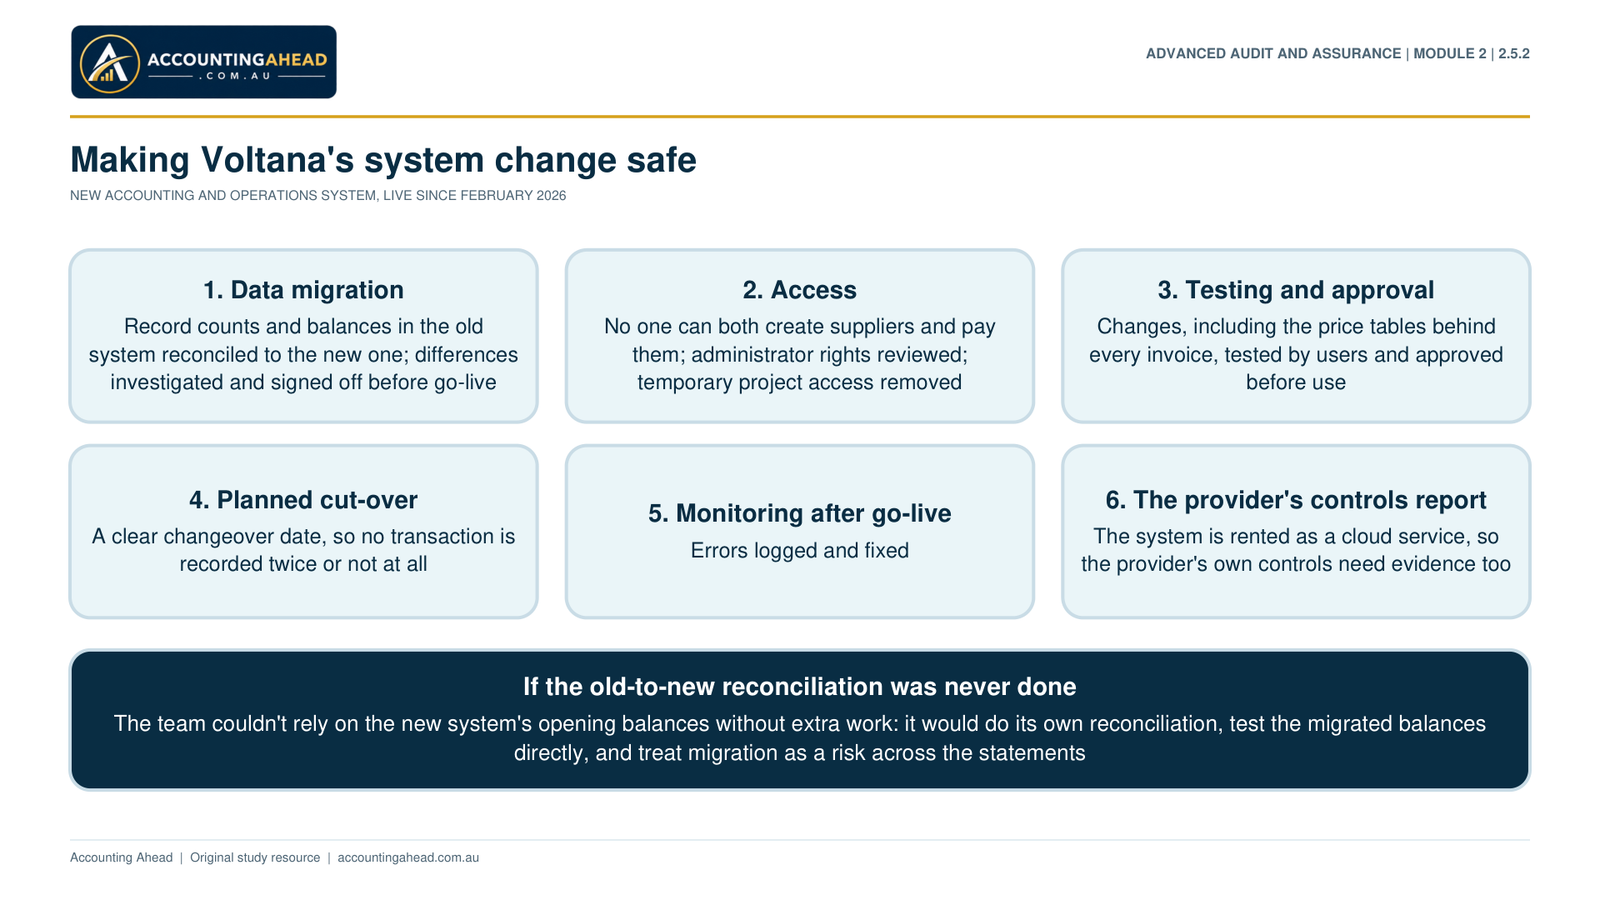
Part 2.5.2 · Controls in an IT Environment
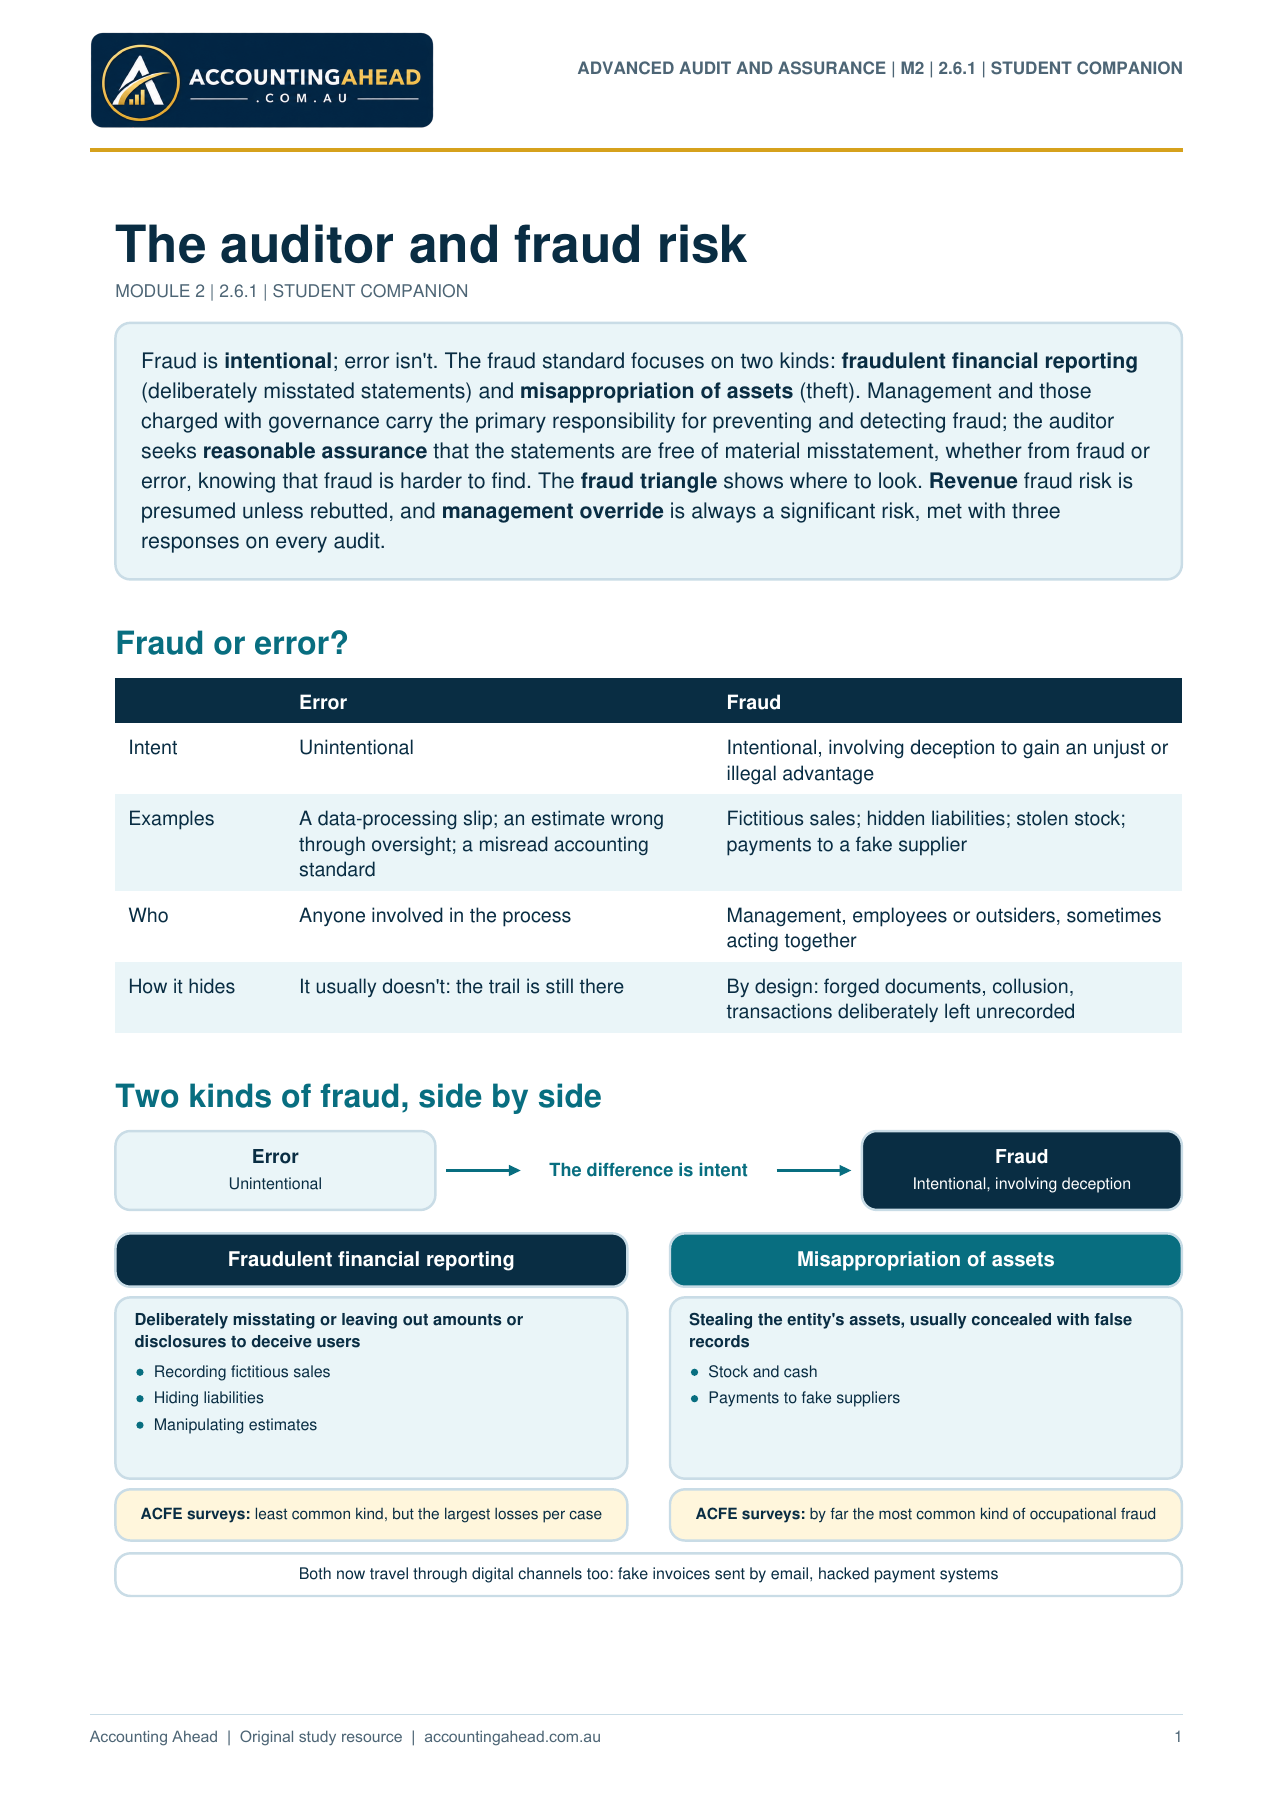
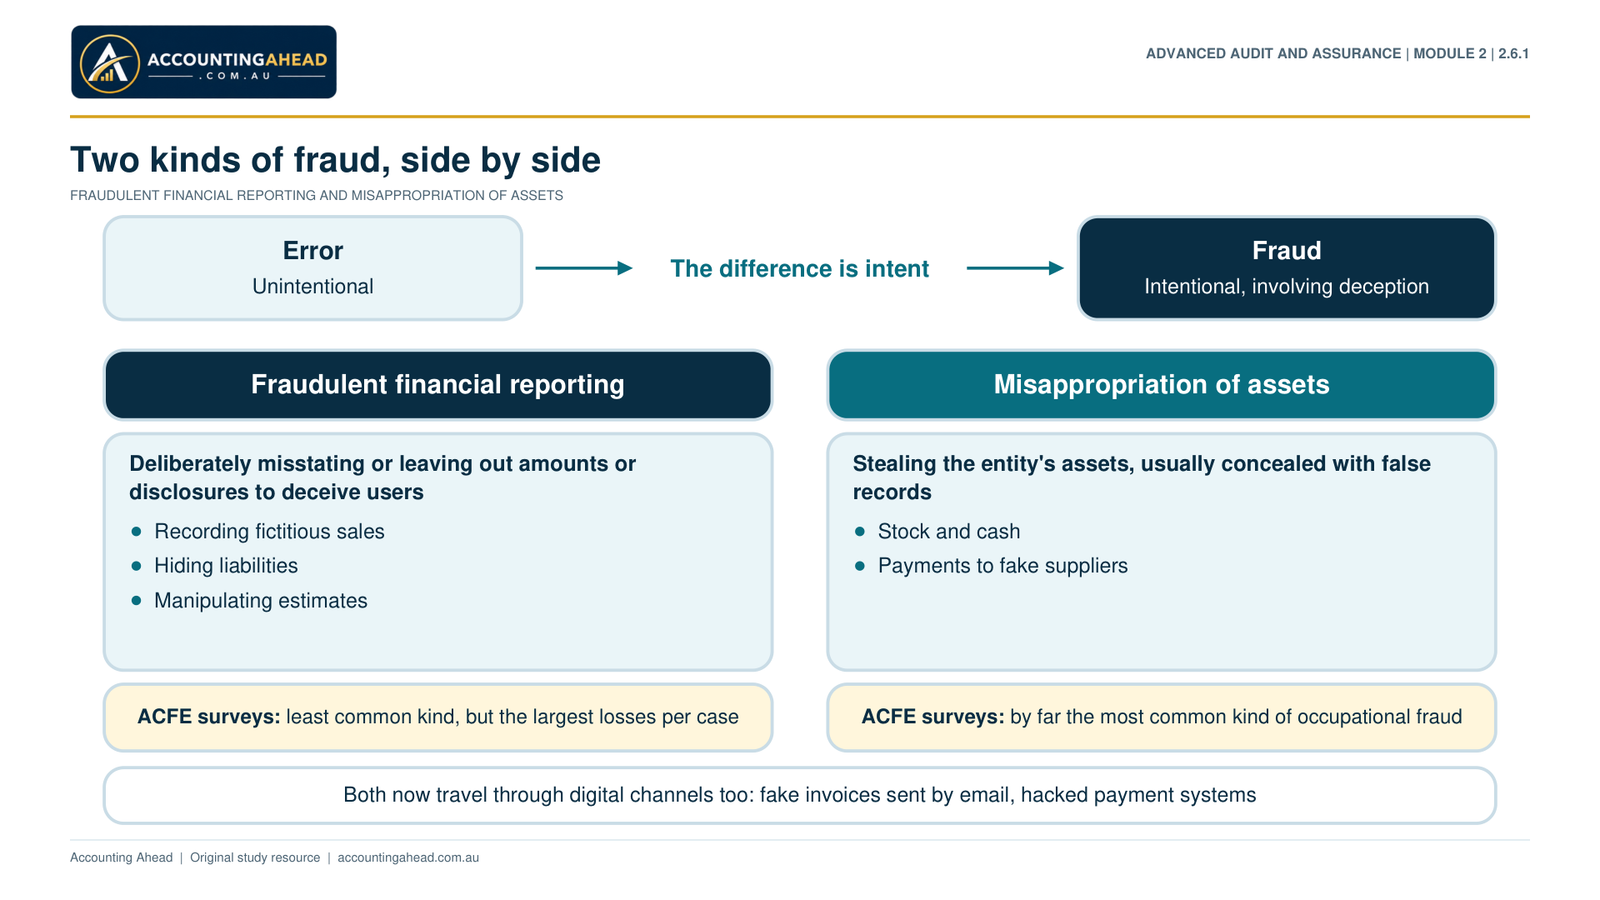
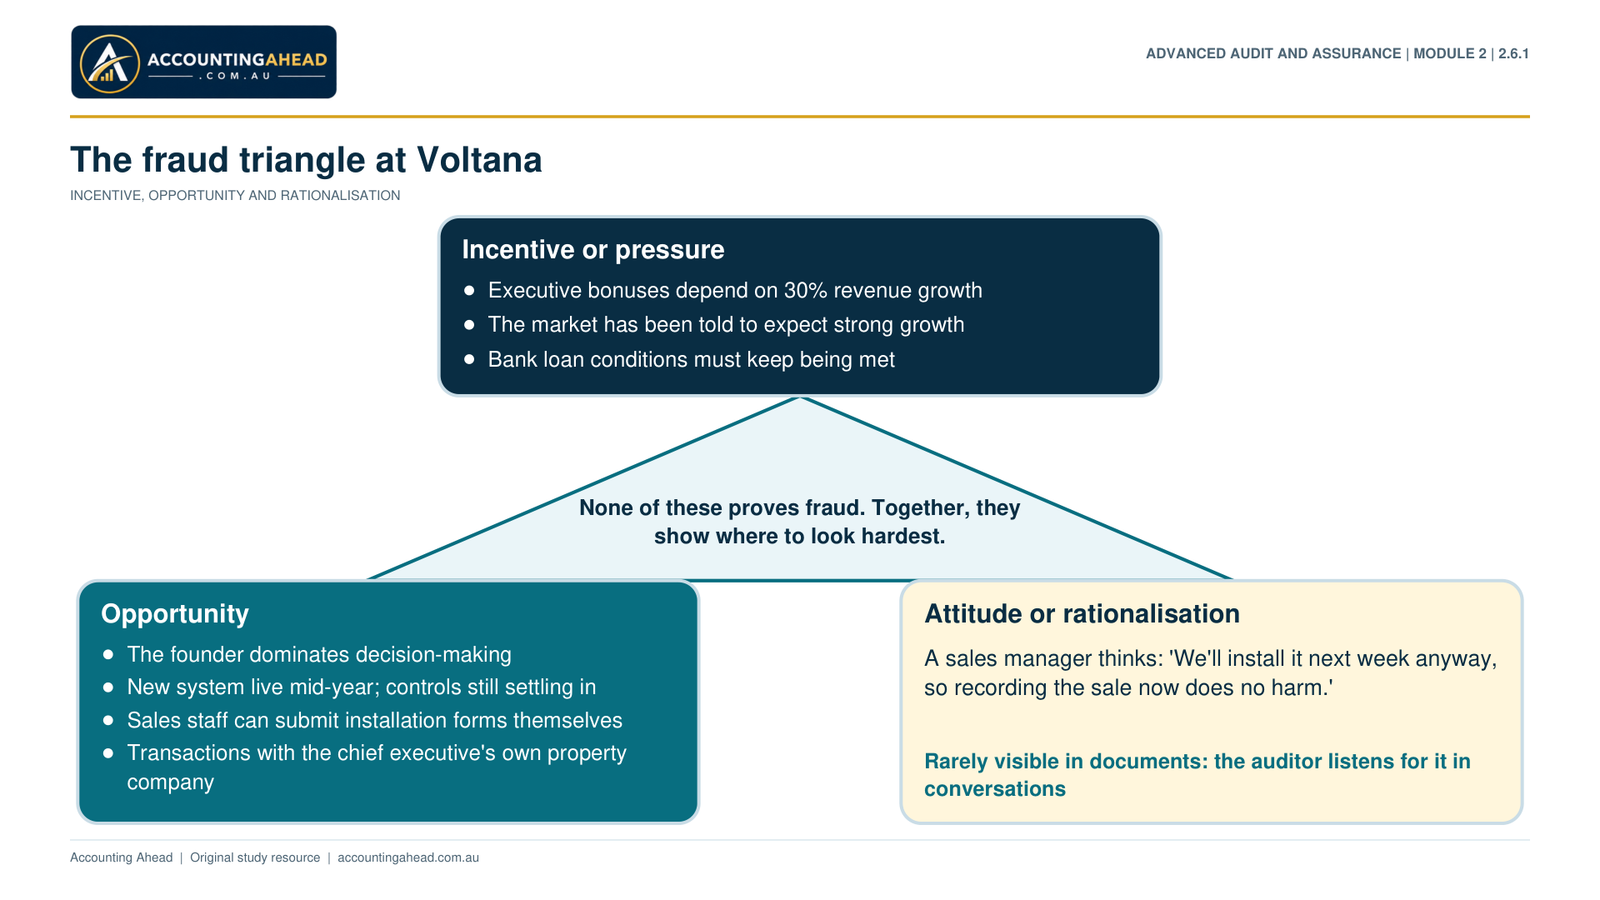
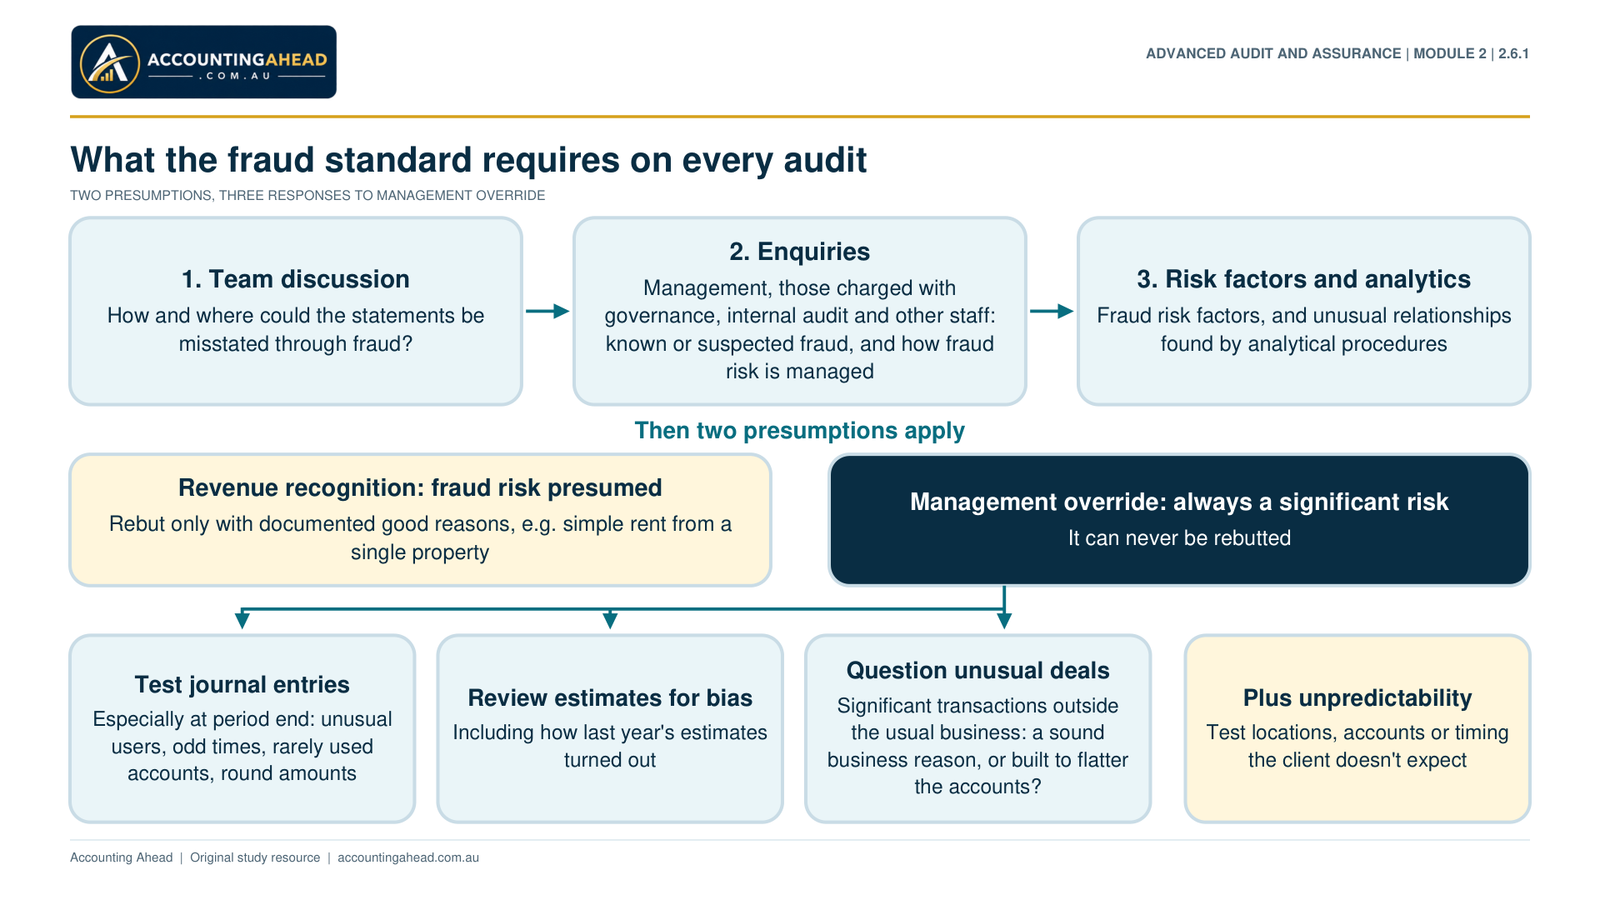
Part 2.6.1 · The Auditor and Fraud Risk
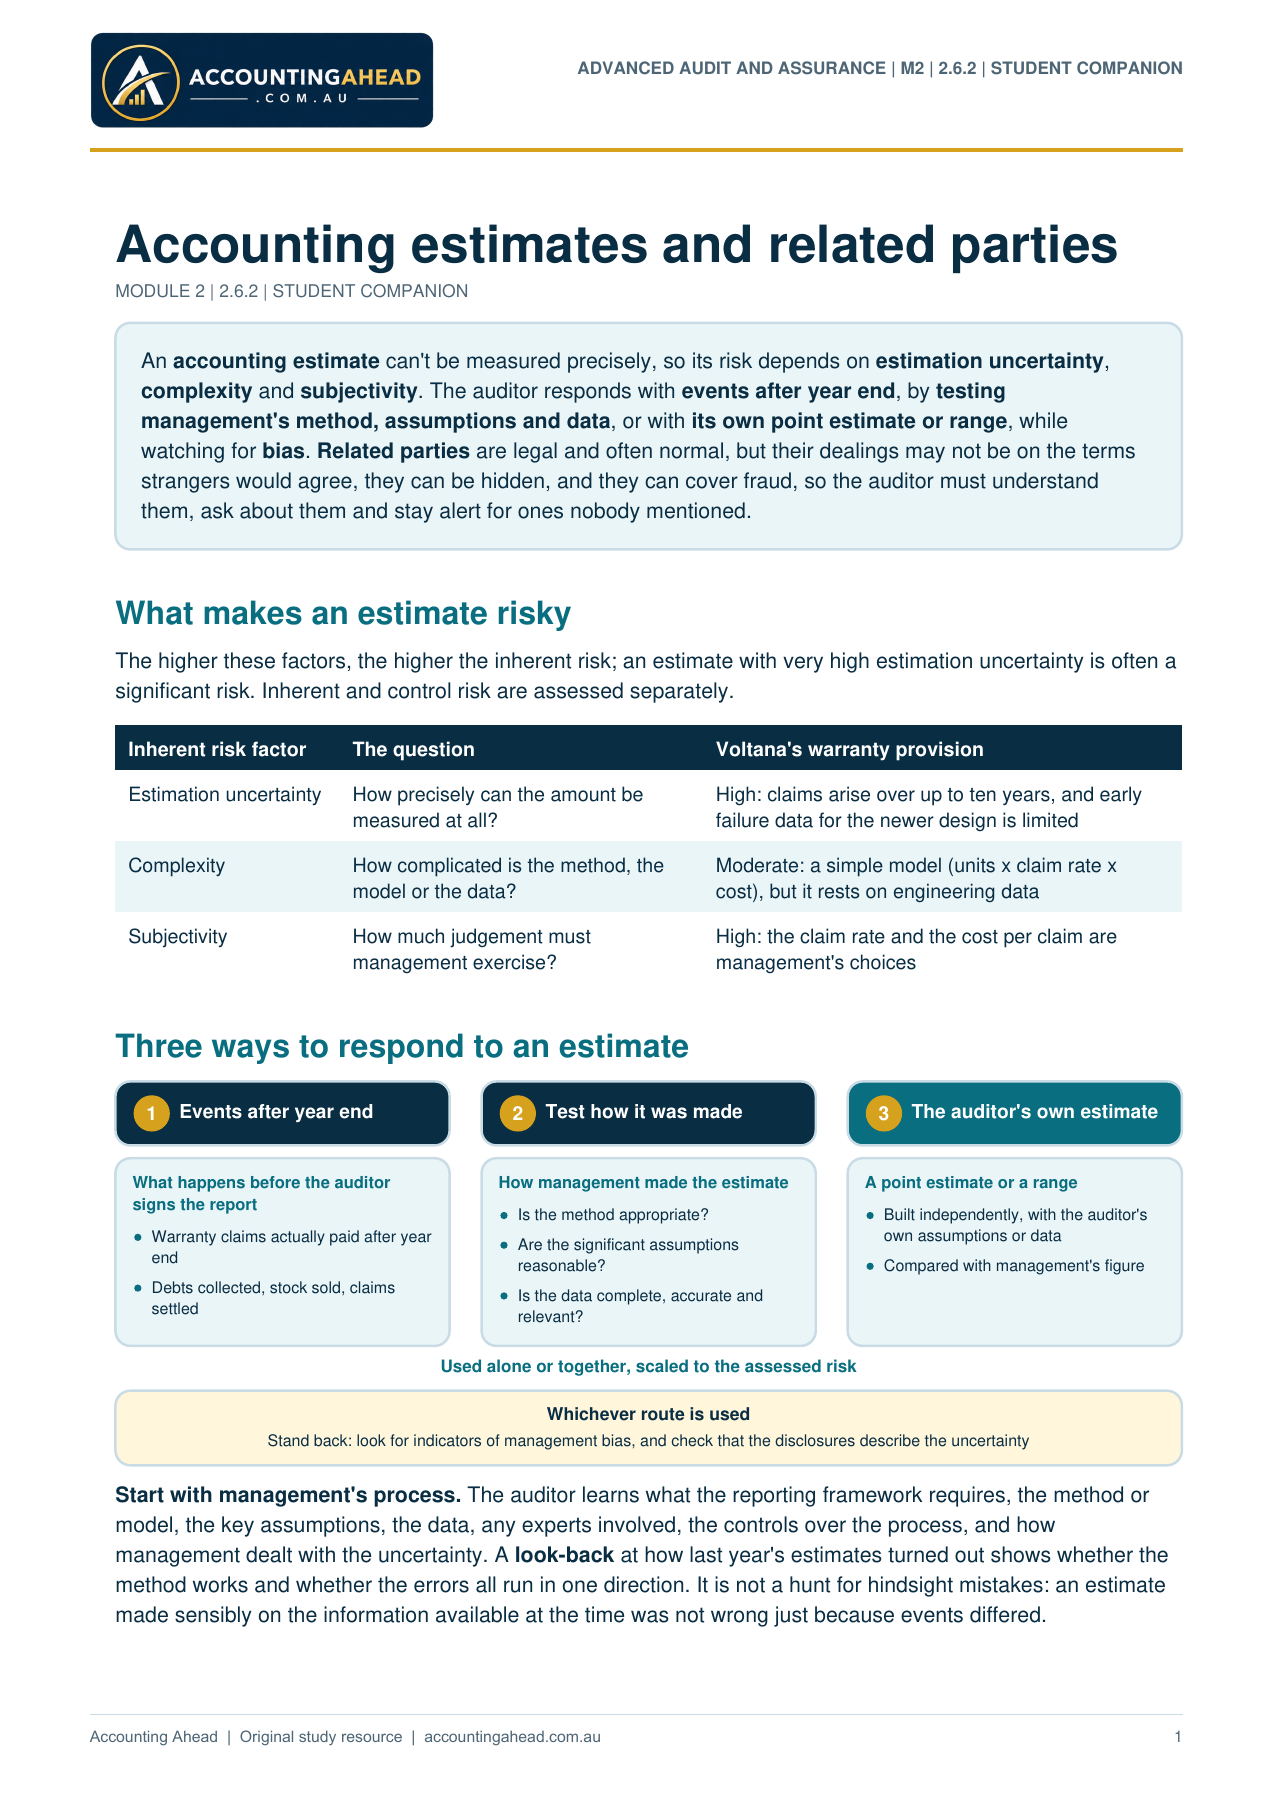
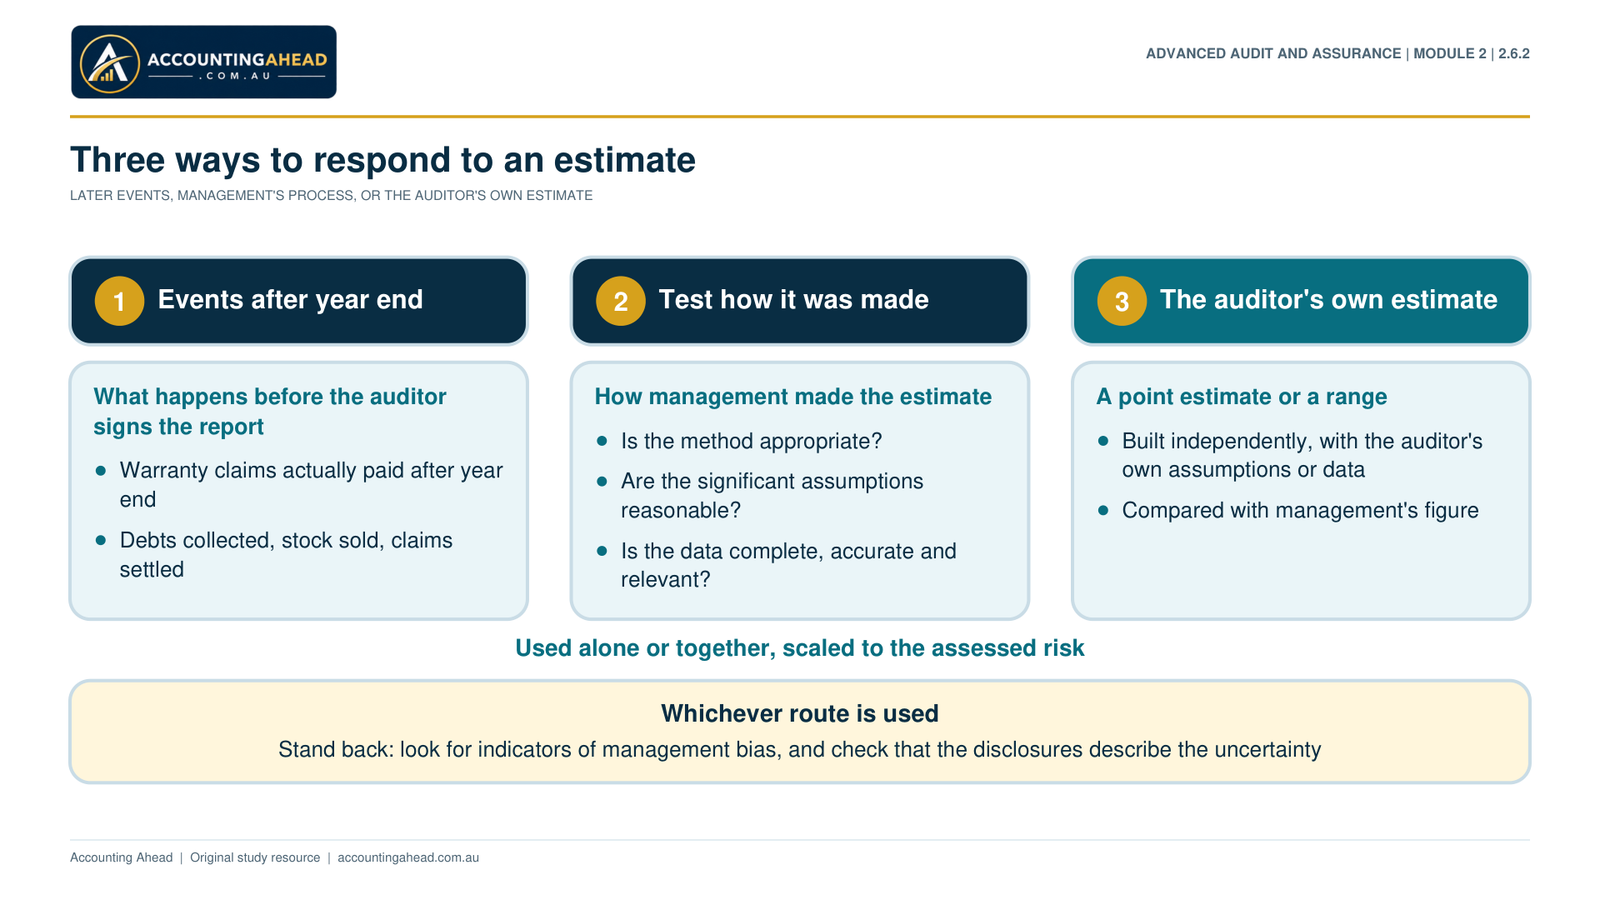
Part 2.6.2 · Accounting Estimates and Related Parties
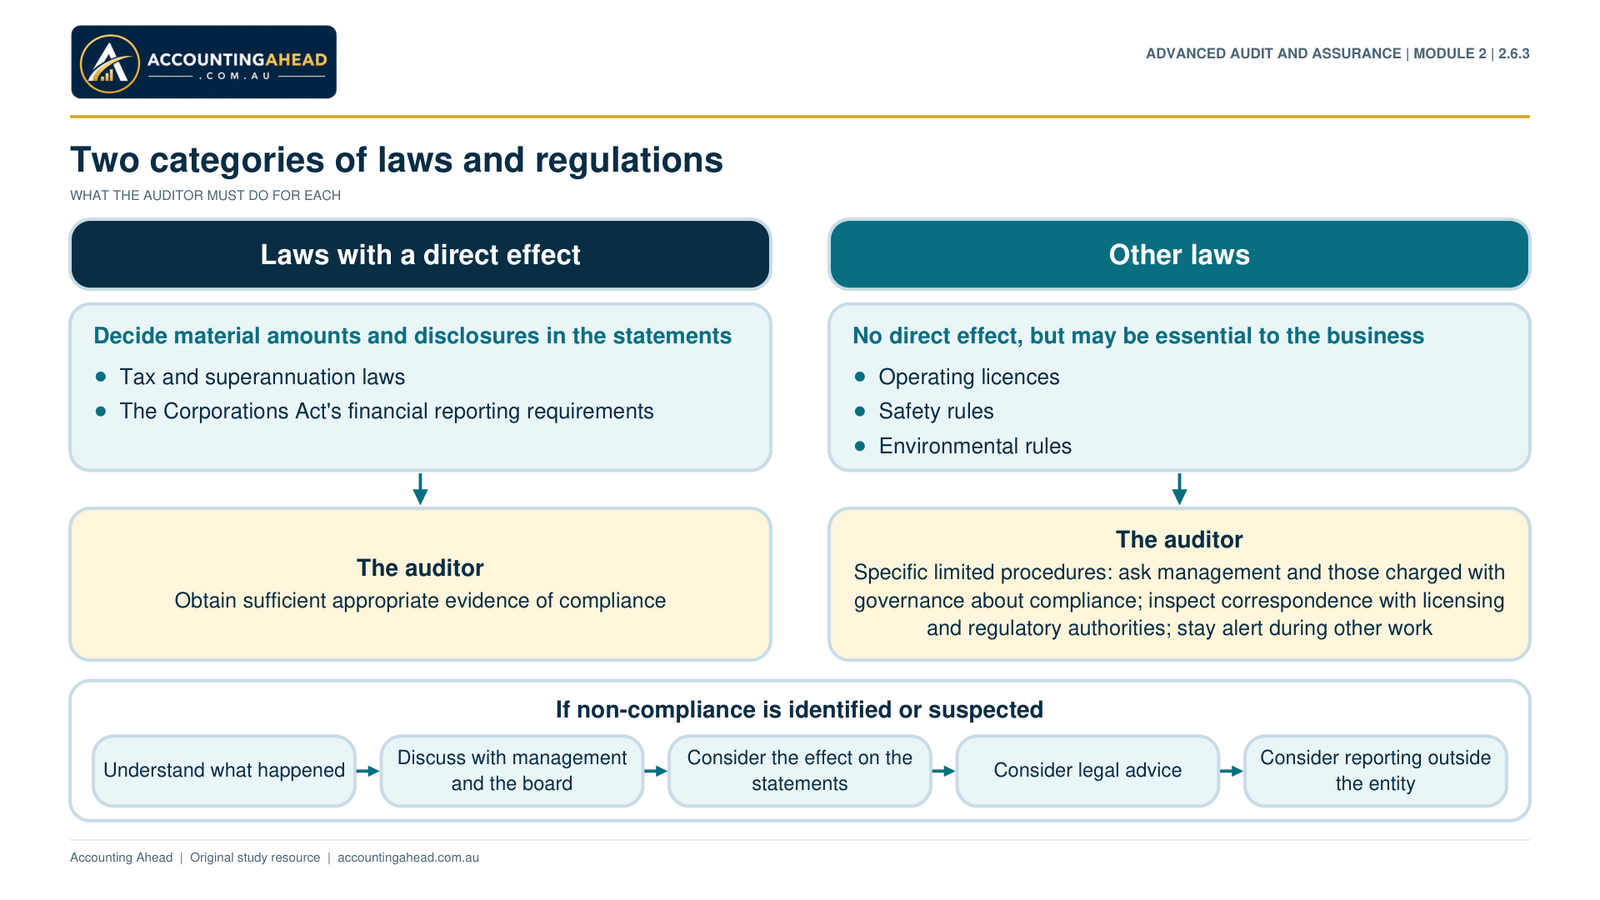
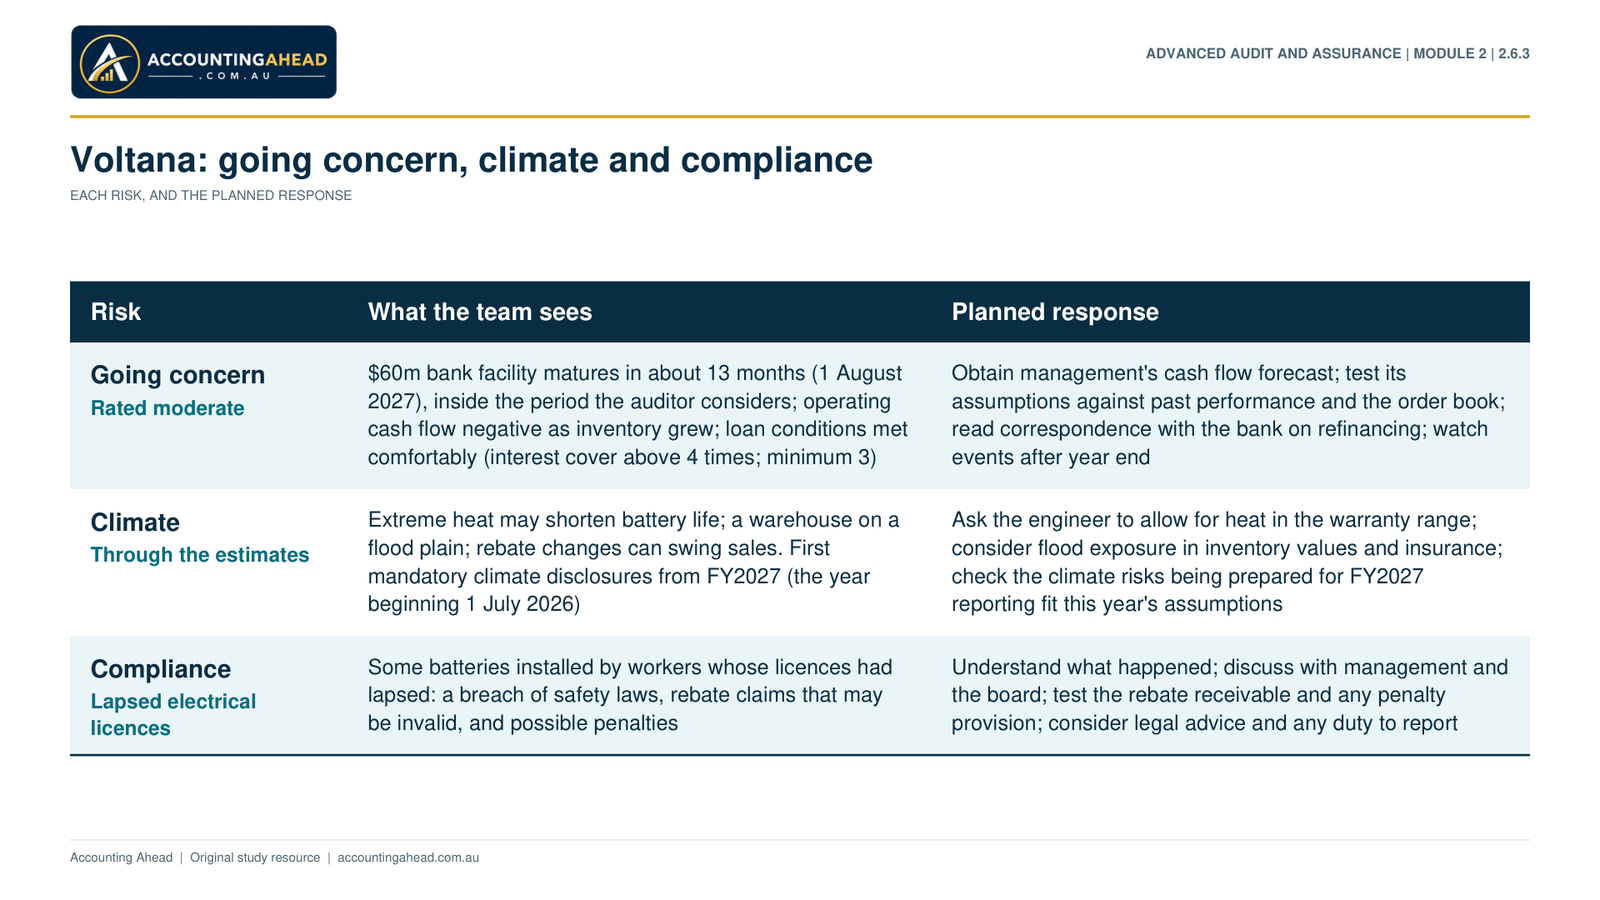
Part 2.6.3 · Going Concern, Climate and NOCLAR Risks
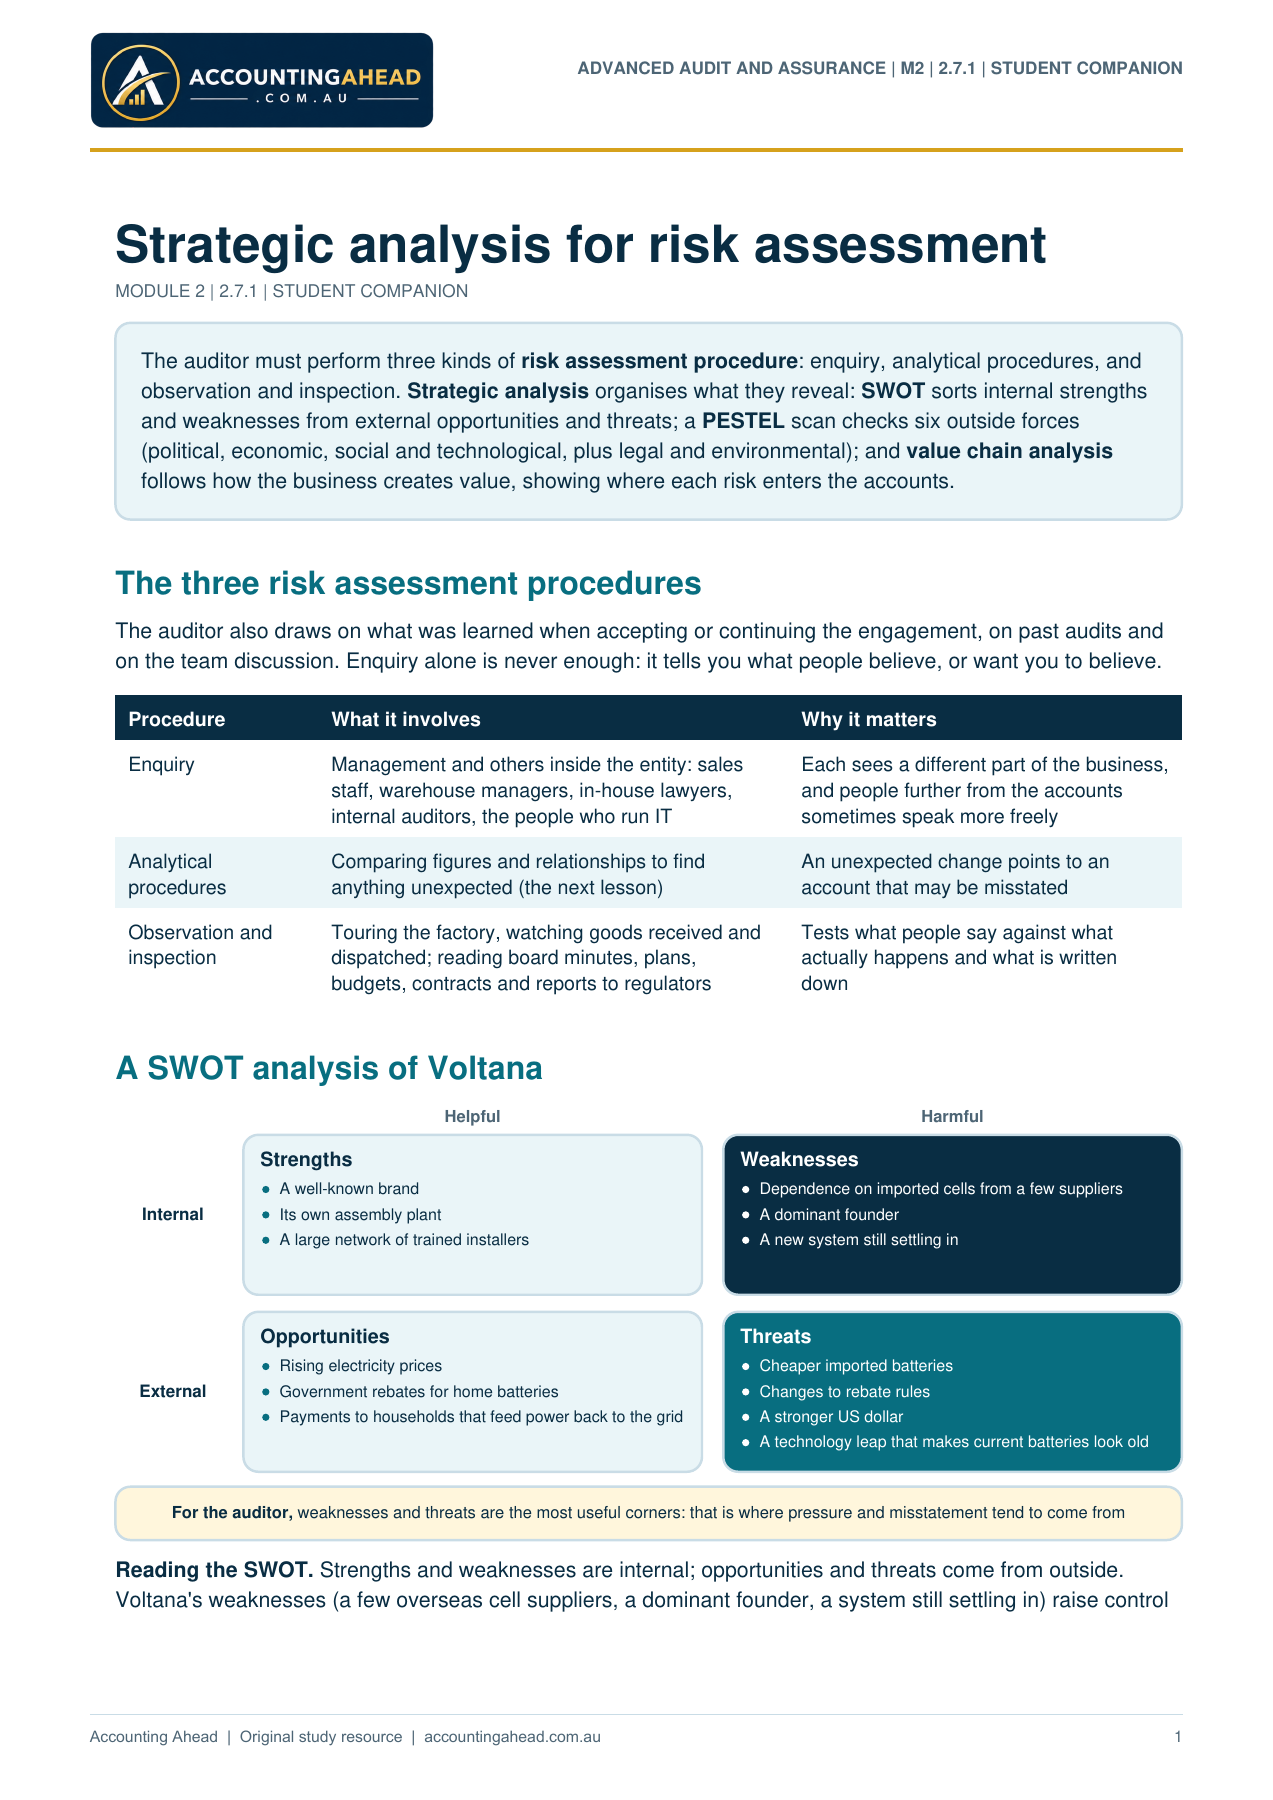
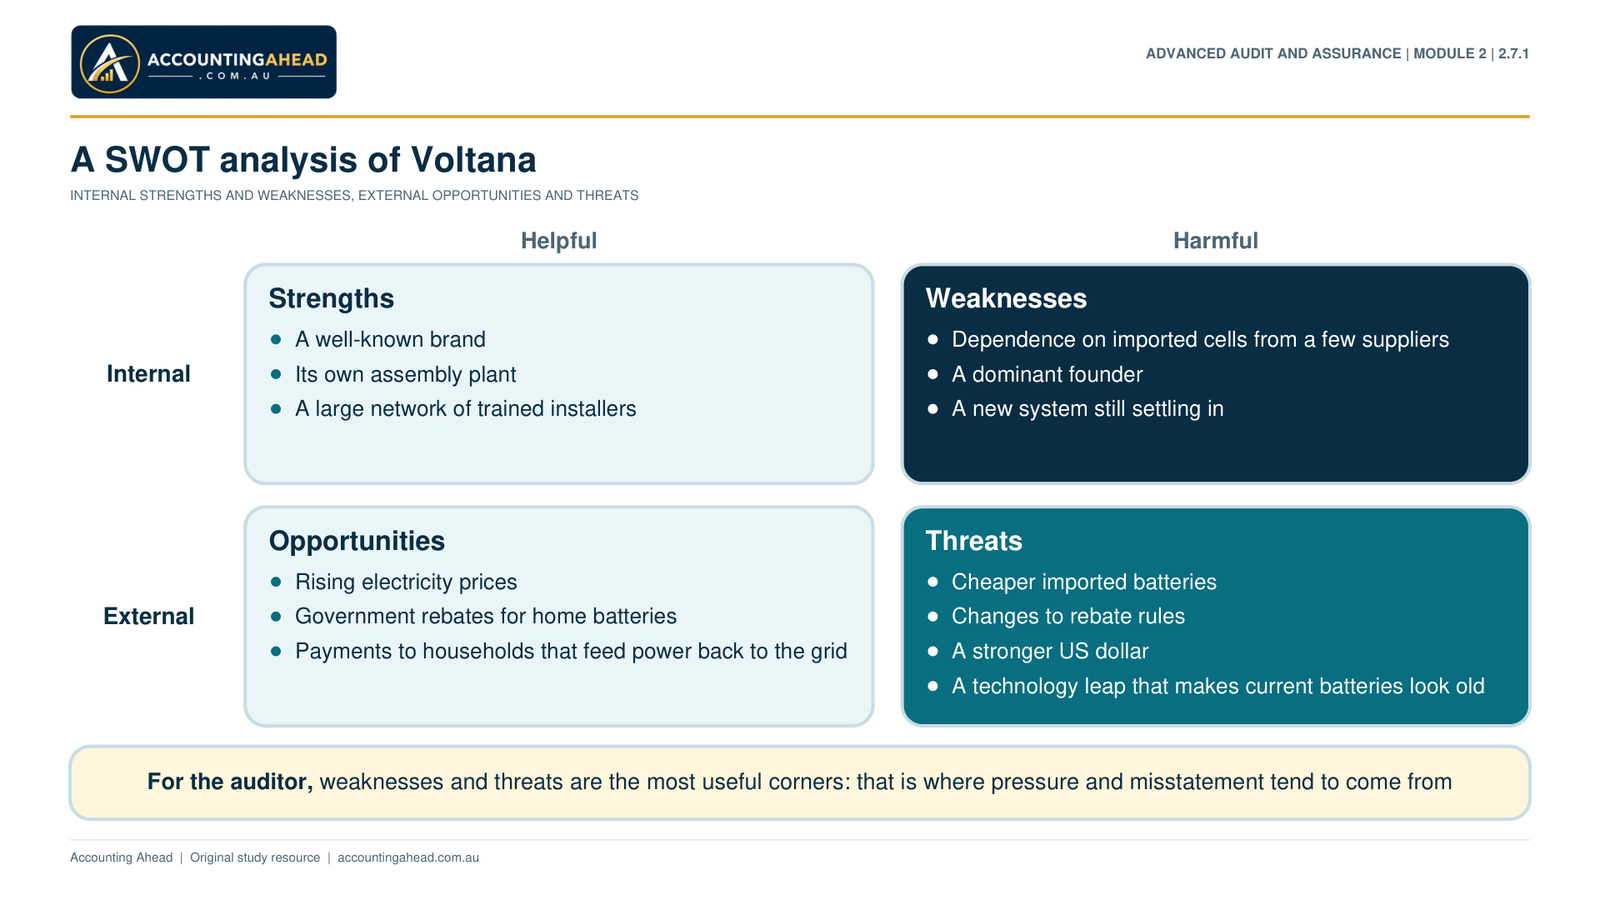
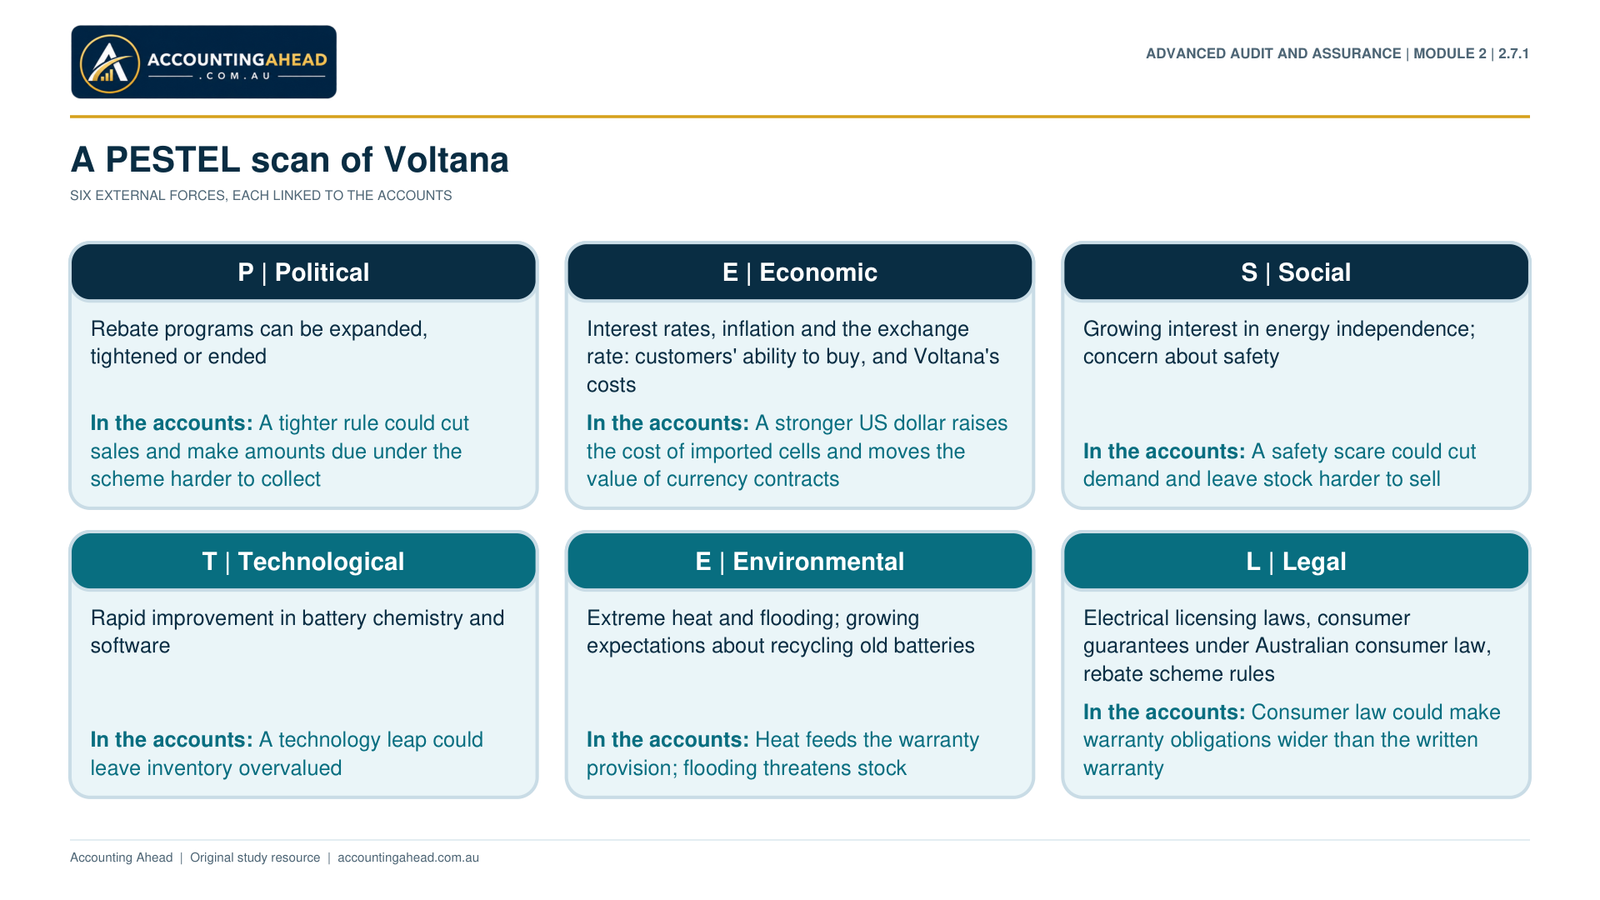
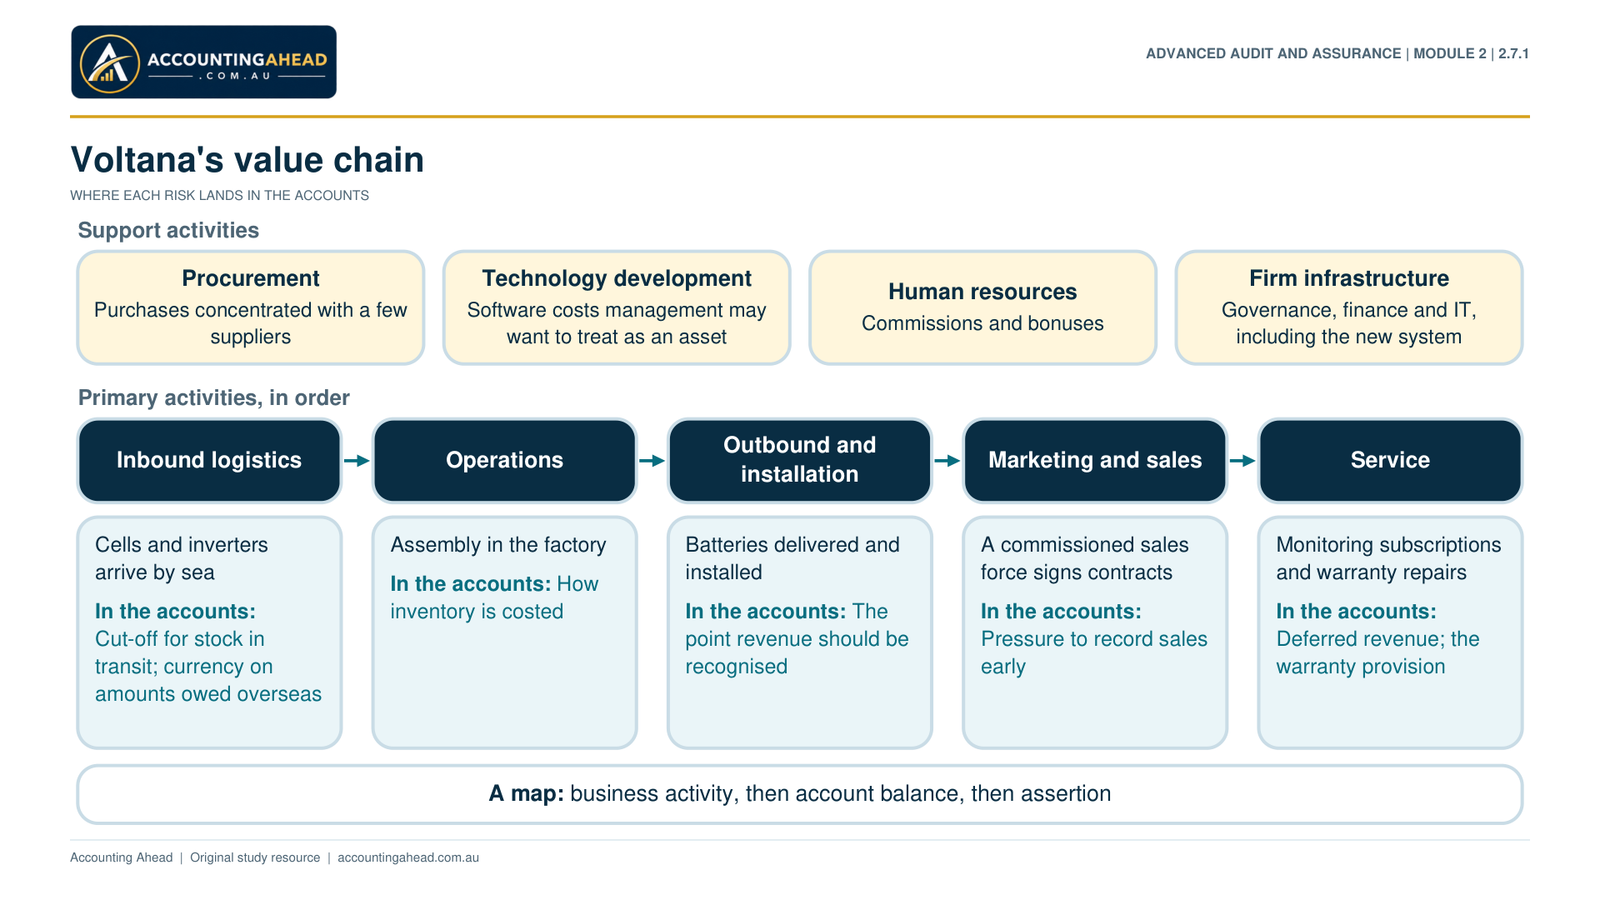
Part 2.7.1 · Strategic Analysis for Risk Assessment
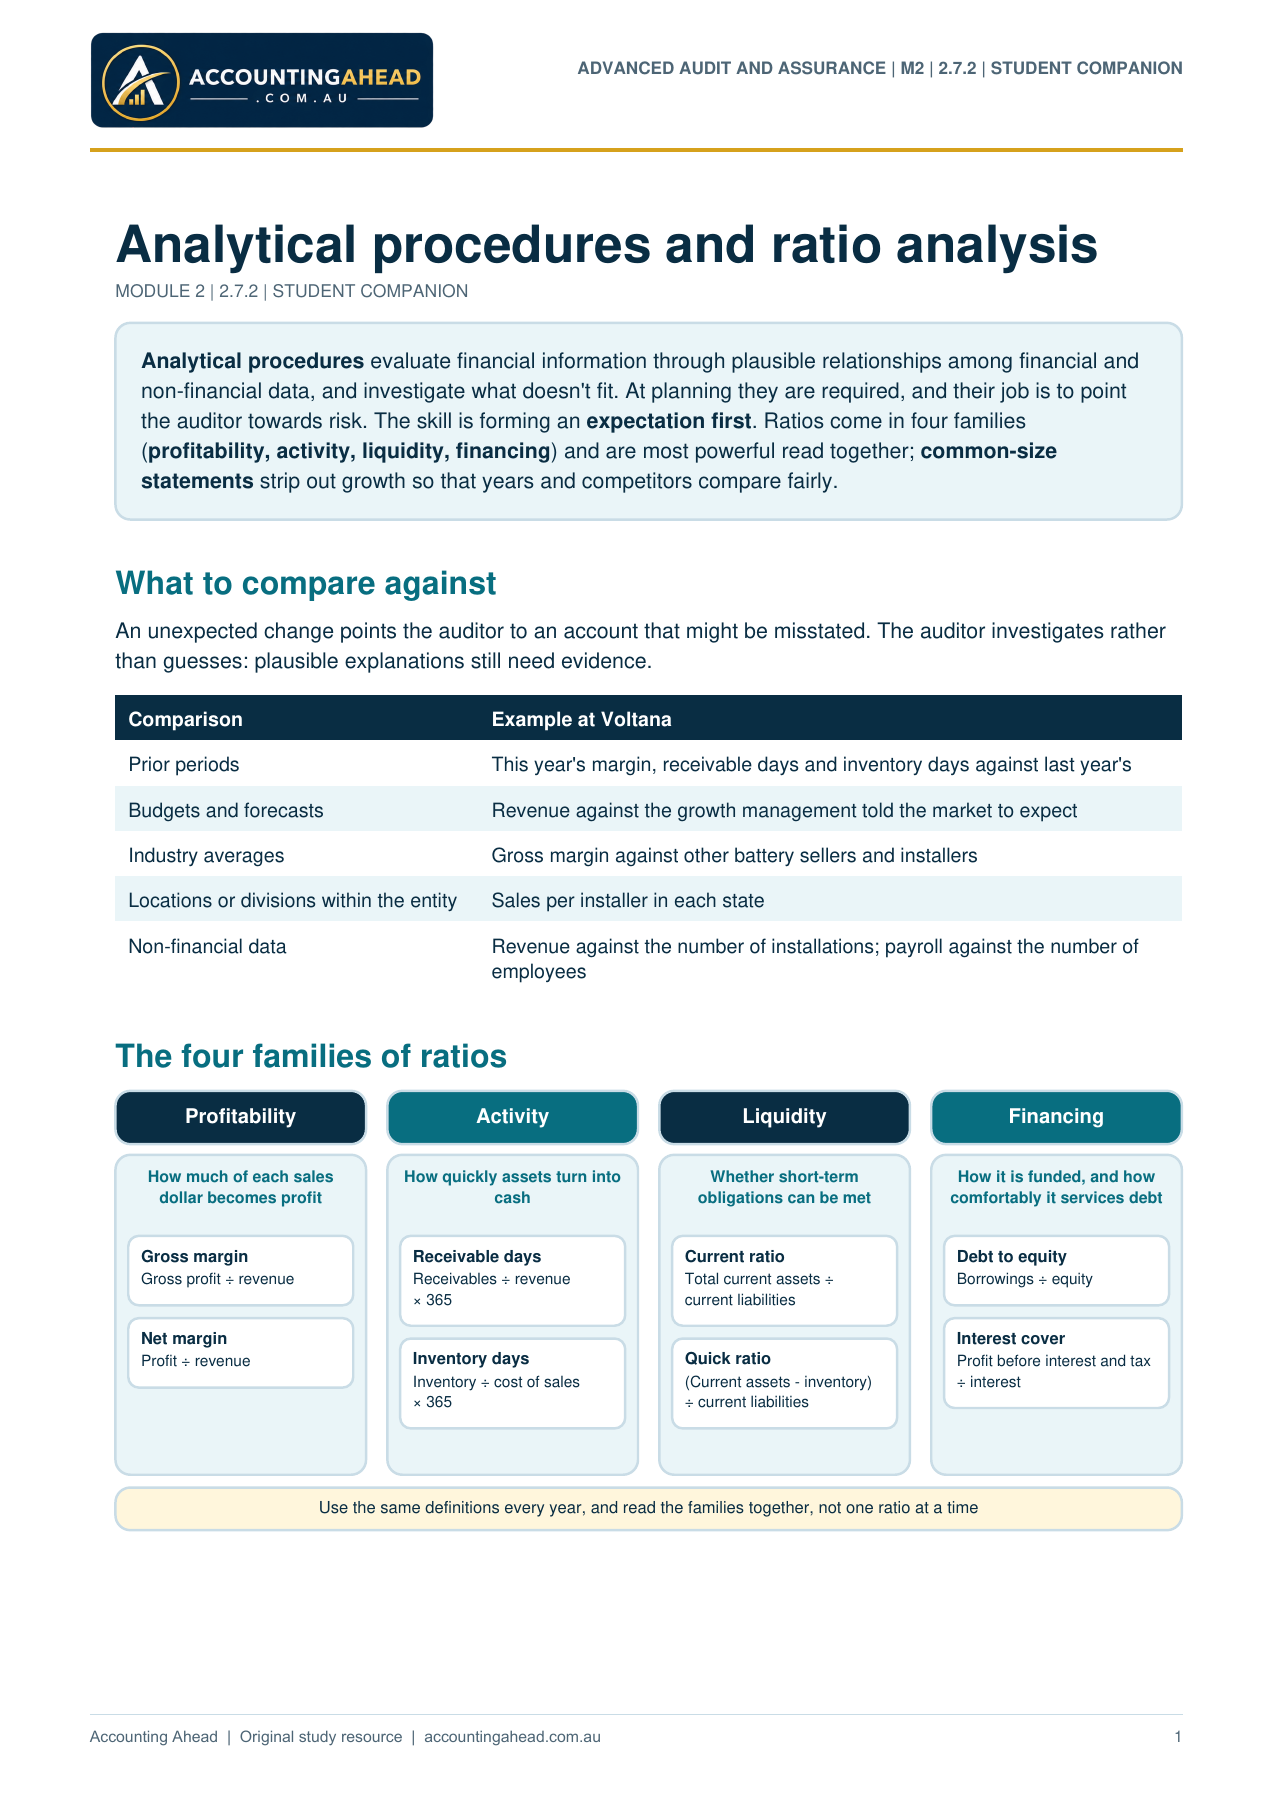
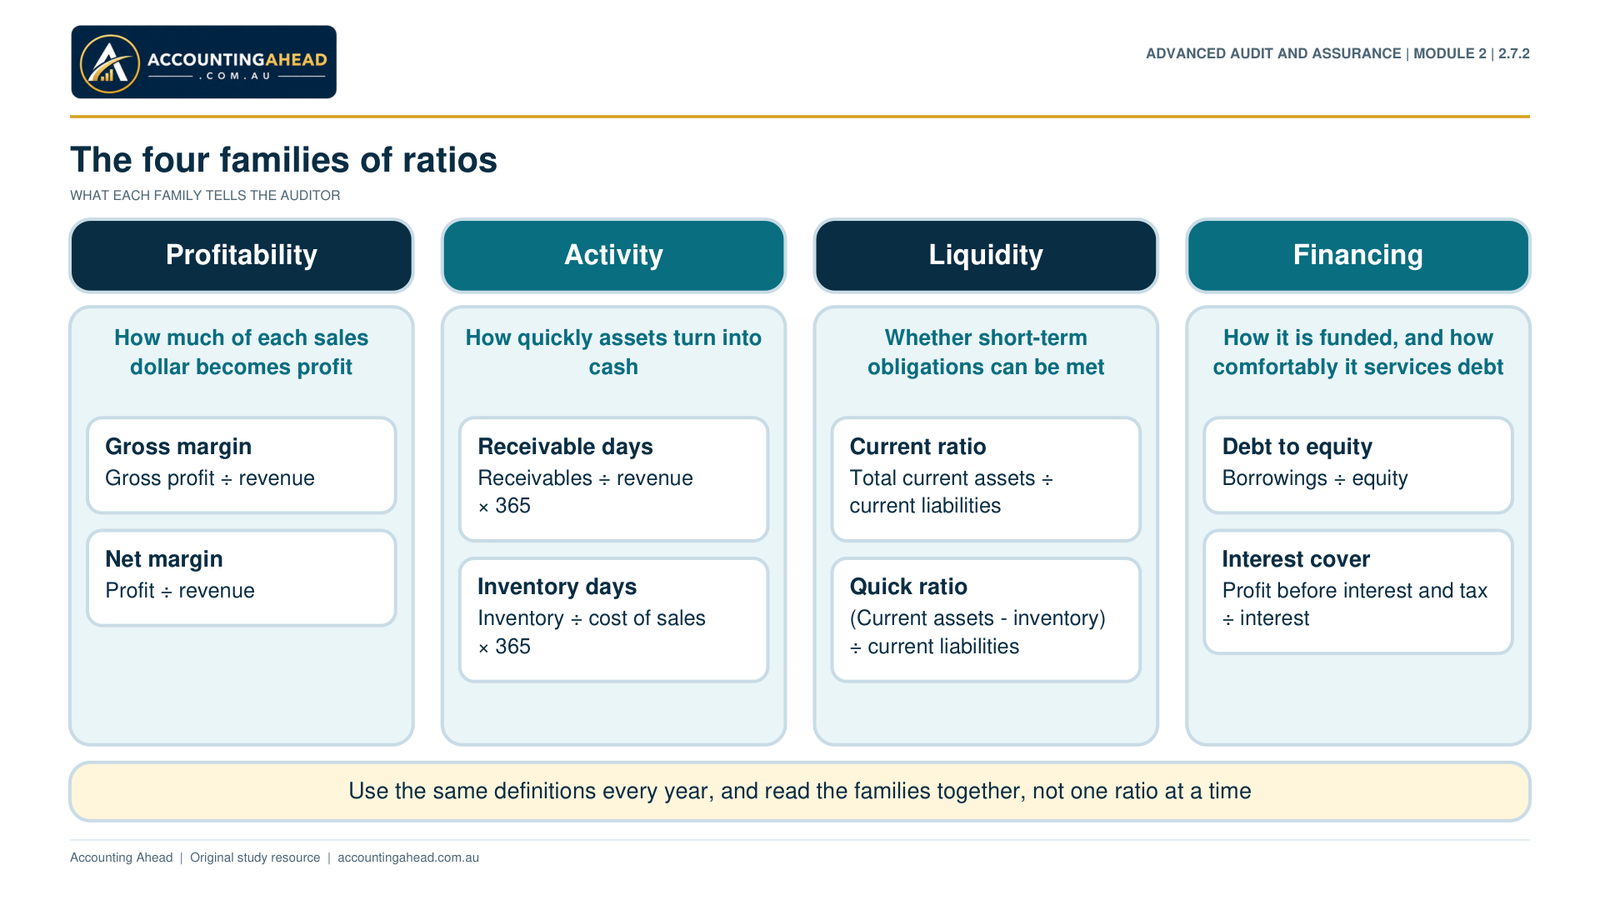
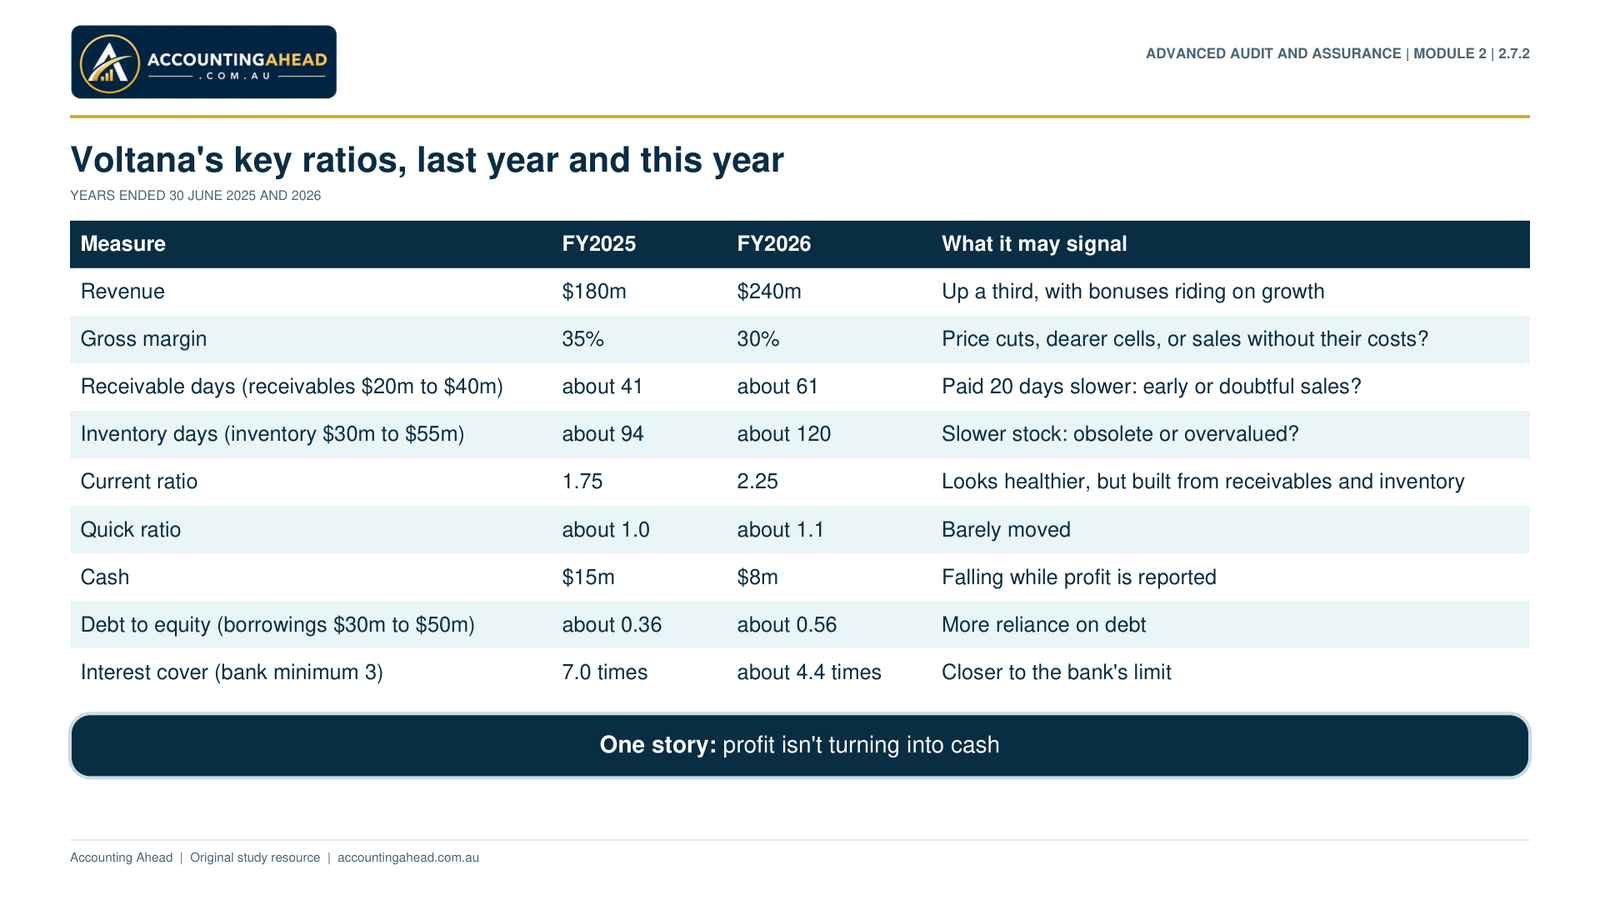
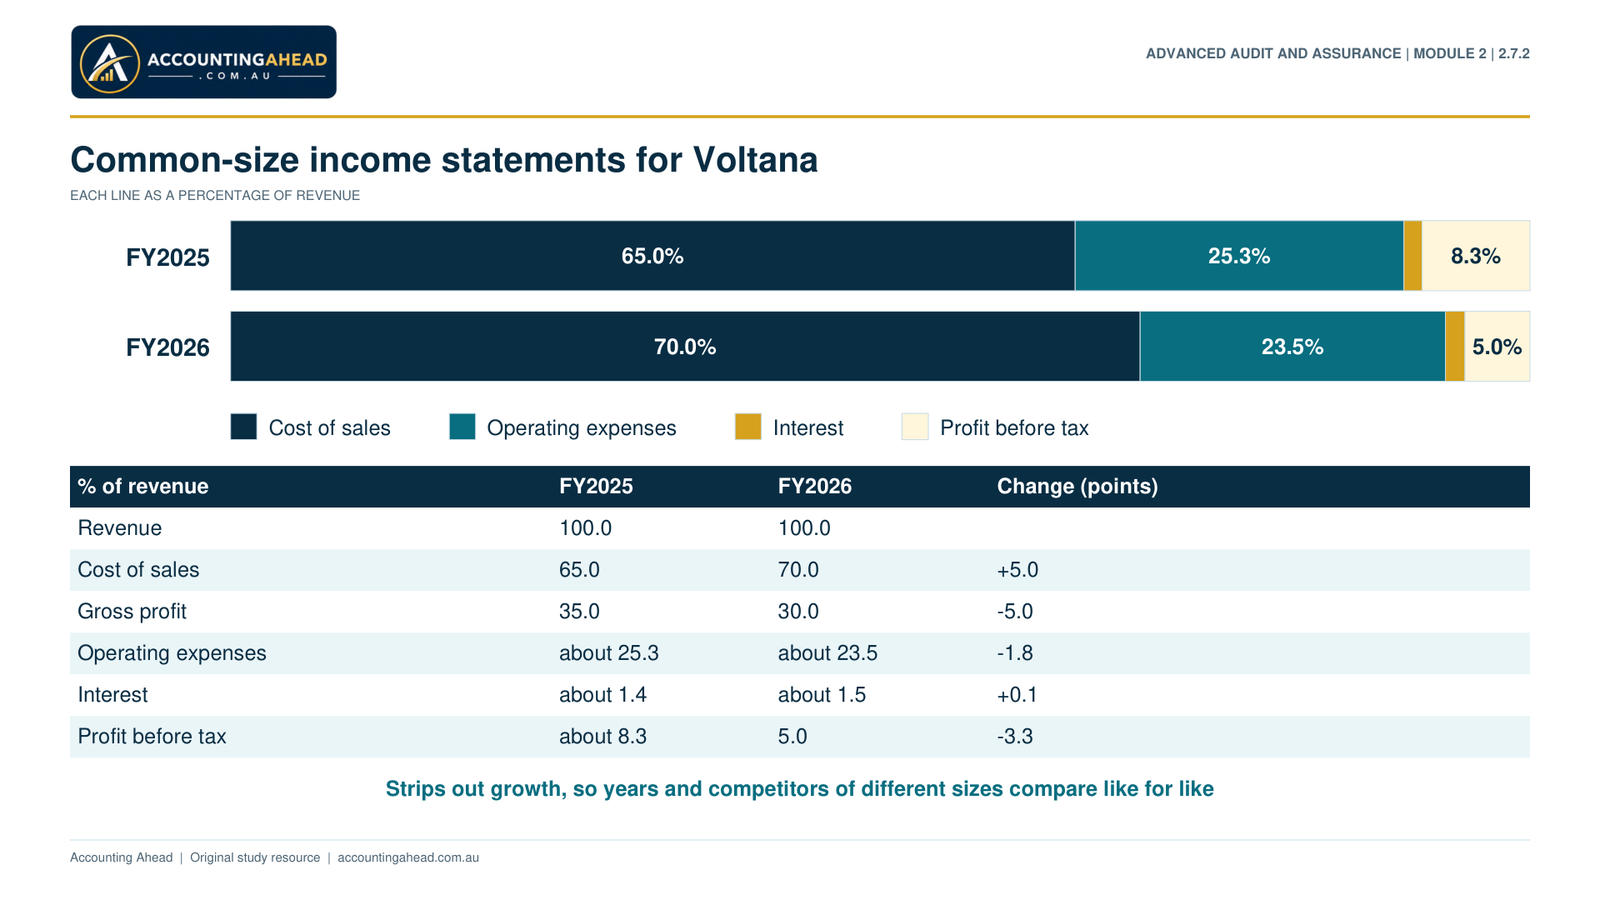
Part 2.7.2 · Analytical Procedures and Ratio Analysis
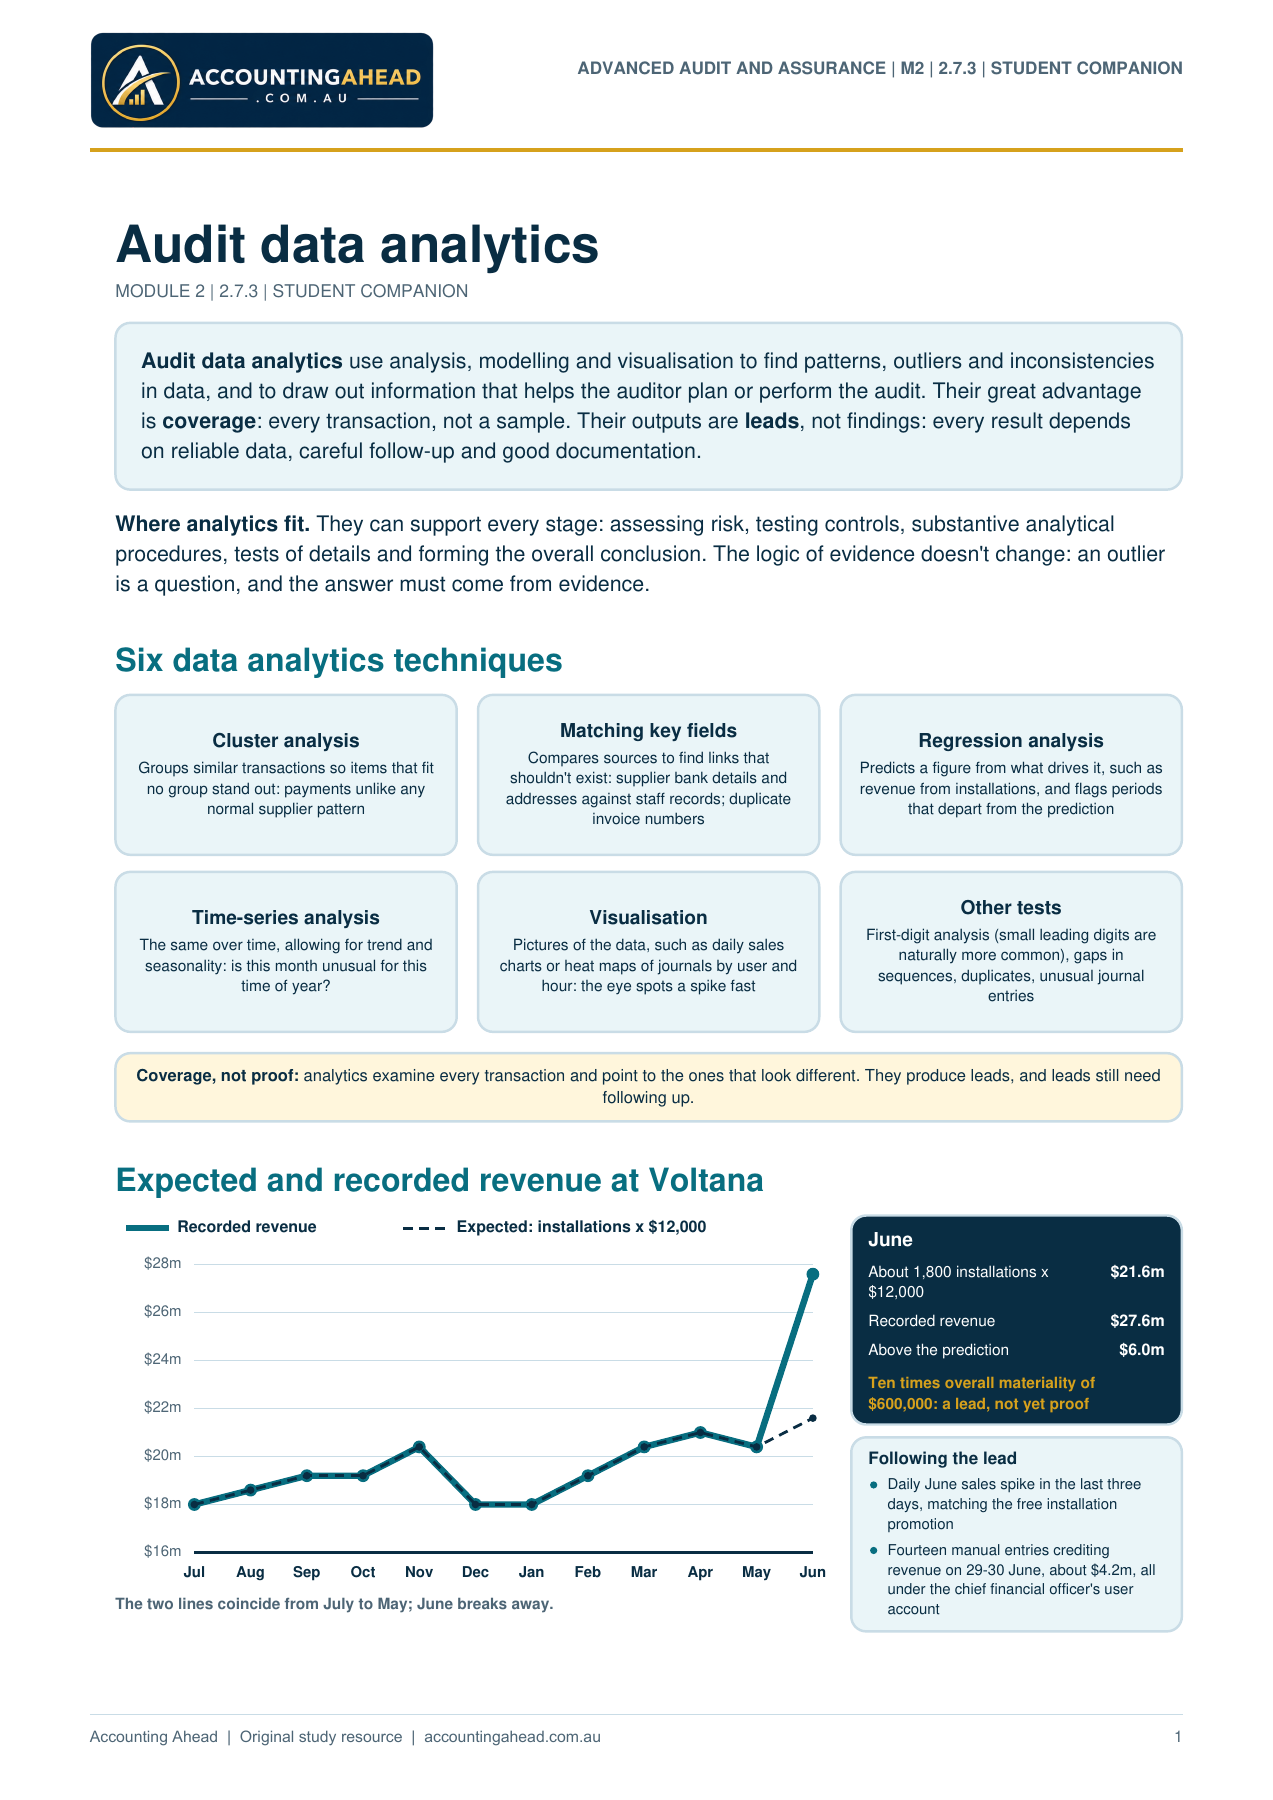
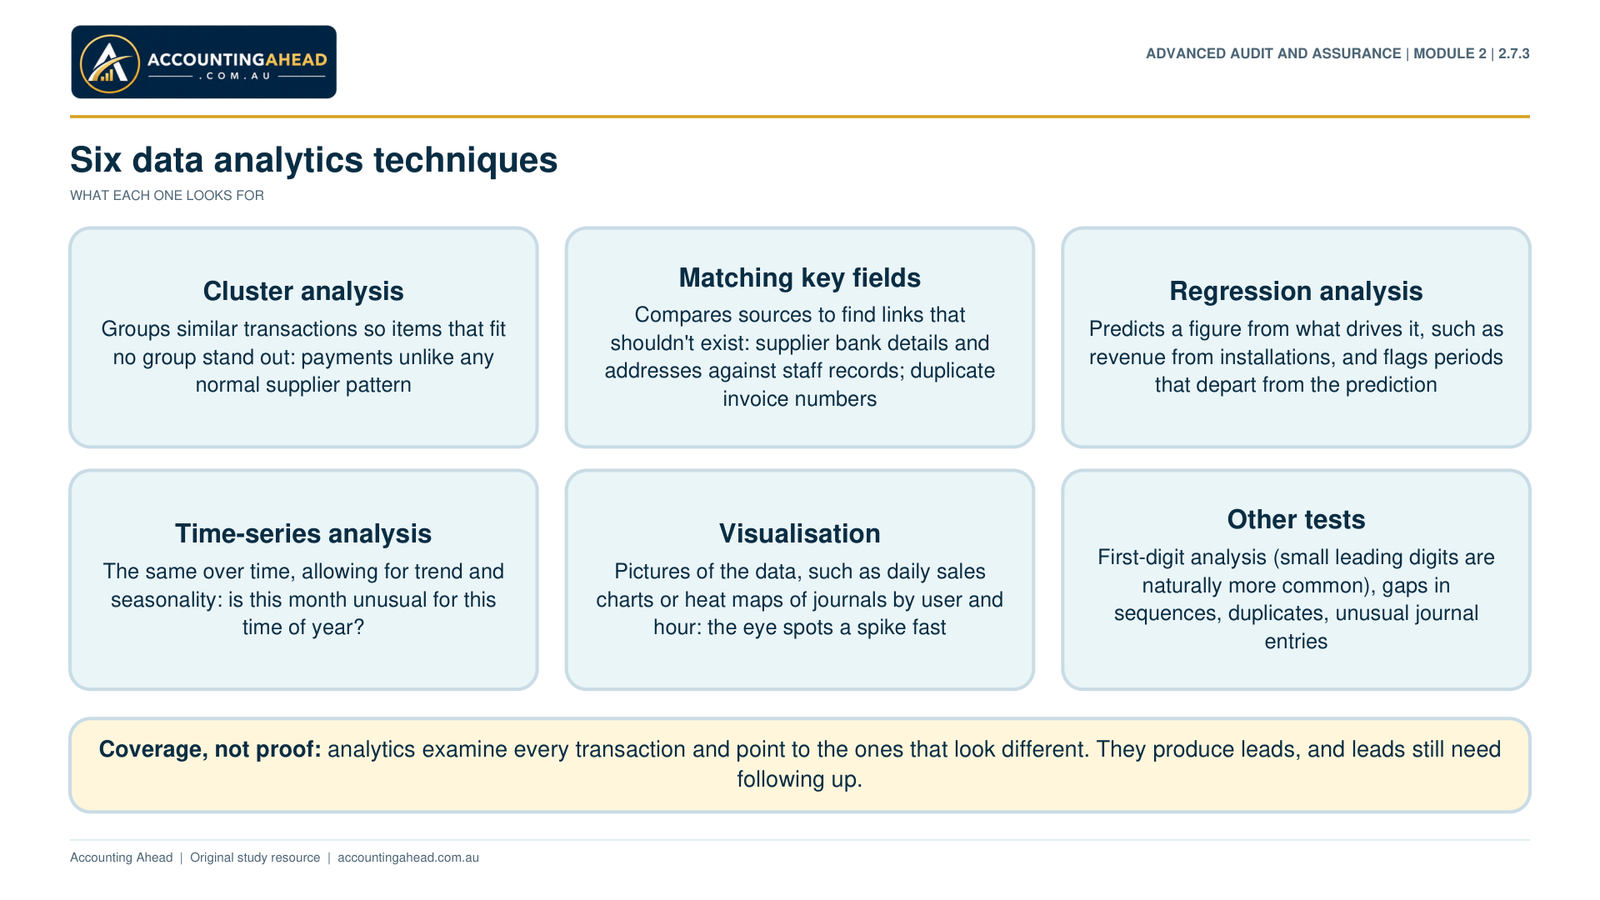
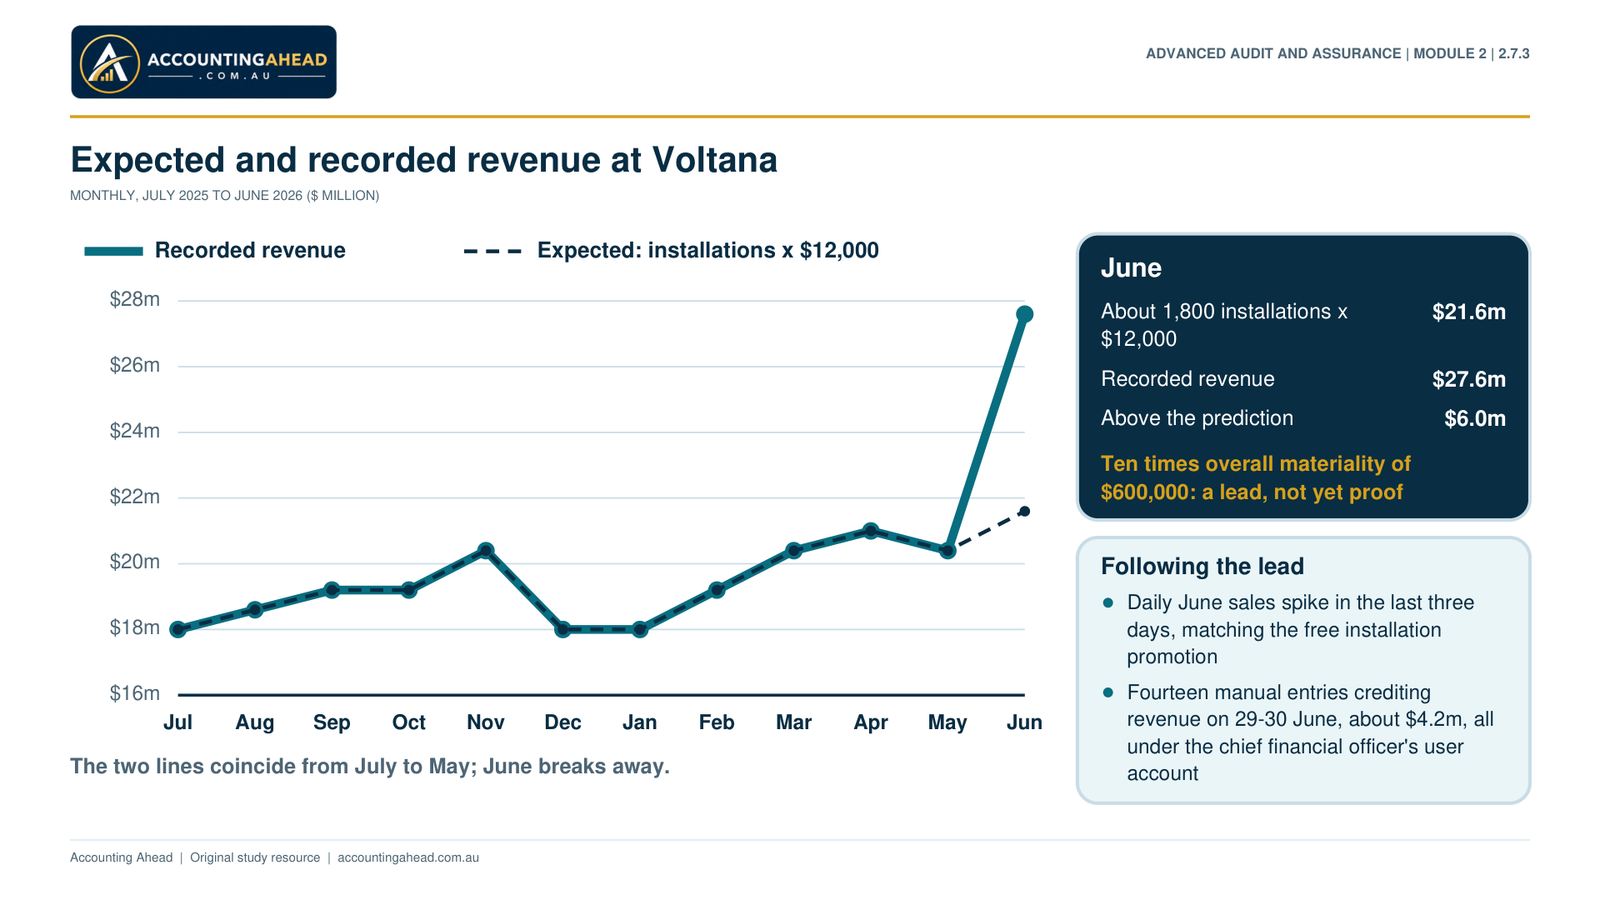
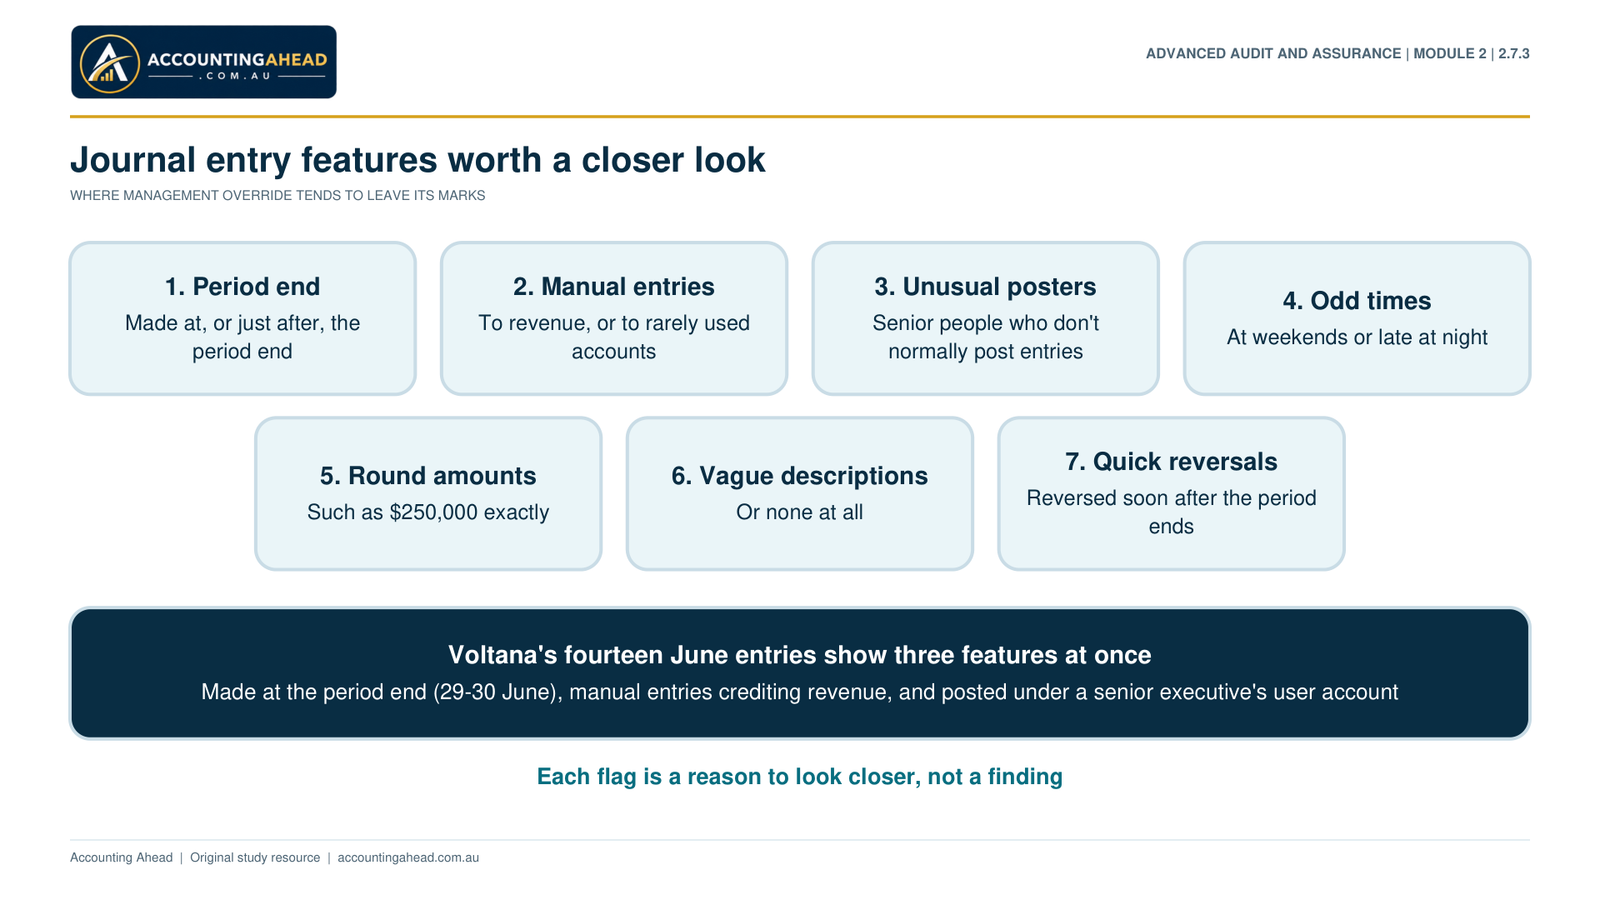
Part 2.7.3 · Audit Data Analytics
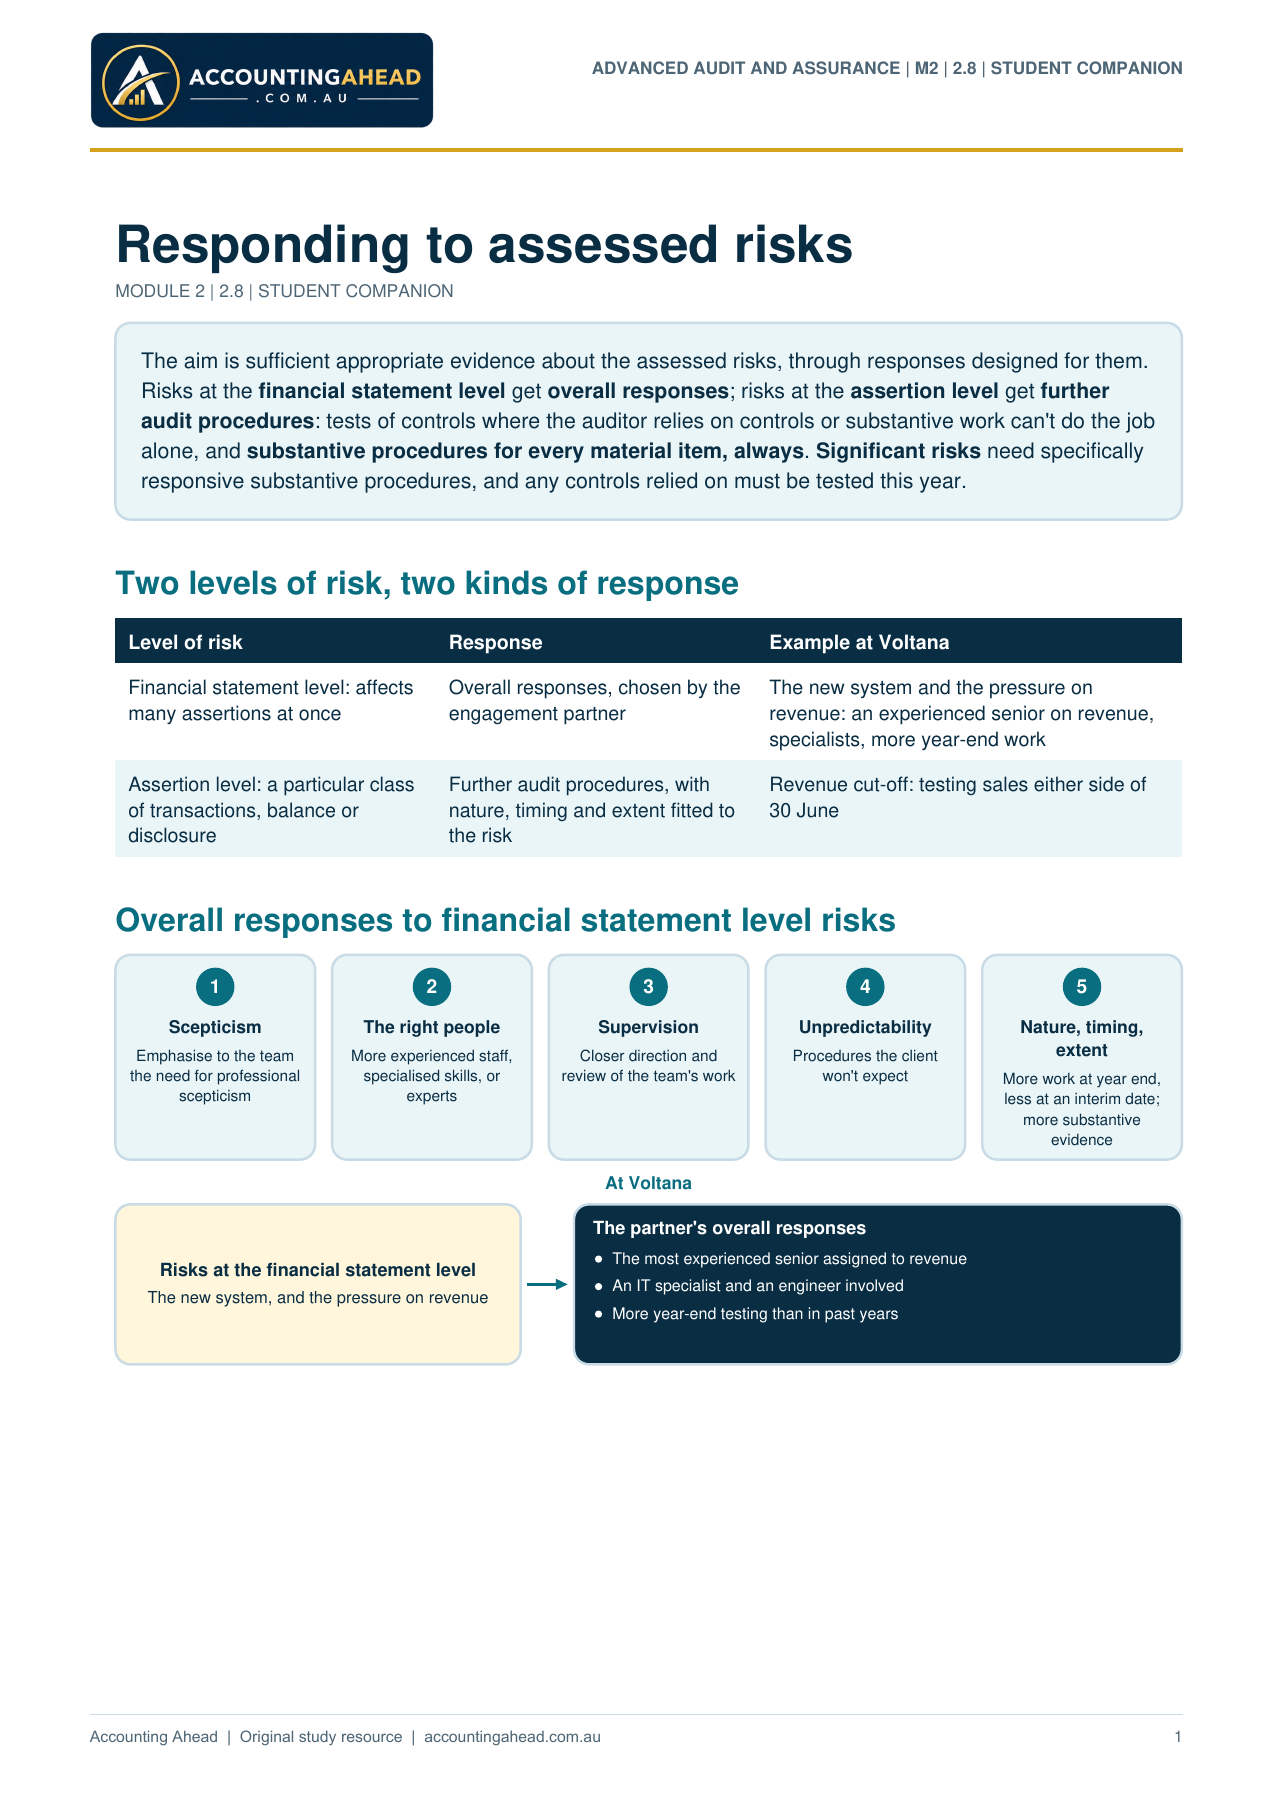
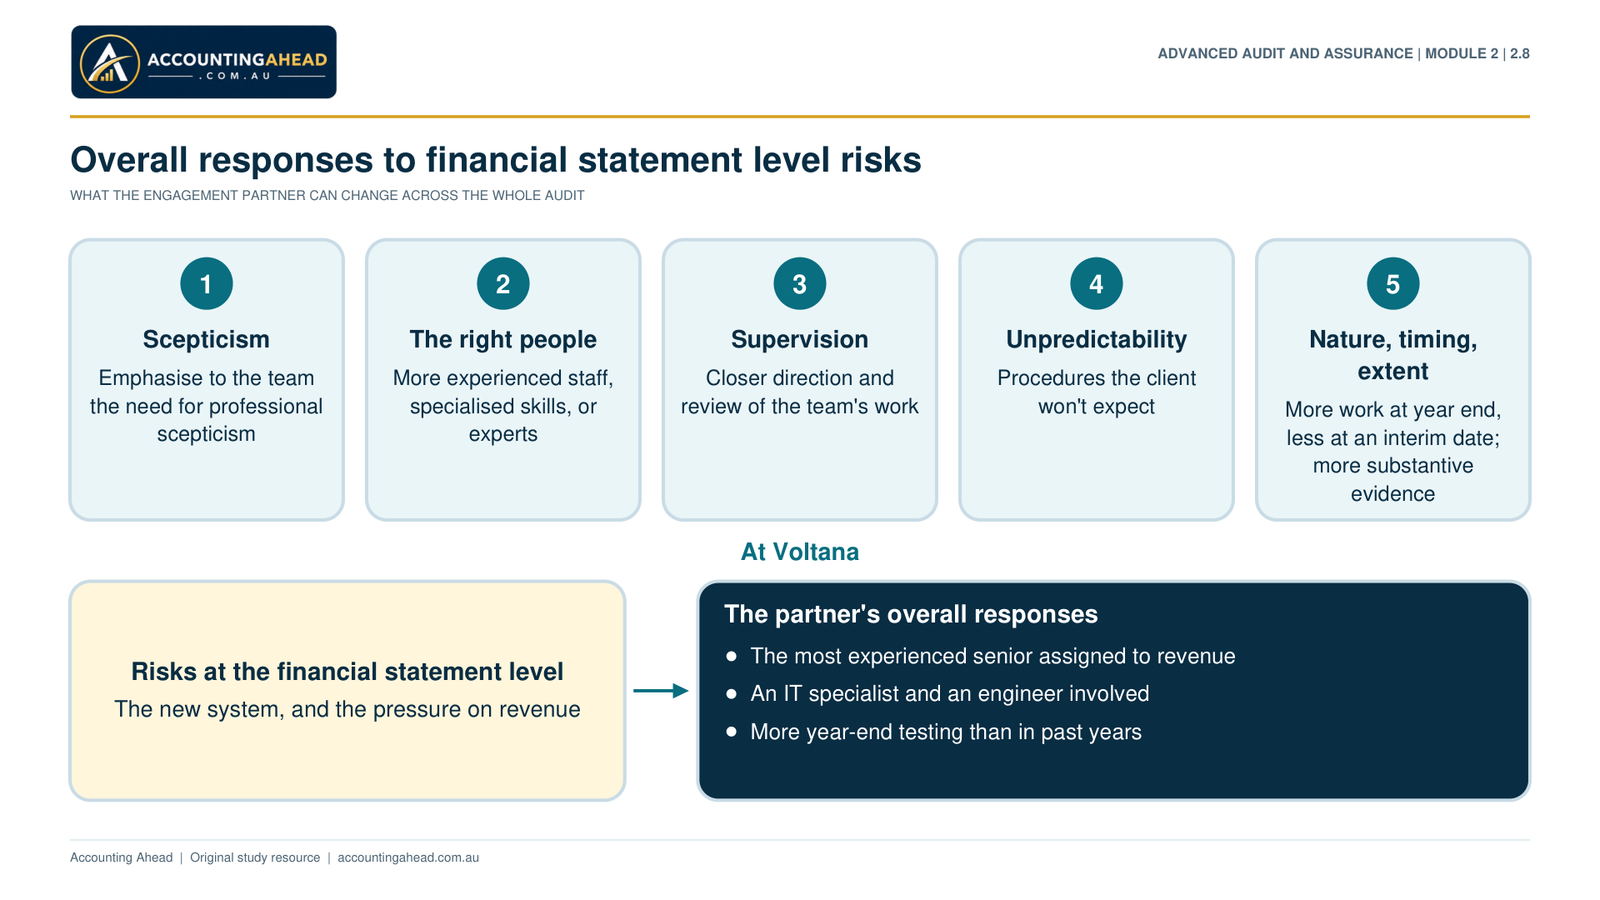
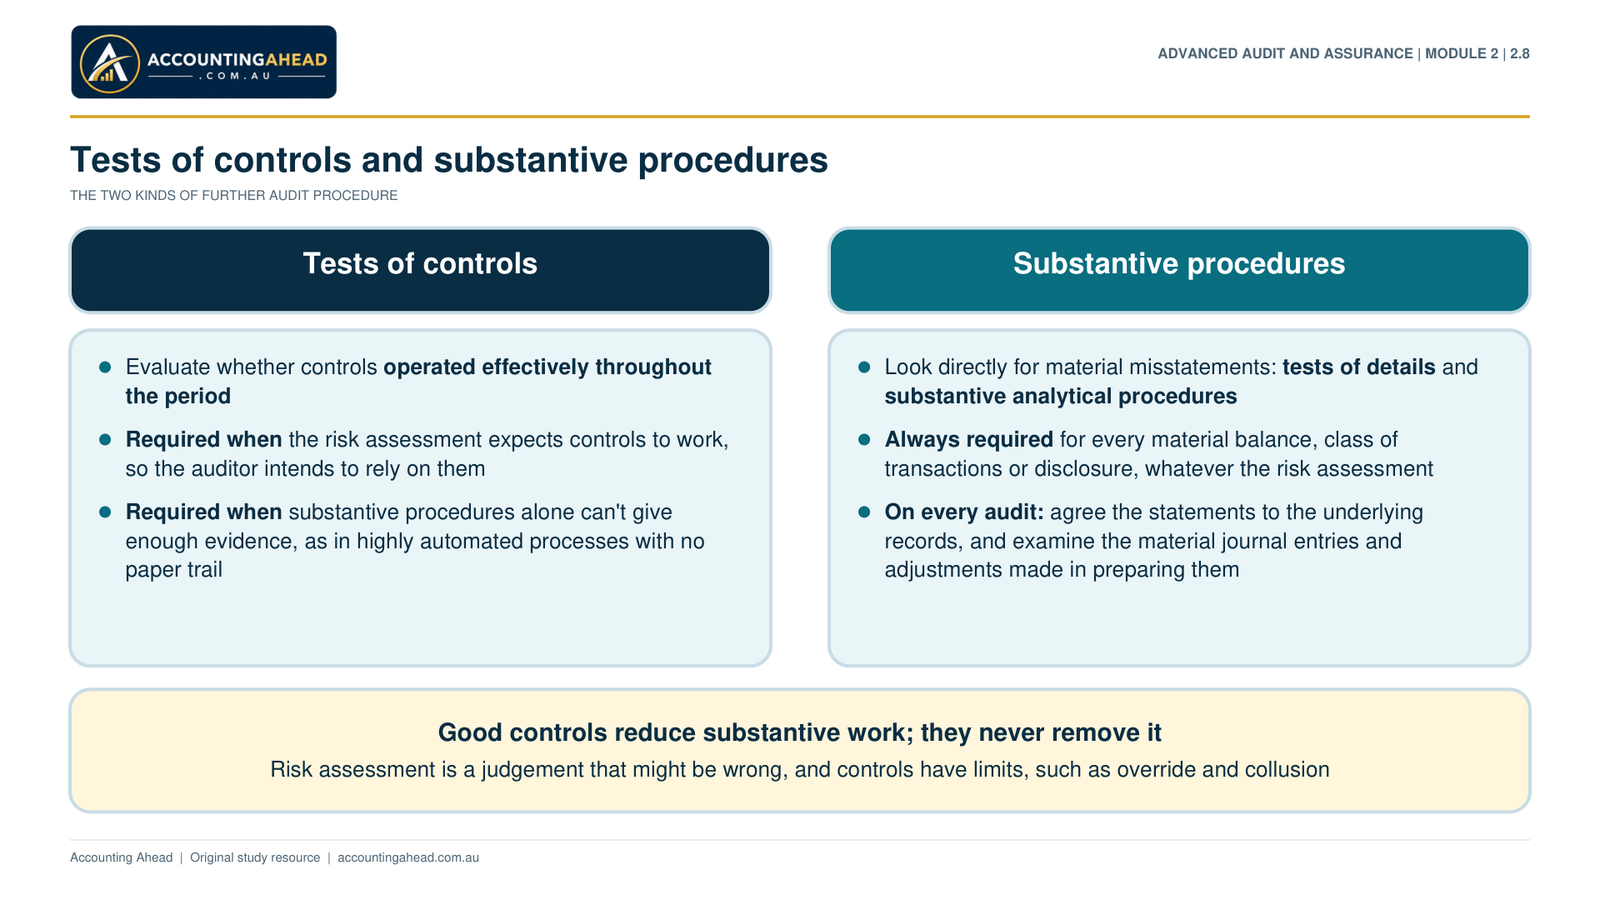
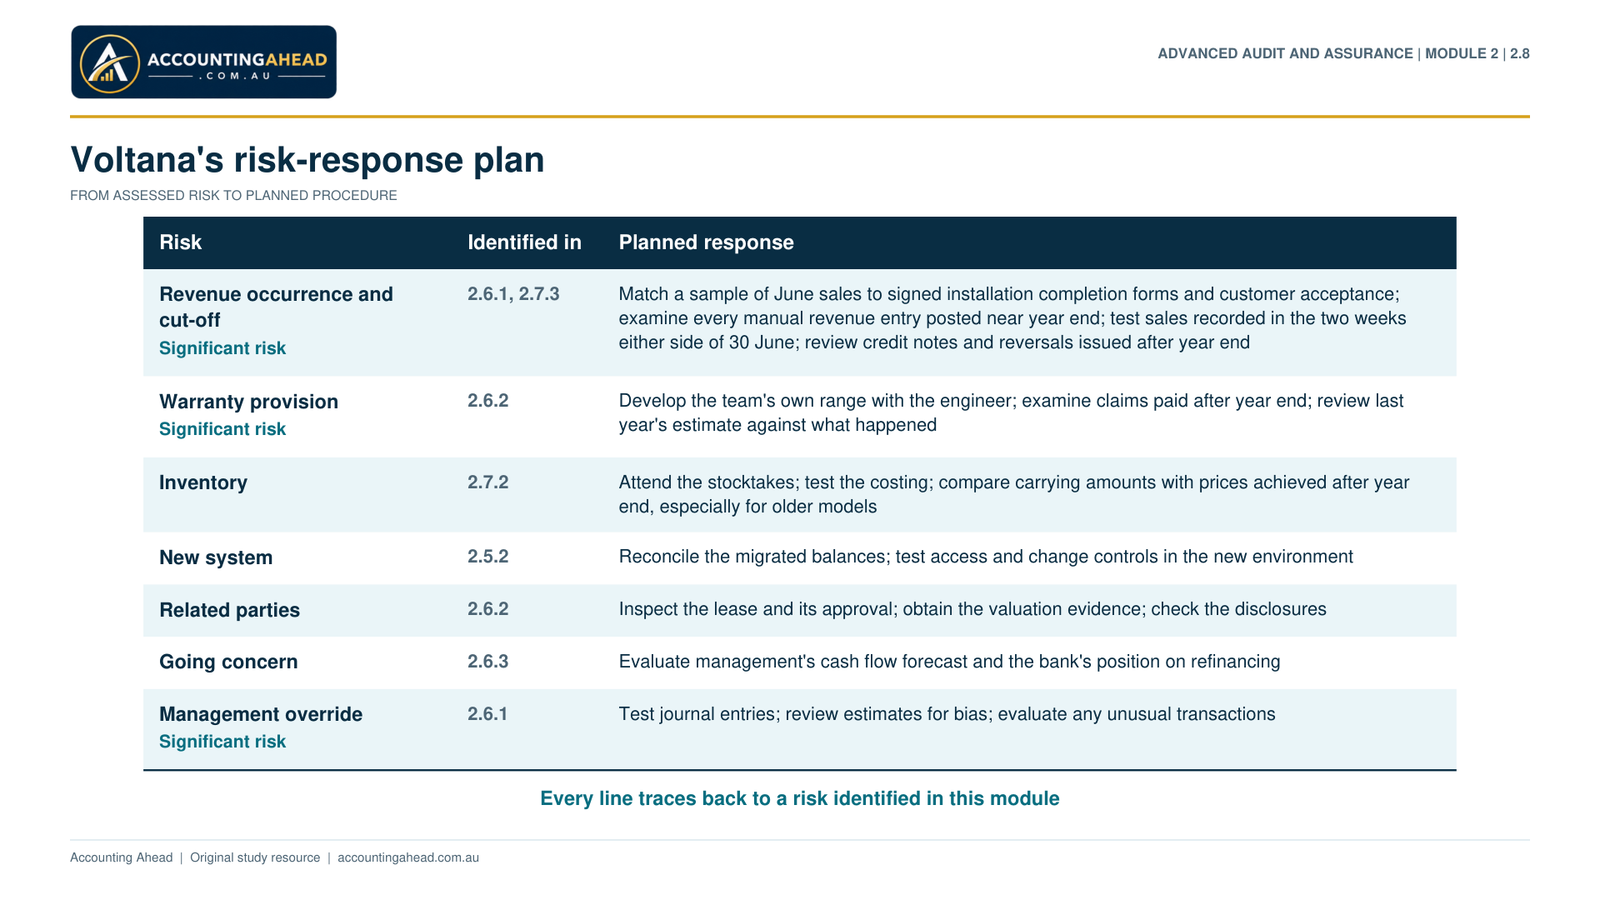
Part 2.8 · Responding to Assessed Risks
Module 3 · Performing the audit of historical financial information
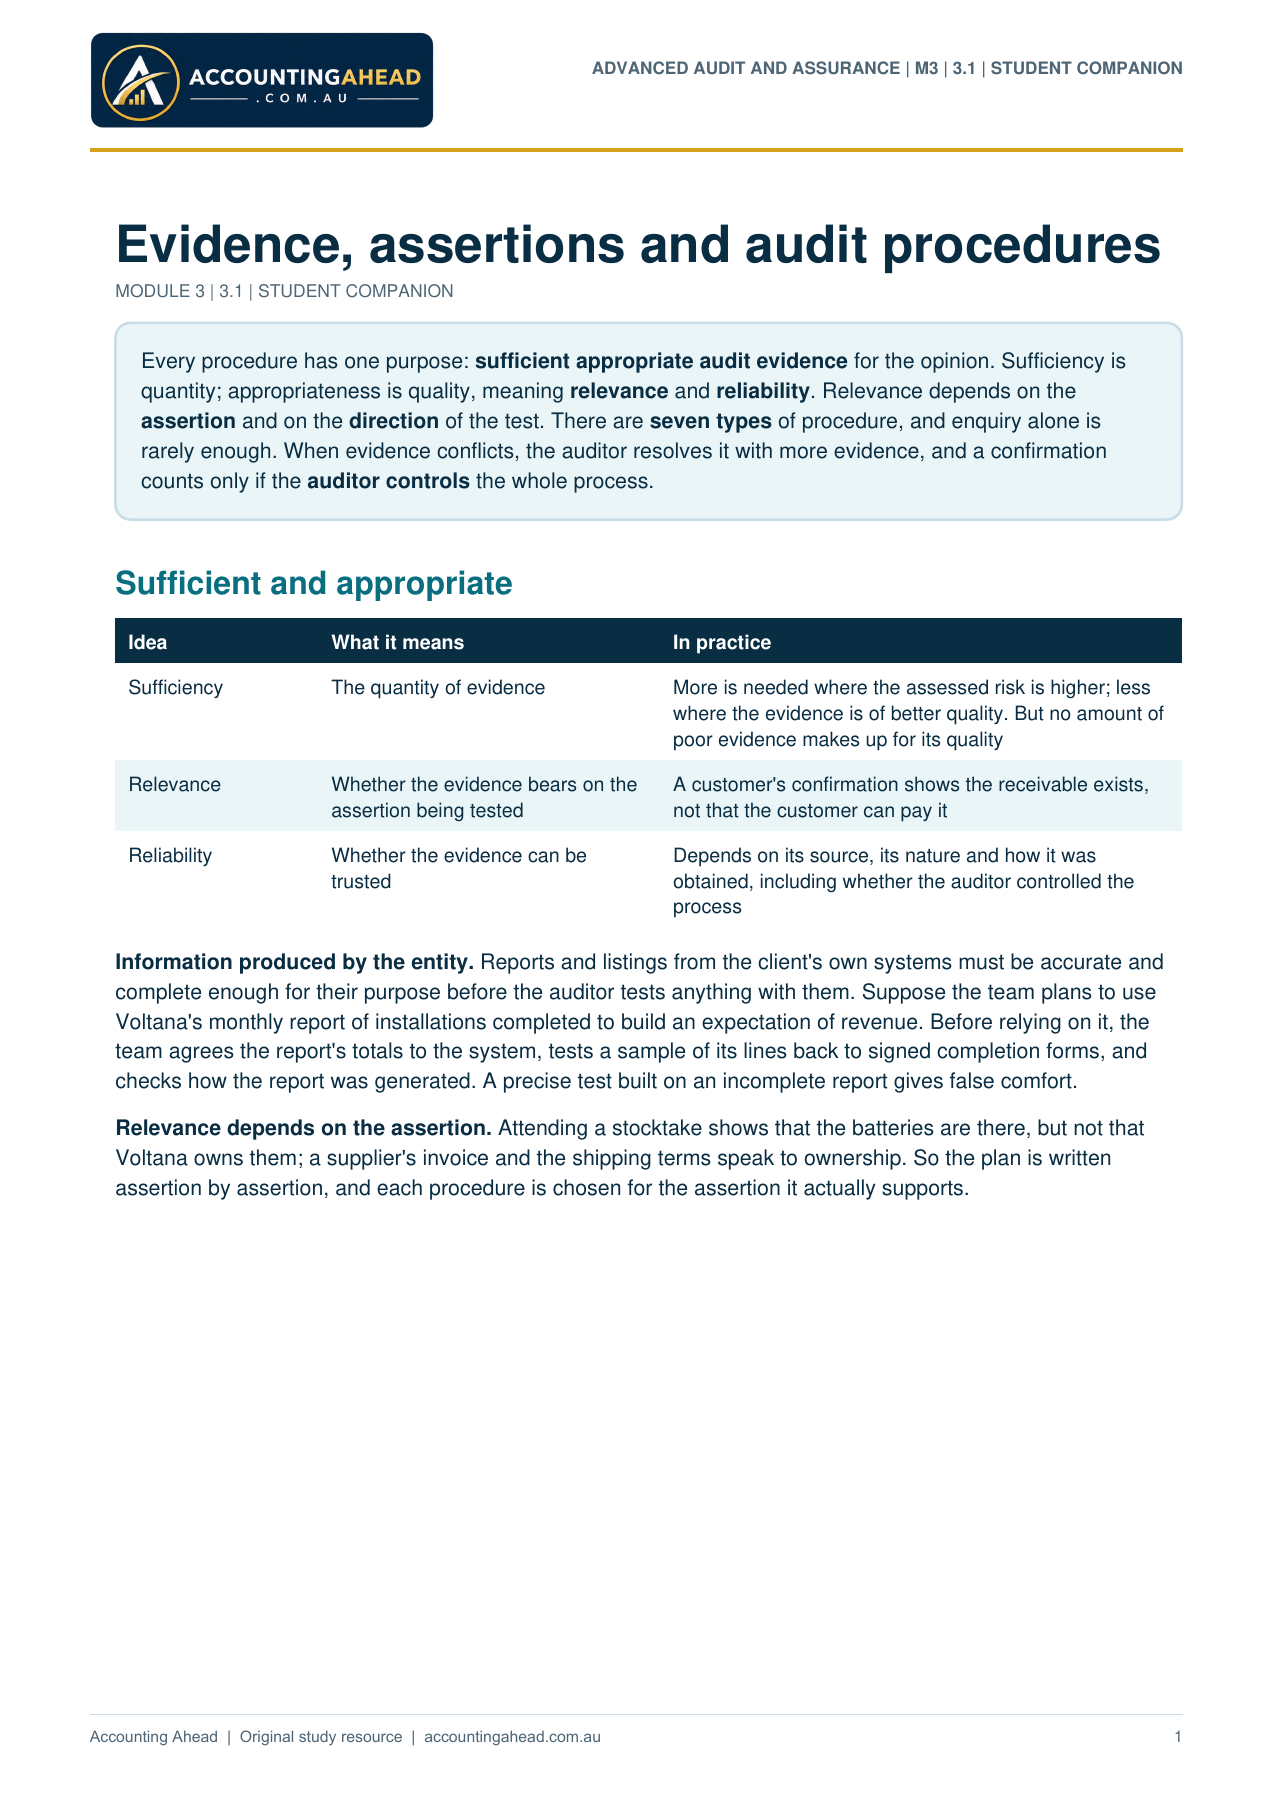
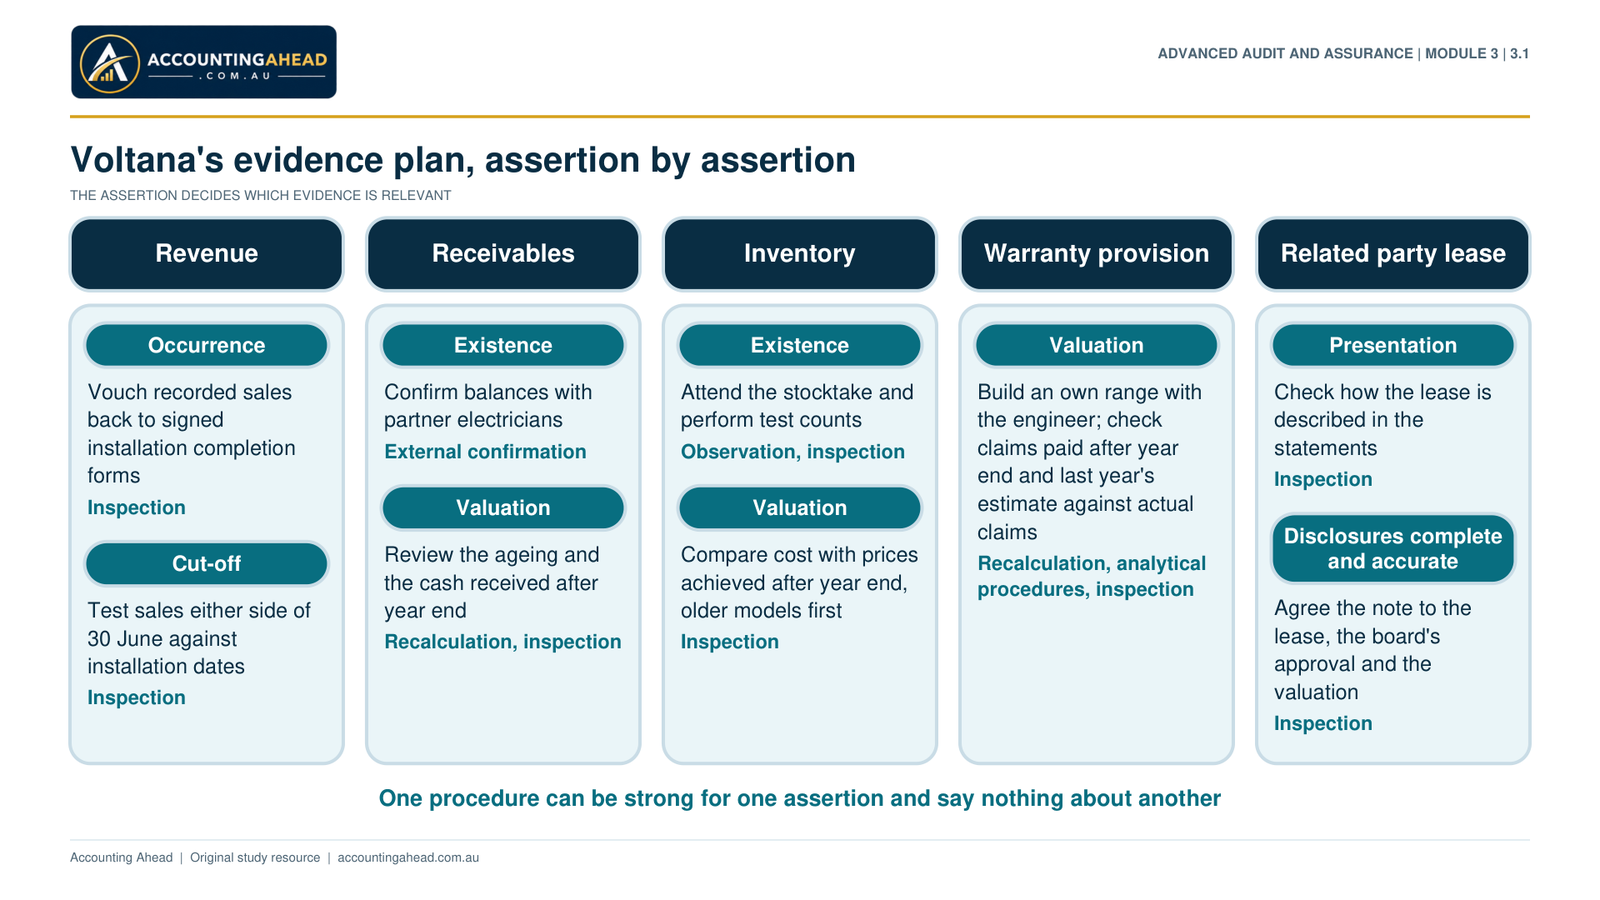
Part 3.1 · Evidence, Assertions and Audit Procedures
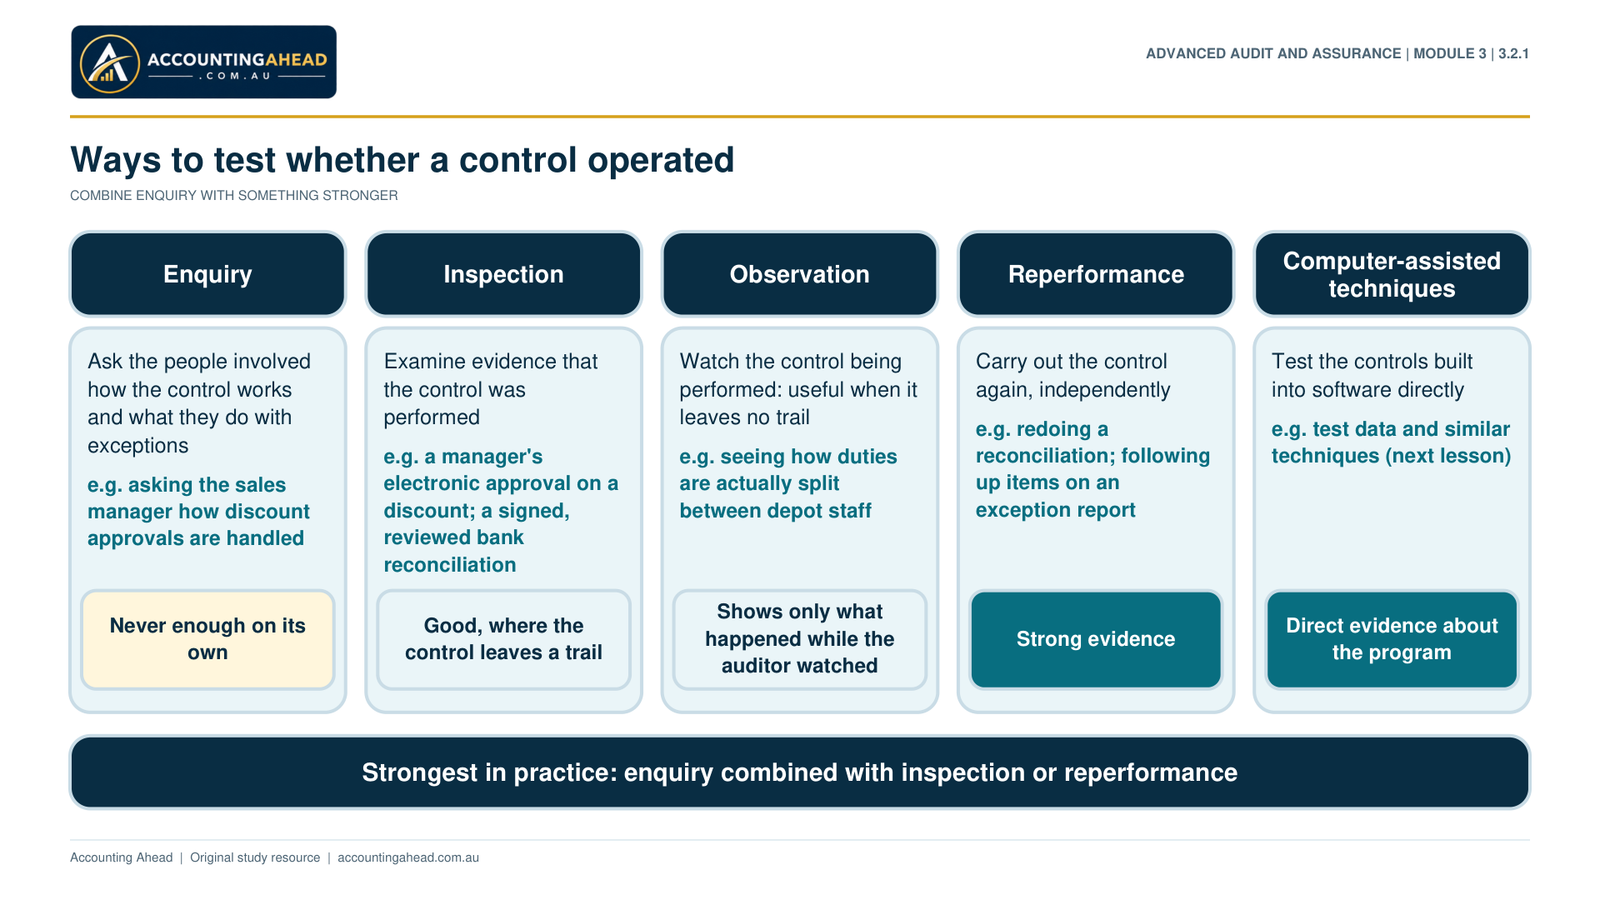
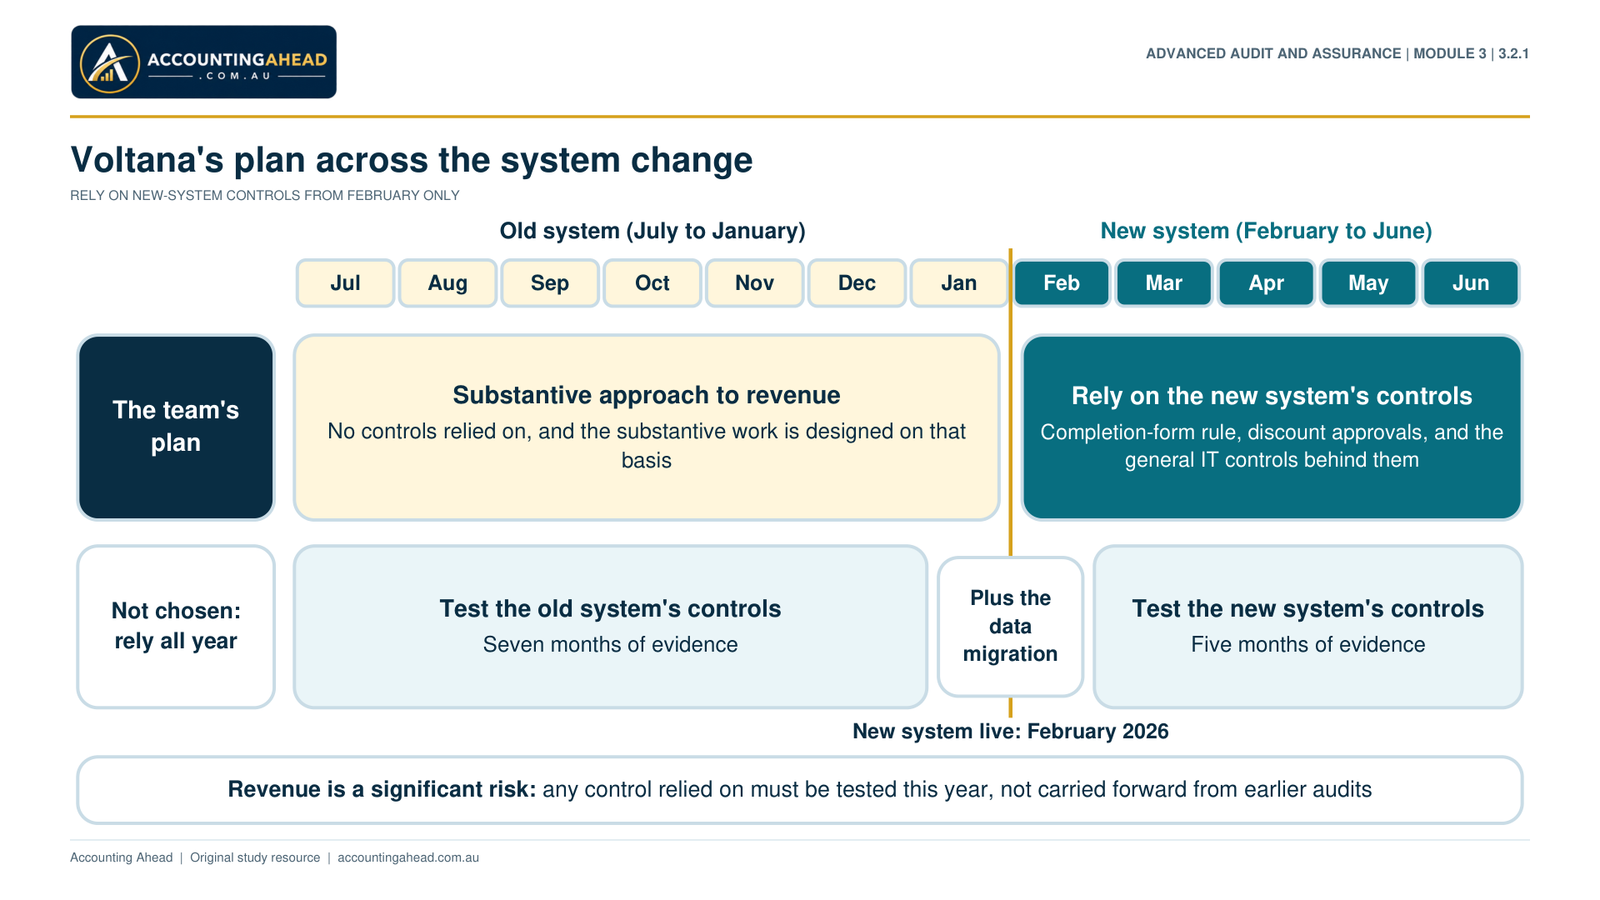
Part 3.2.1 · Tests of Controls
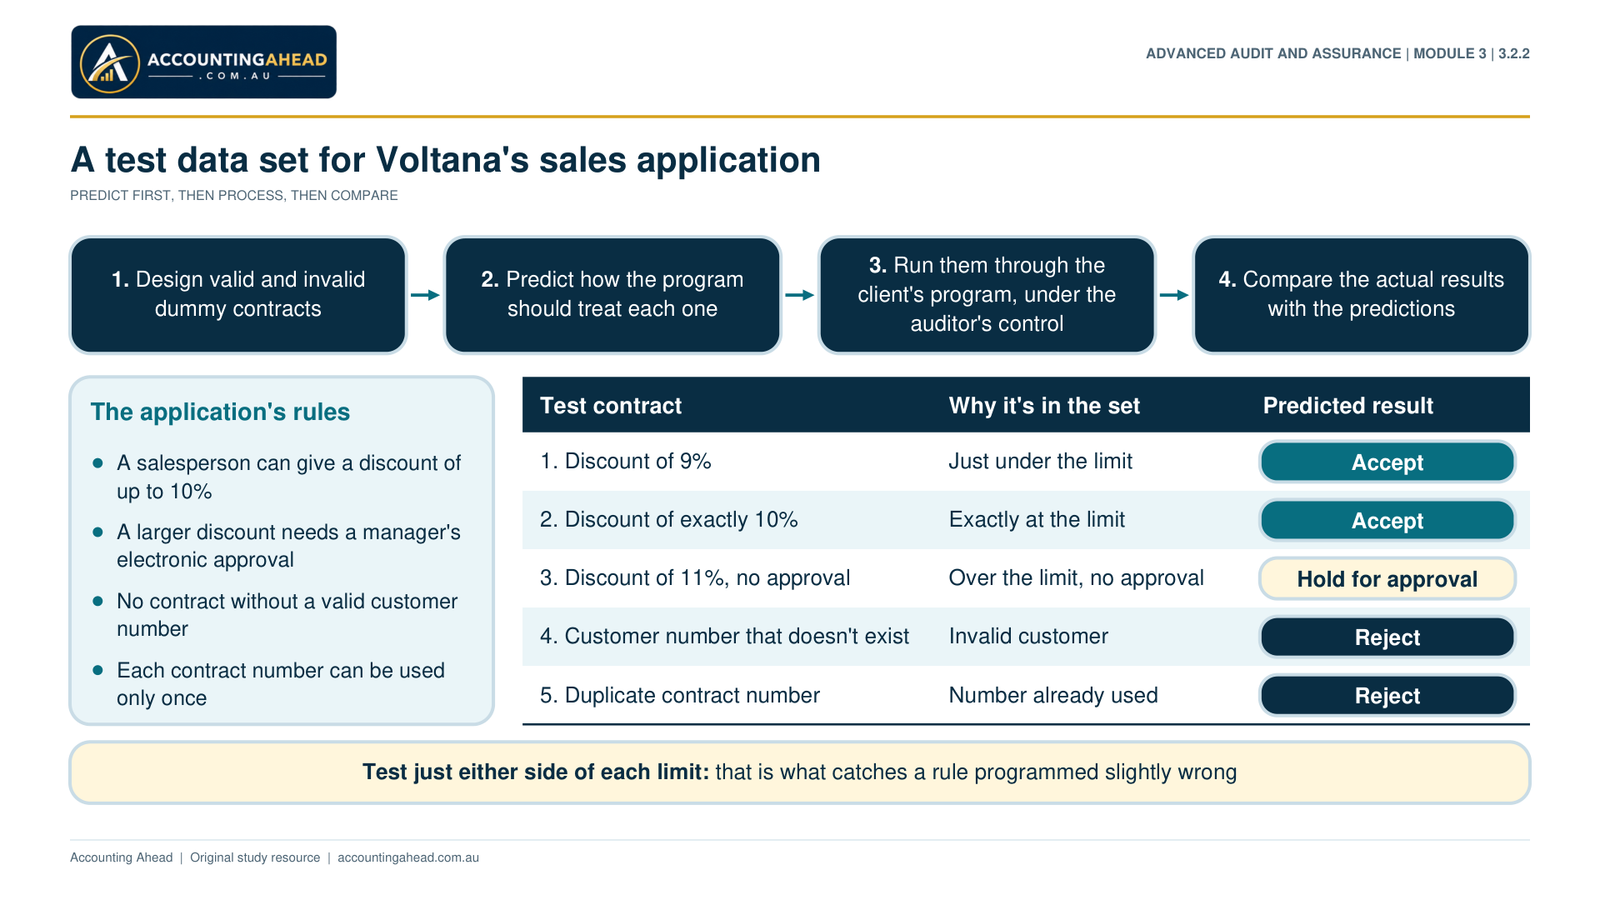
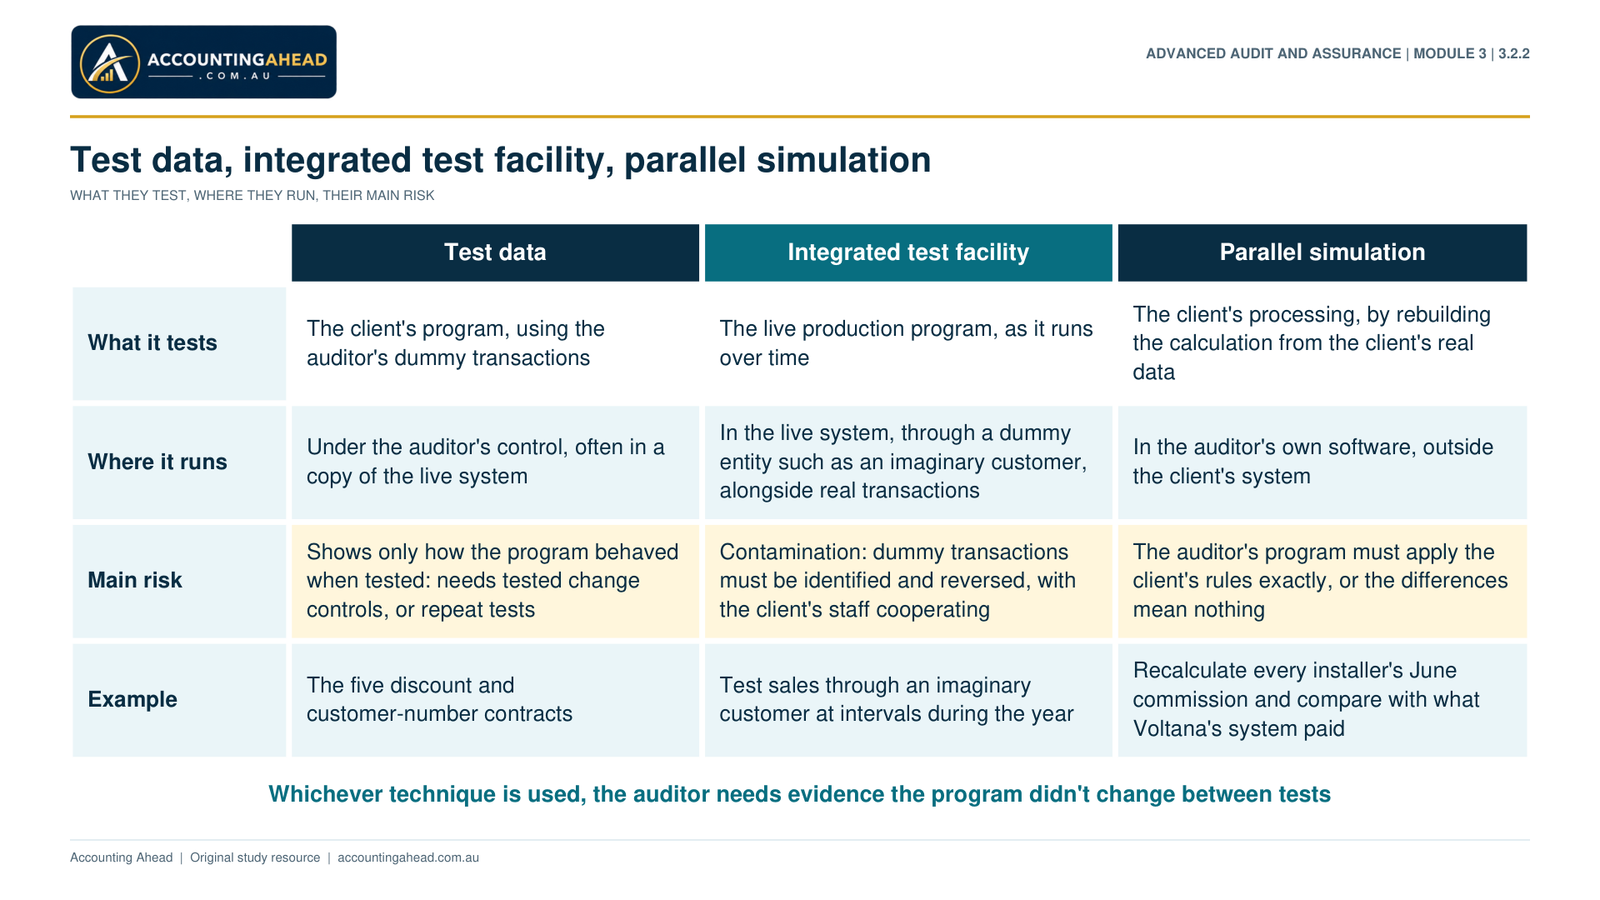
Part 3.2.2 · CAATs for Controls - Test Data and ITF
Part 3.2.3 · Sampling for Tests of Controls
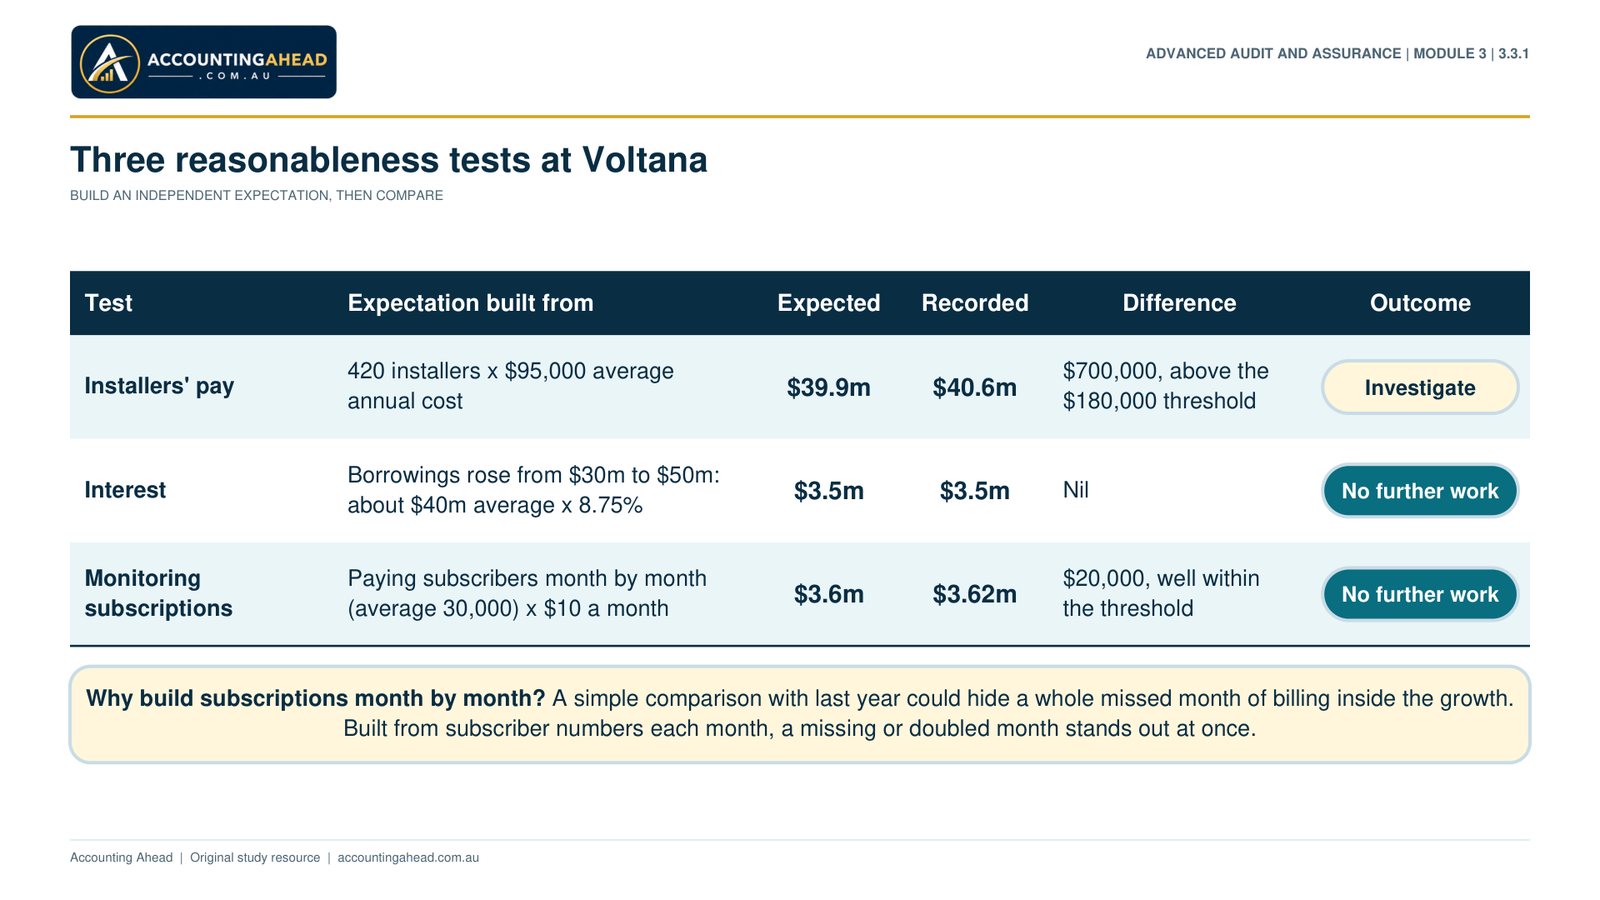
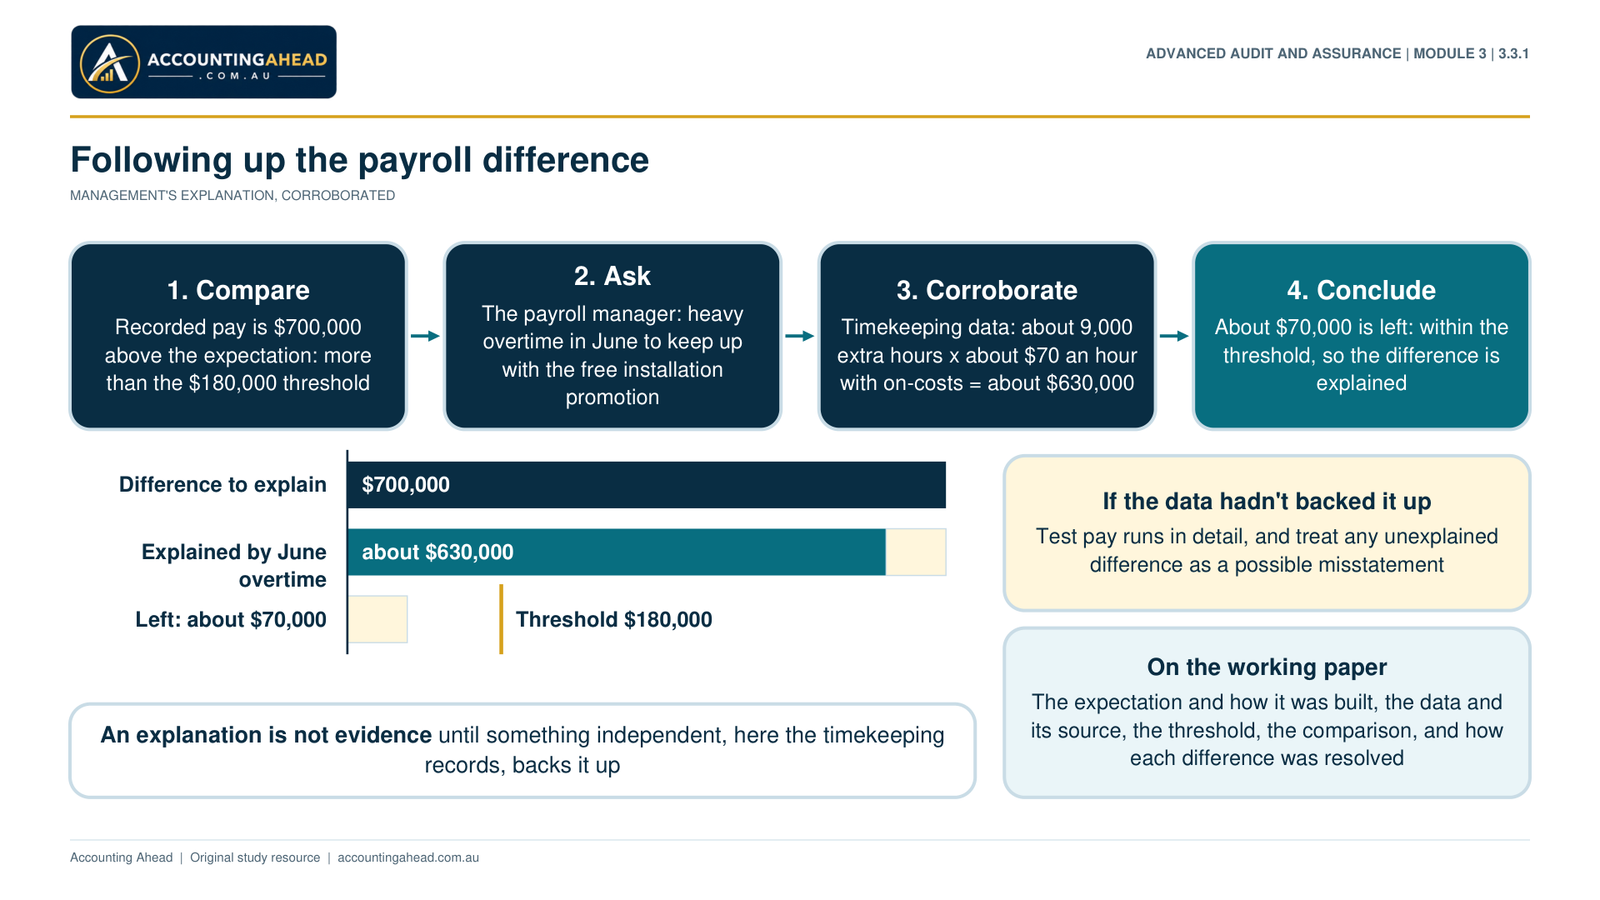
Part 3.3.1 · Substantive Analytical Procedures
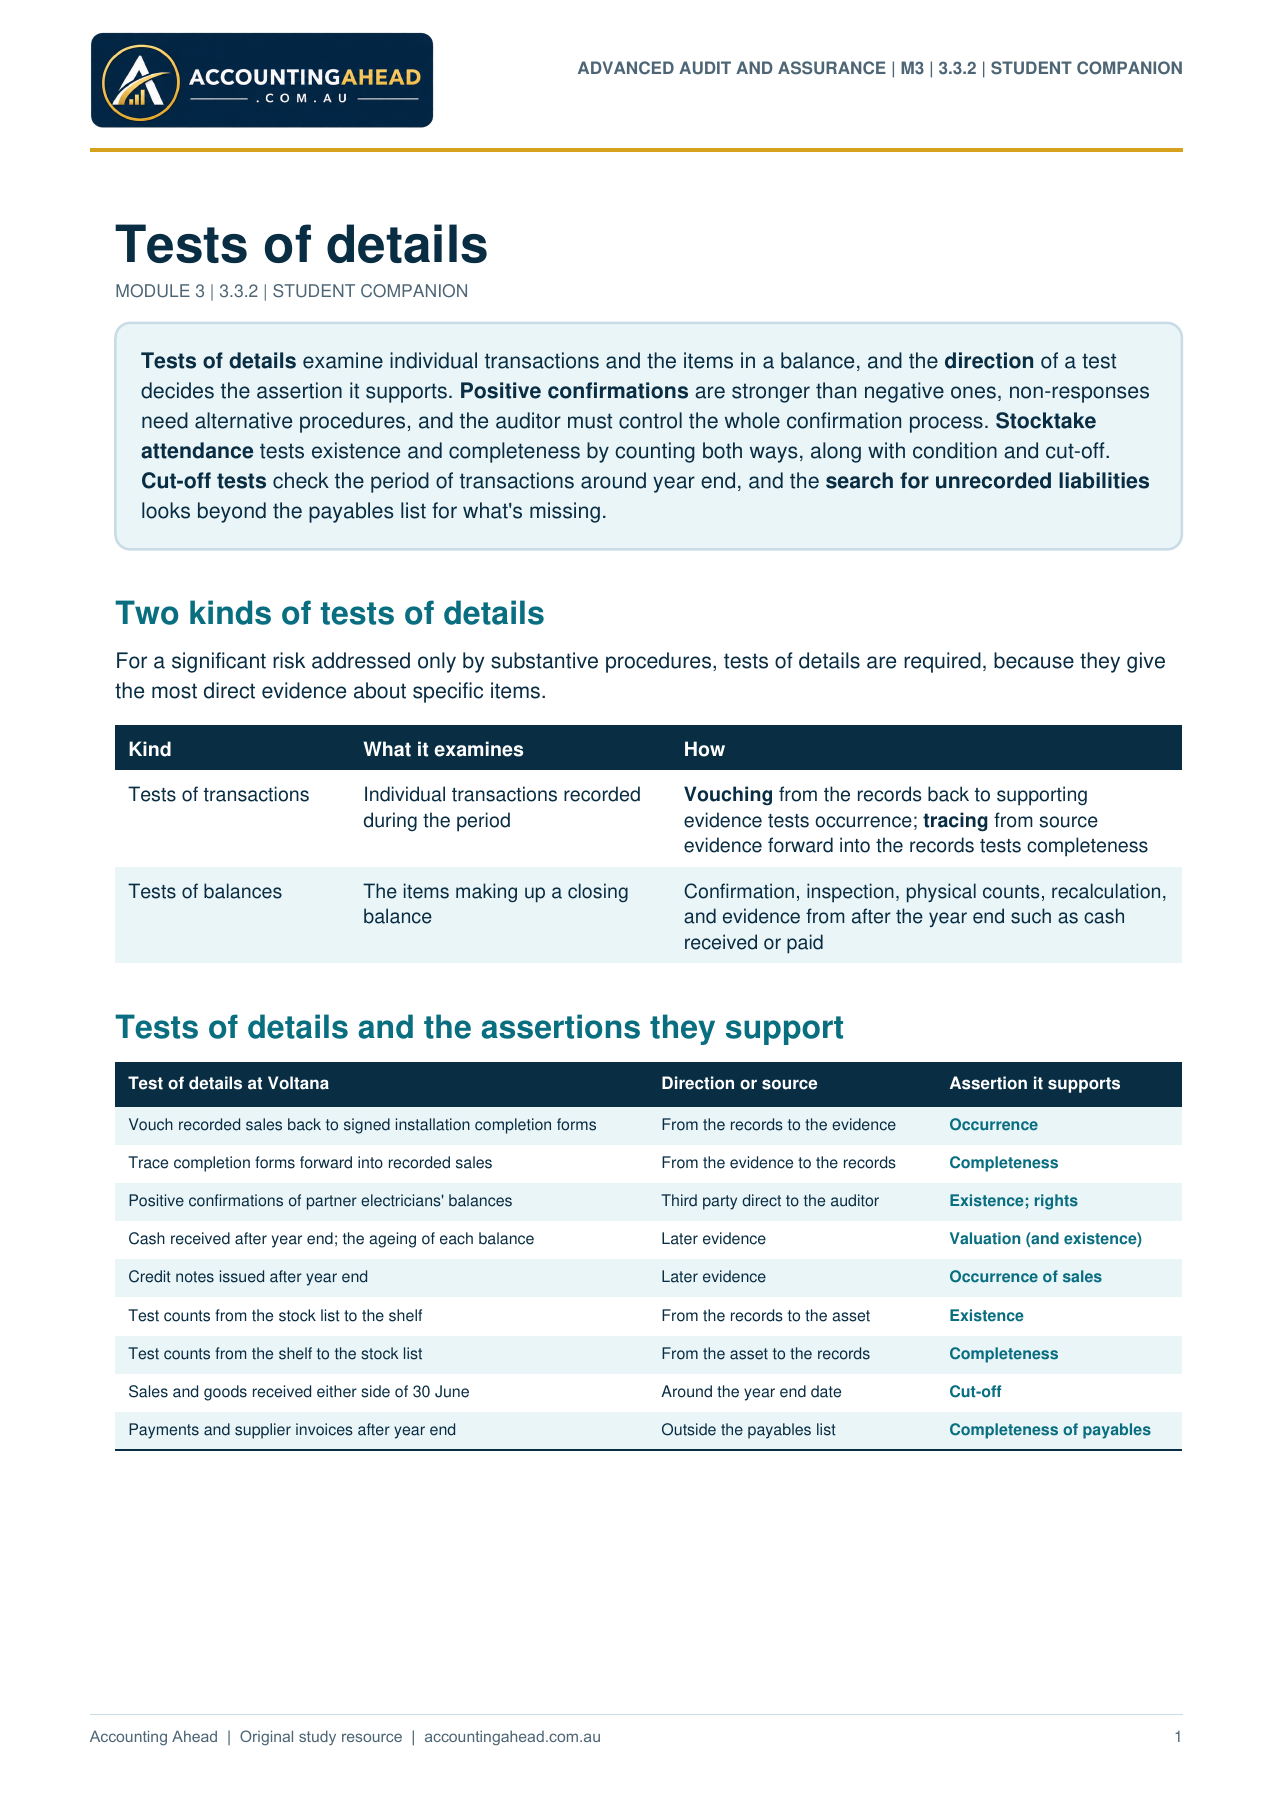
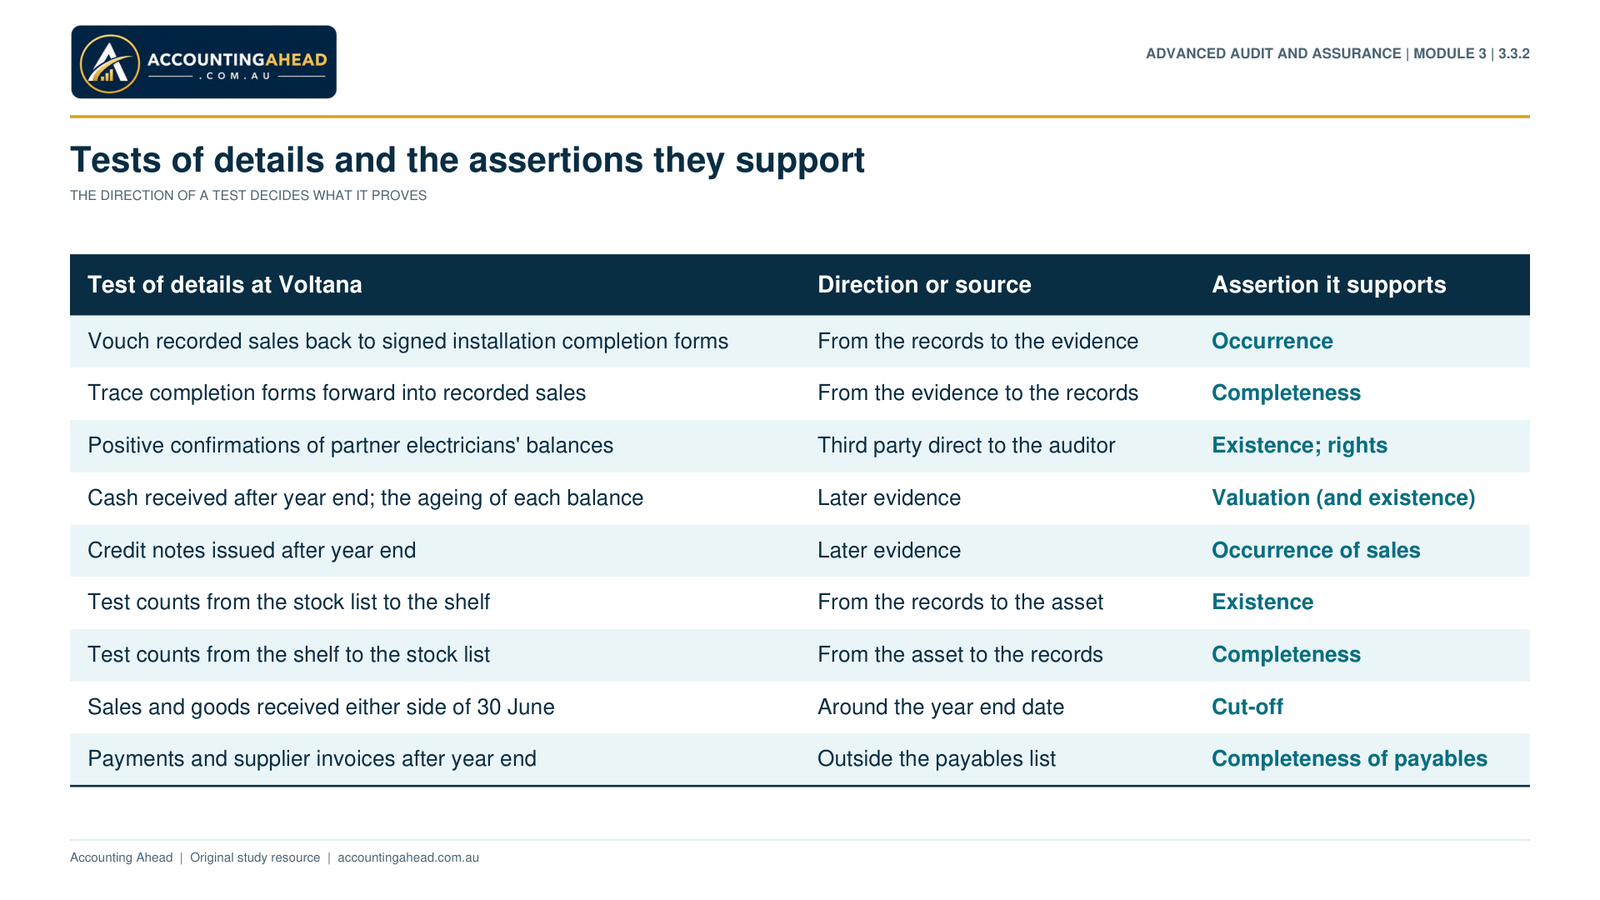
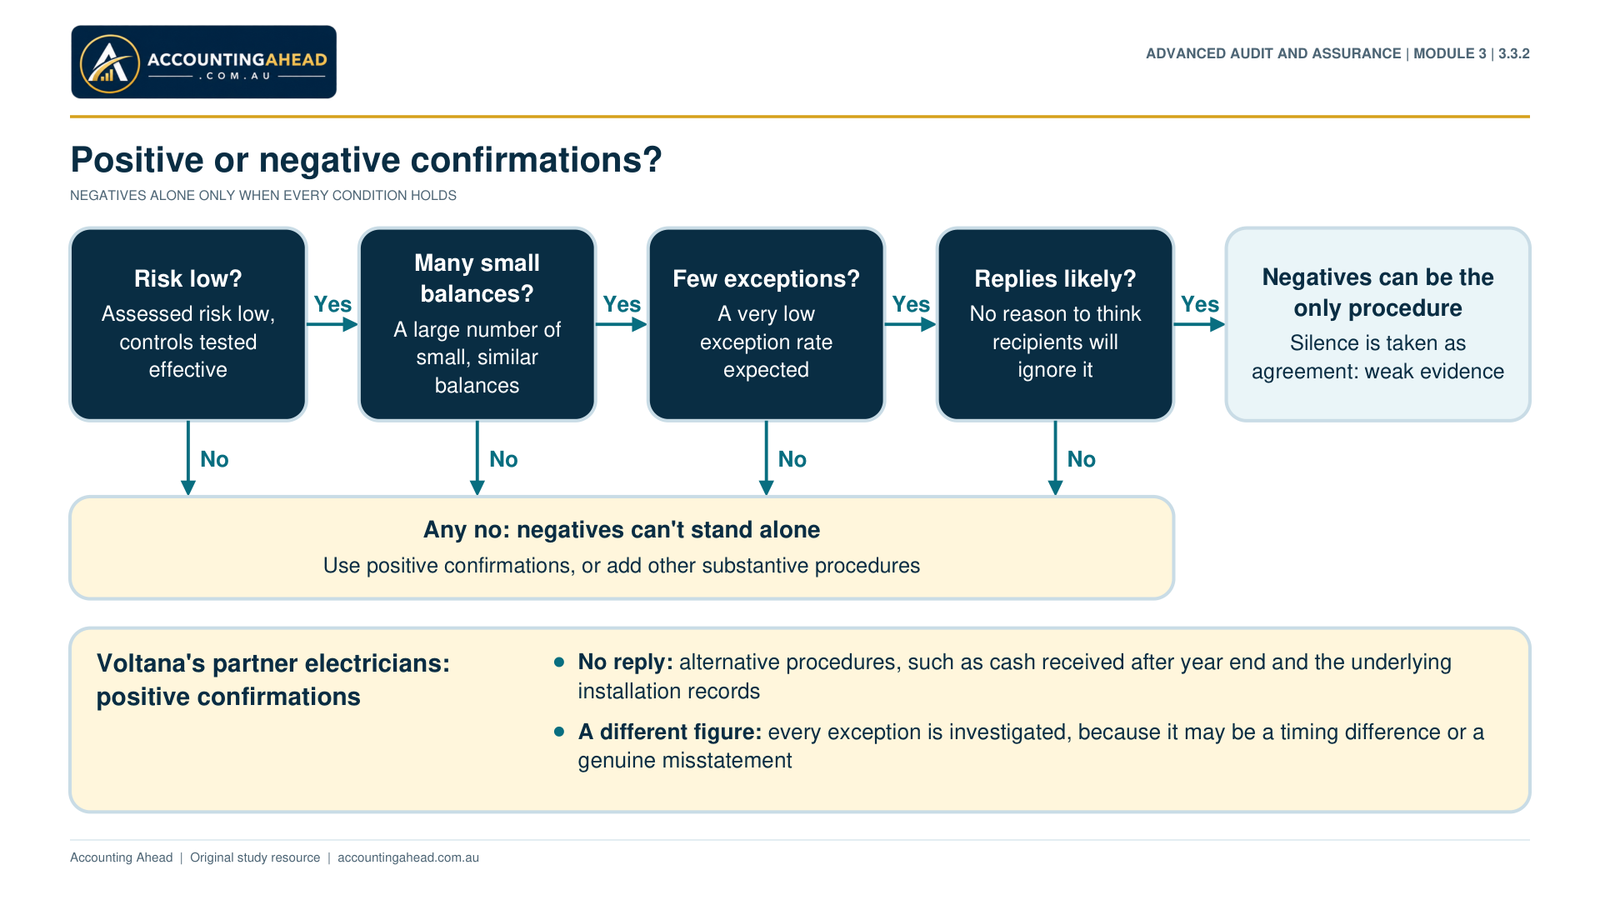
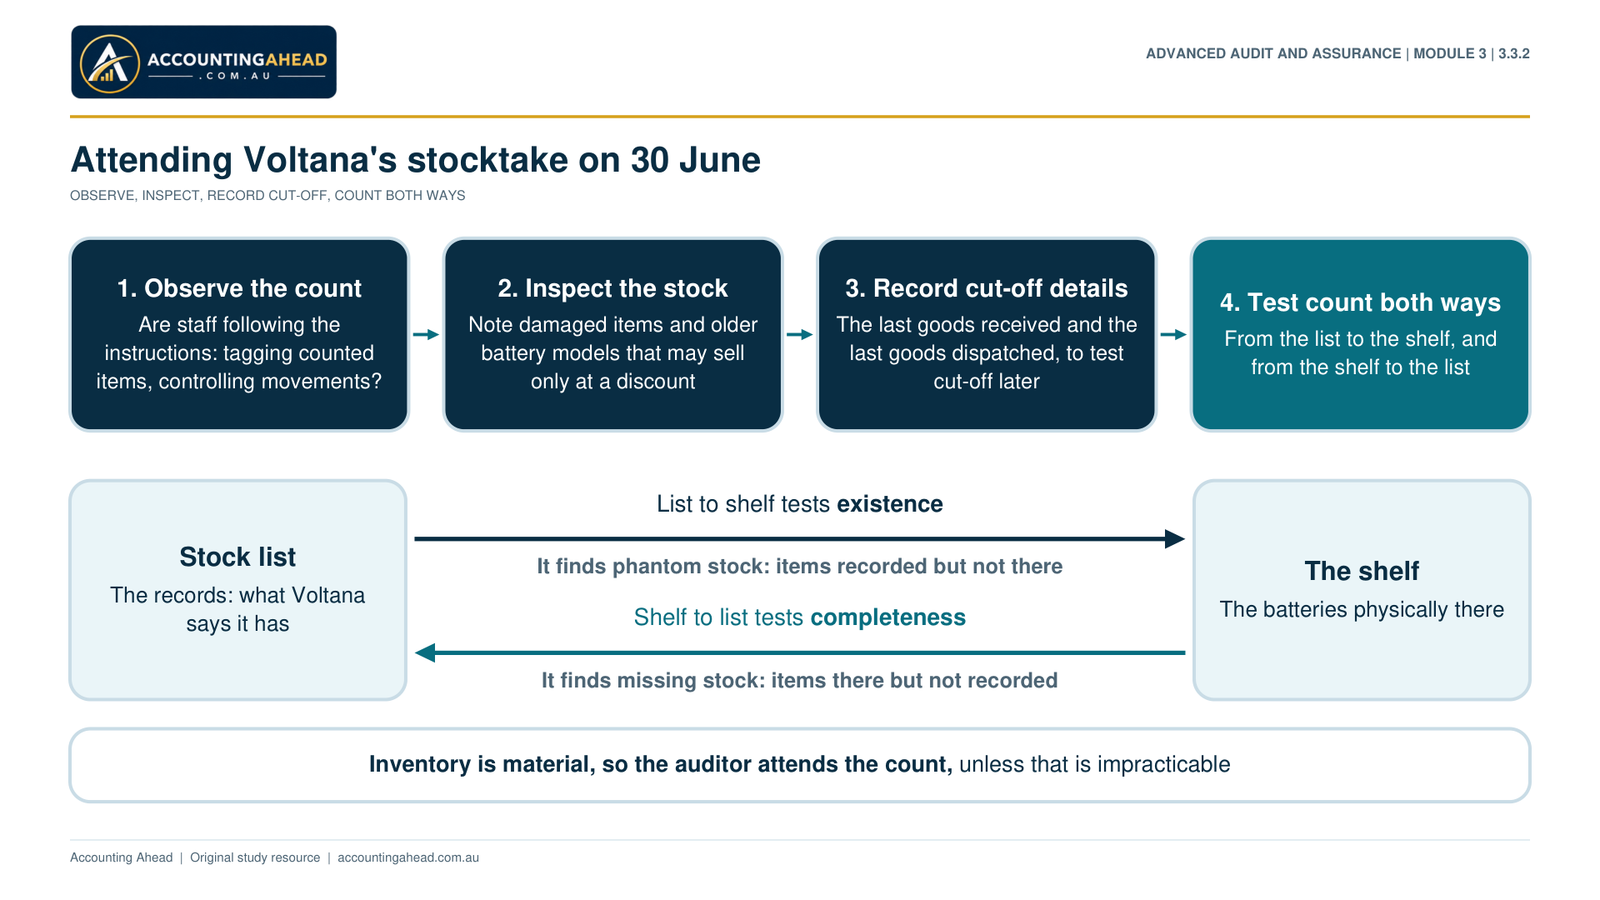
Part 3.3.2 · Tests of Details
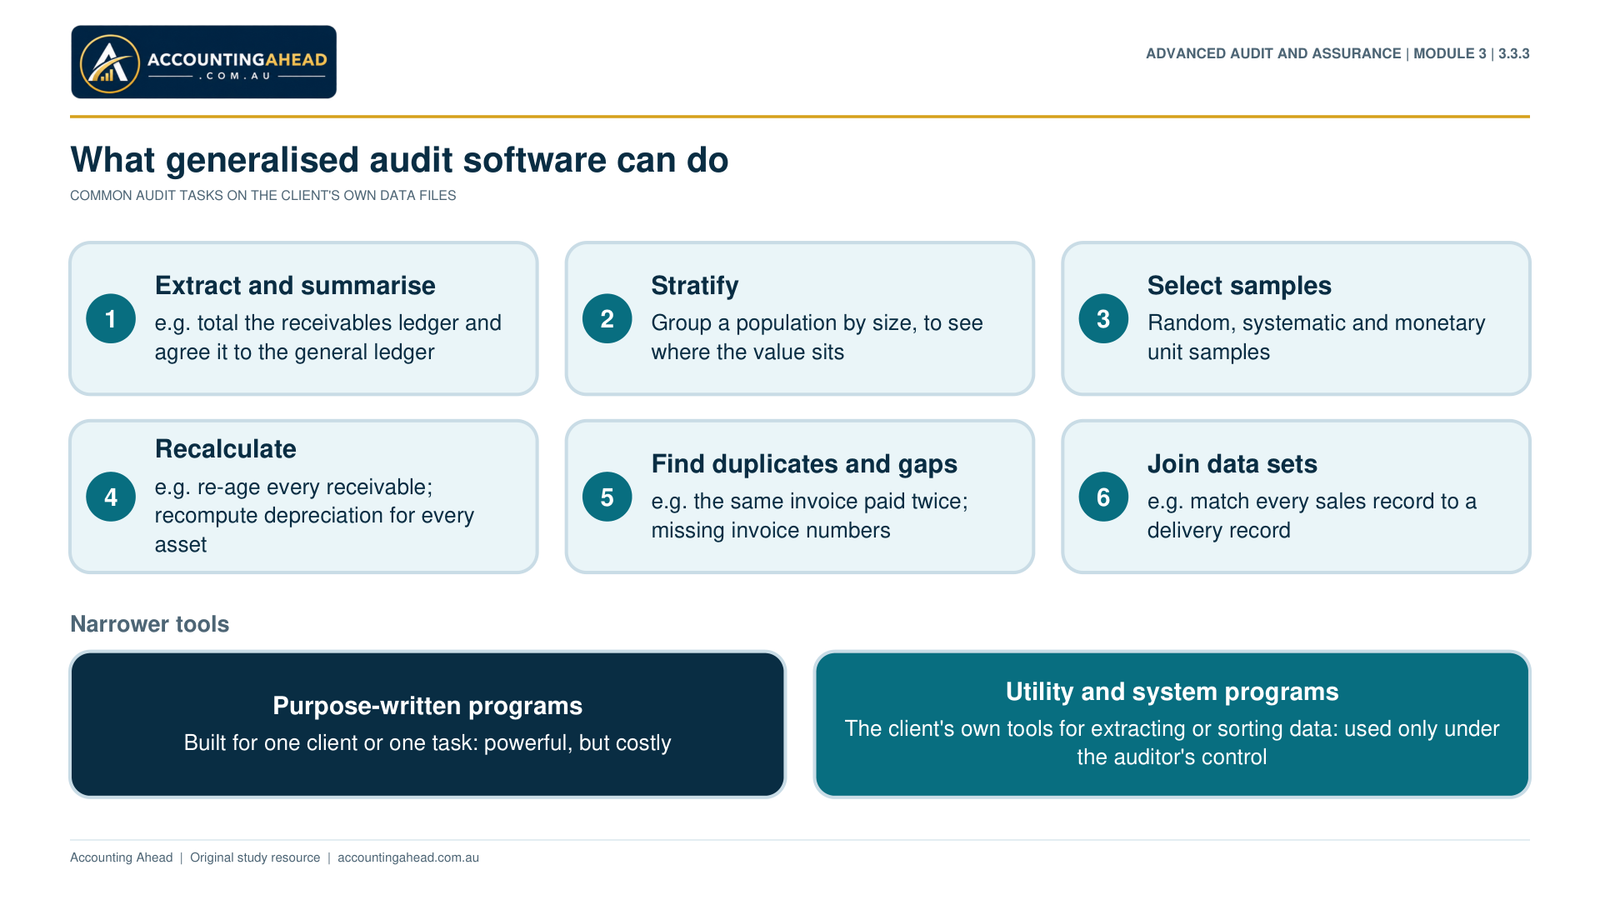
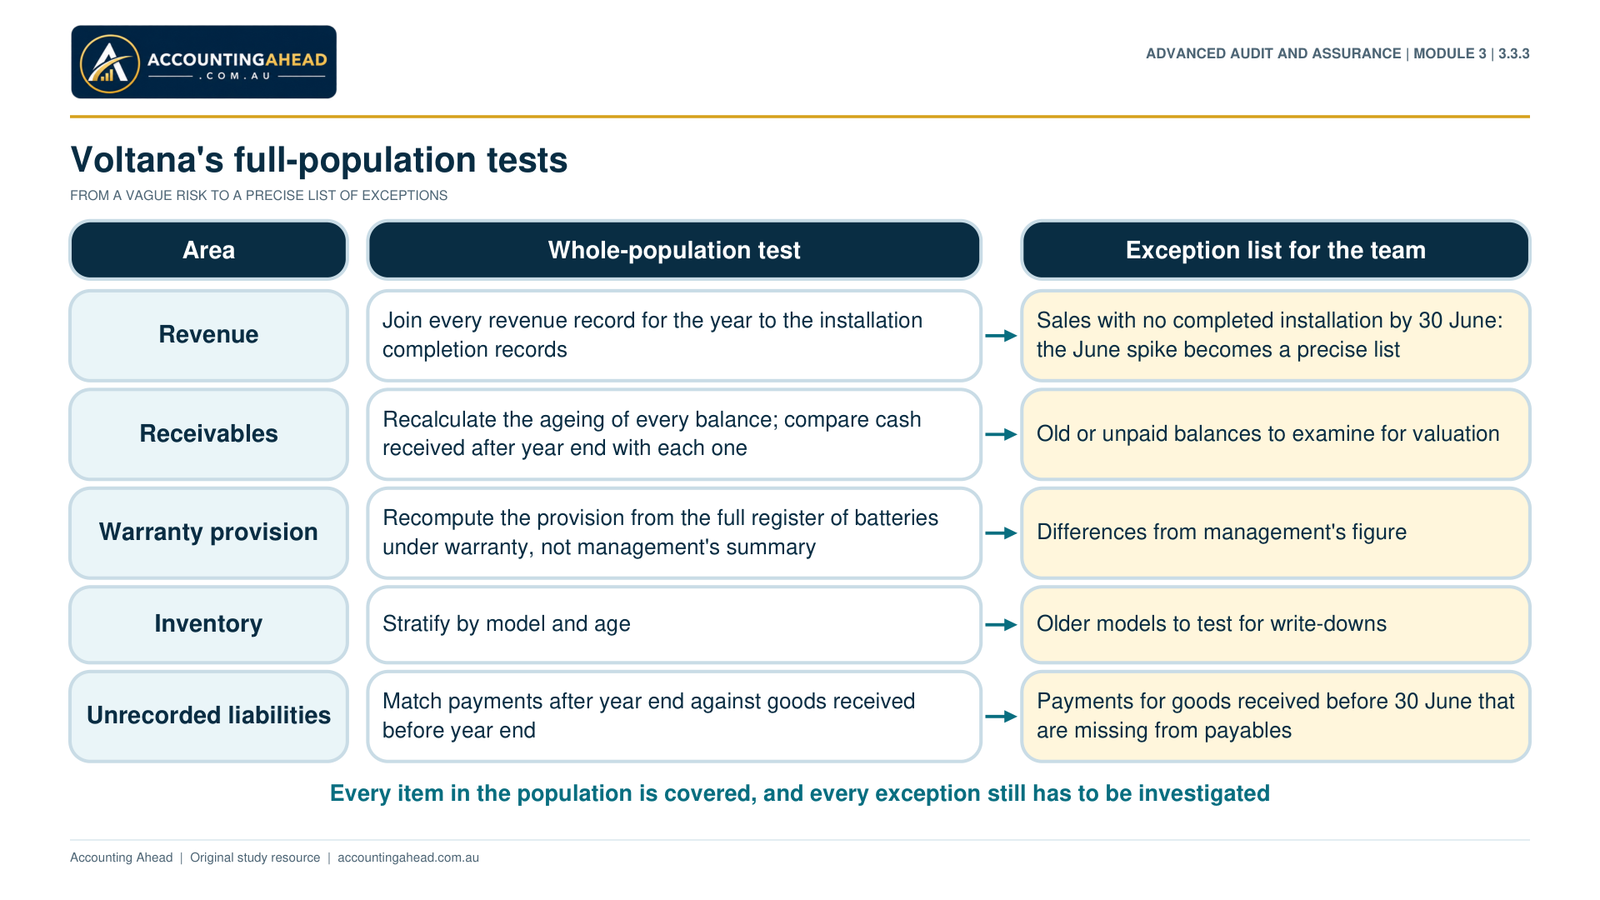
Part 3.3.3 · CAATs and Data Analytics in Substantive Work
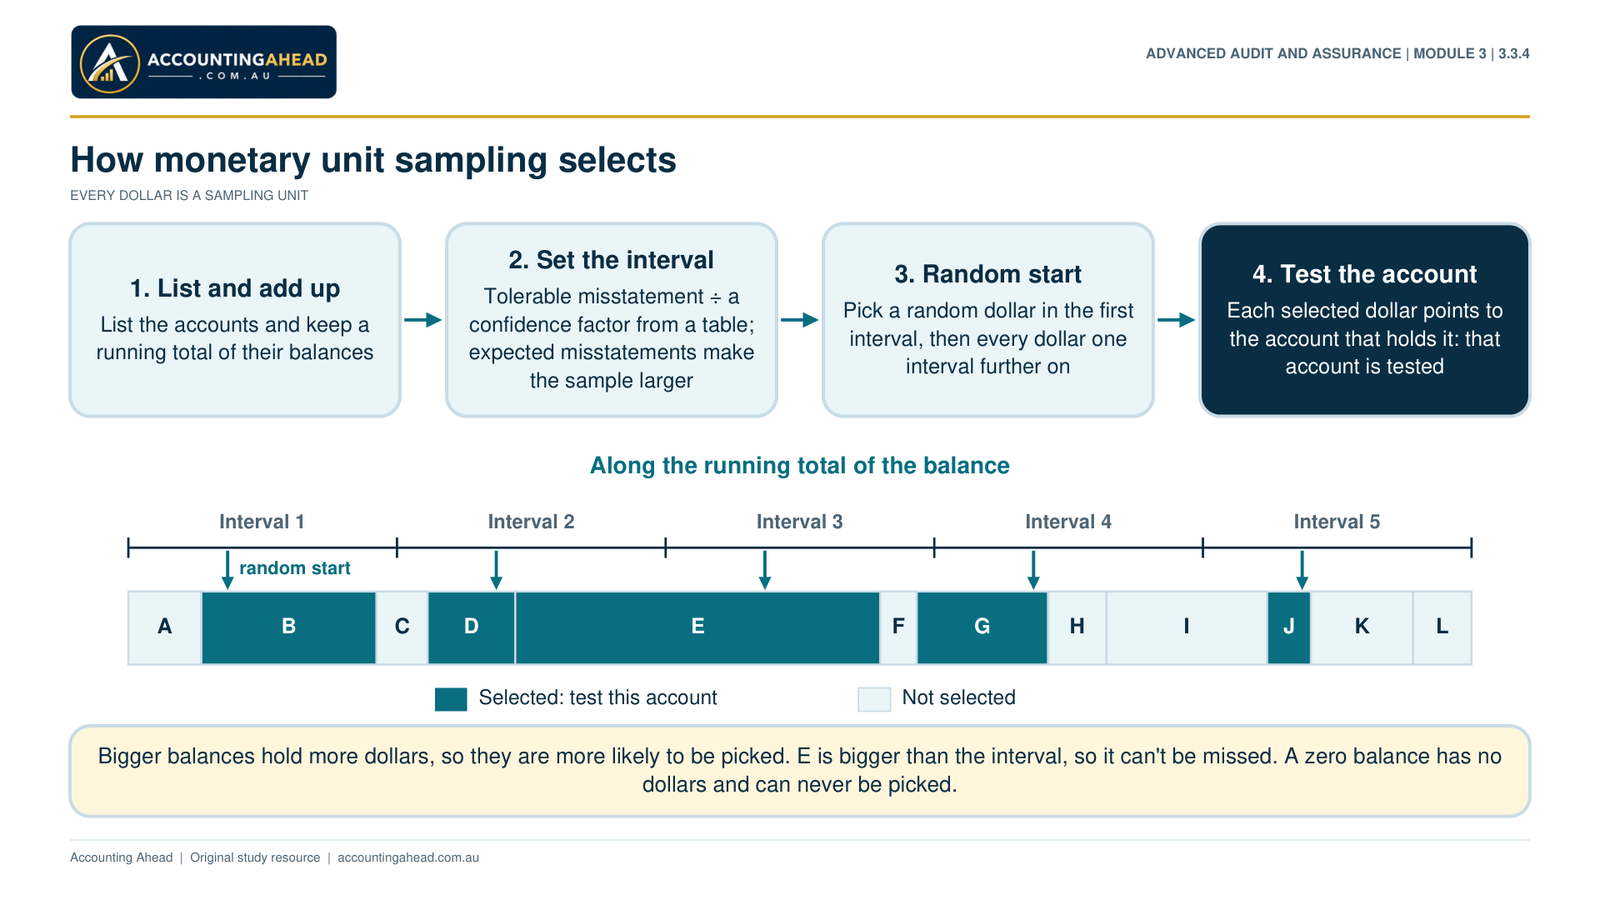
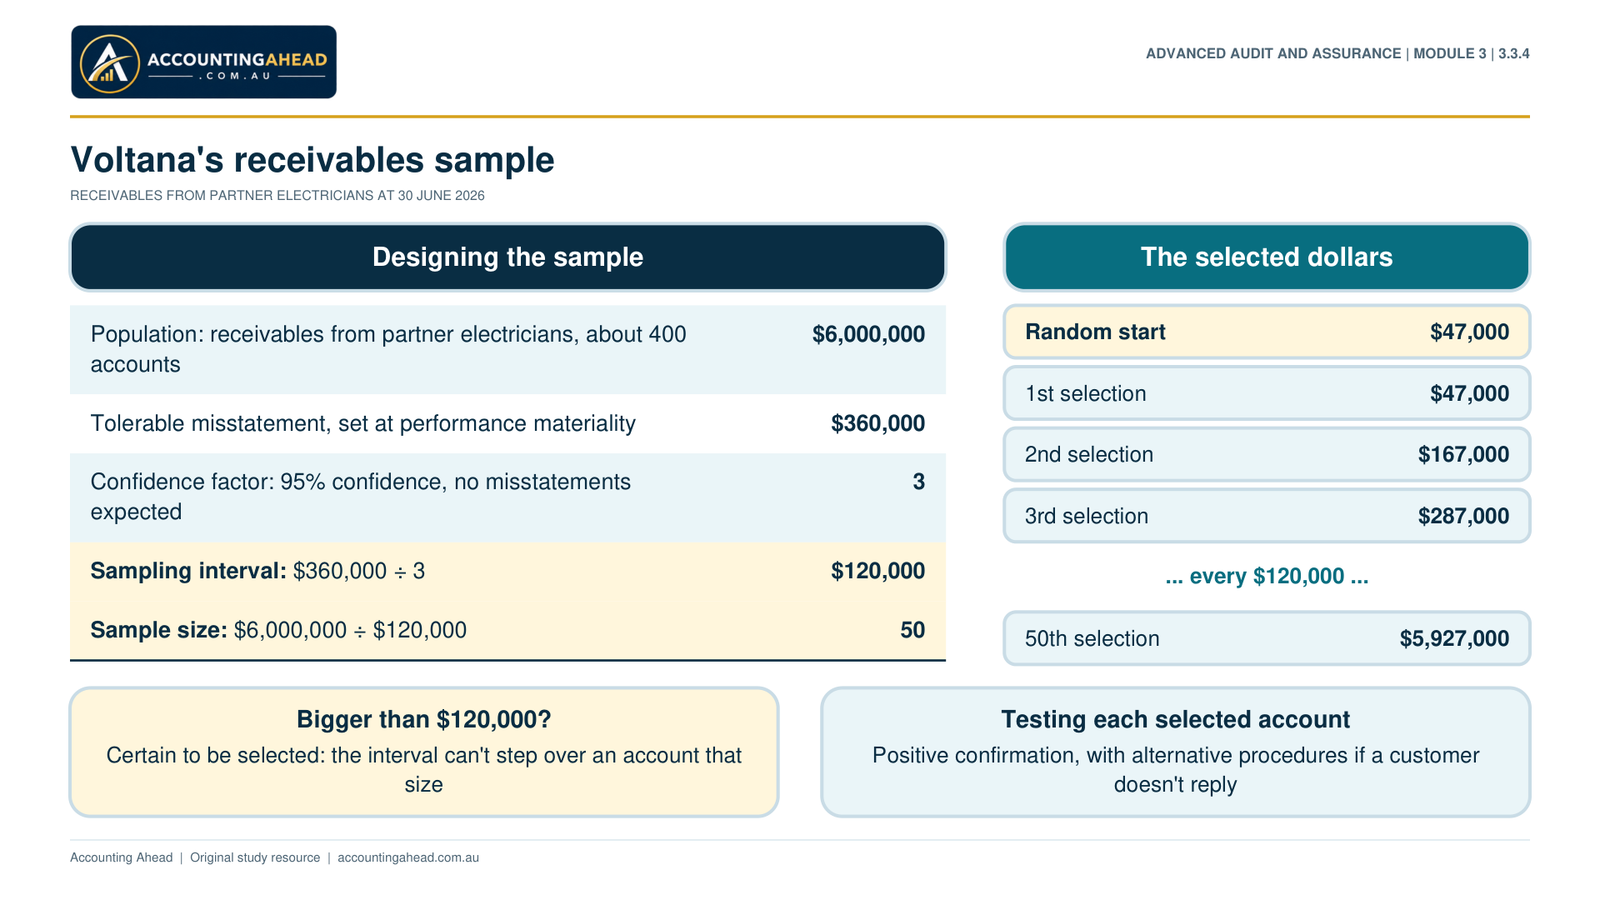
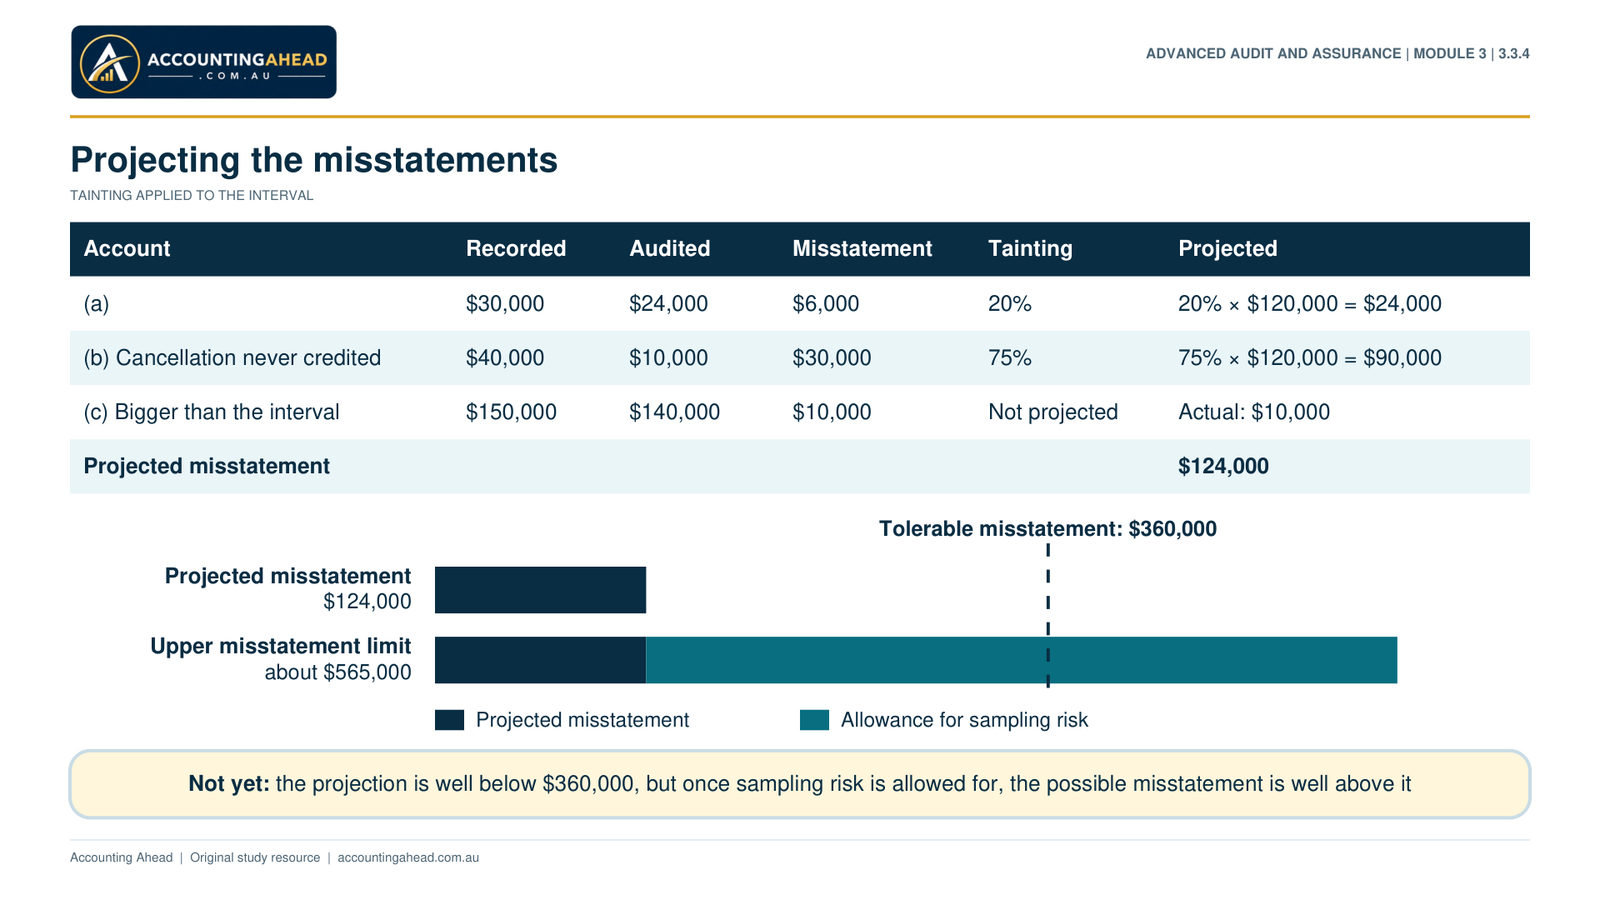
Part 3.3.4 · Monetary Unit Sampling
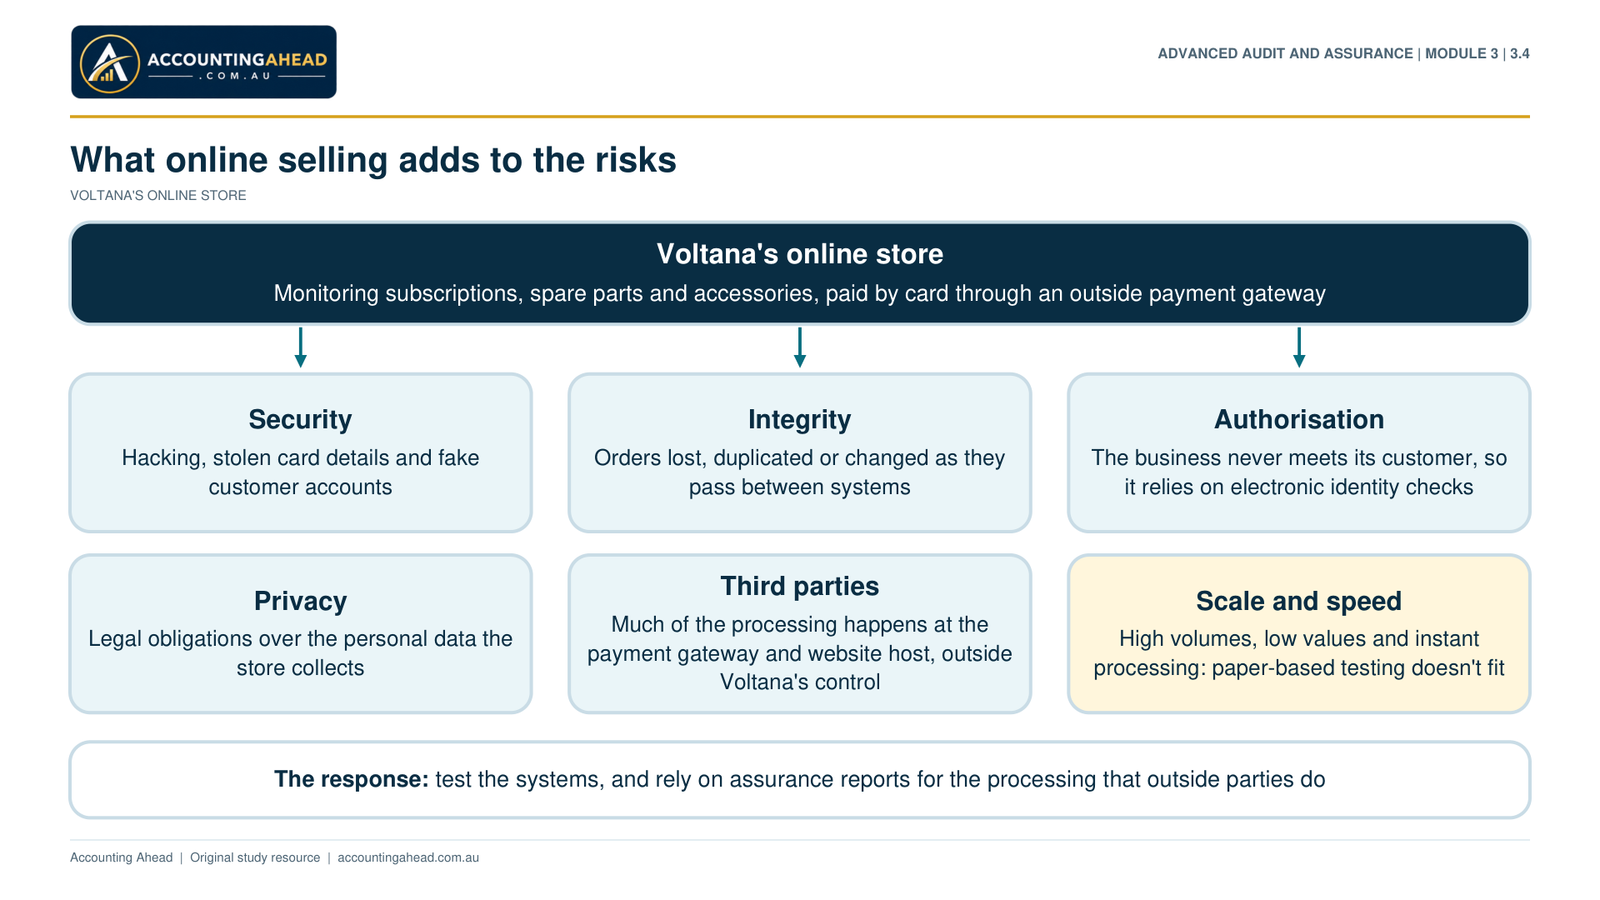
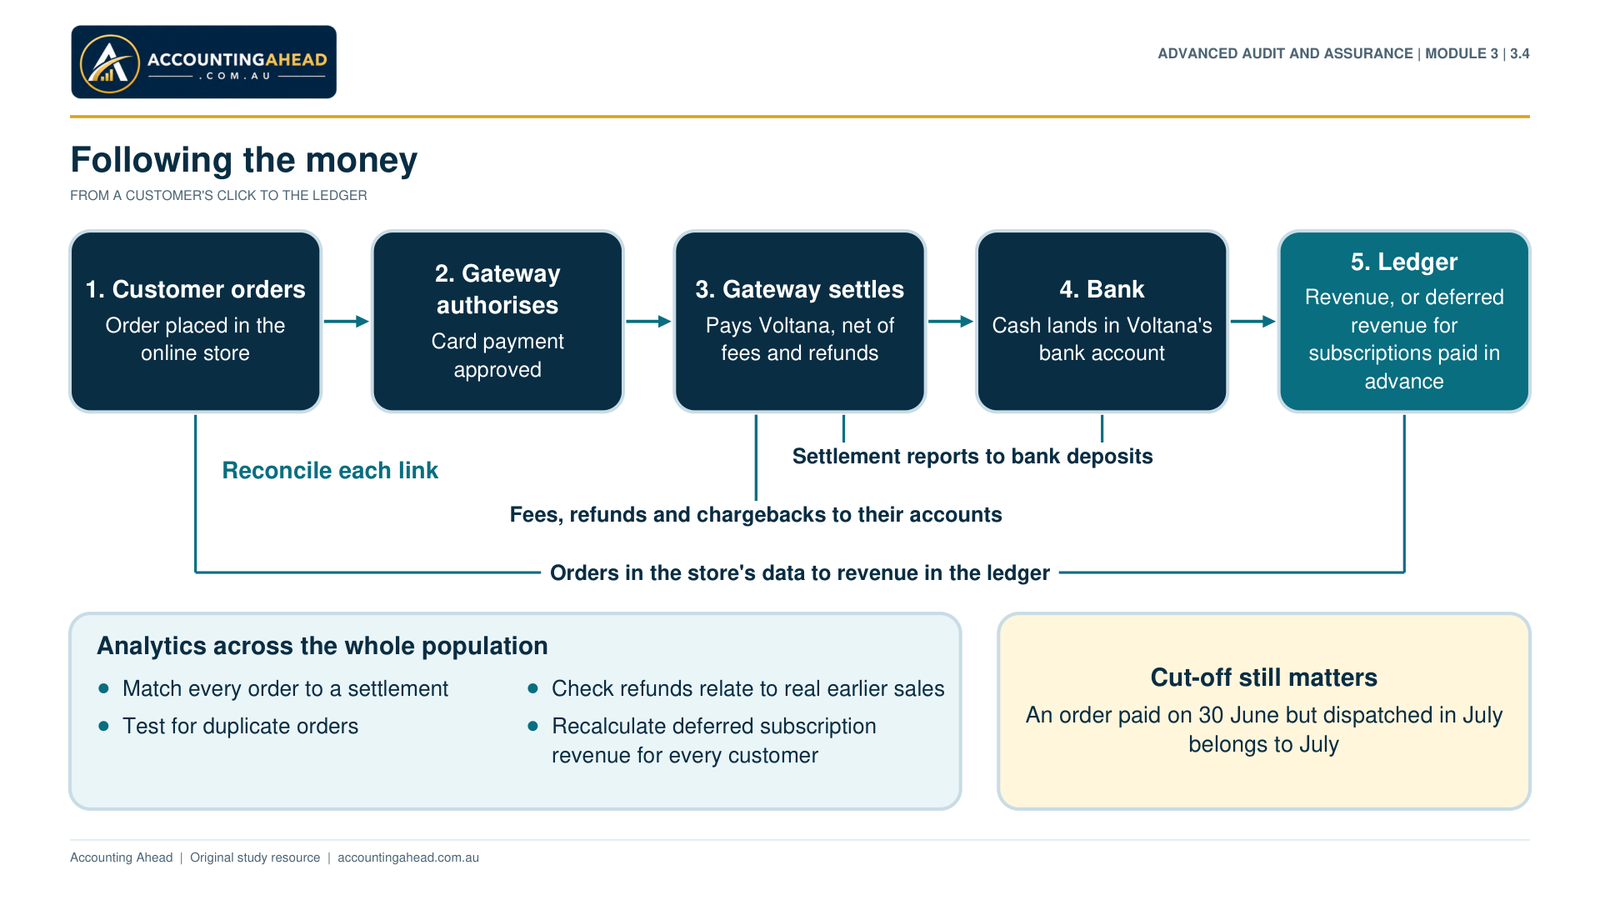
Part 3.4 · Evidence in an E-Commerce Environment
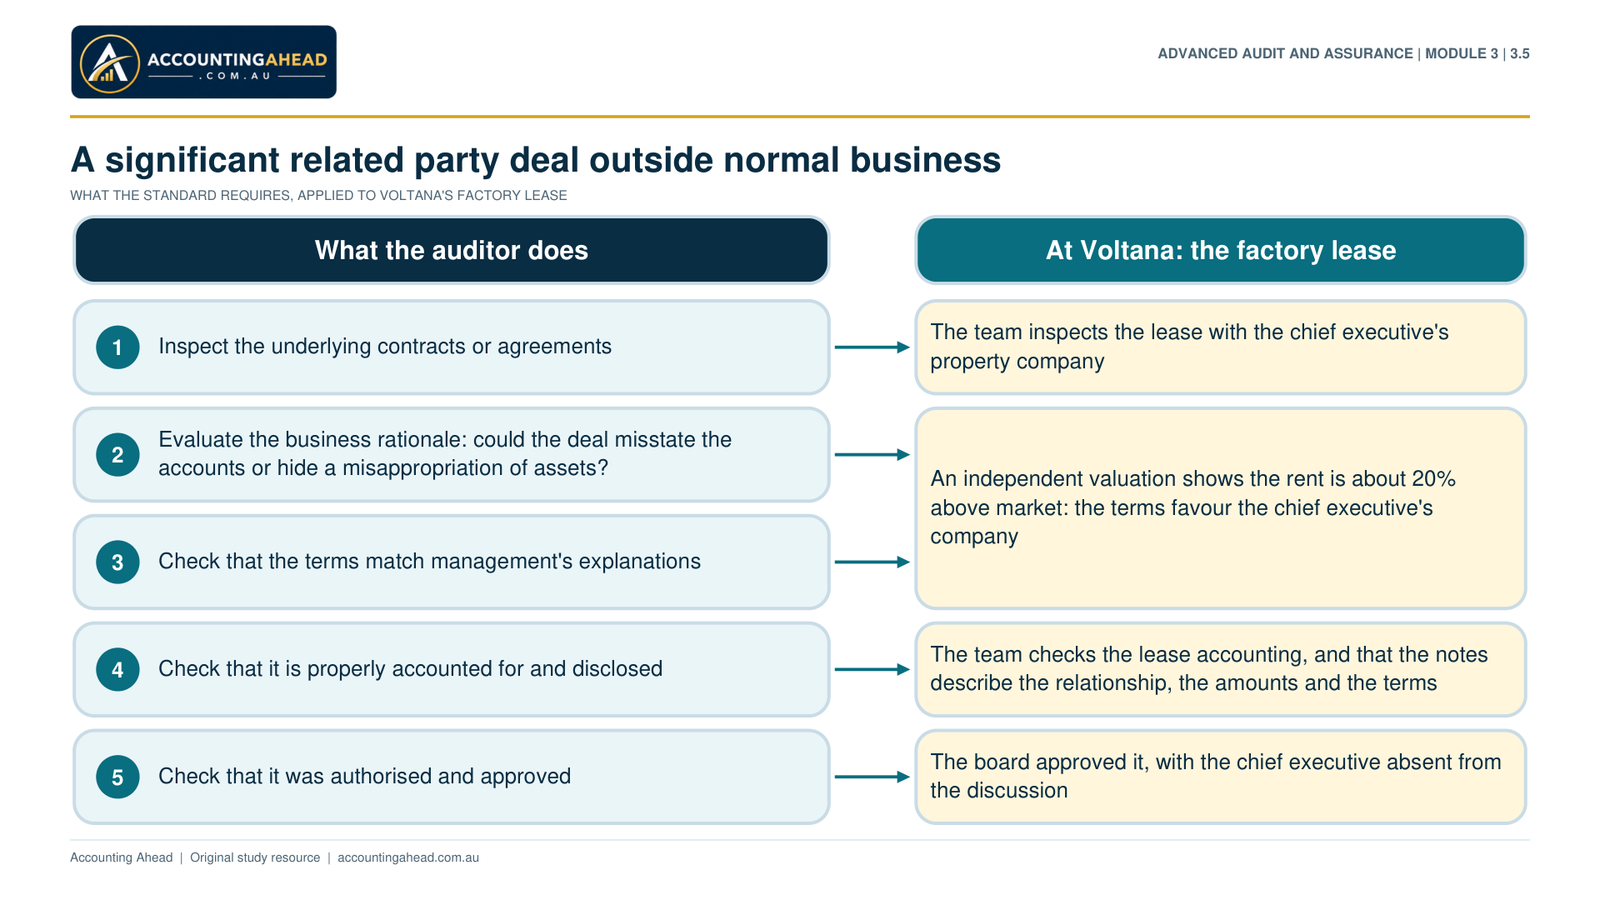
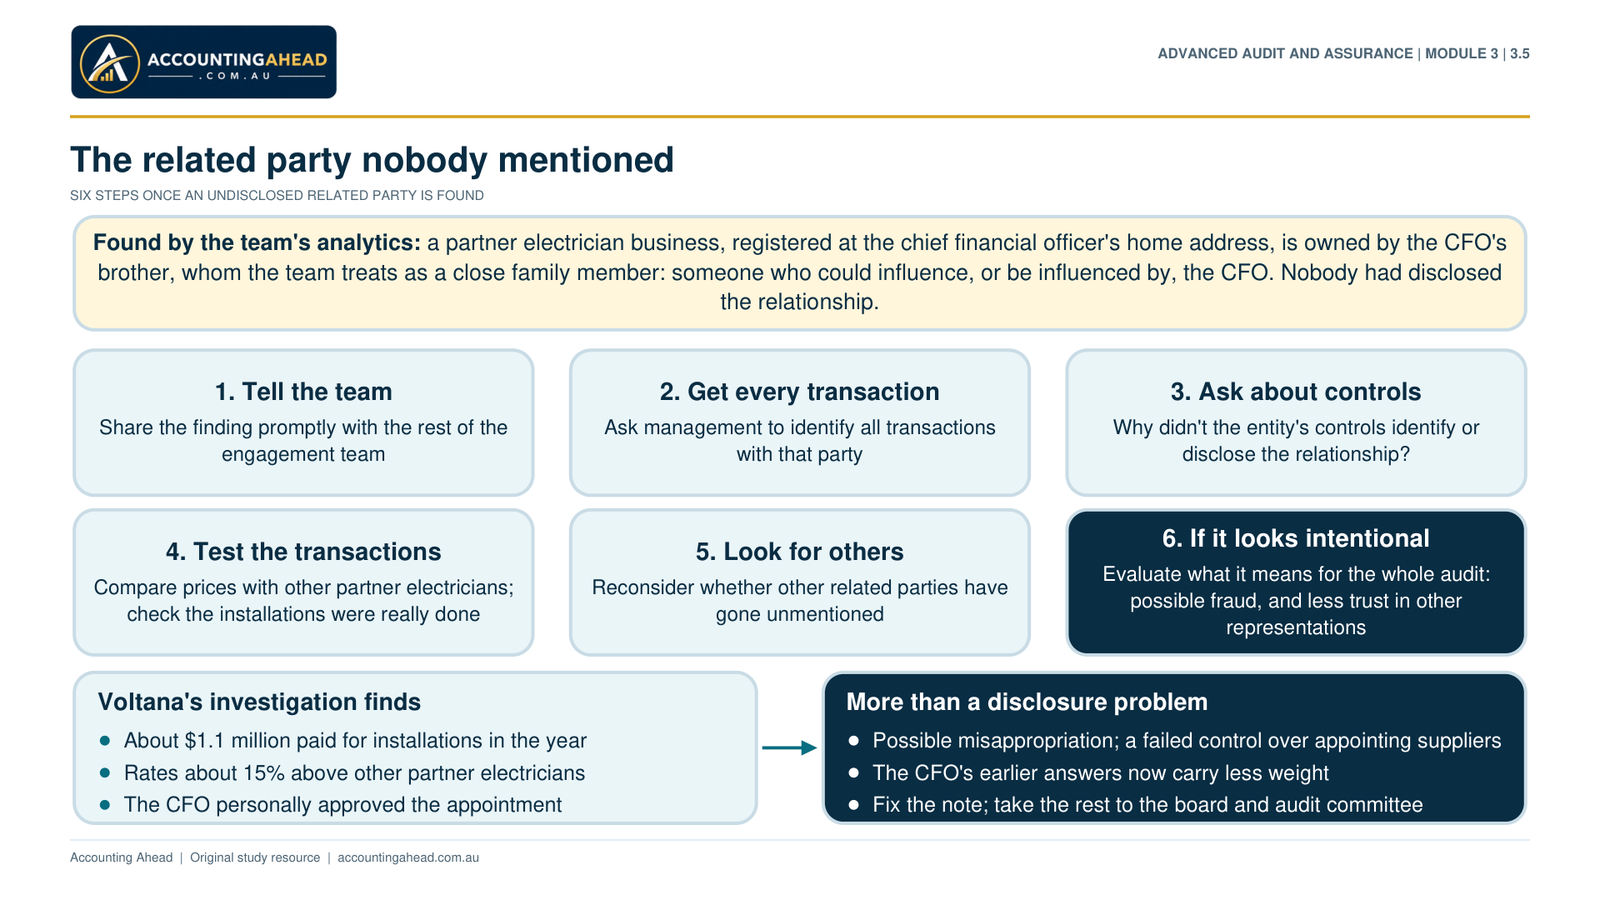
Part 3.5 · Audit Procedures for Related Parties
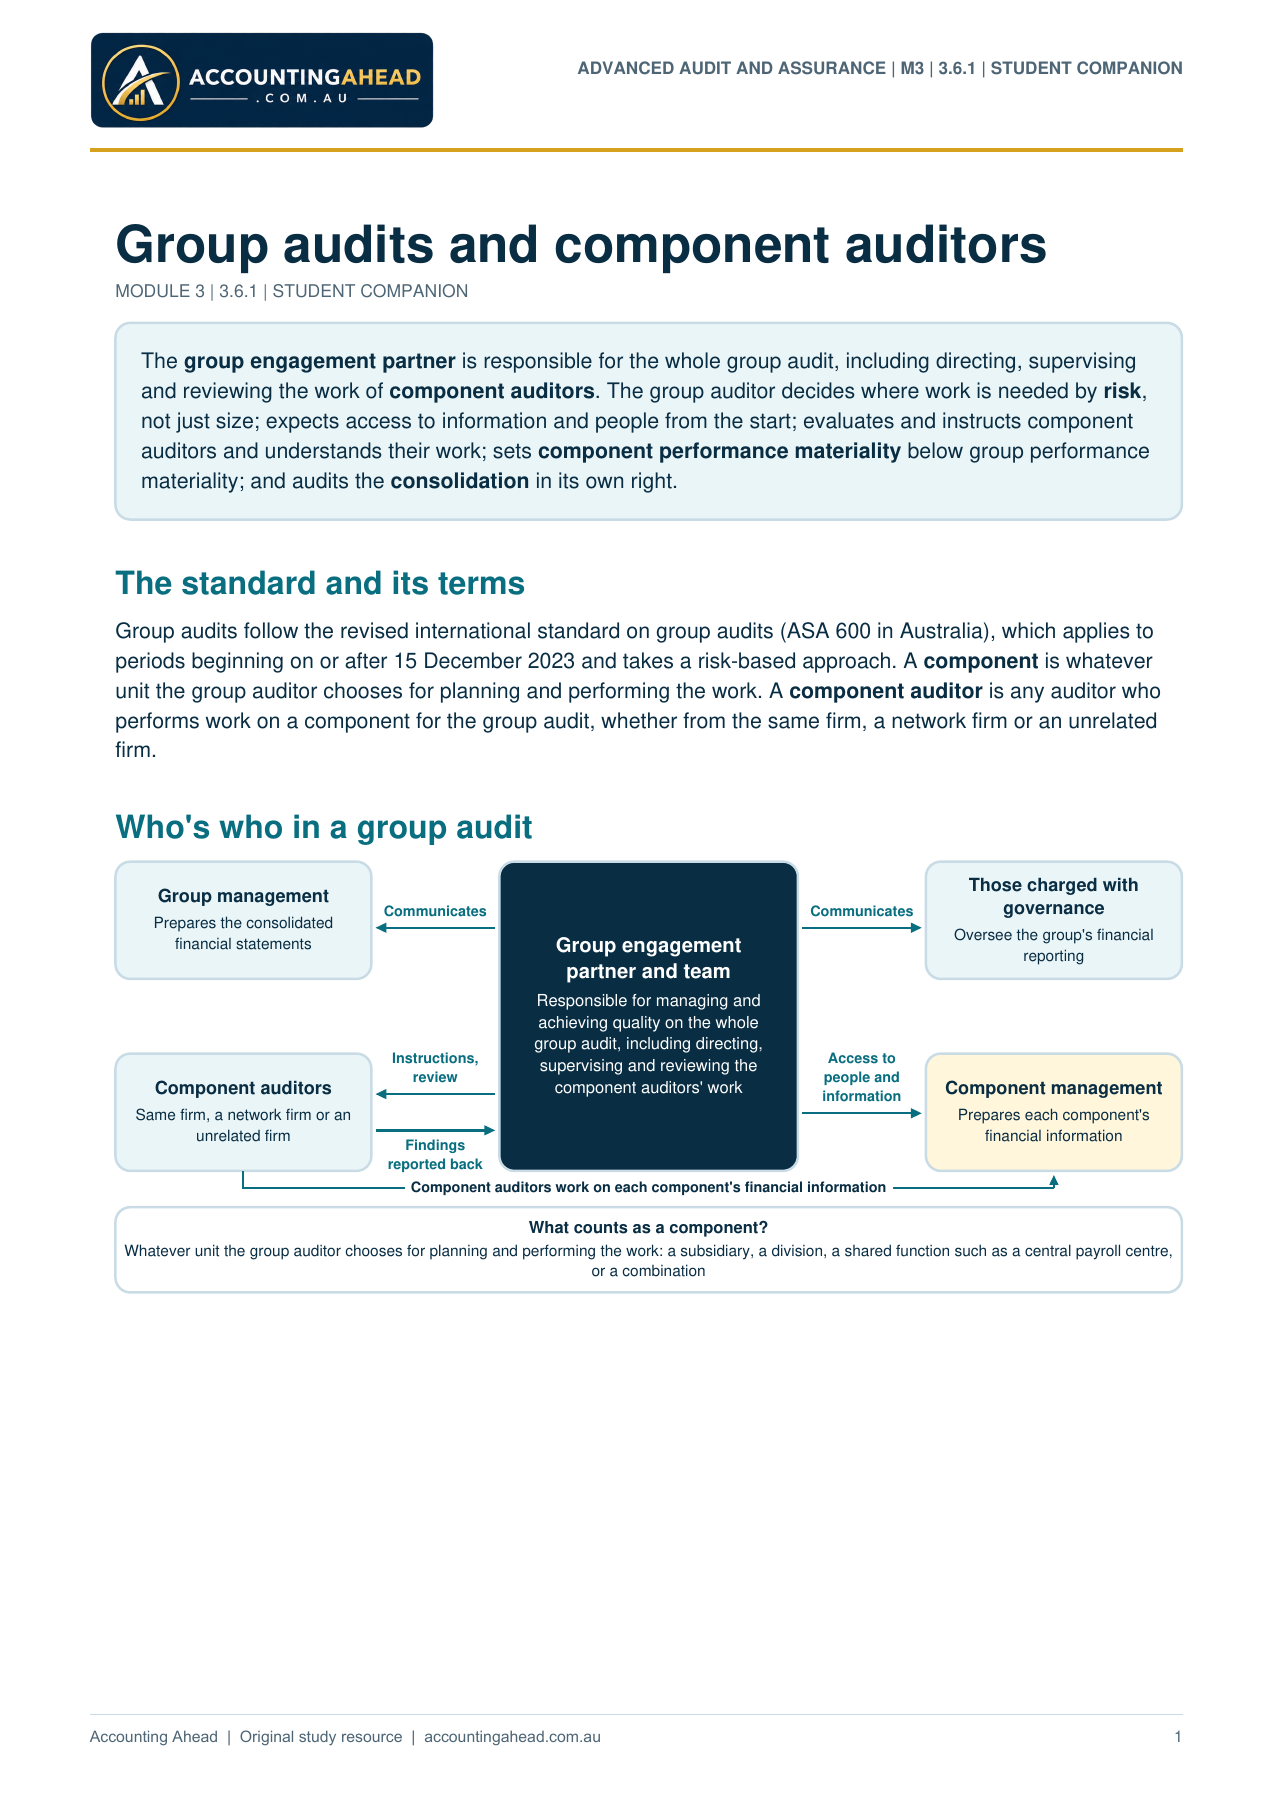
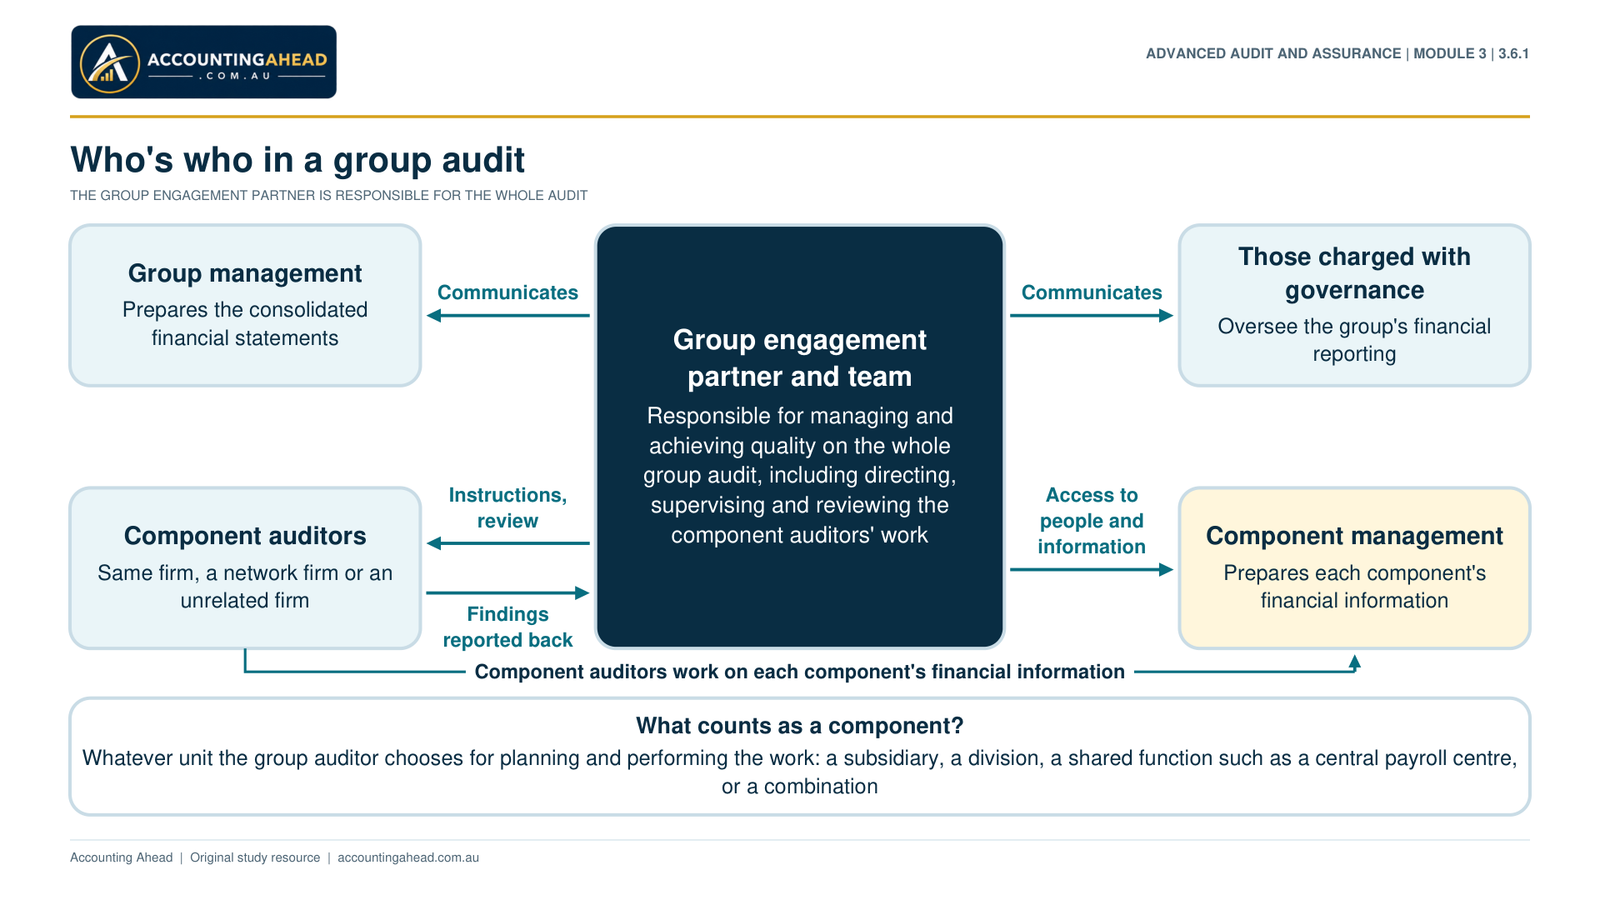
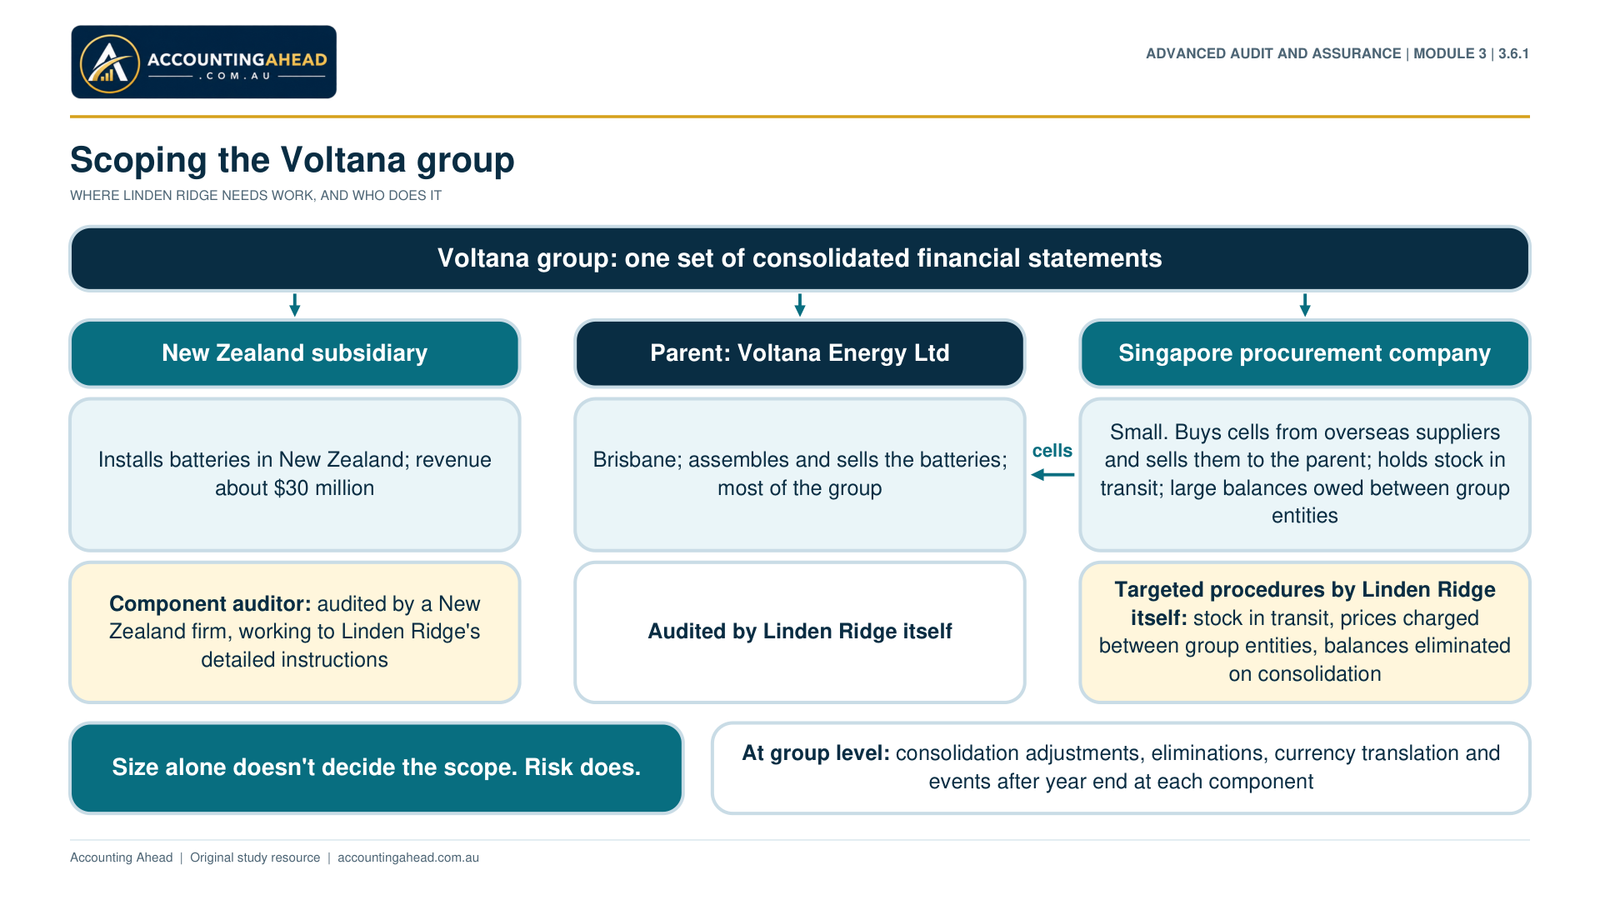
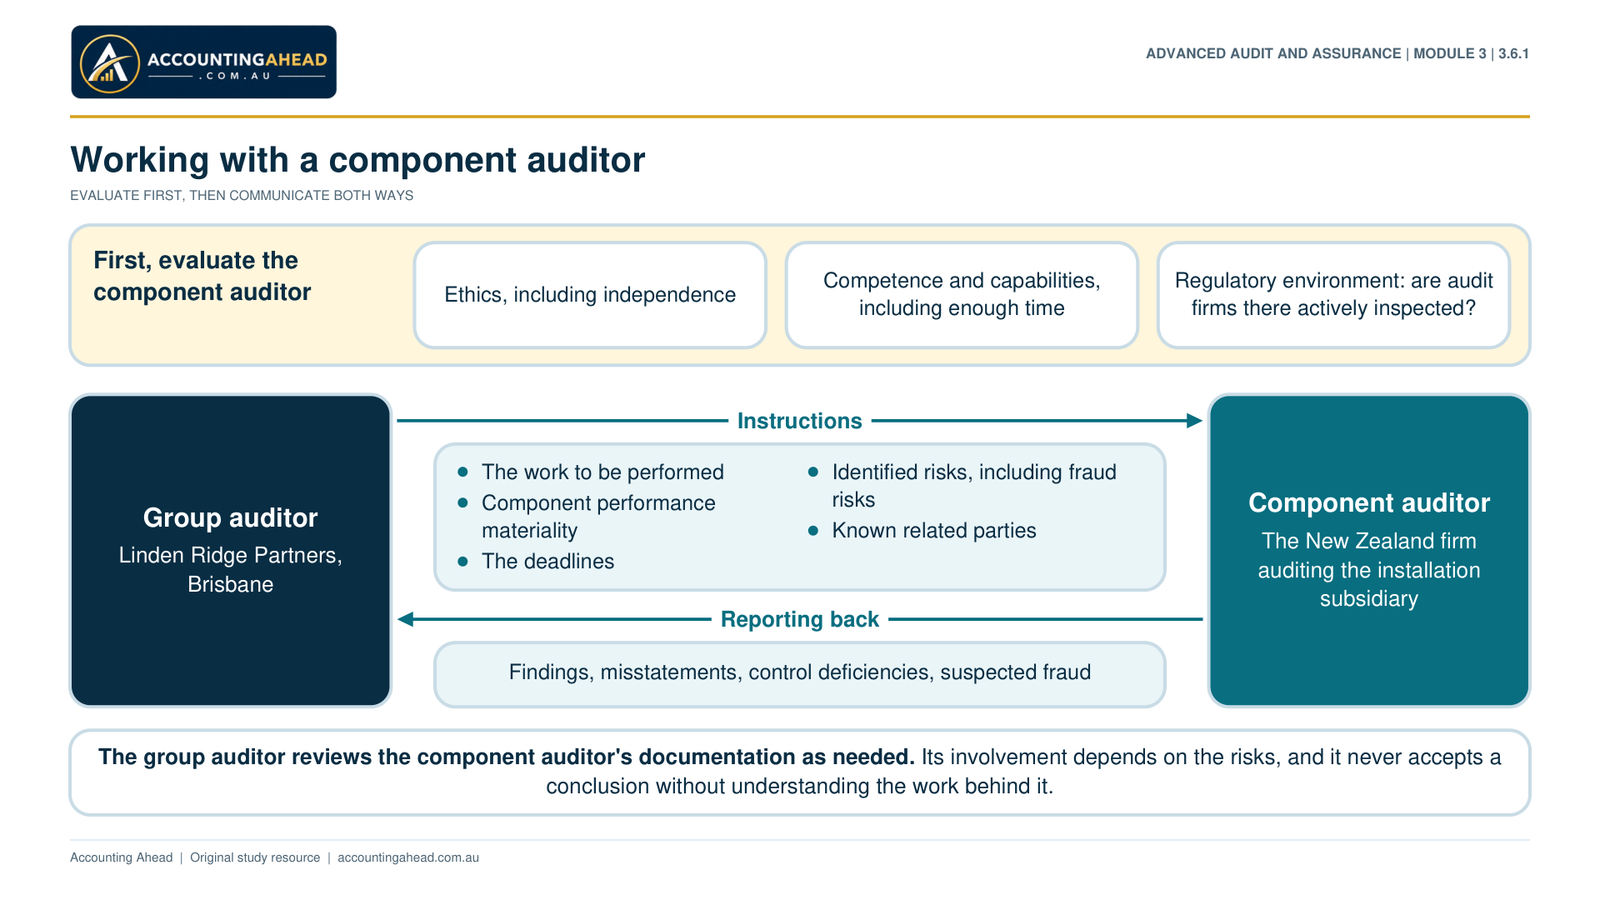
Part 3.6.1 · Group Audits and Component Auditors
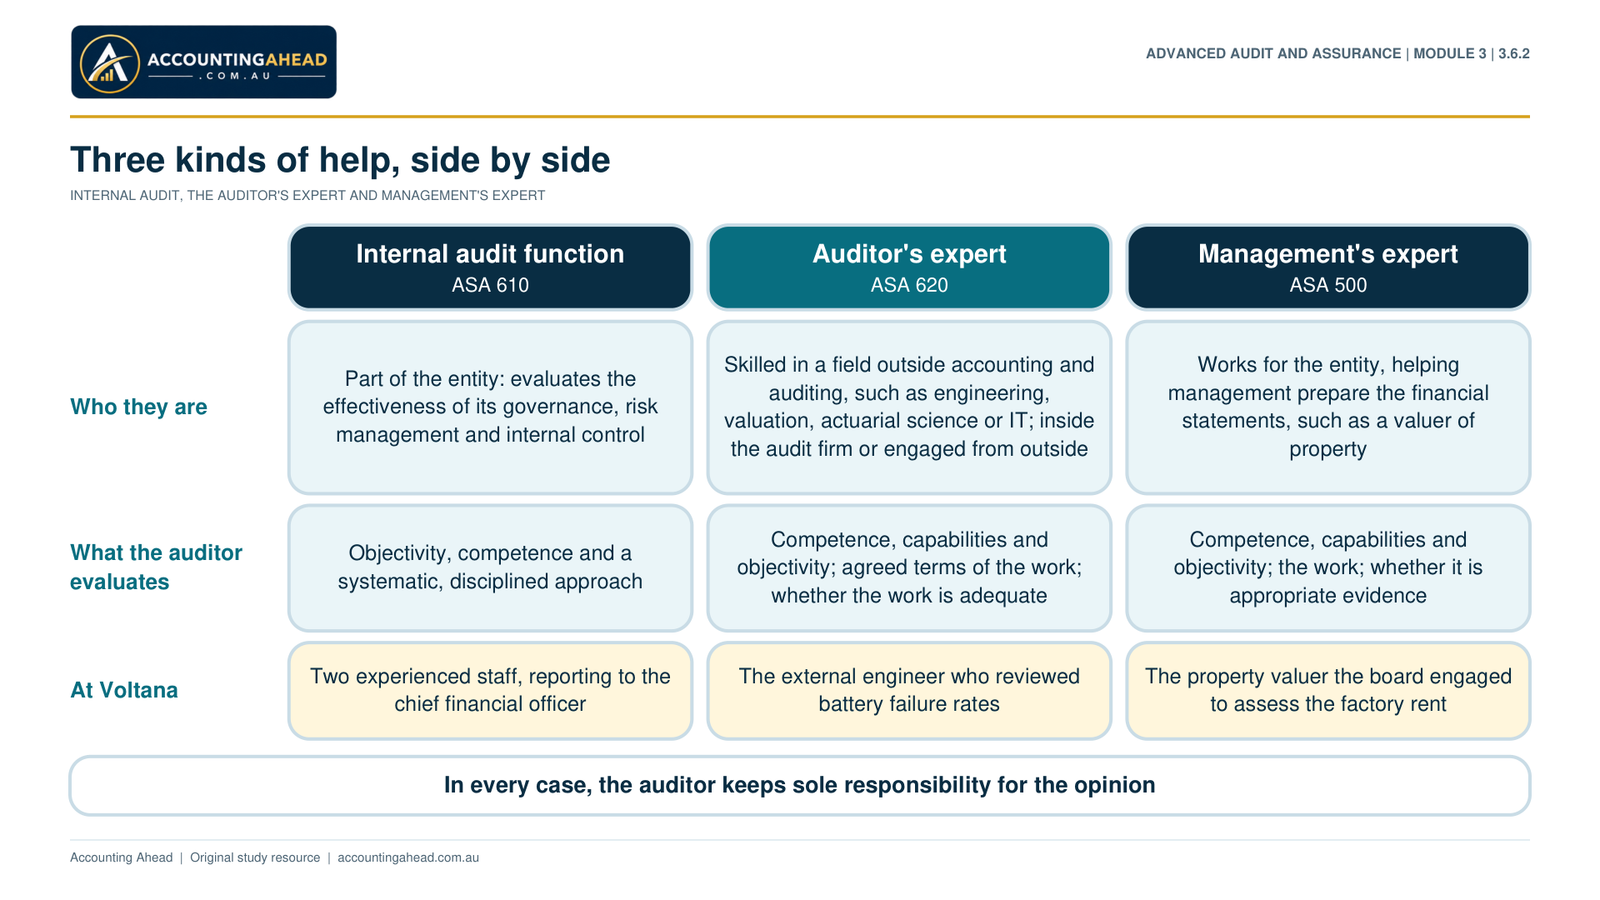
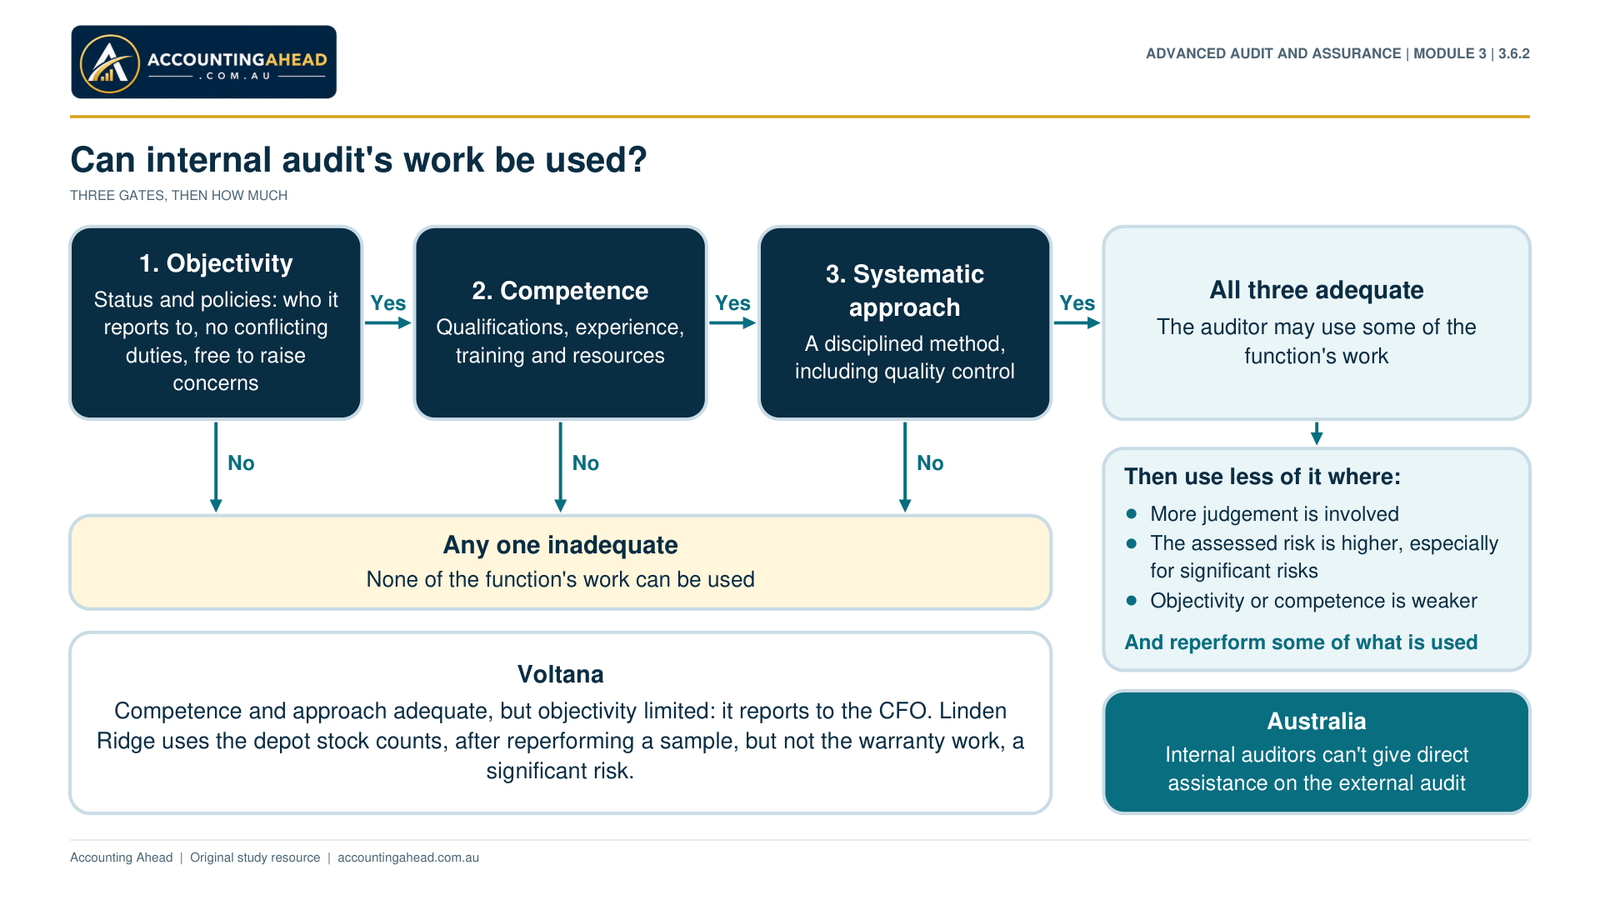
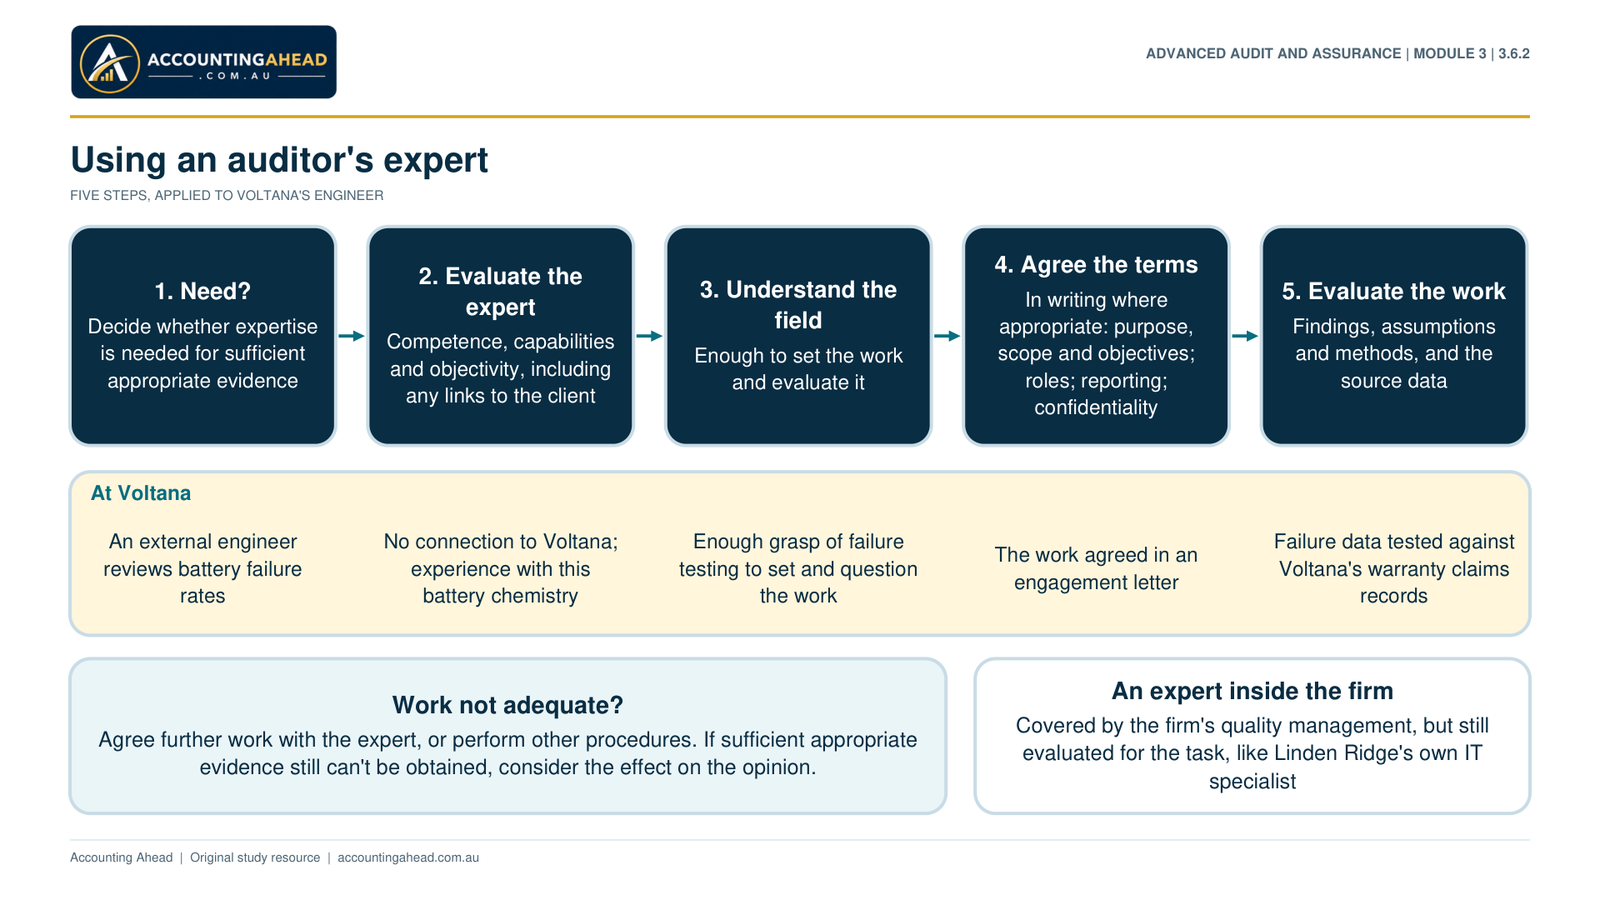
Part 3.6.2 · Using Internal Auditors and Experts
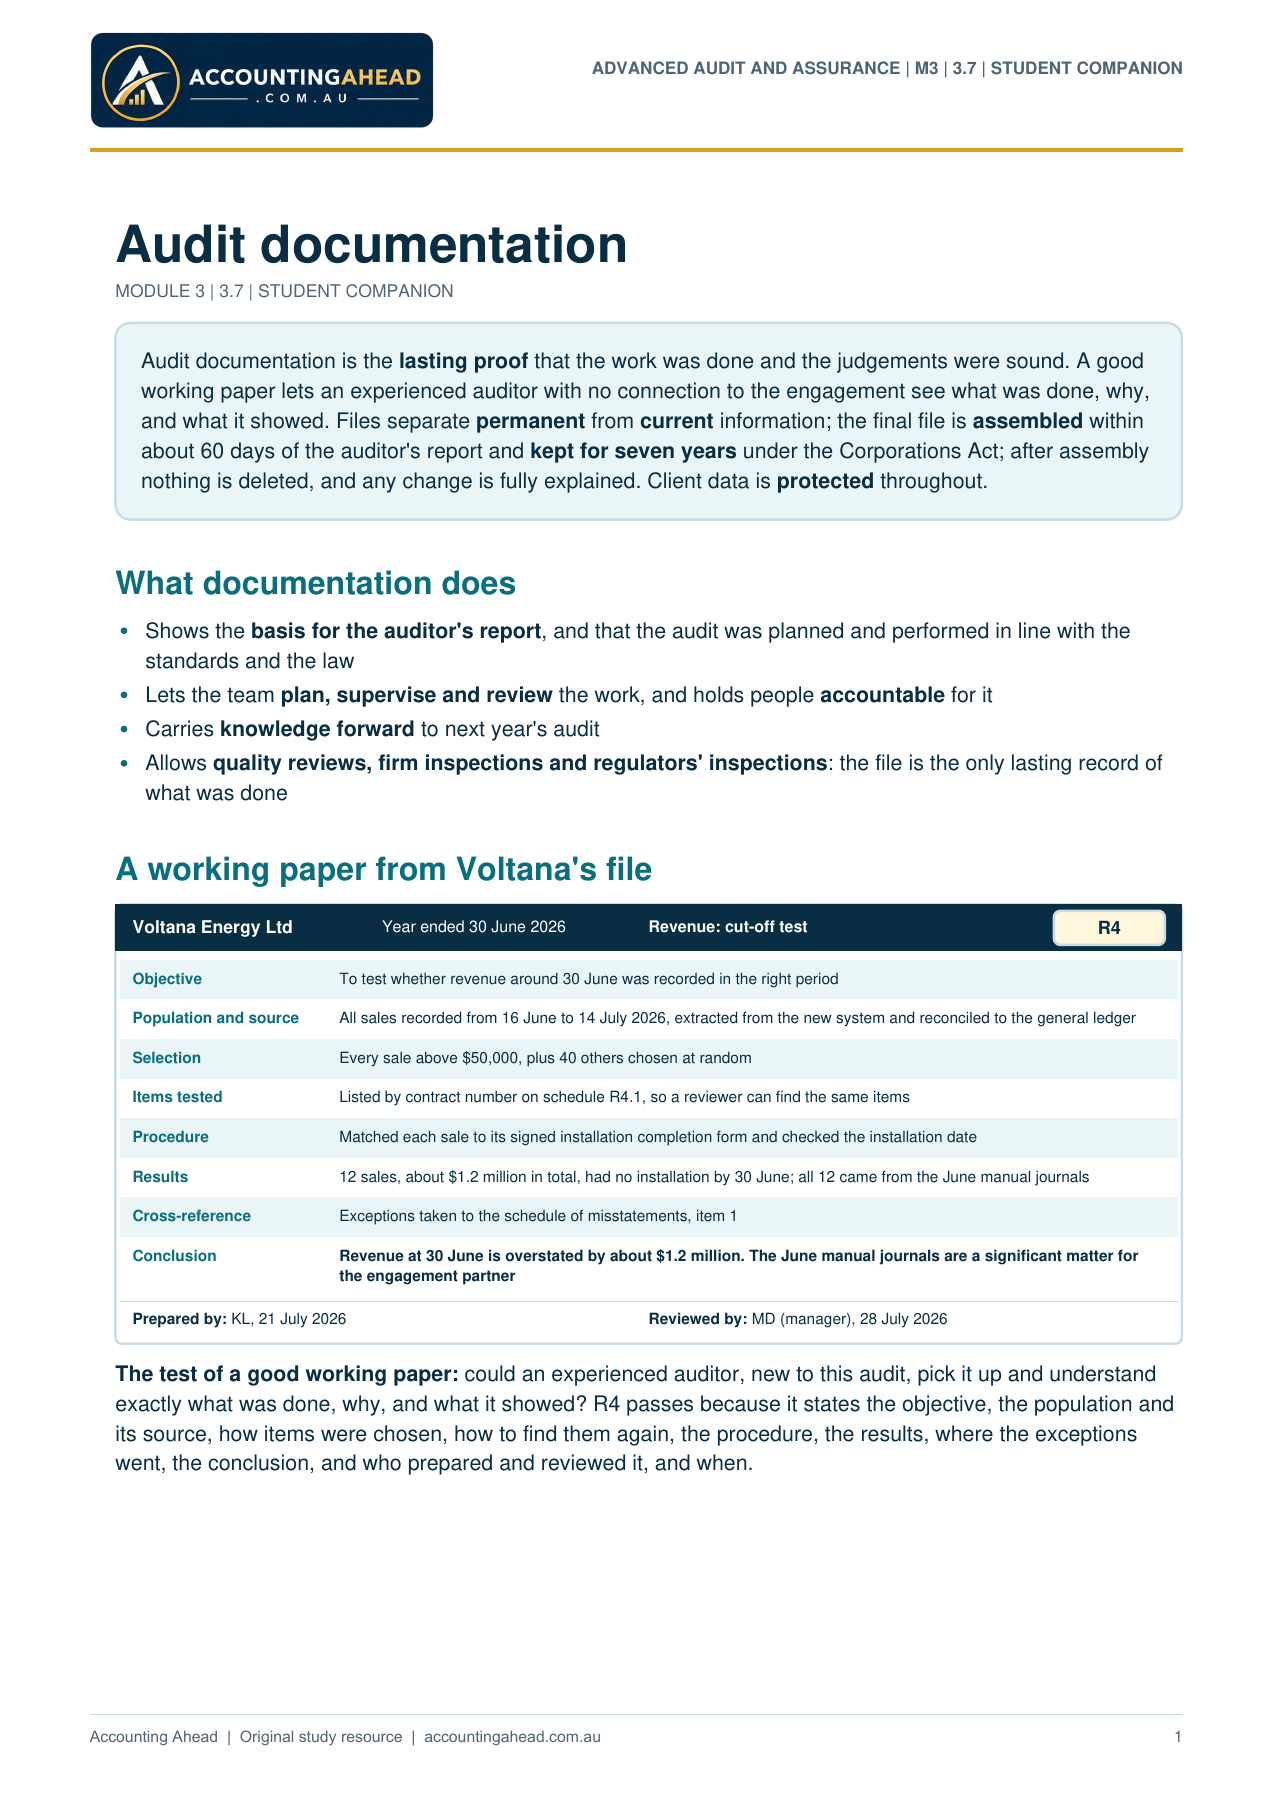
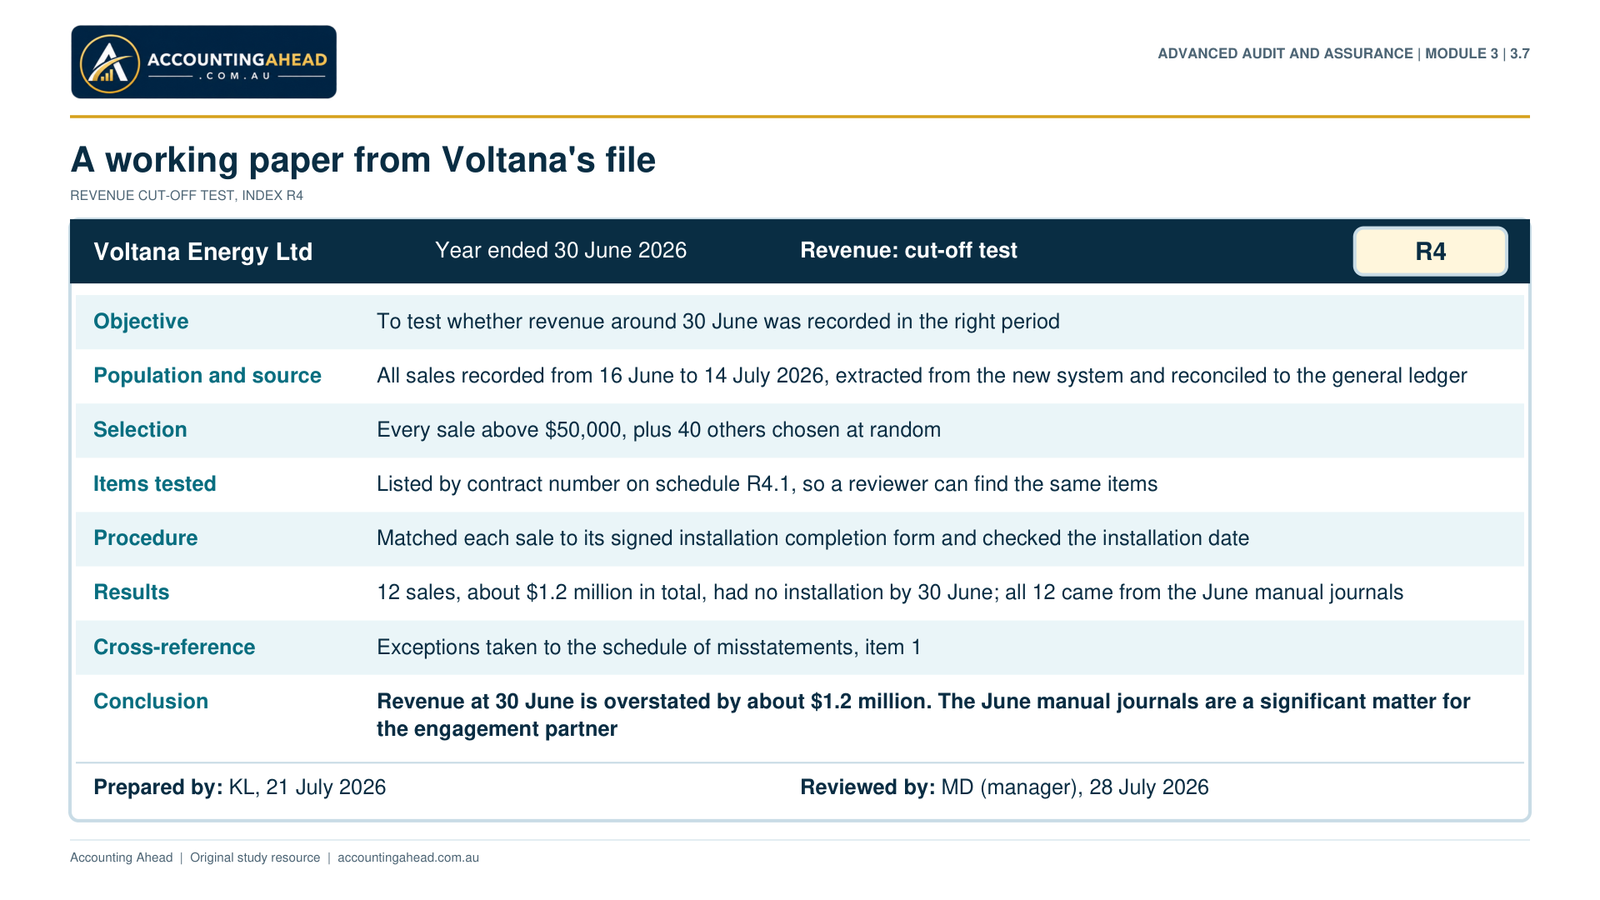
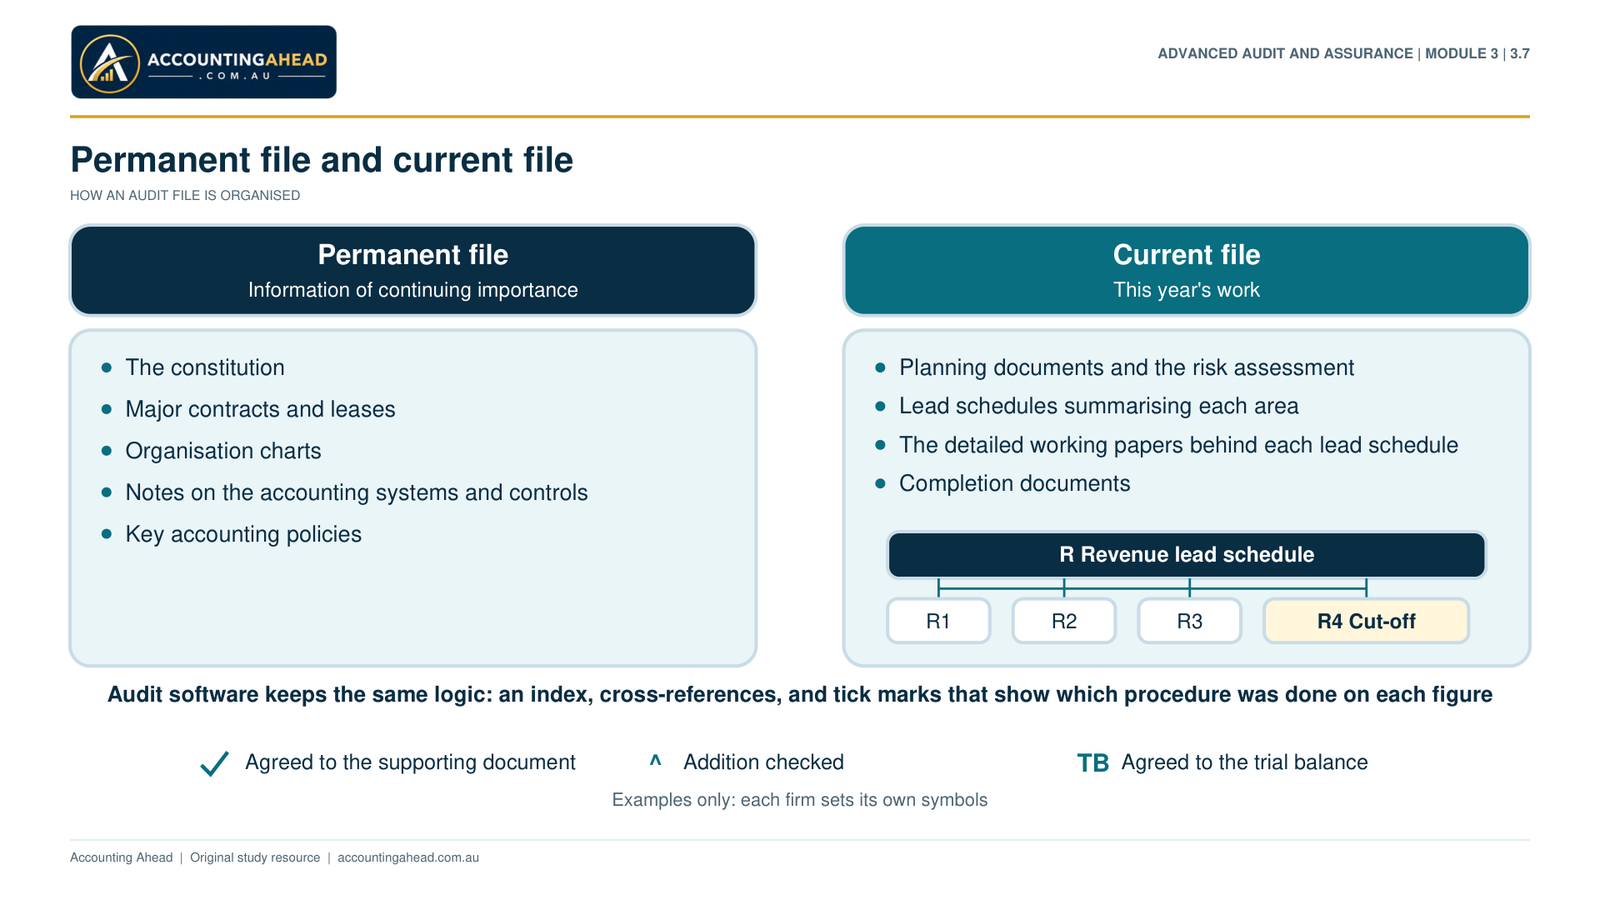
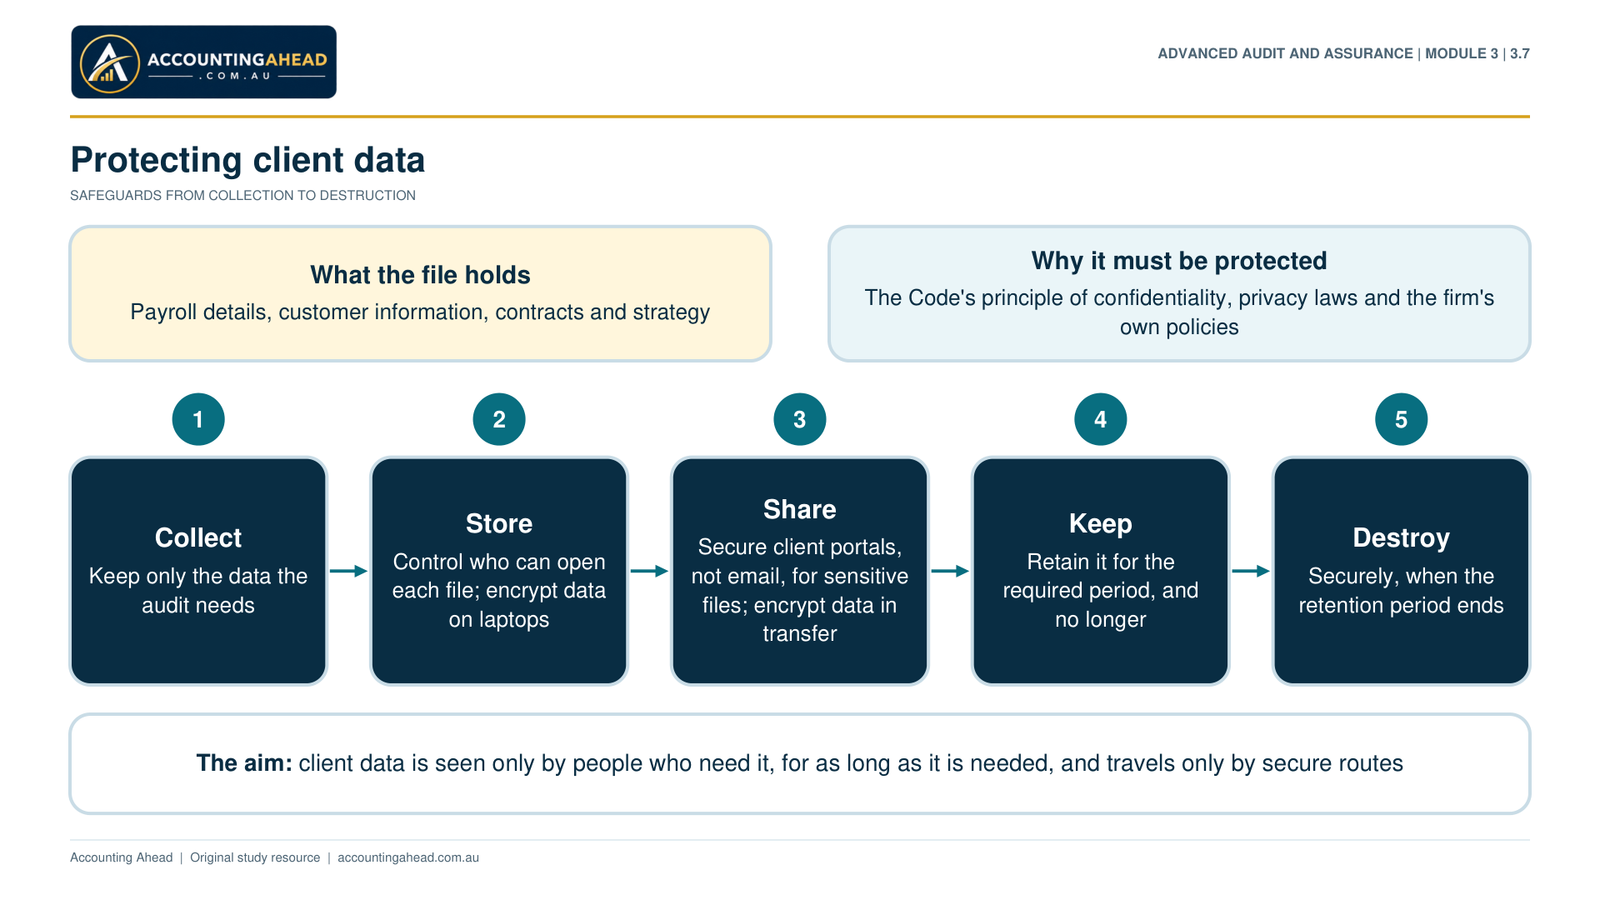
Part 3.7 · Audit Documentation
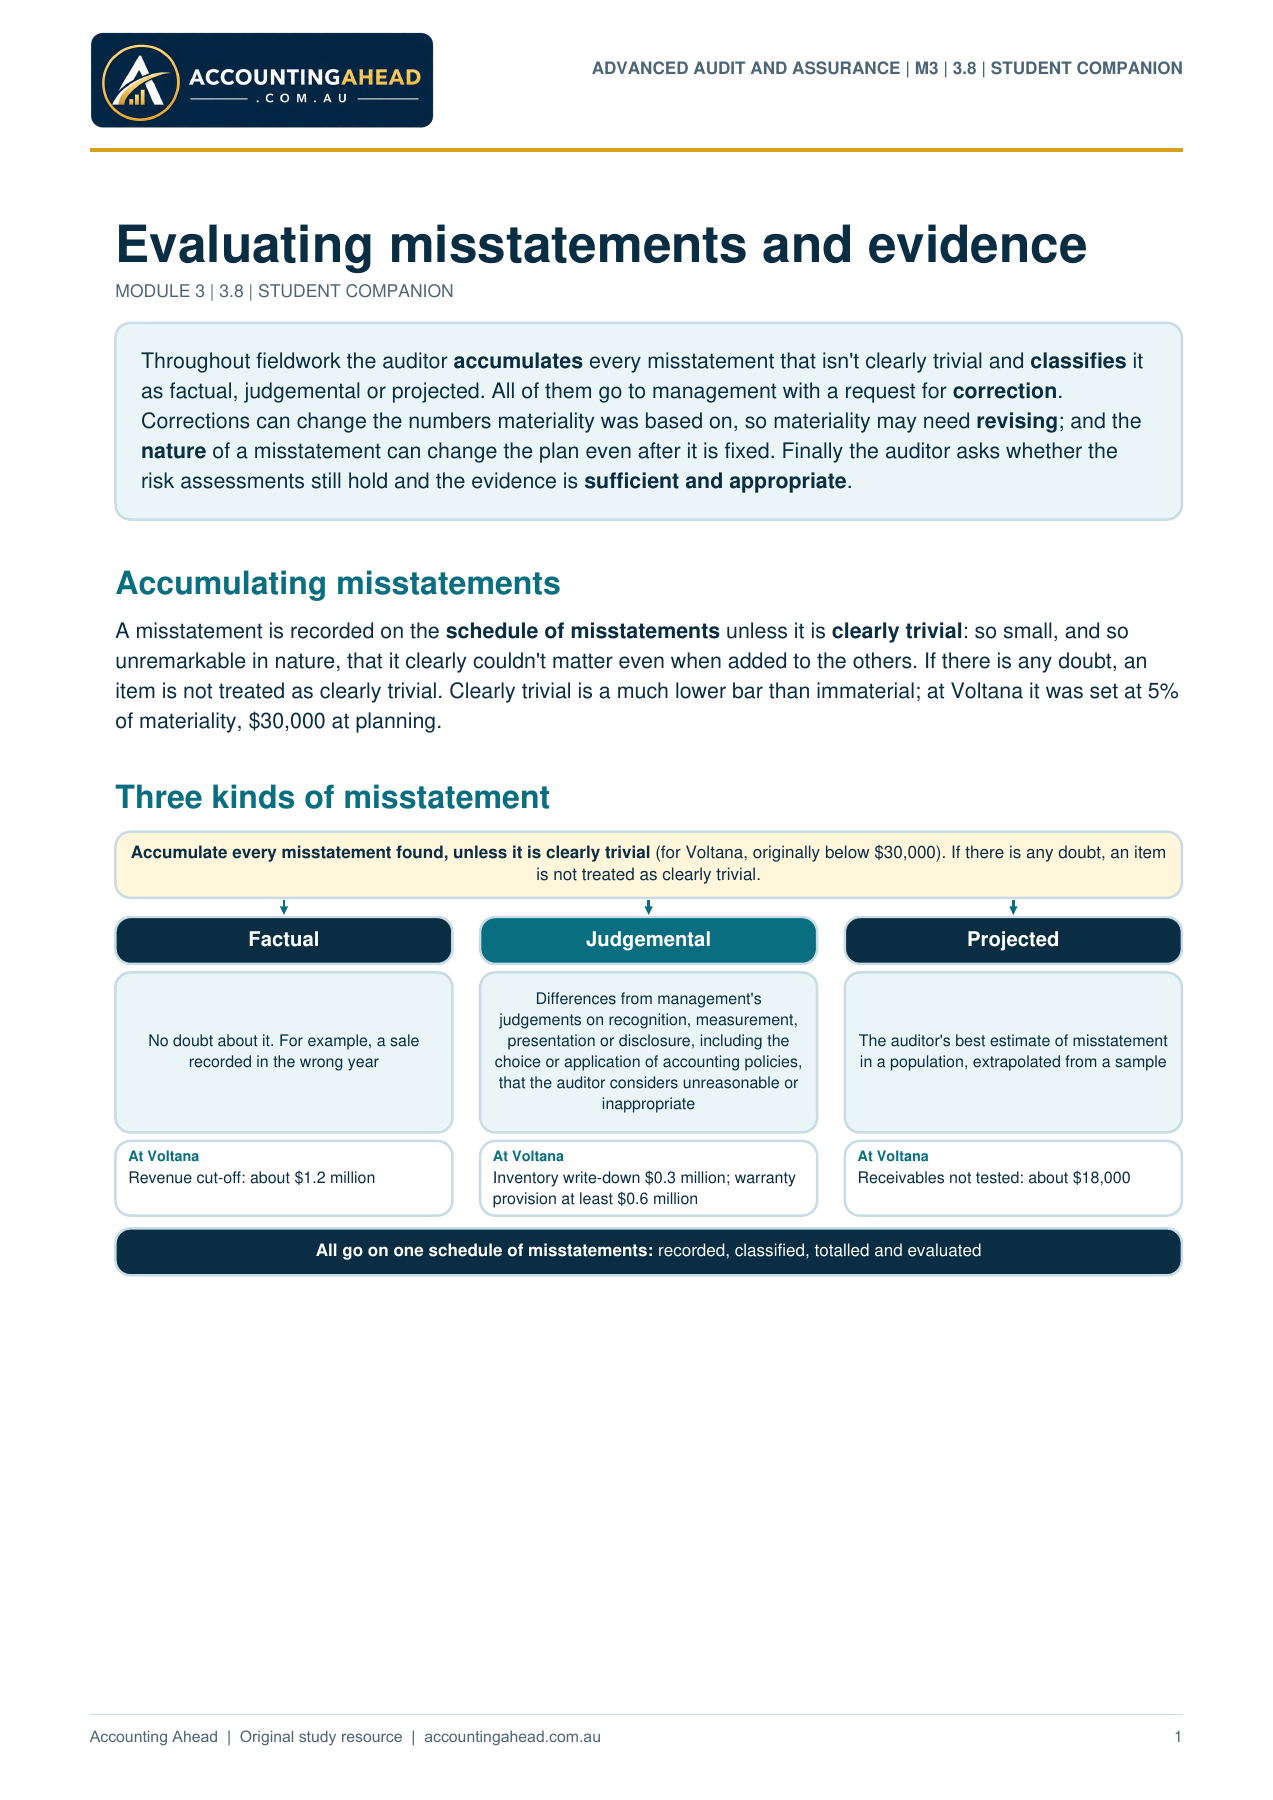
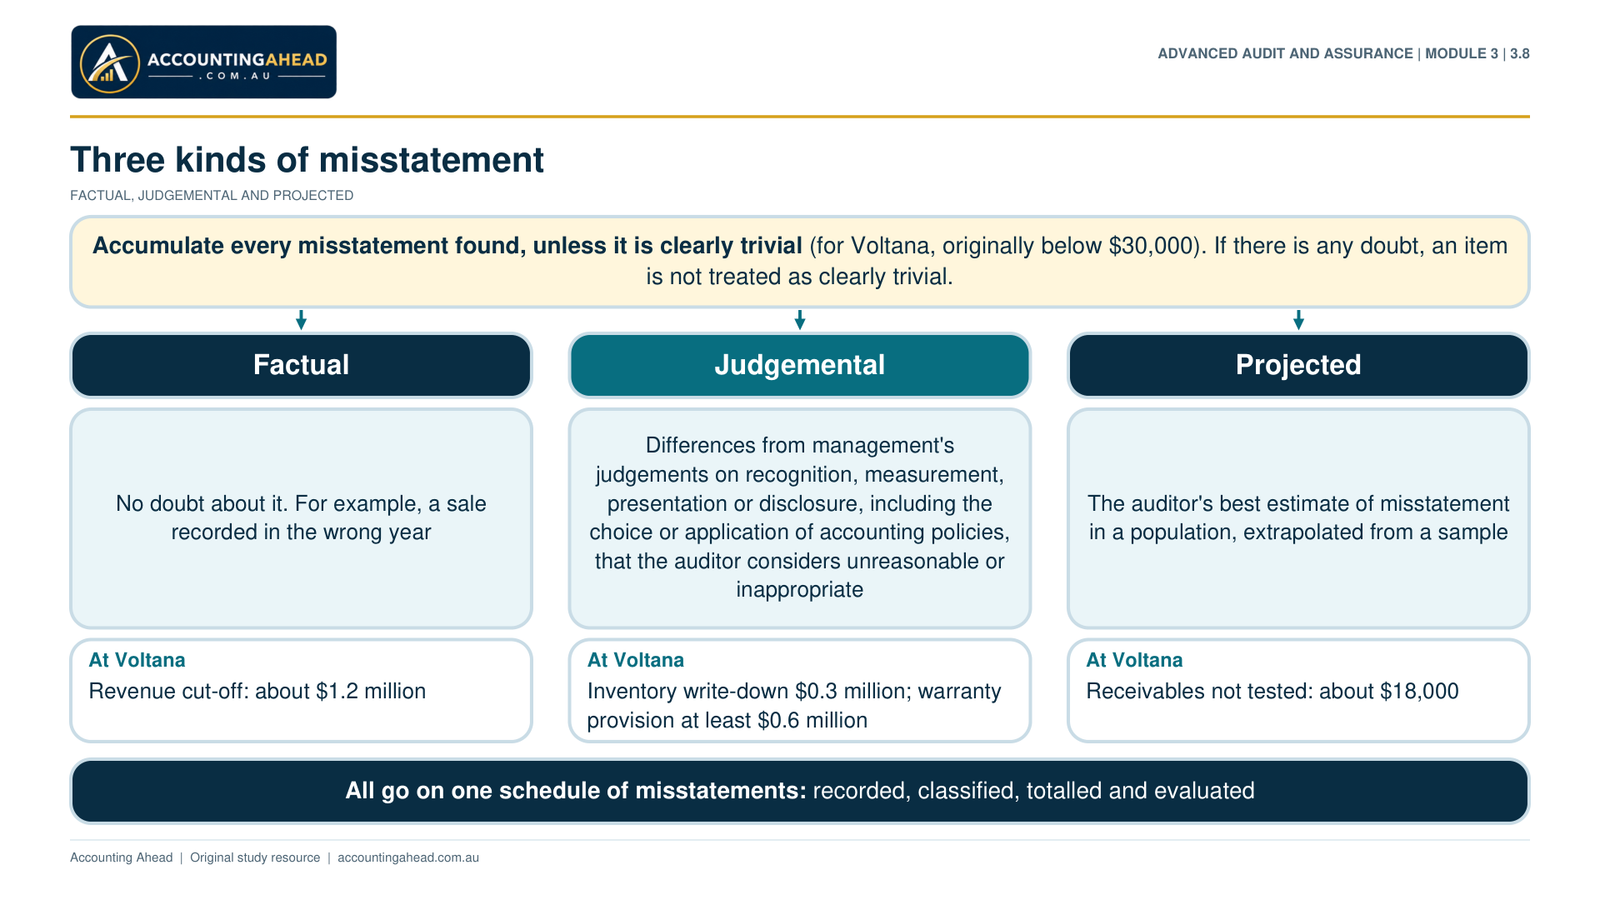
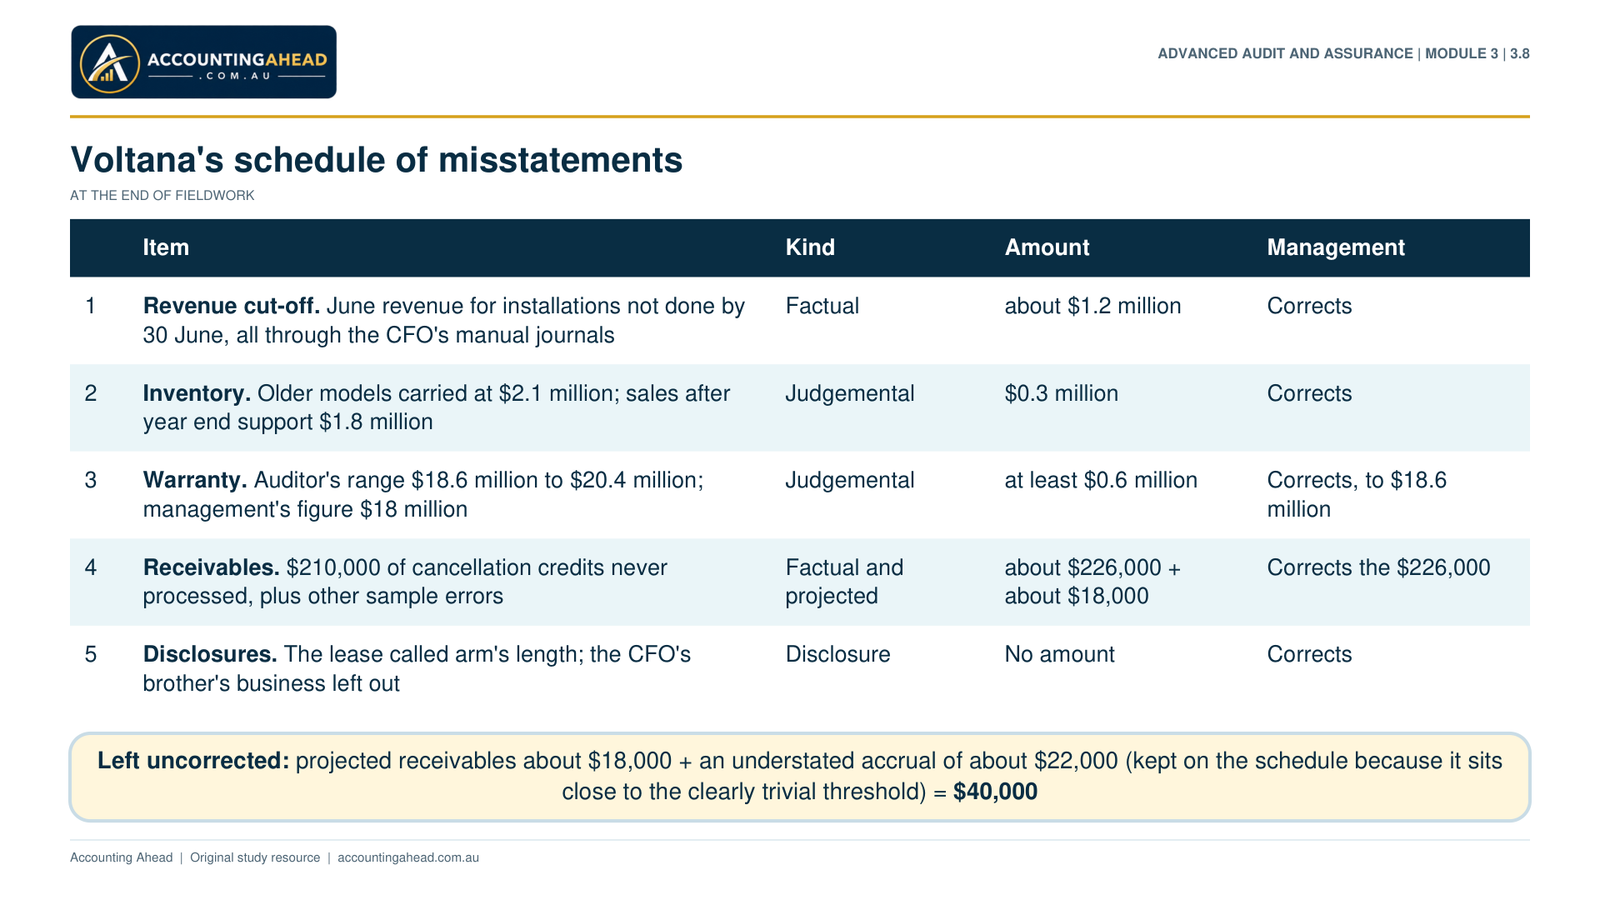
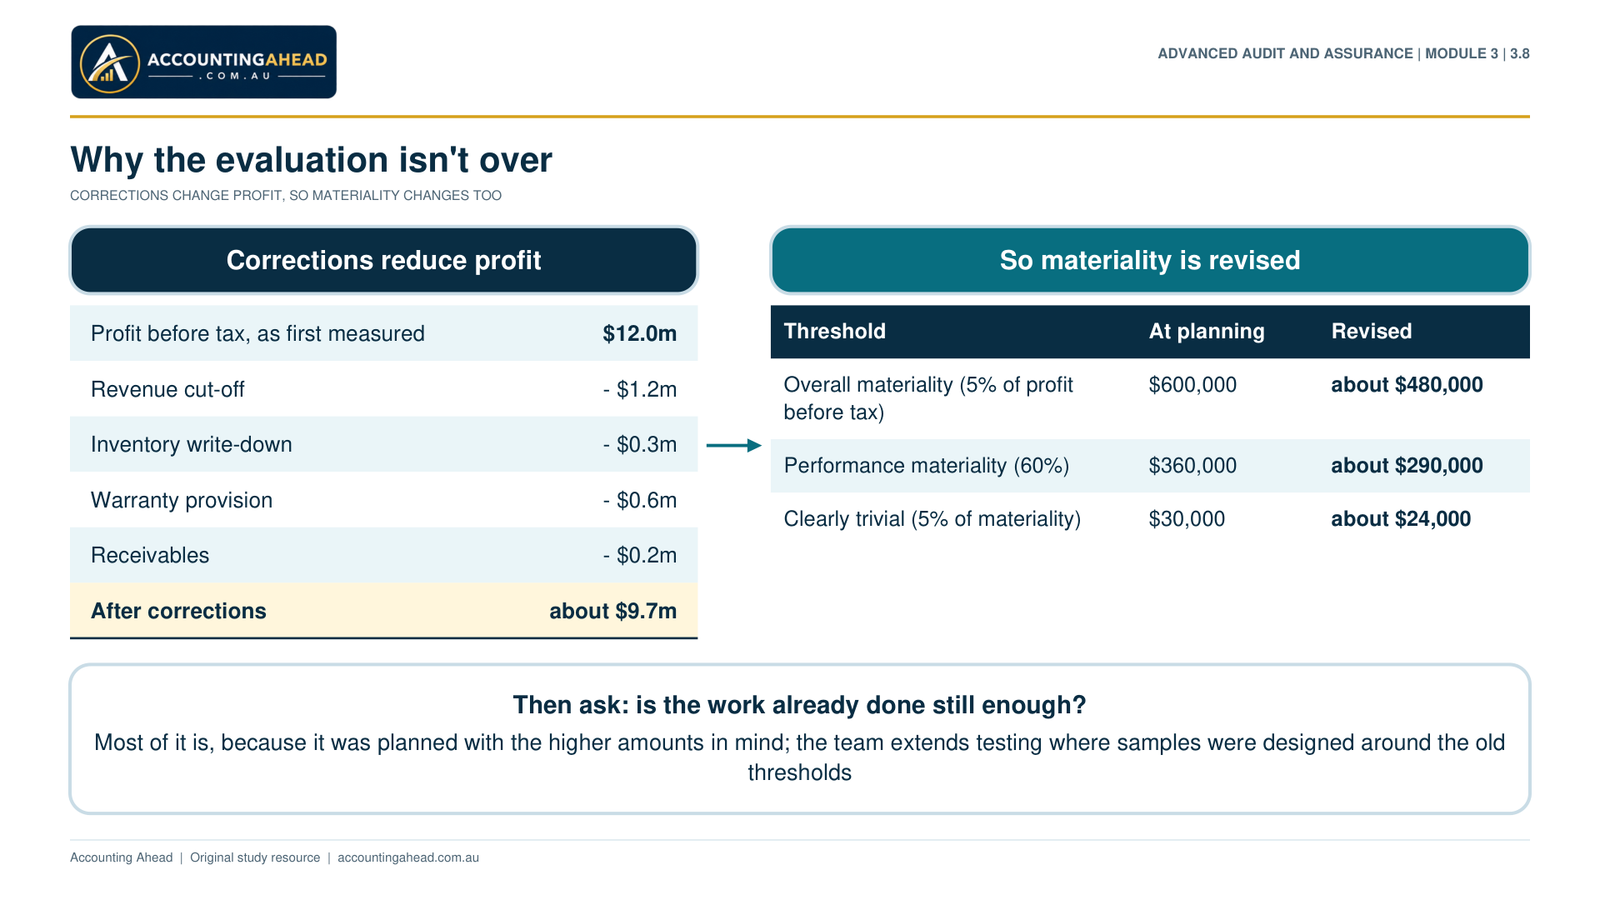
Part 3.8 · Evaluating Misstatements and Evidence
Module 4 · Conclusions and reporting responsibilities
Part 4.1.1 · Significant Areas, Litigation and Claims
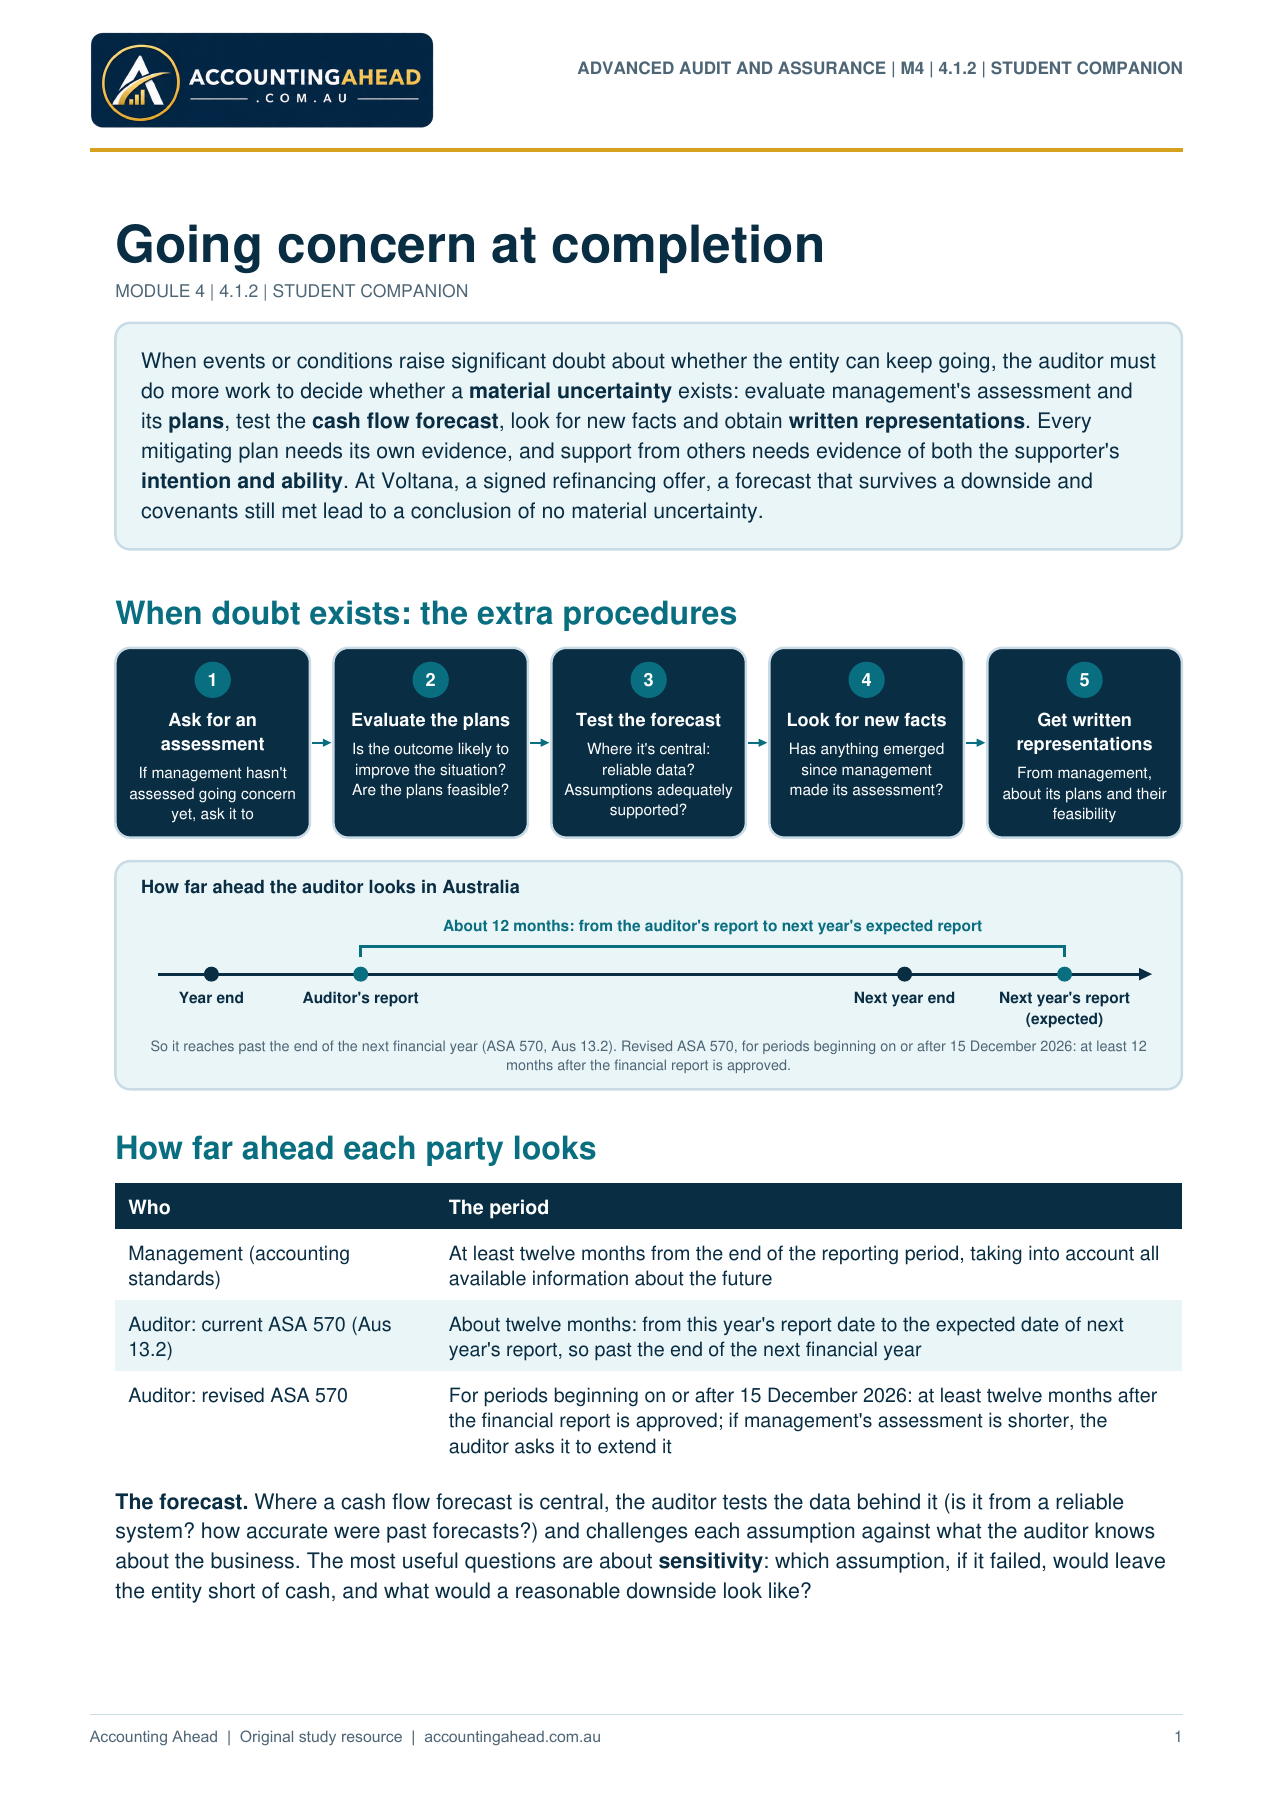
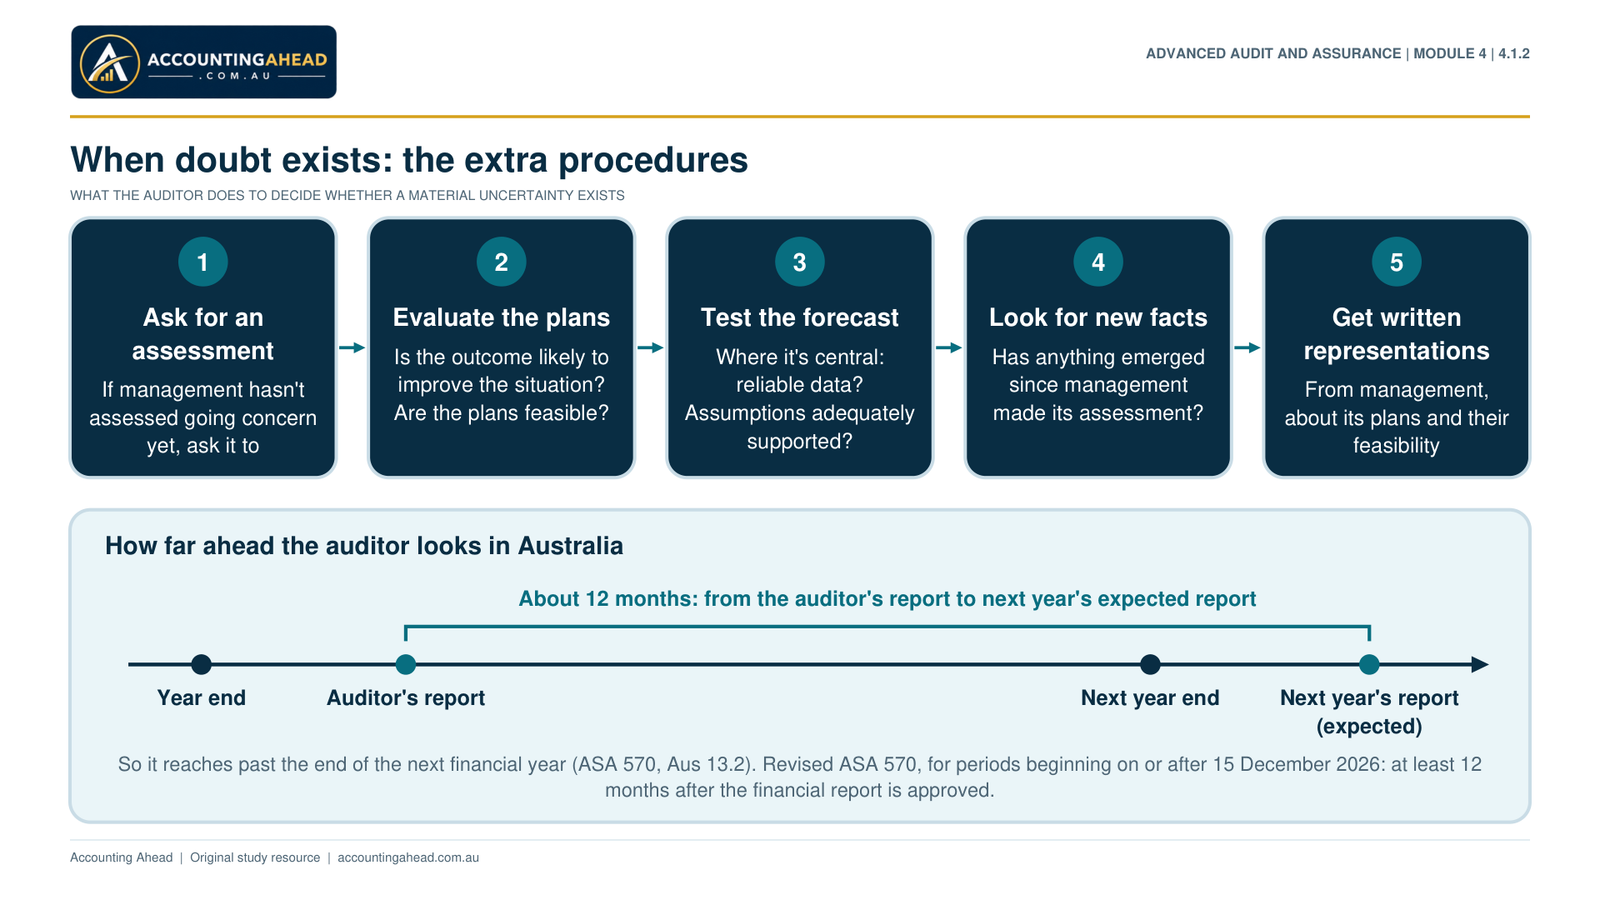
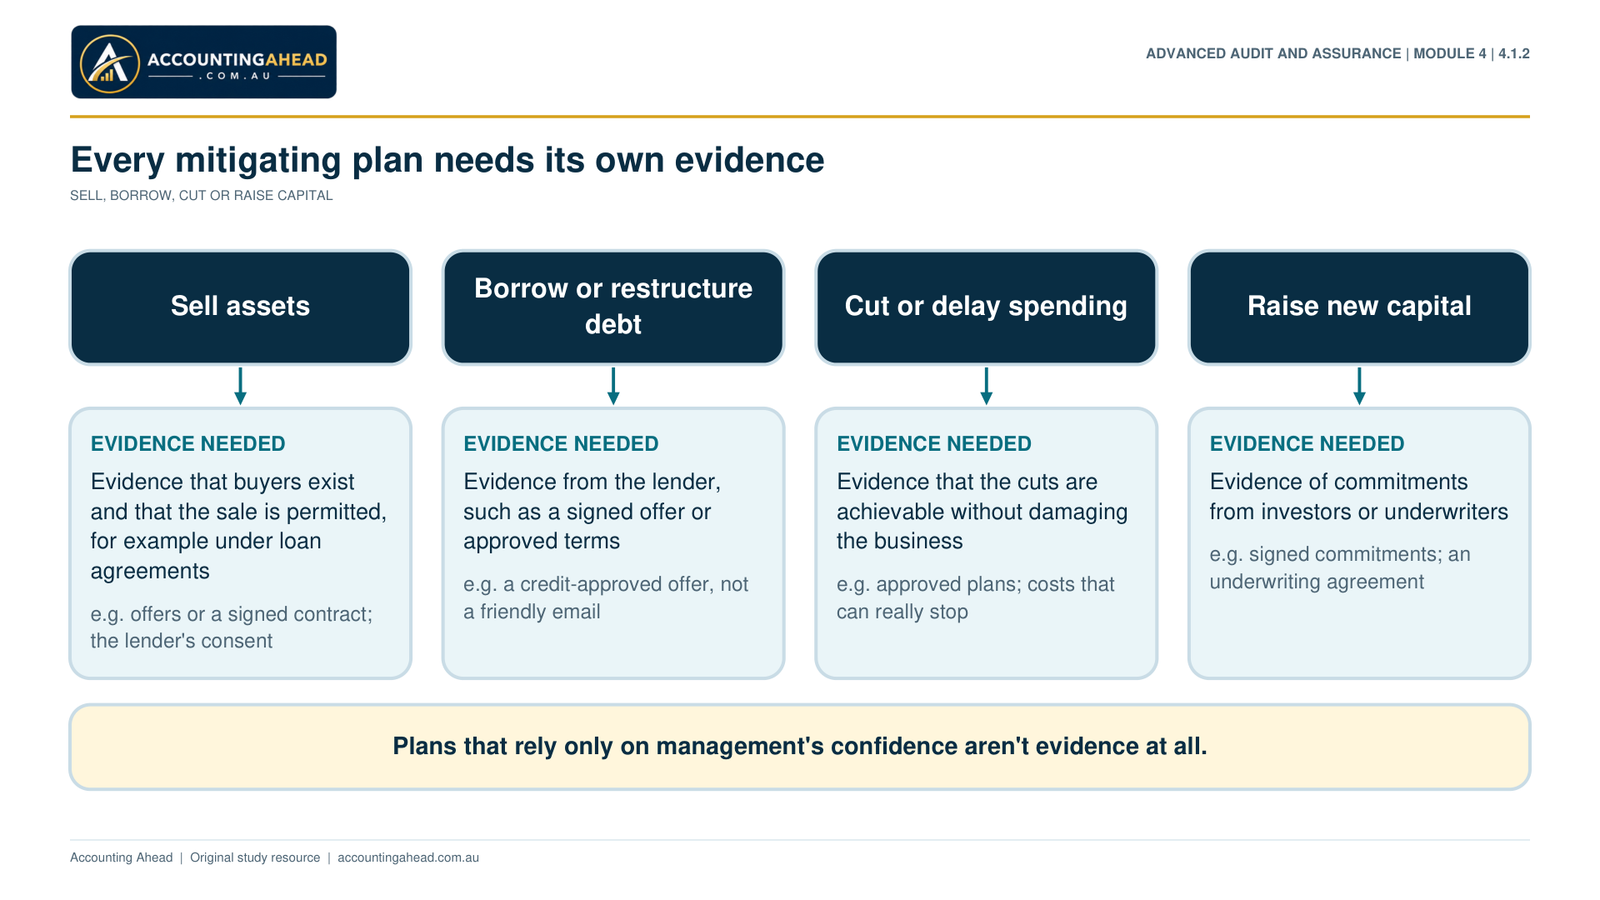
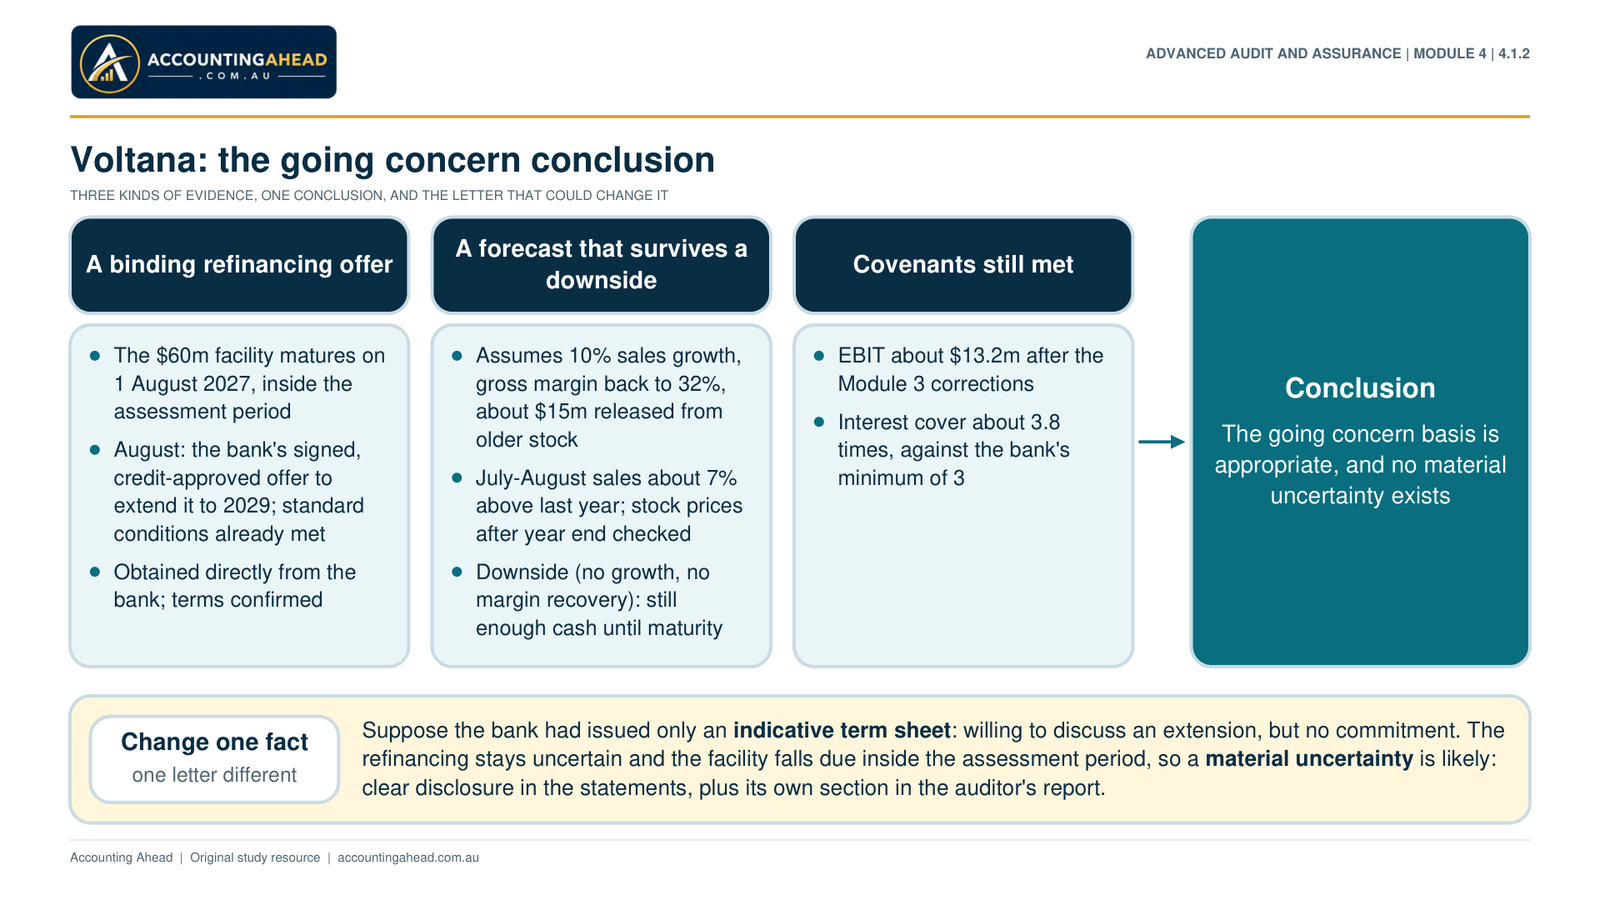
Part 4.1.2 · Going Concern at Completion
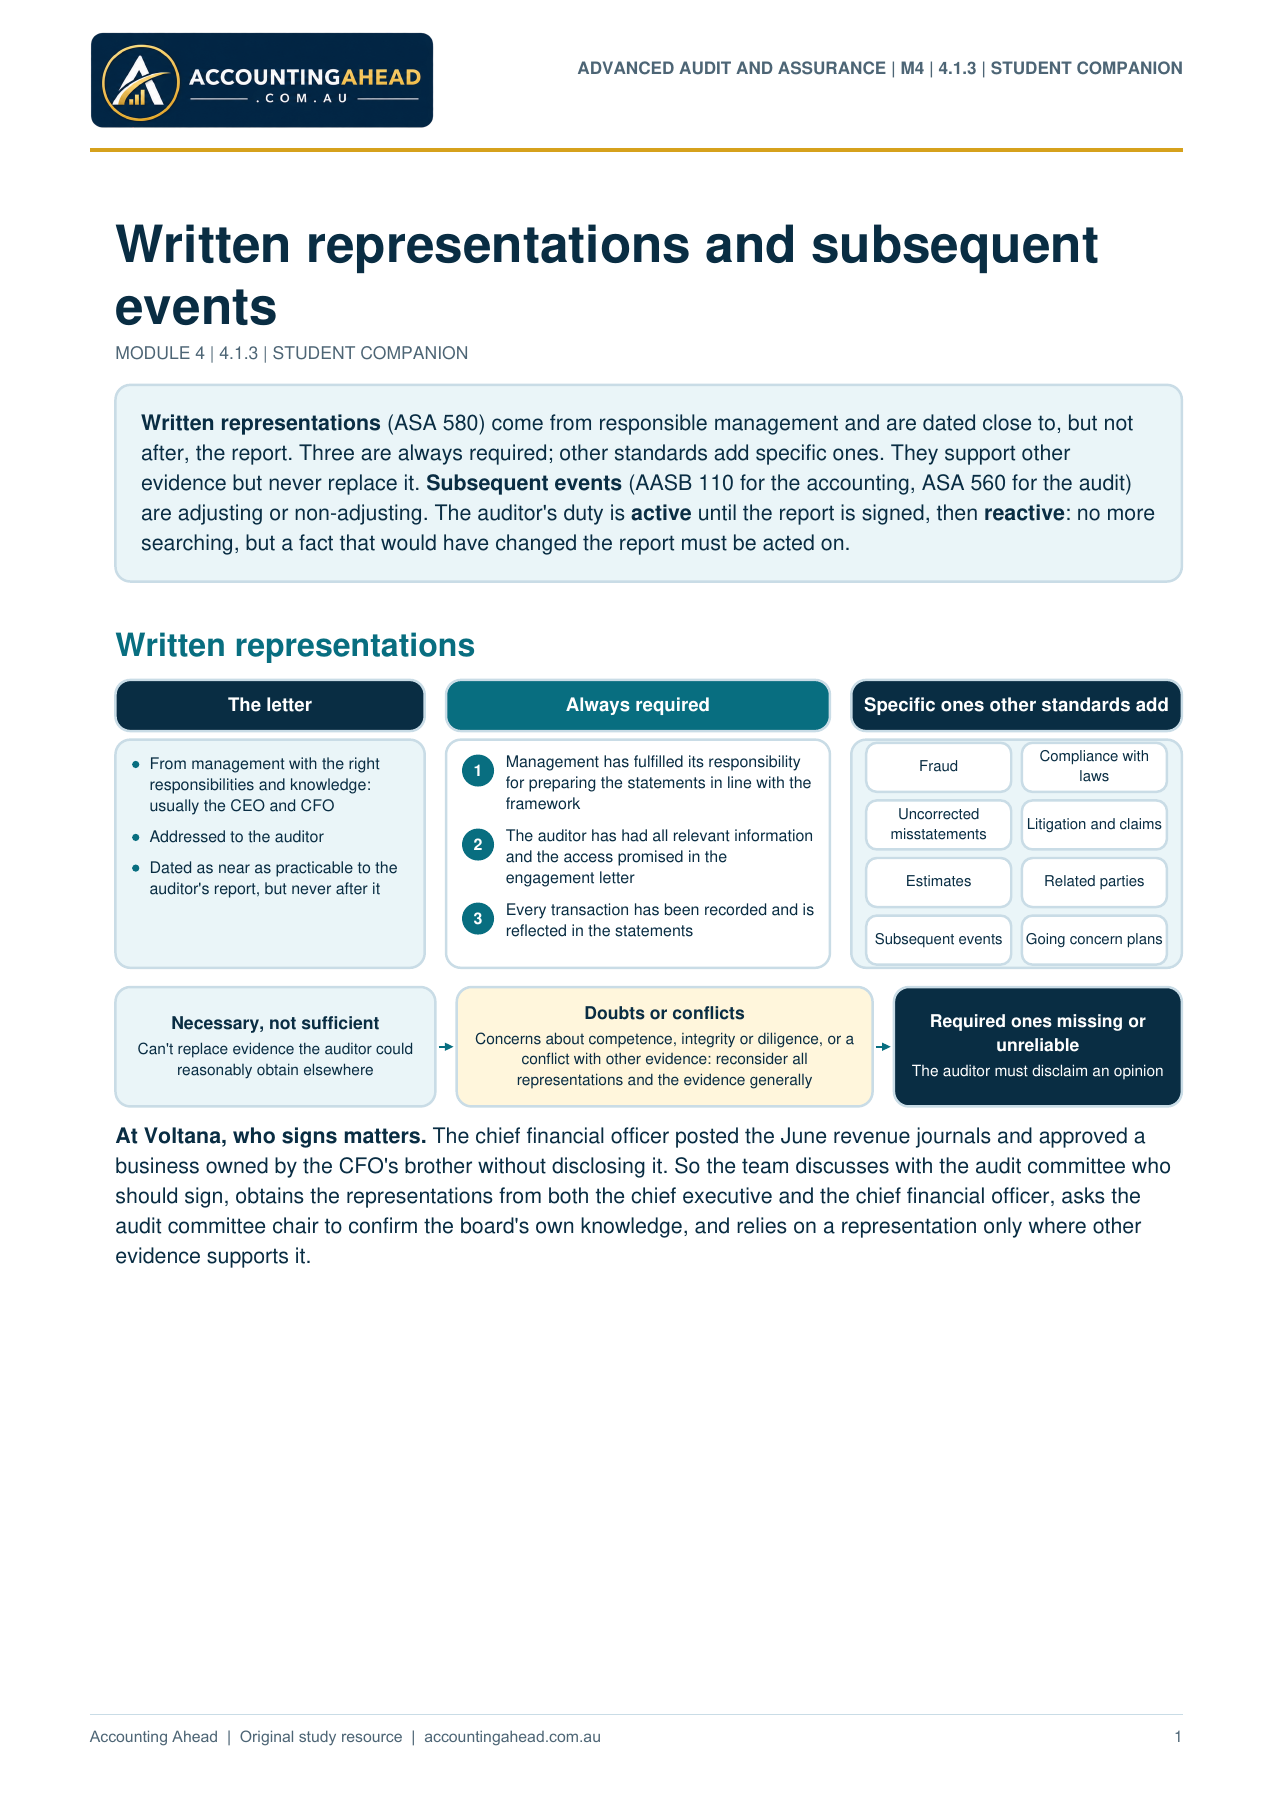
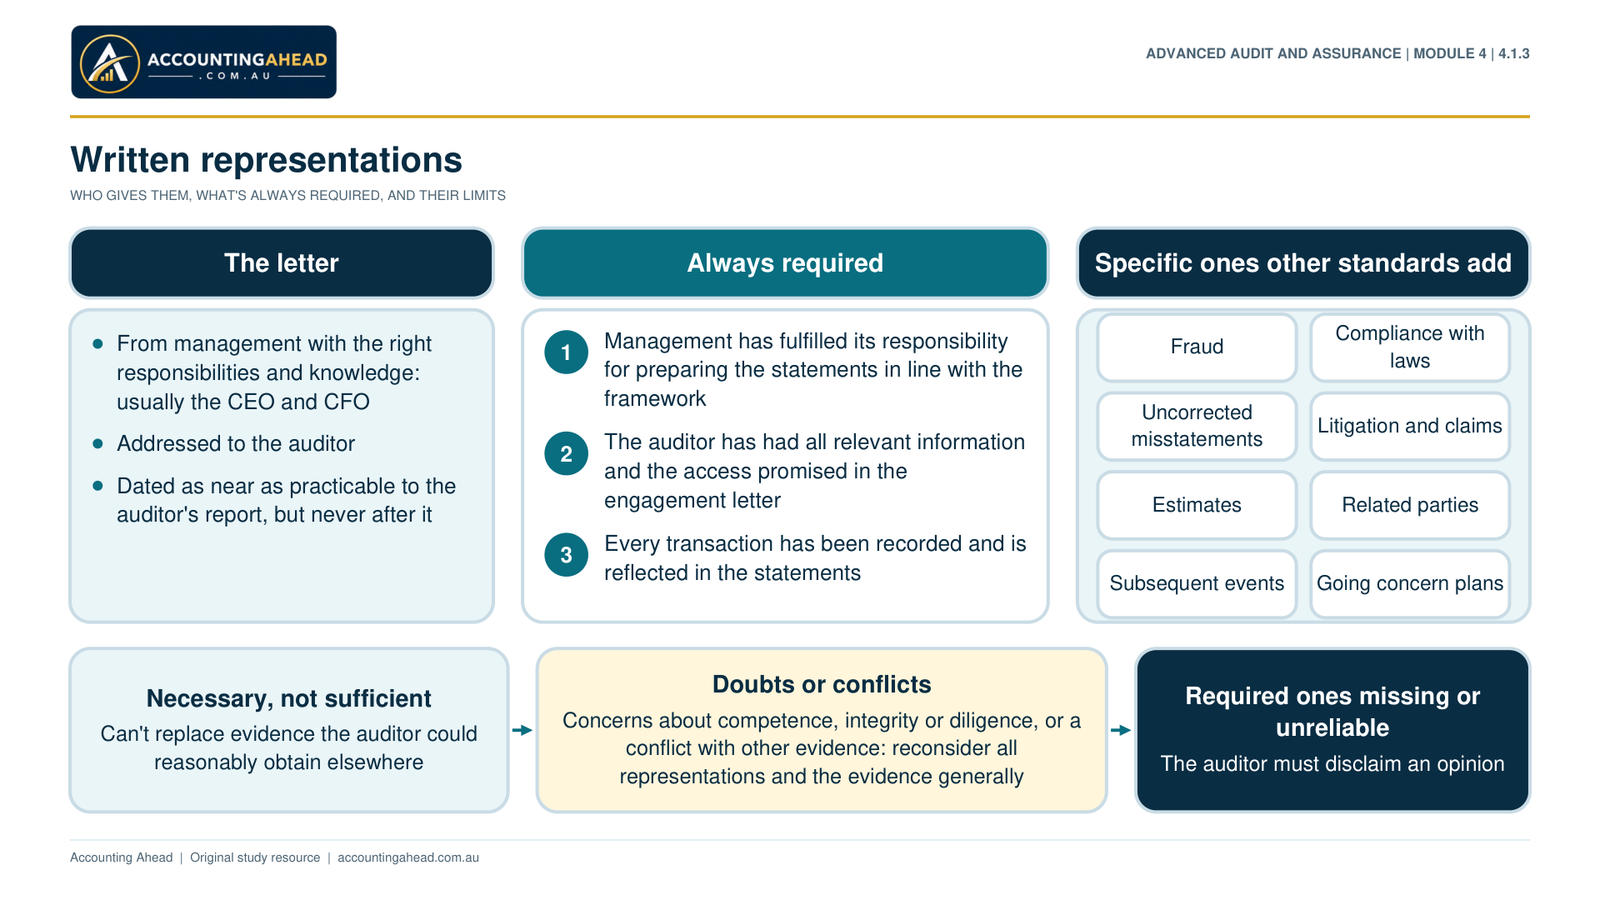
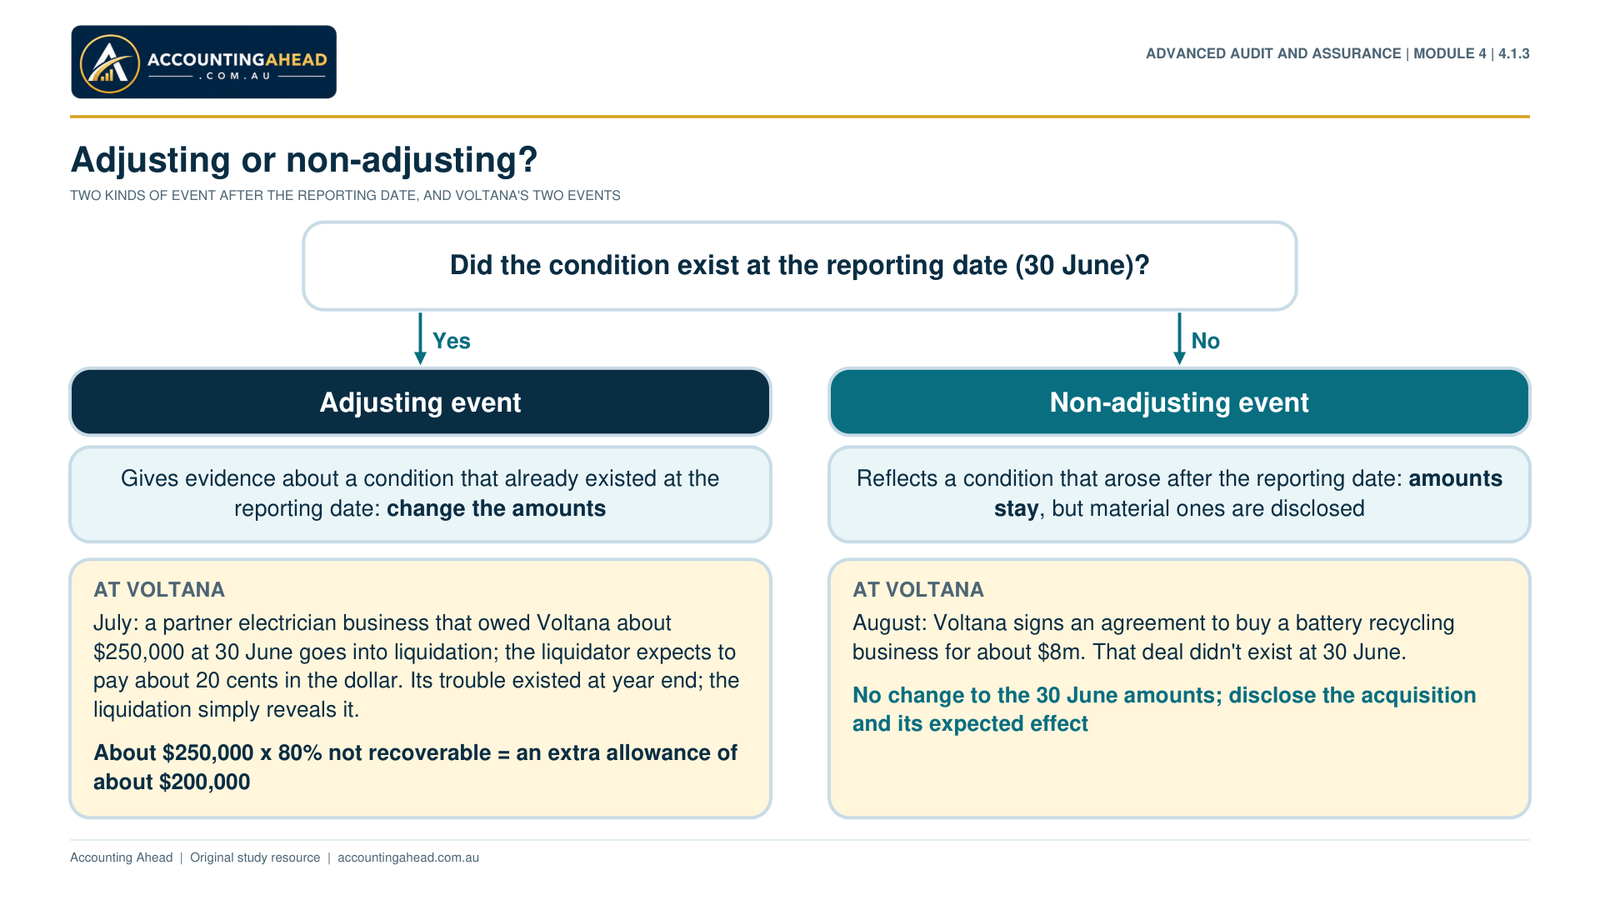
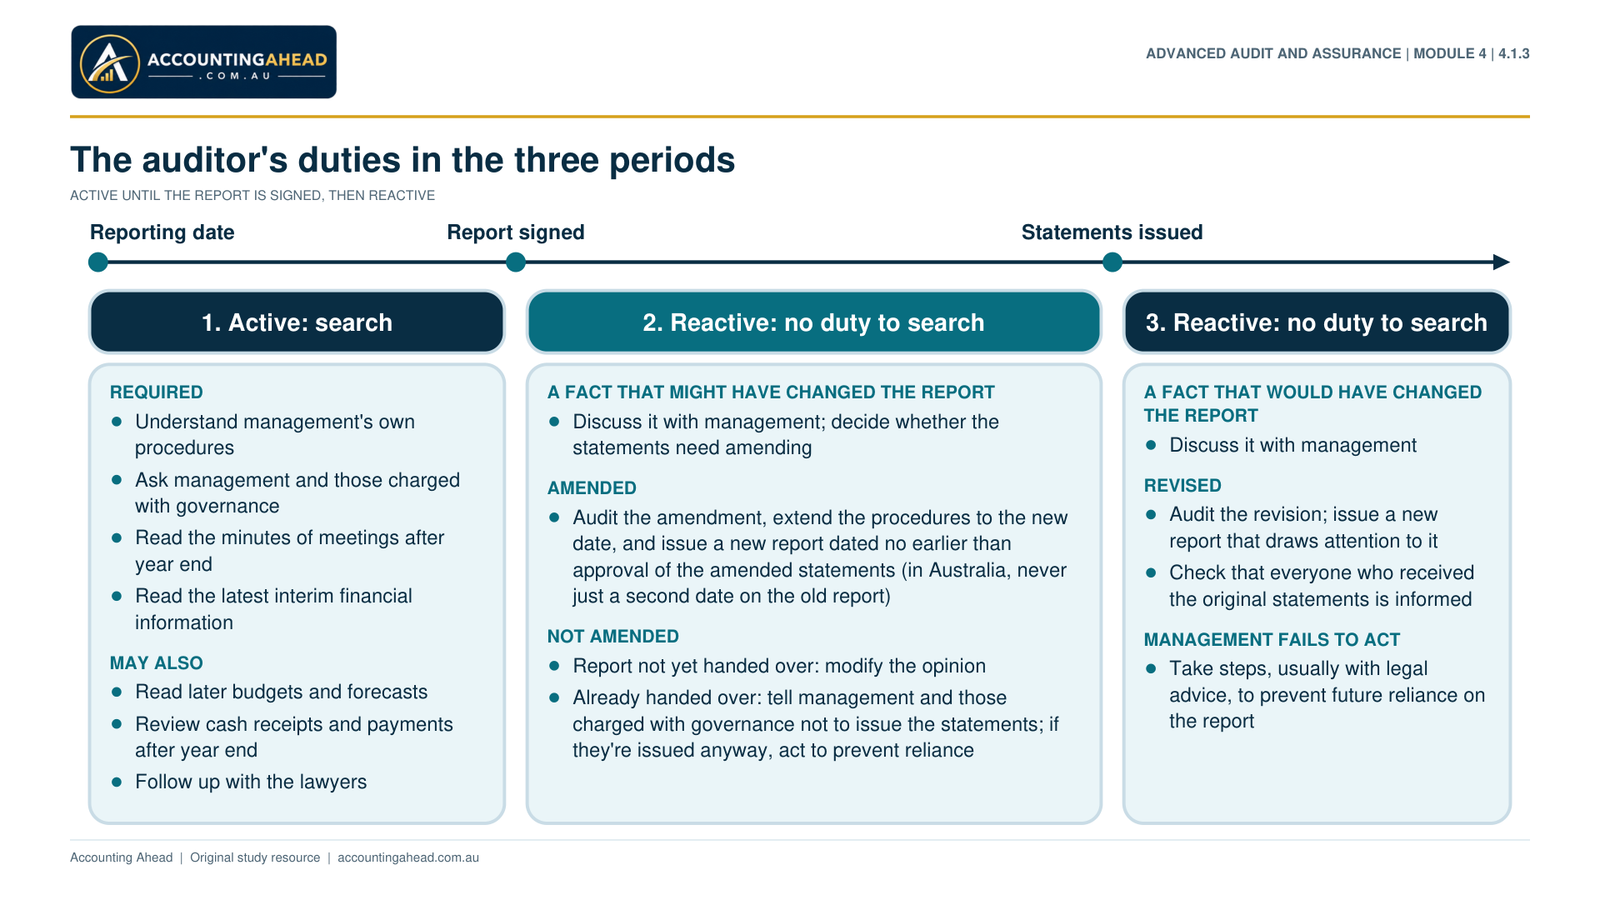
Part 4.1.3 · Written Representations and Subsequent Events
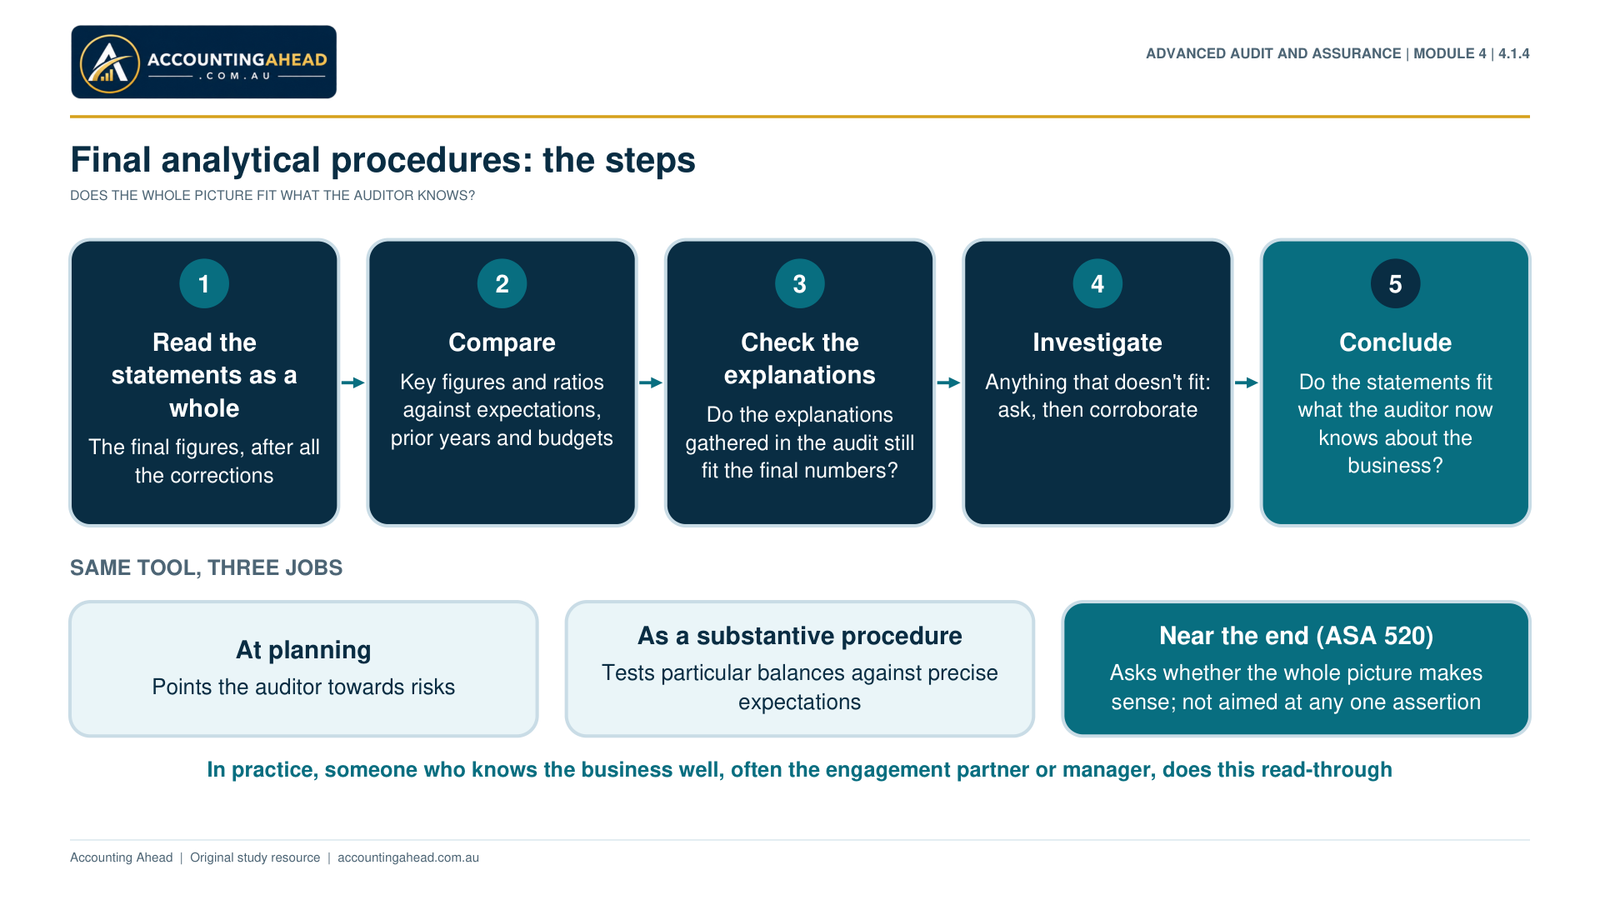
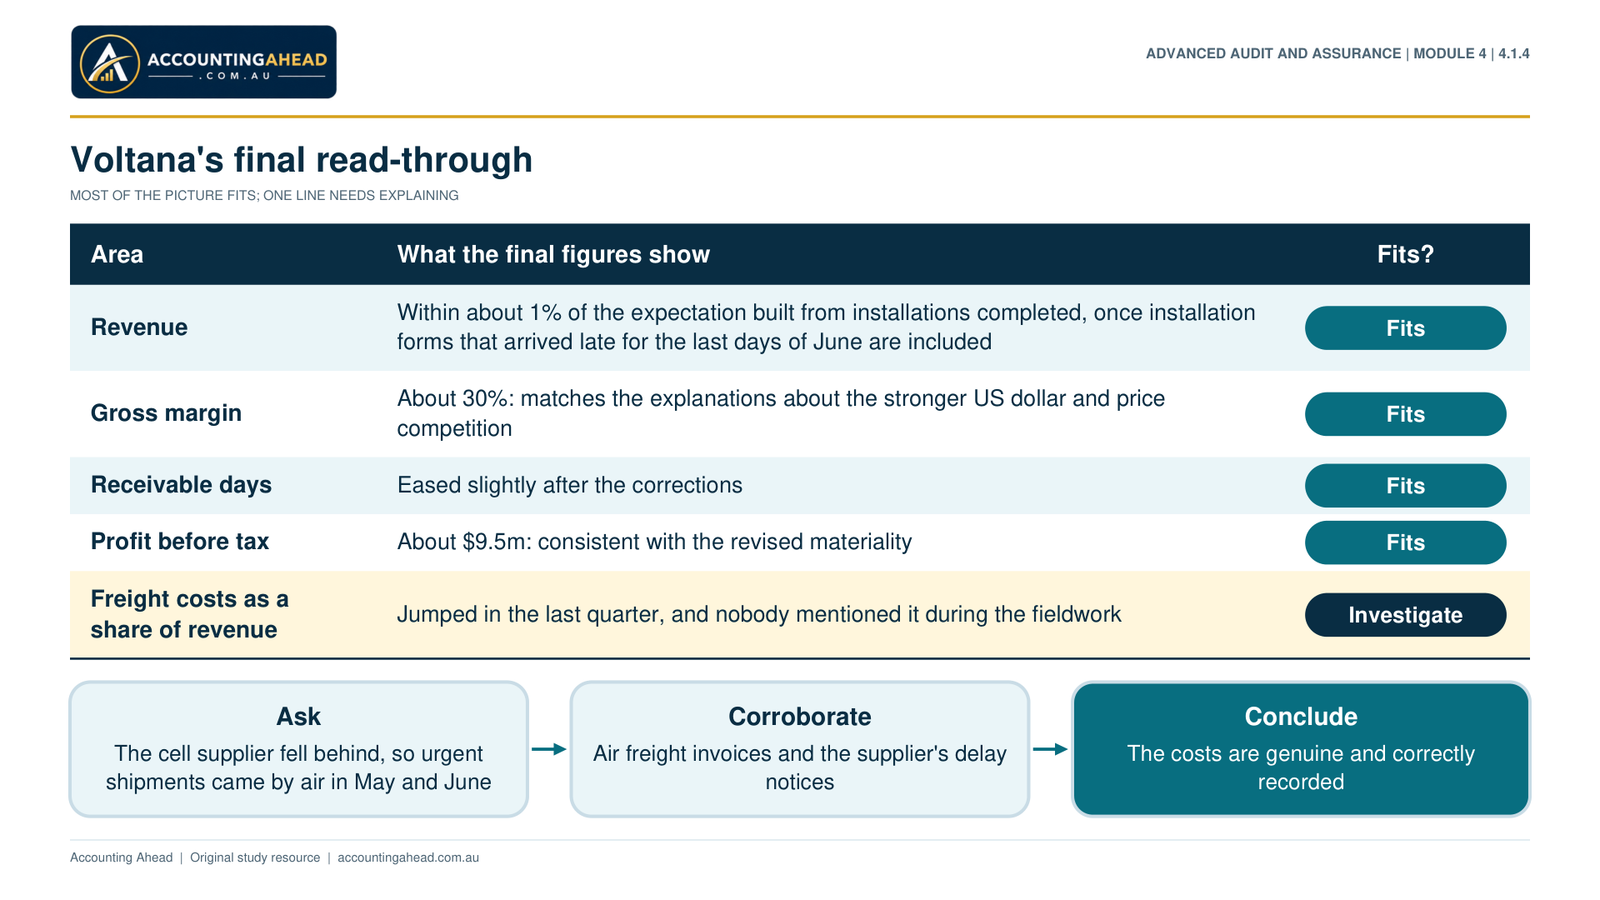
Part 4.1.4 · Final Analytical Procedures
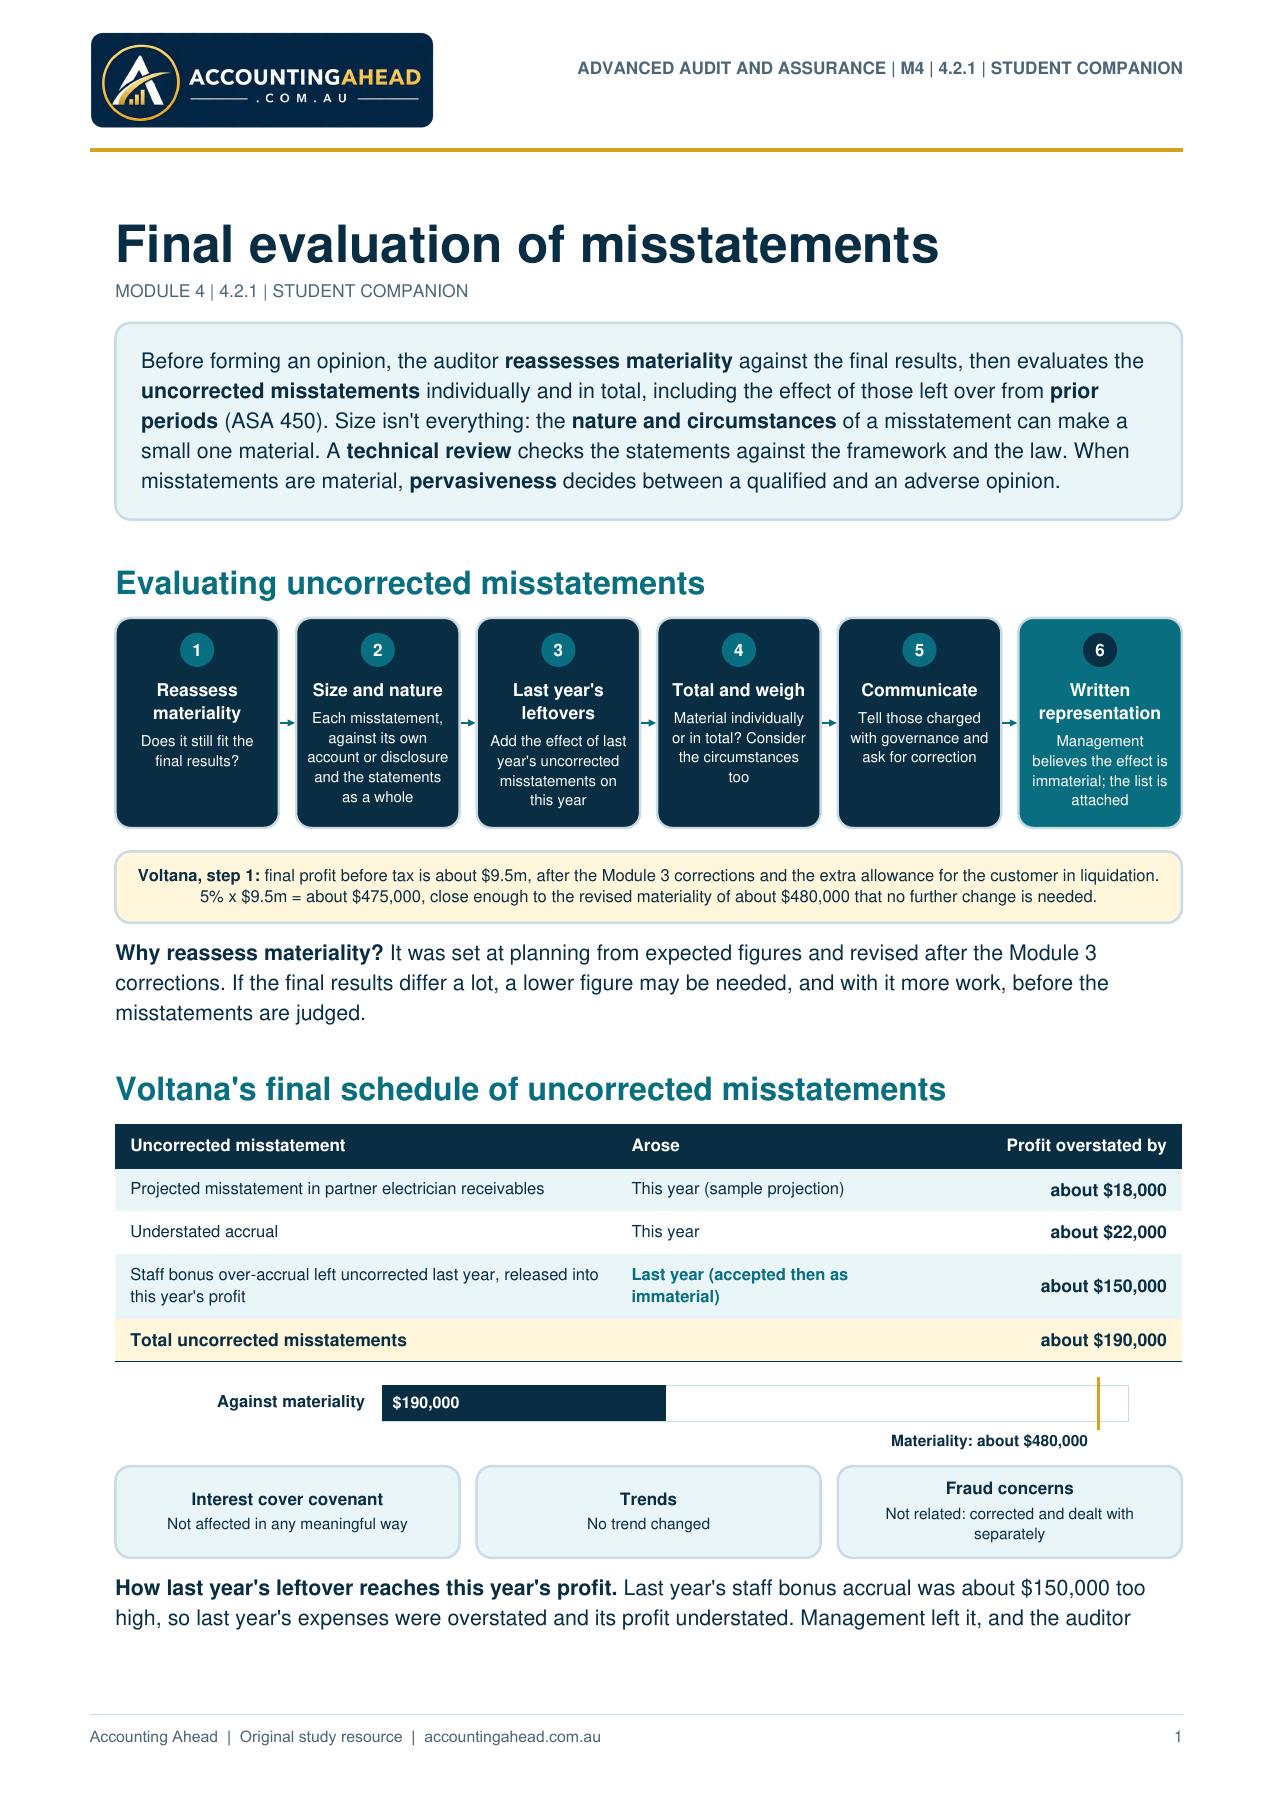
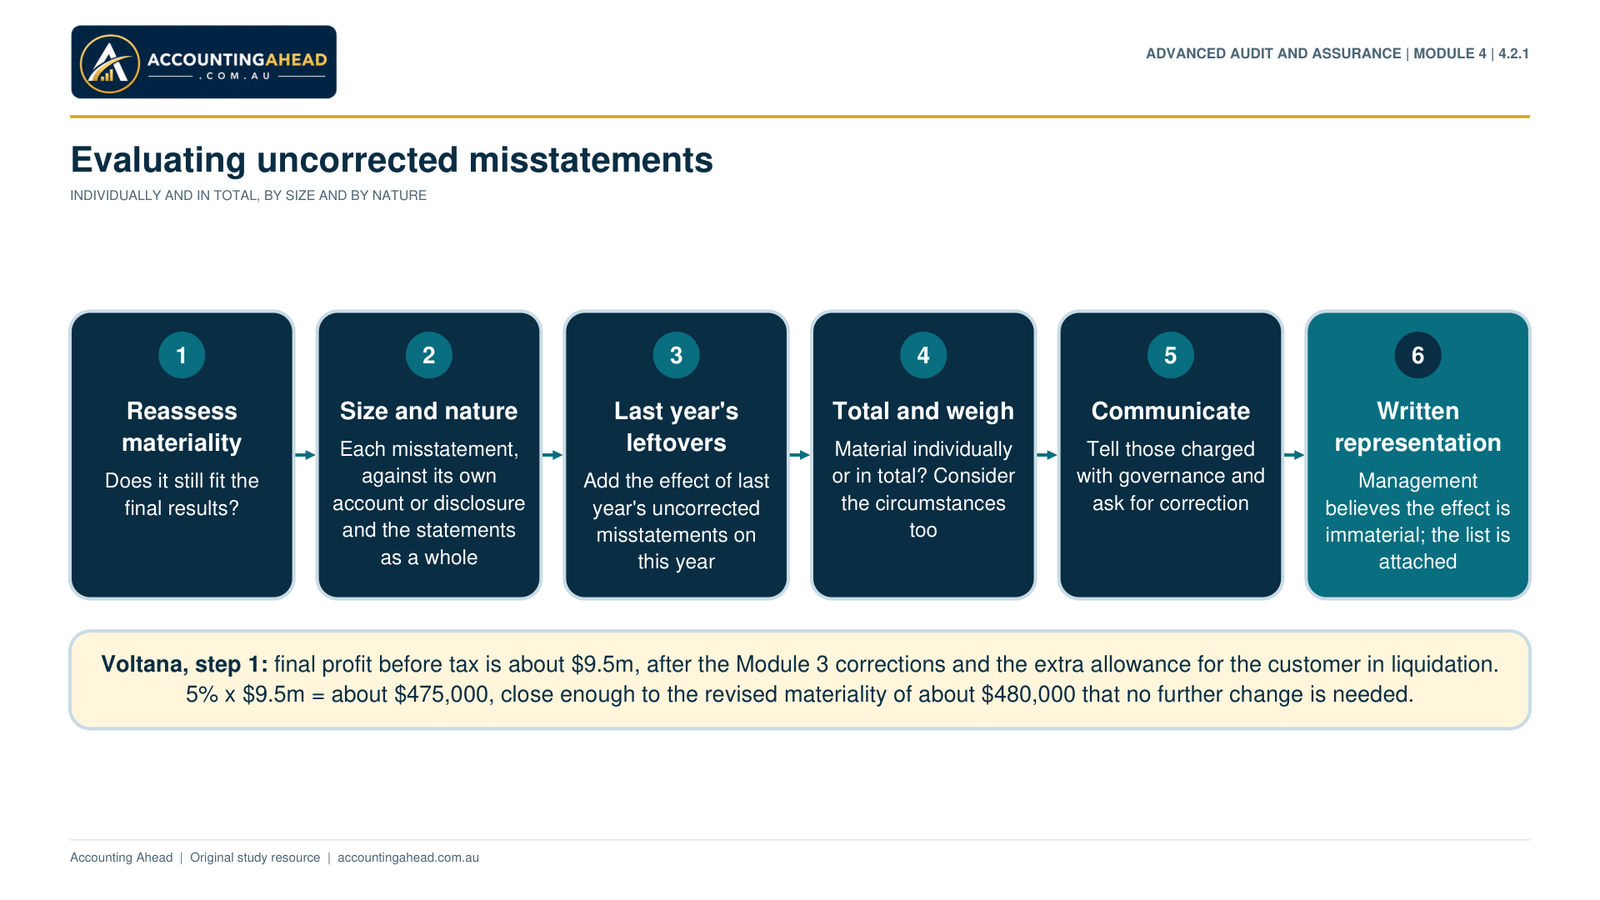
Part 4.2.1 · Final Evaluation of Misstatements
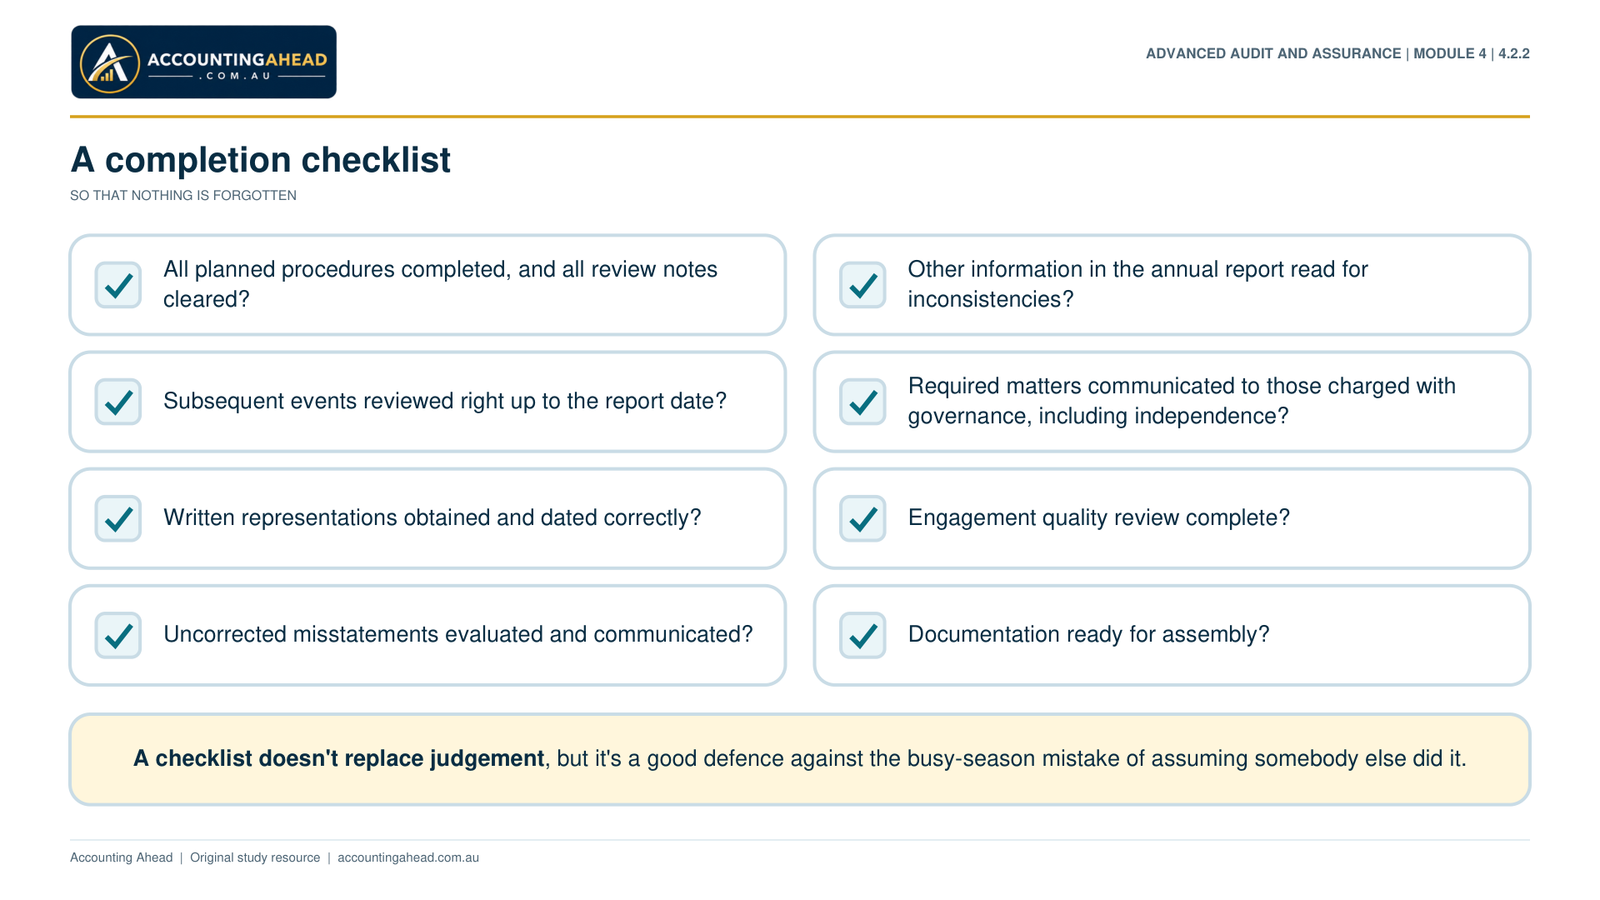
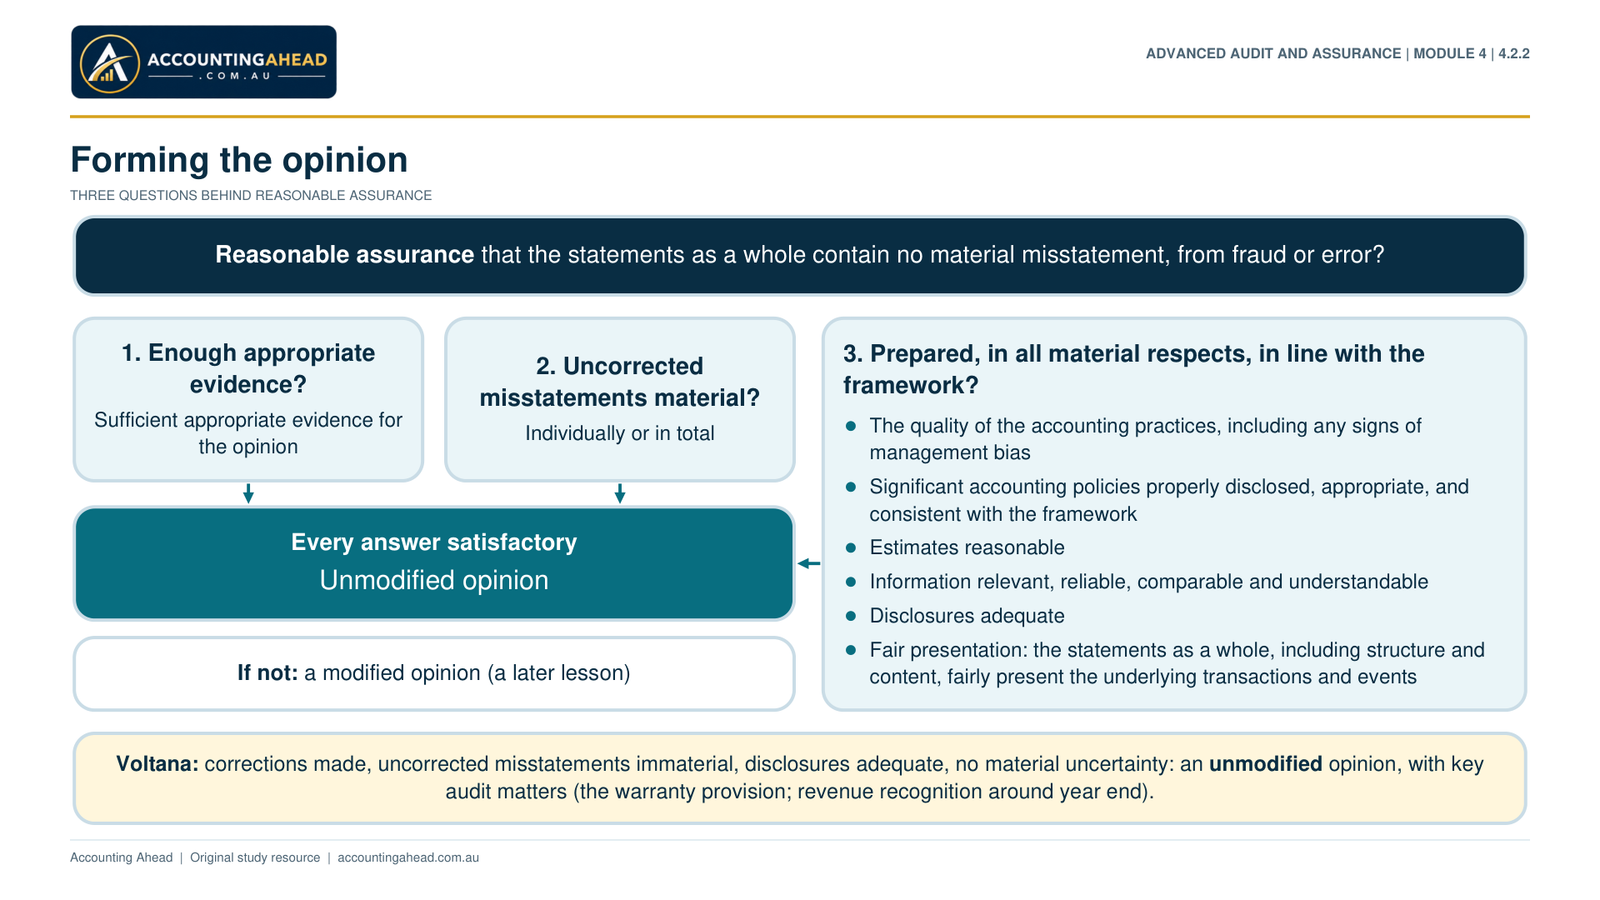
Part 4.2.2 · Final Review, EQR and Forming the Opinion
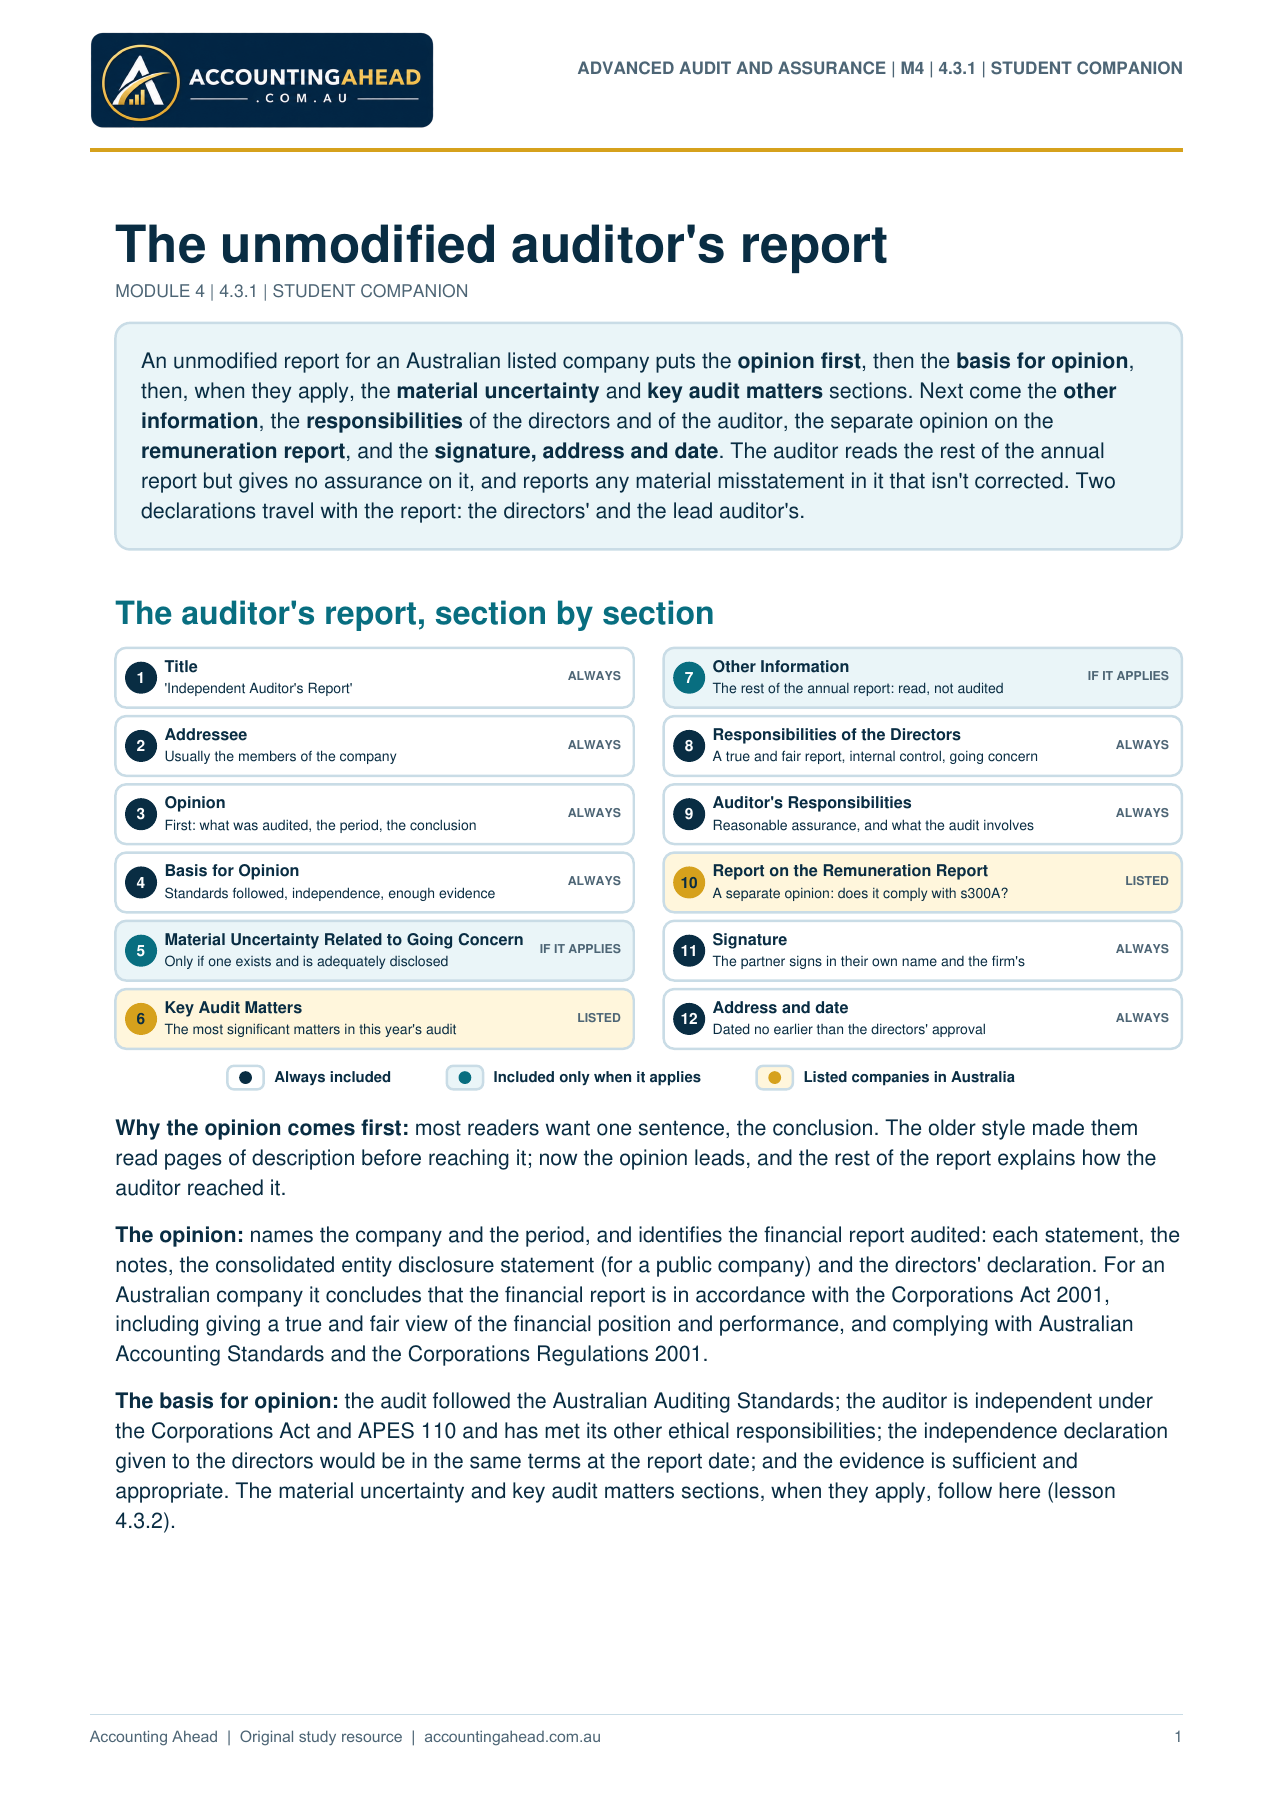
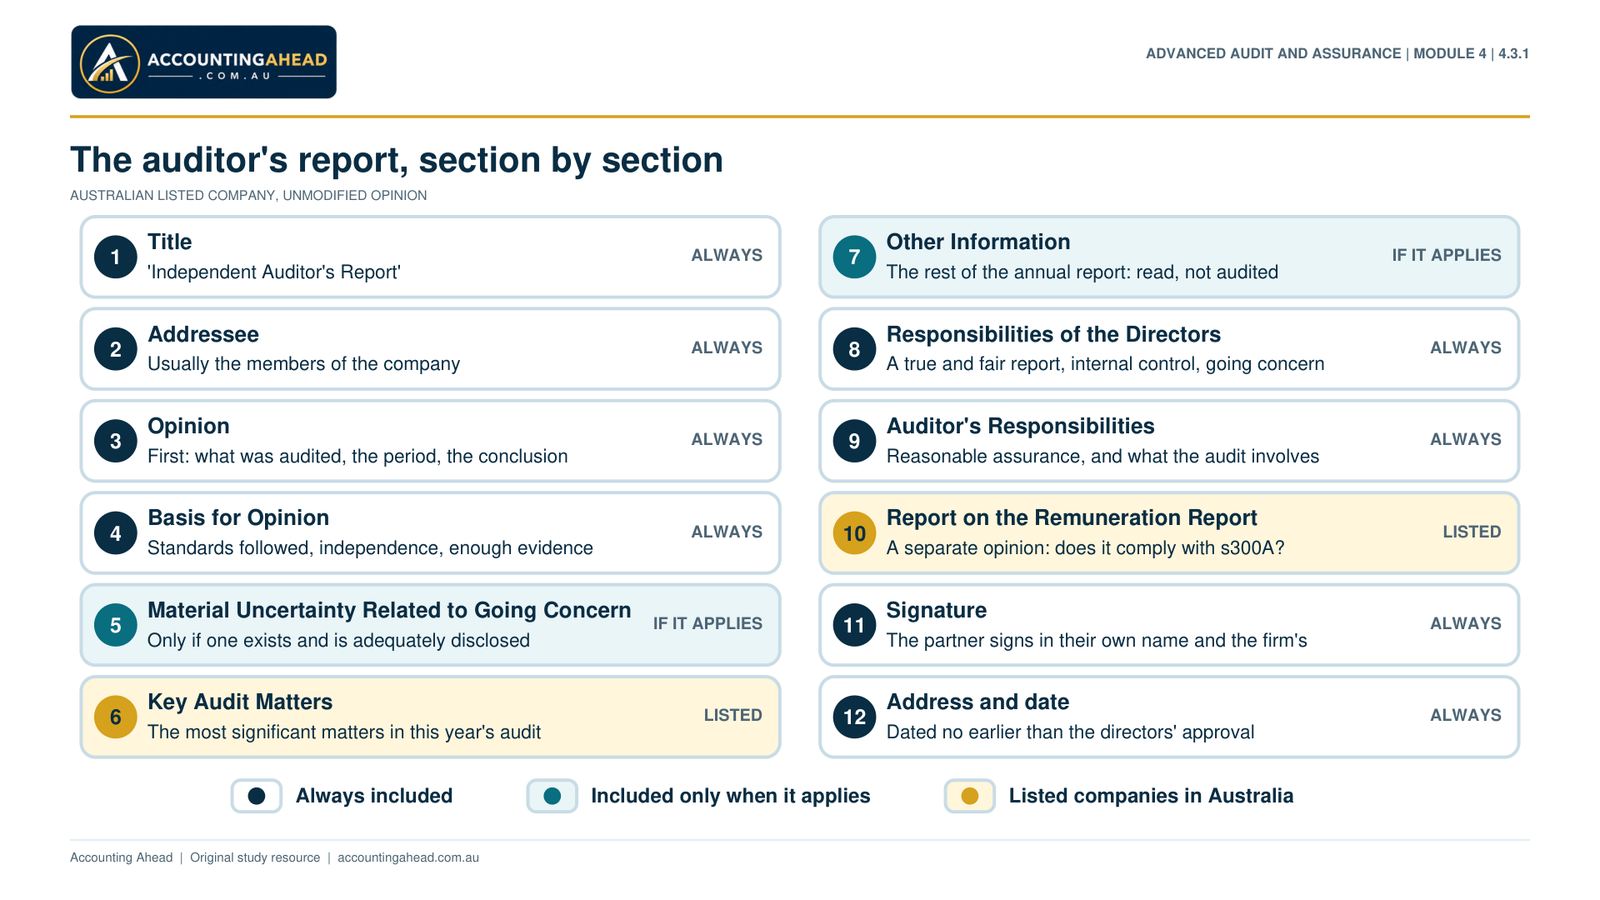
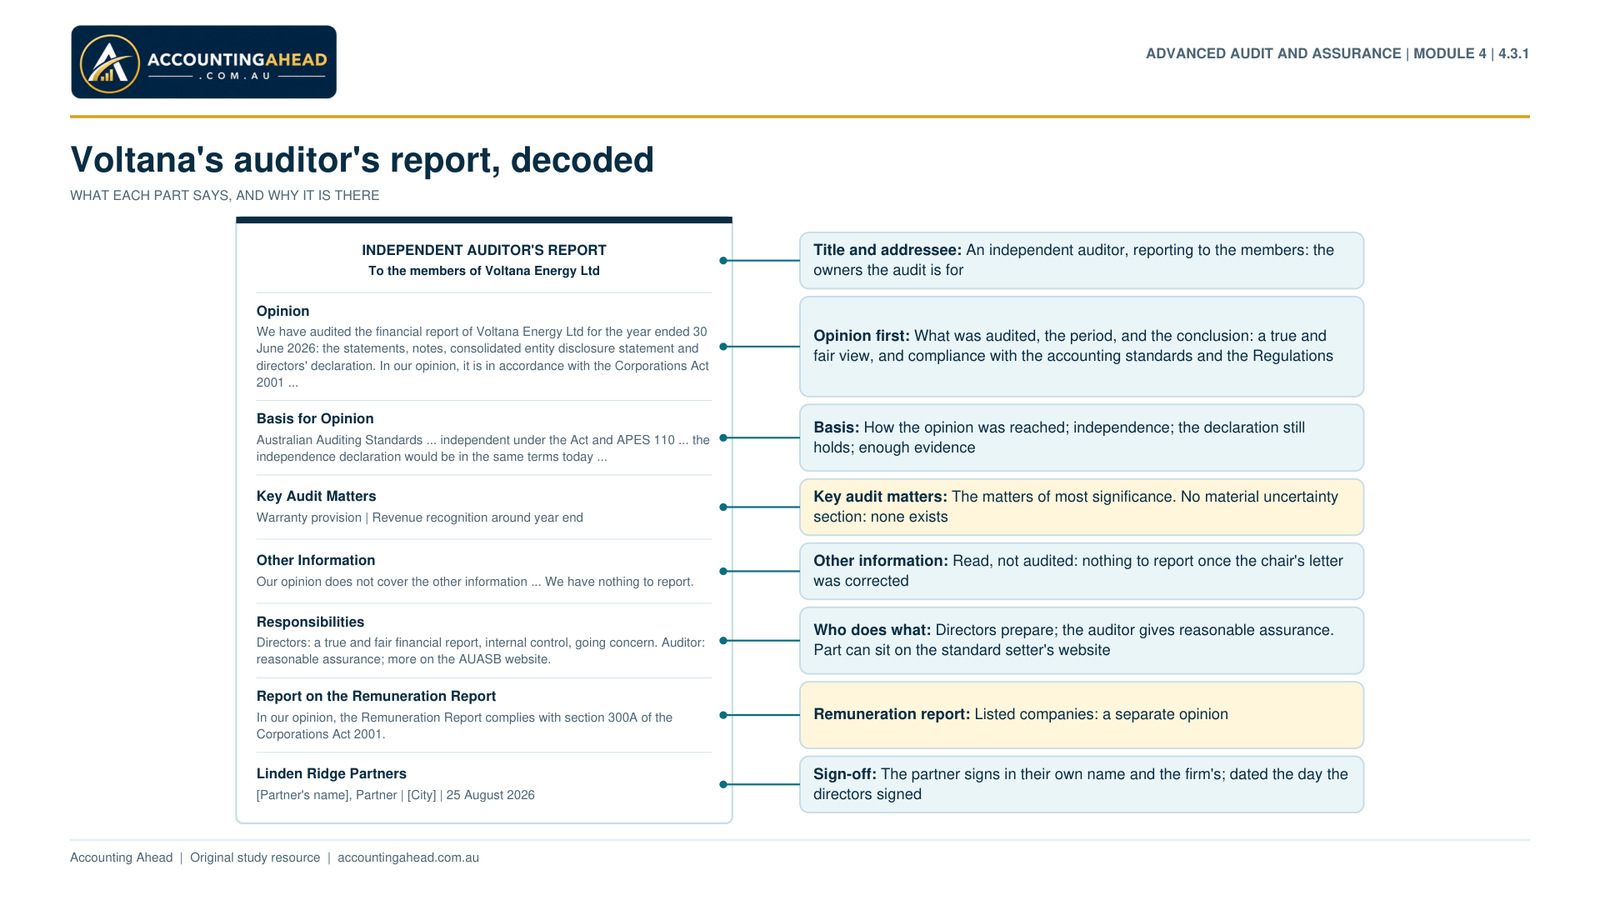
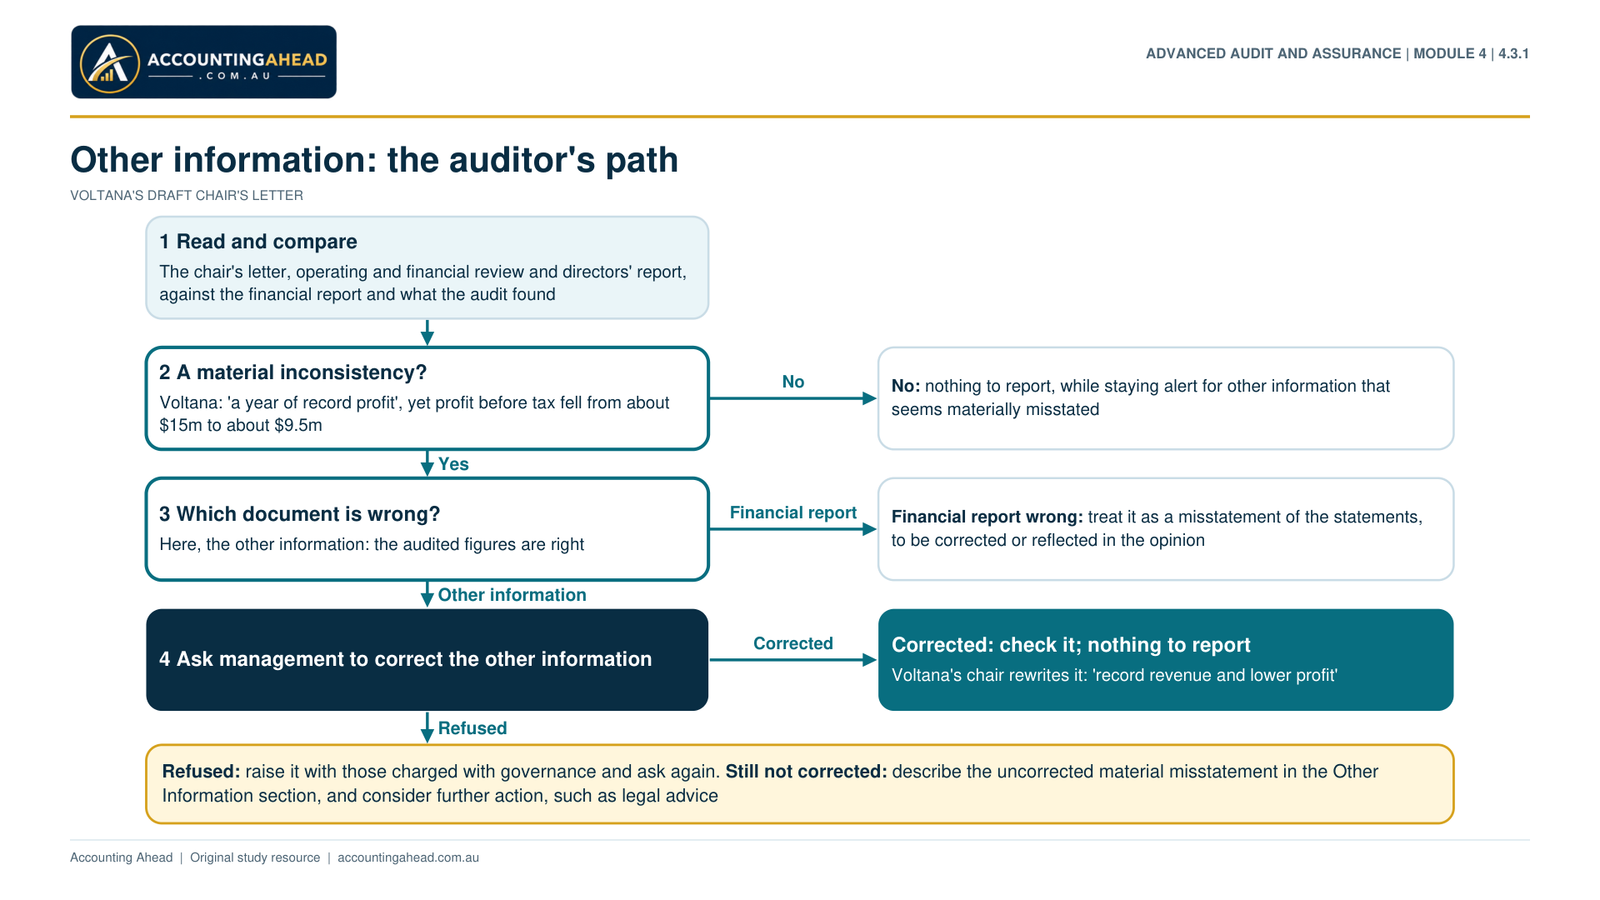
Part 4.3.1 · The Unmodified Auditor's Report
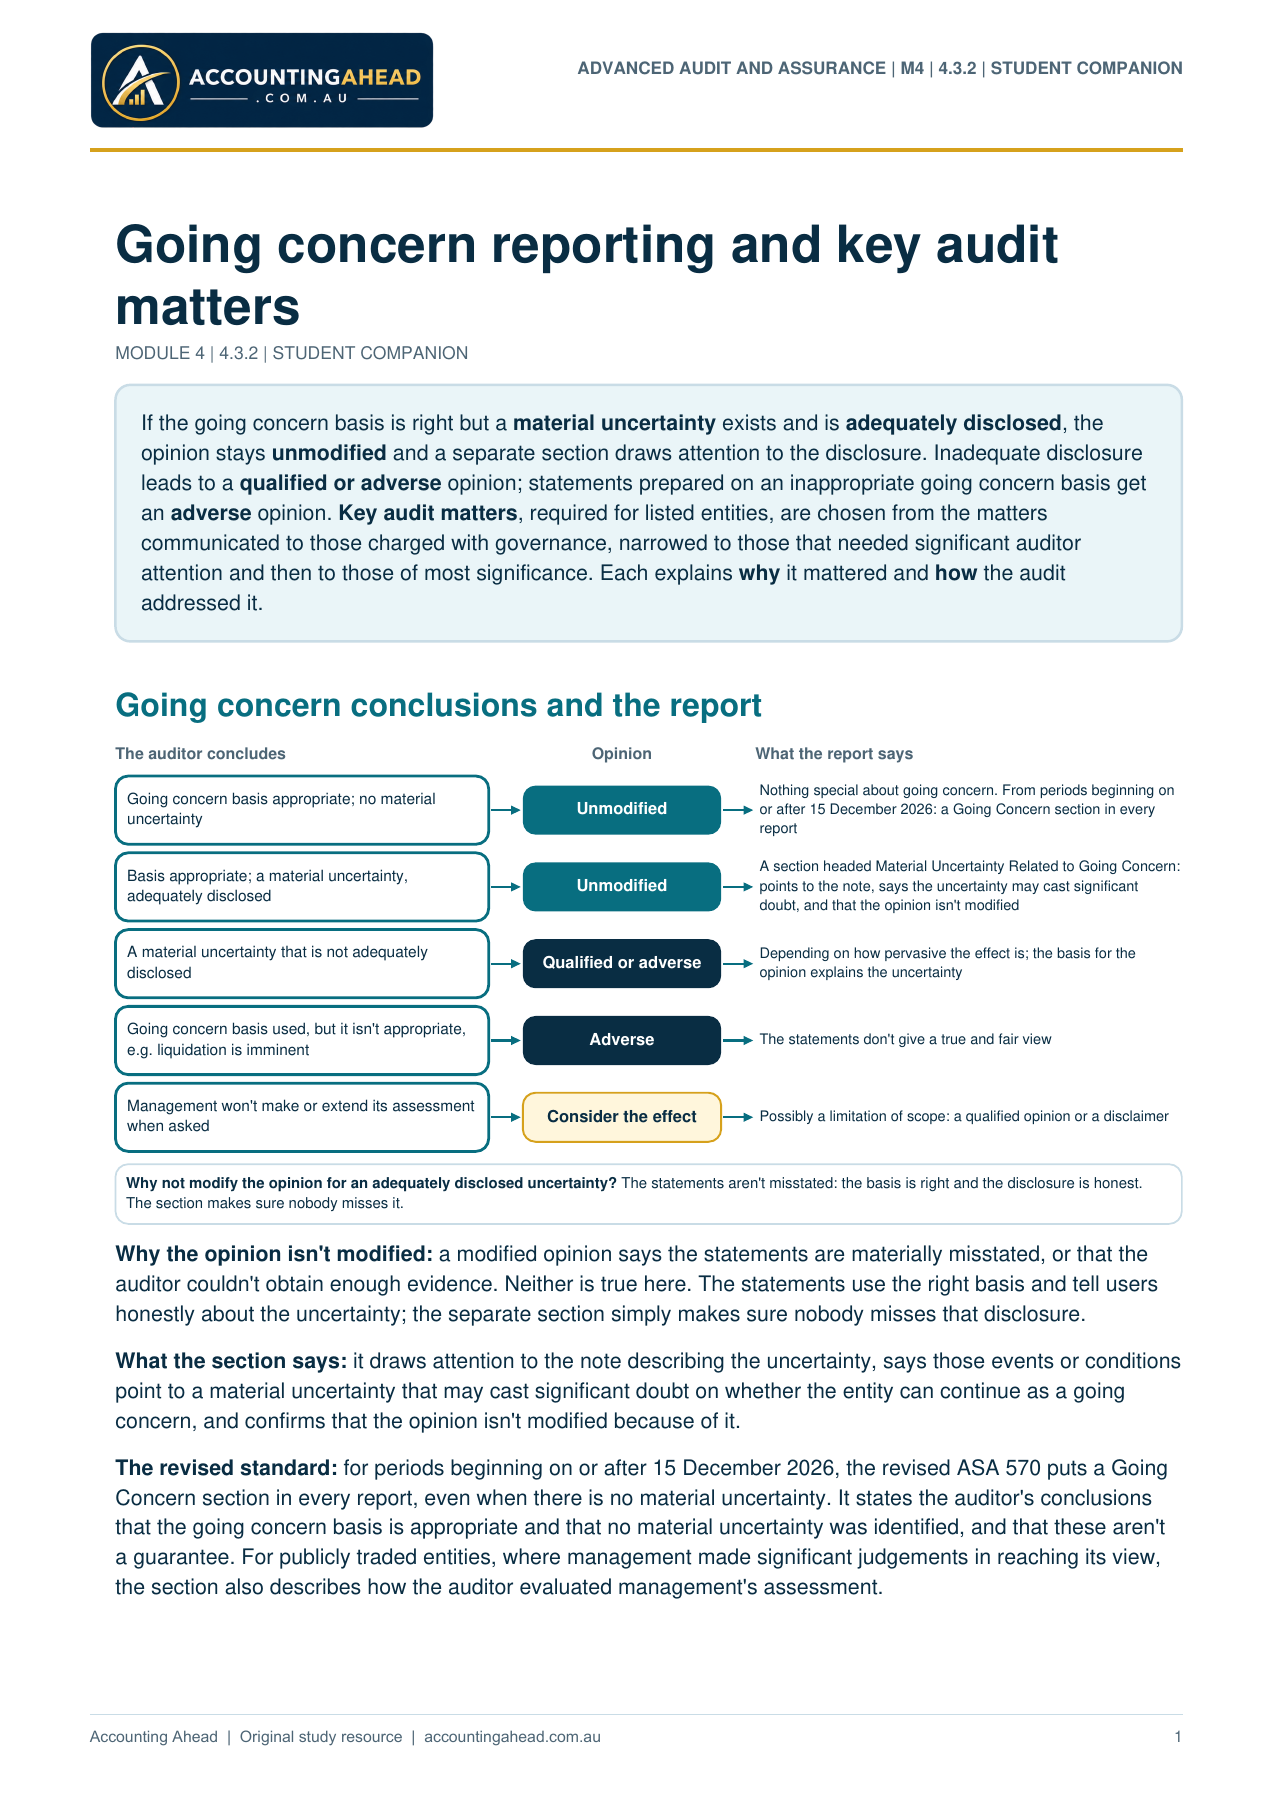
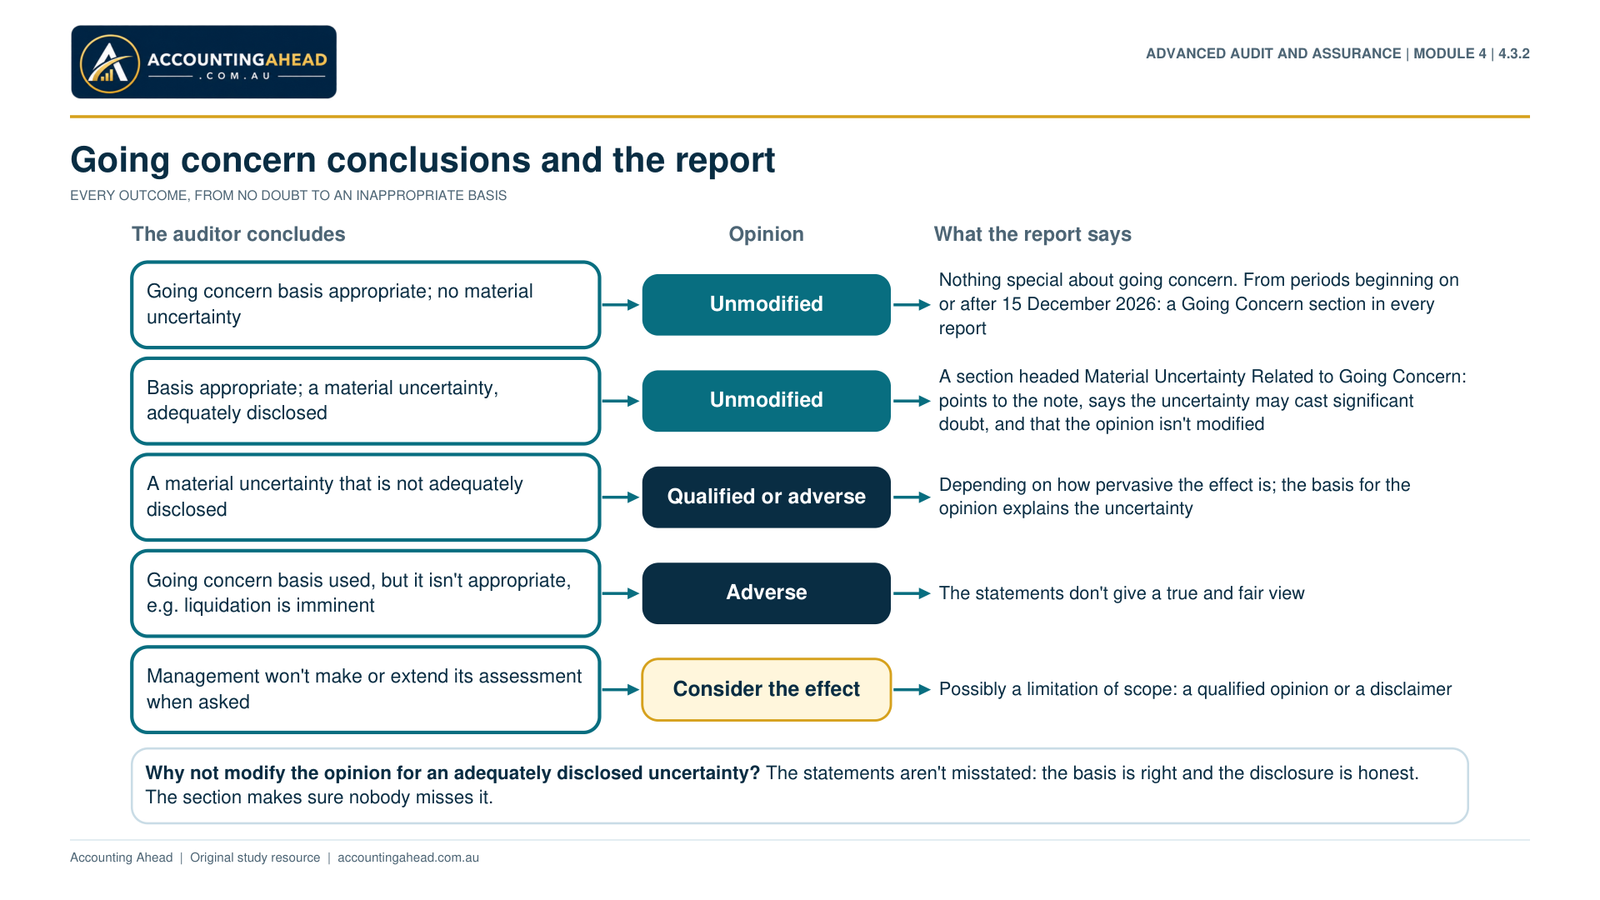
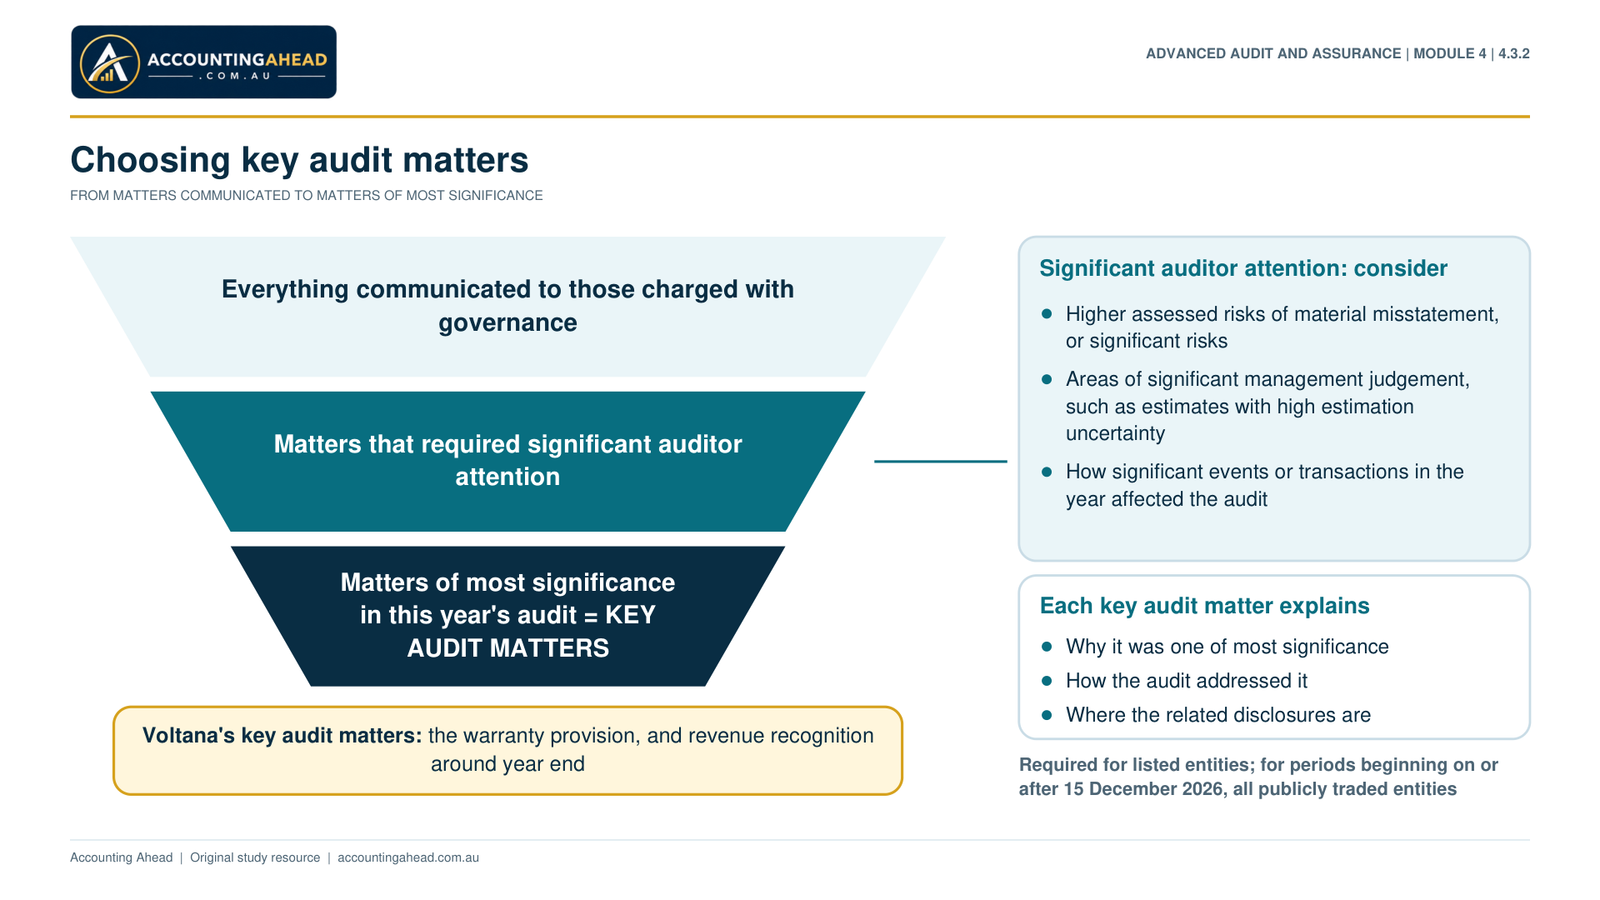
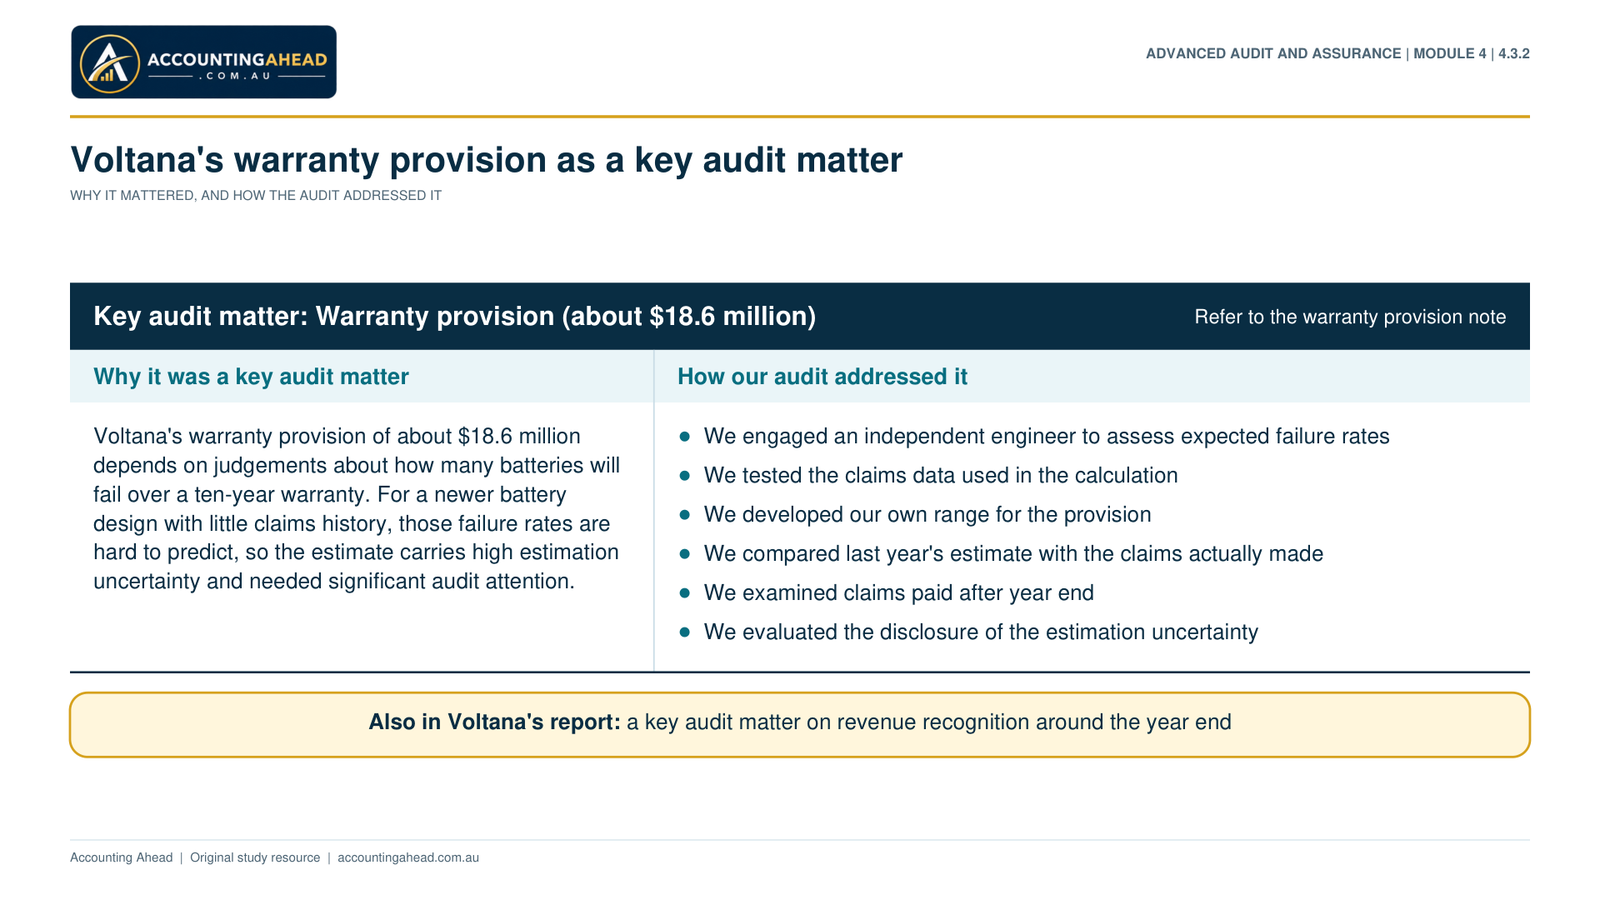
Part 4.3.2 · Going Concern Reporting and Key Audit Matters
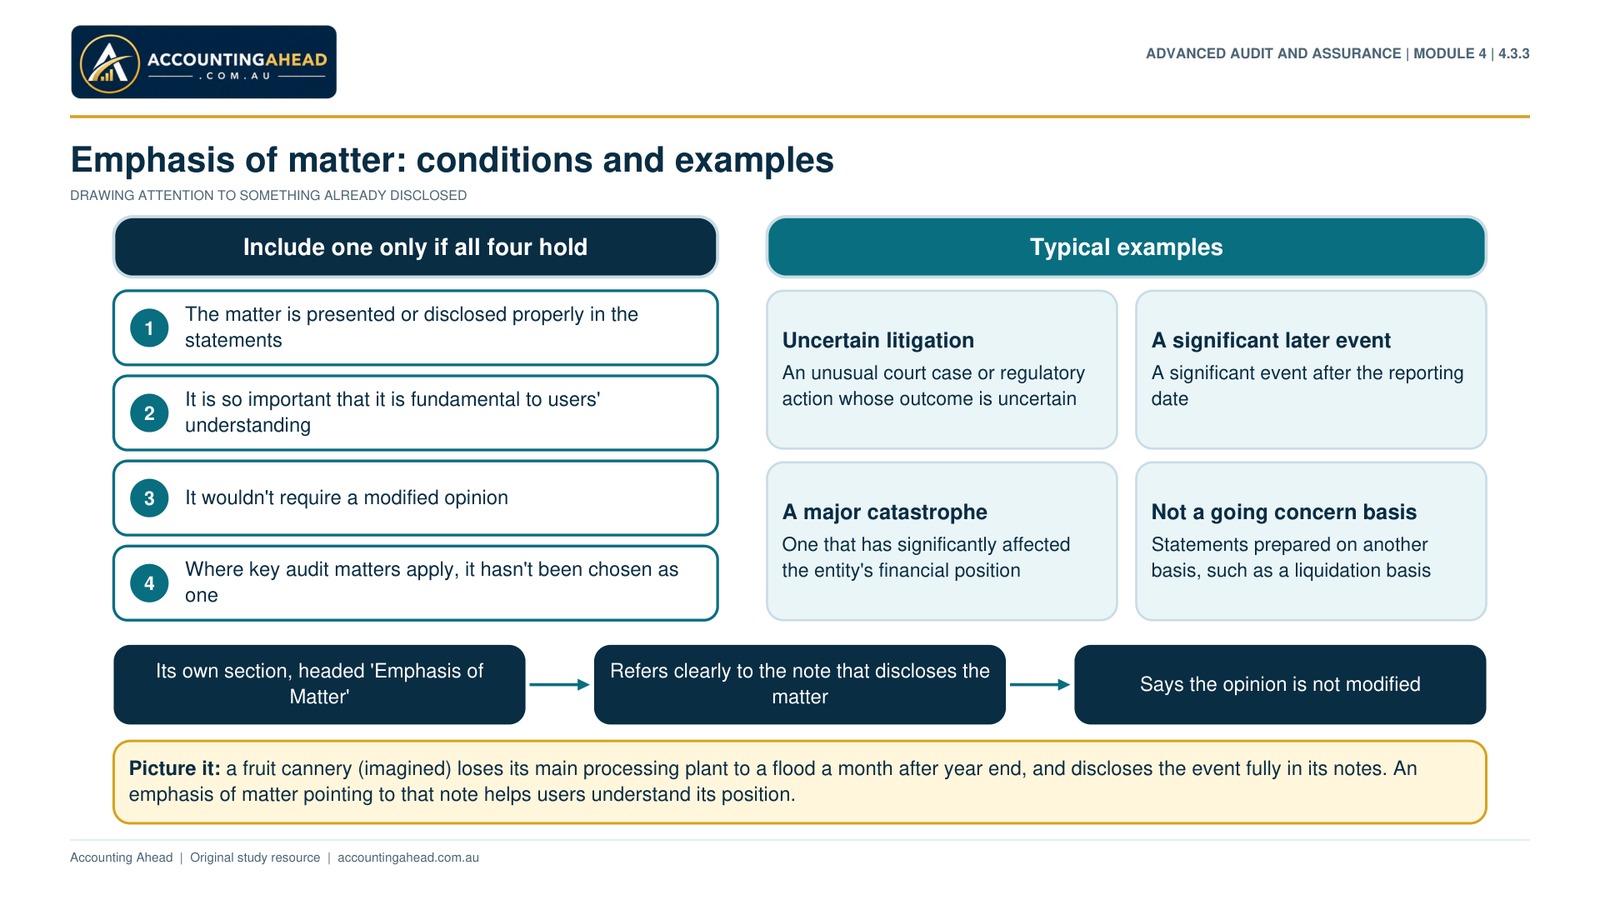
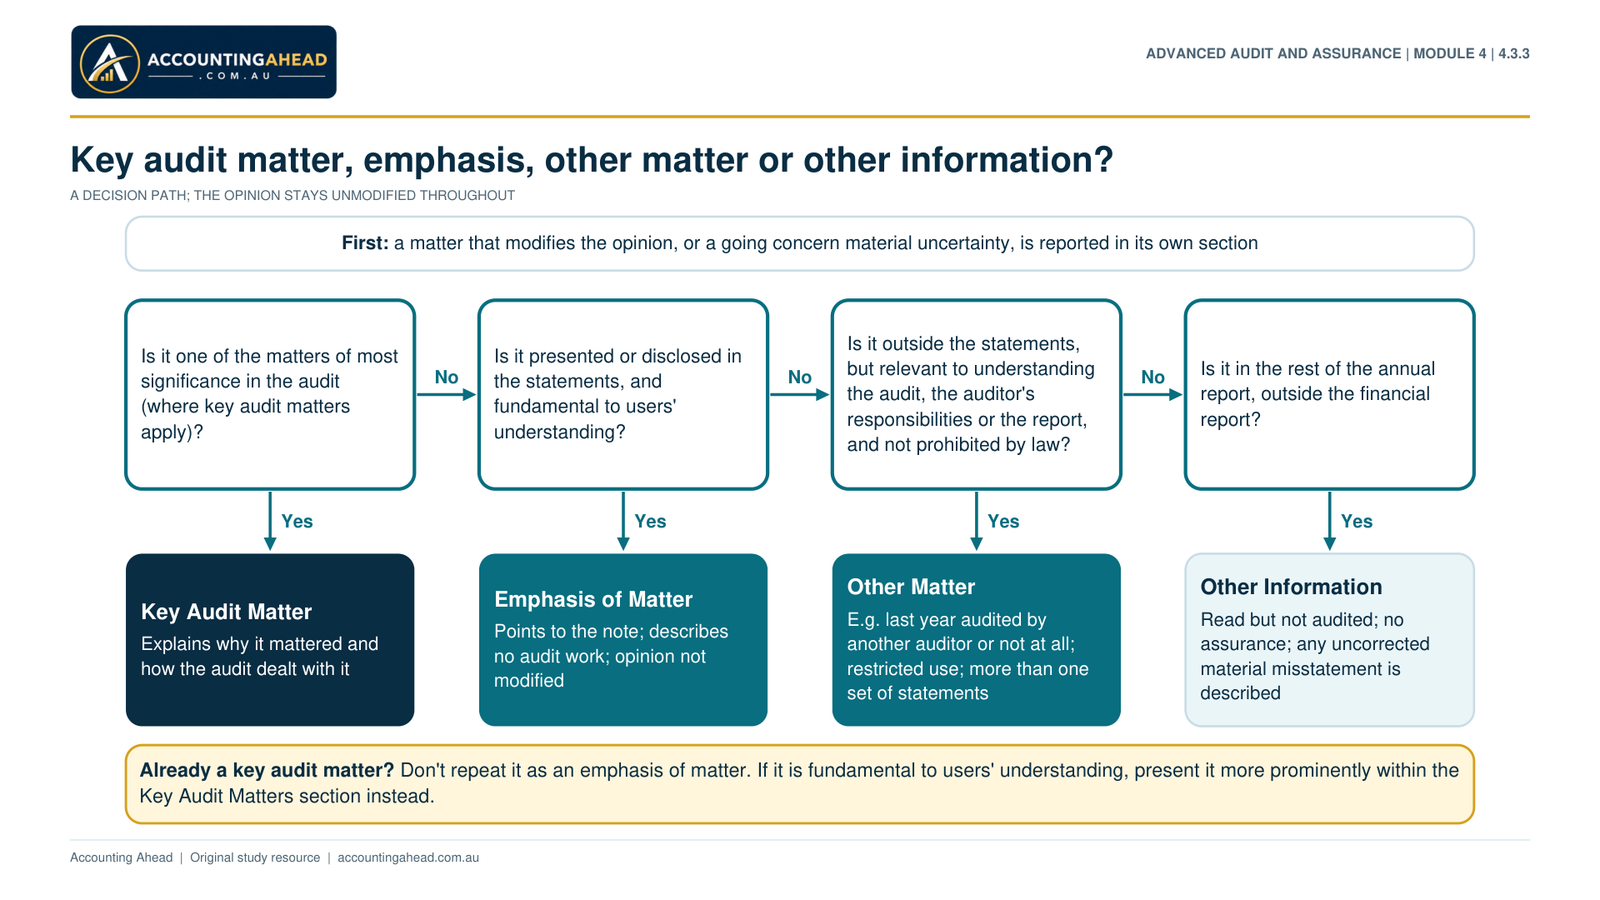
Part 4.3.3 · Emphasis of Matter and Other Matter
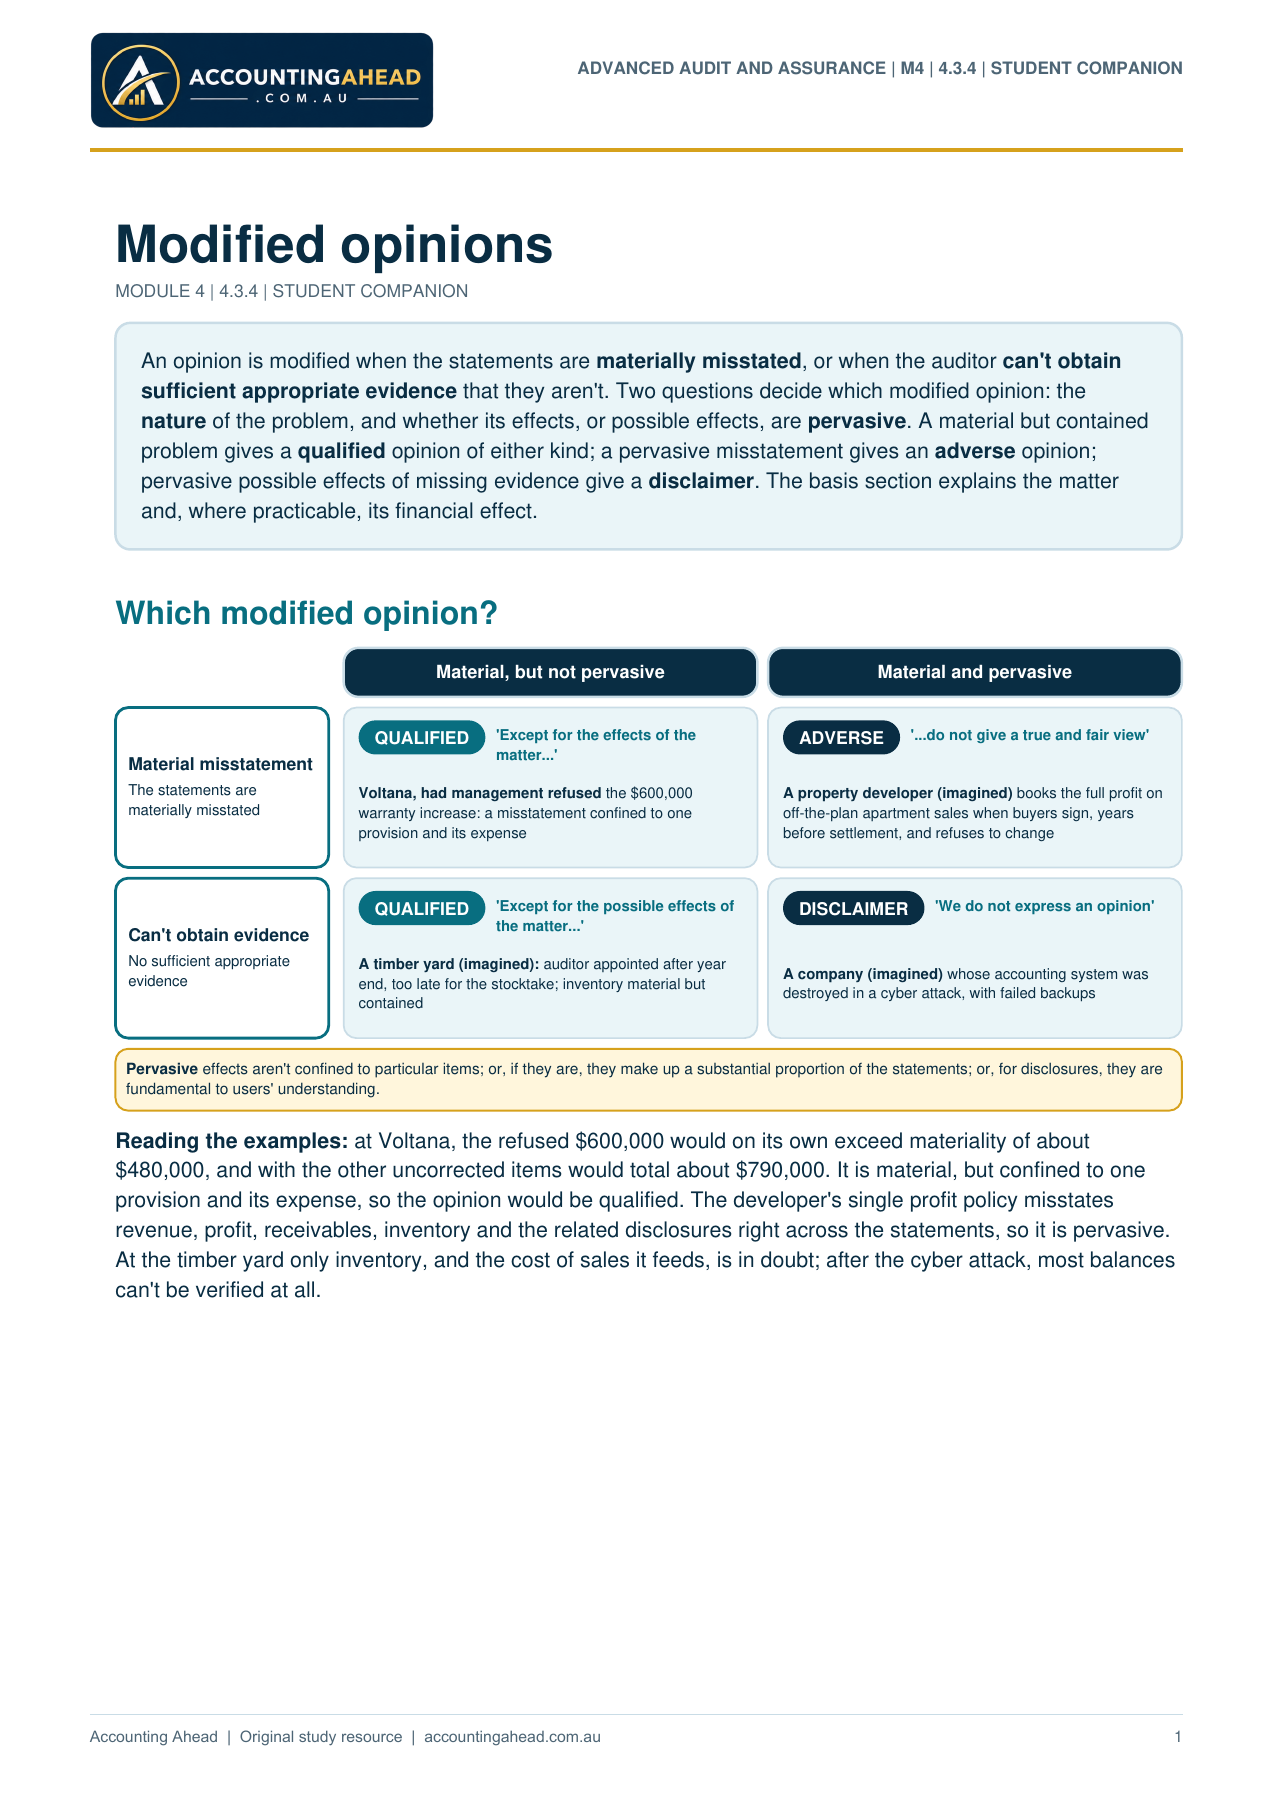
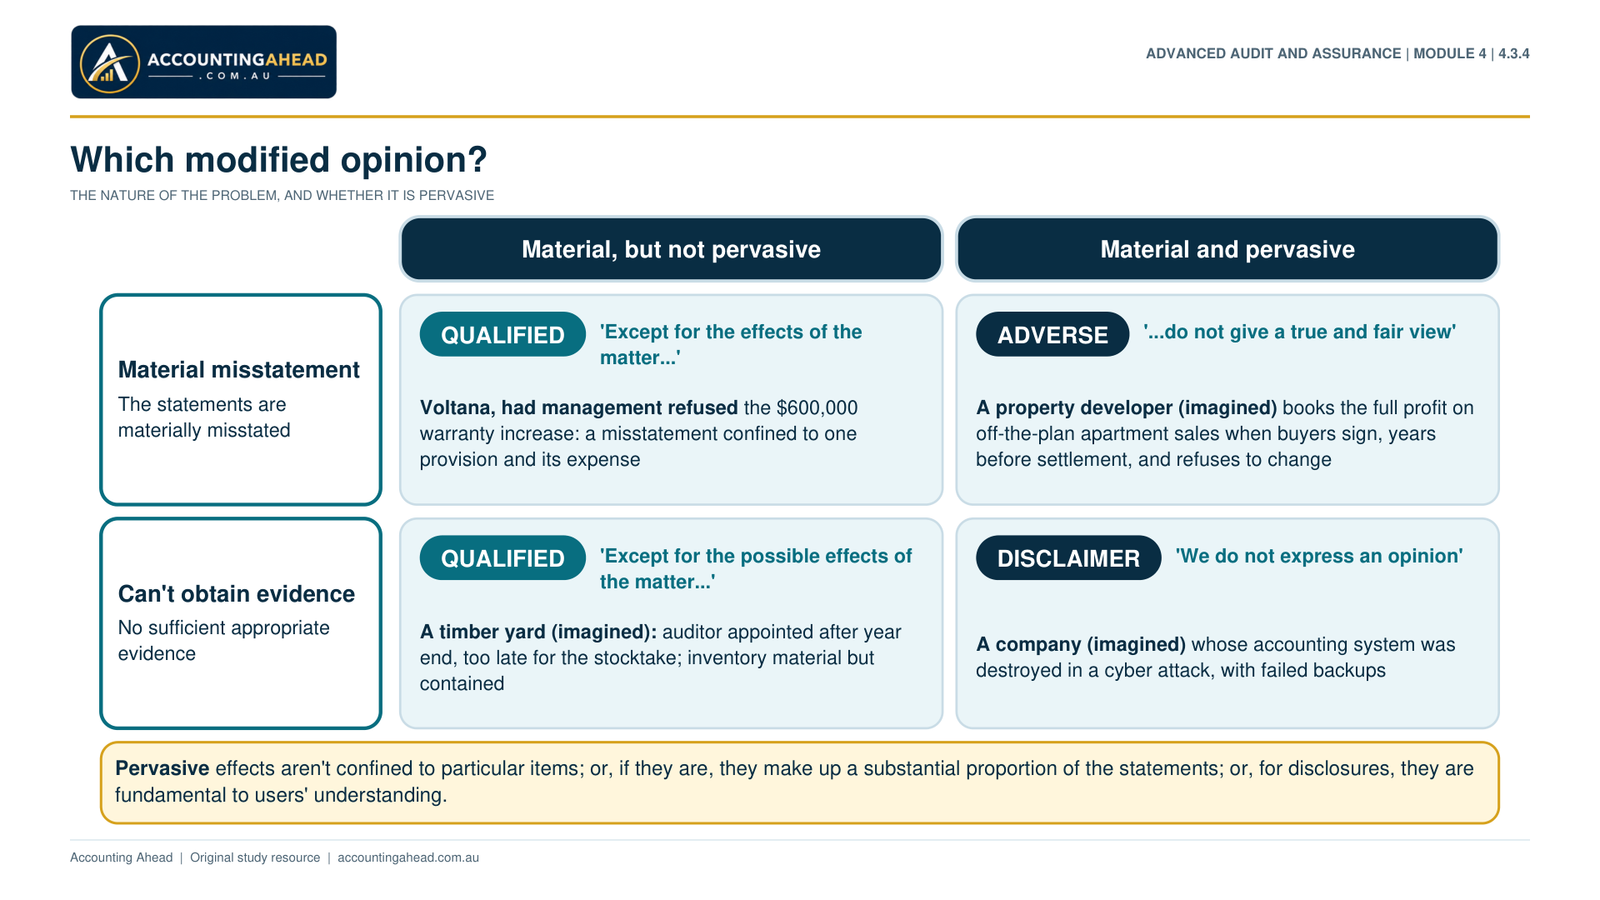
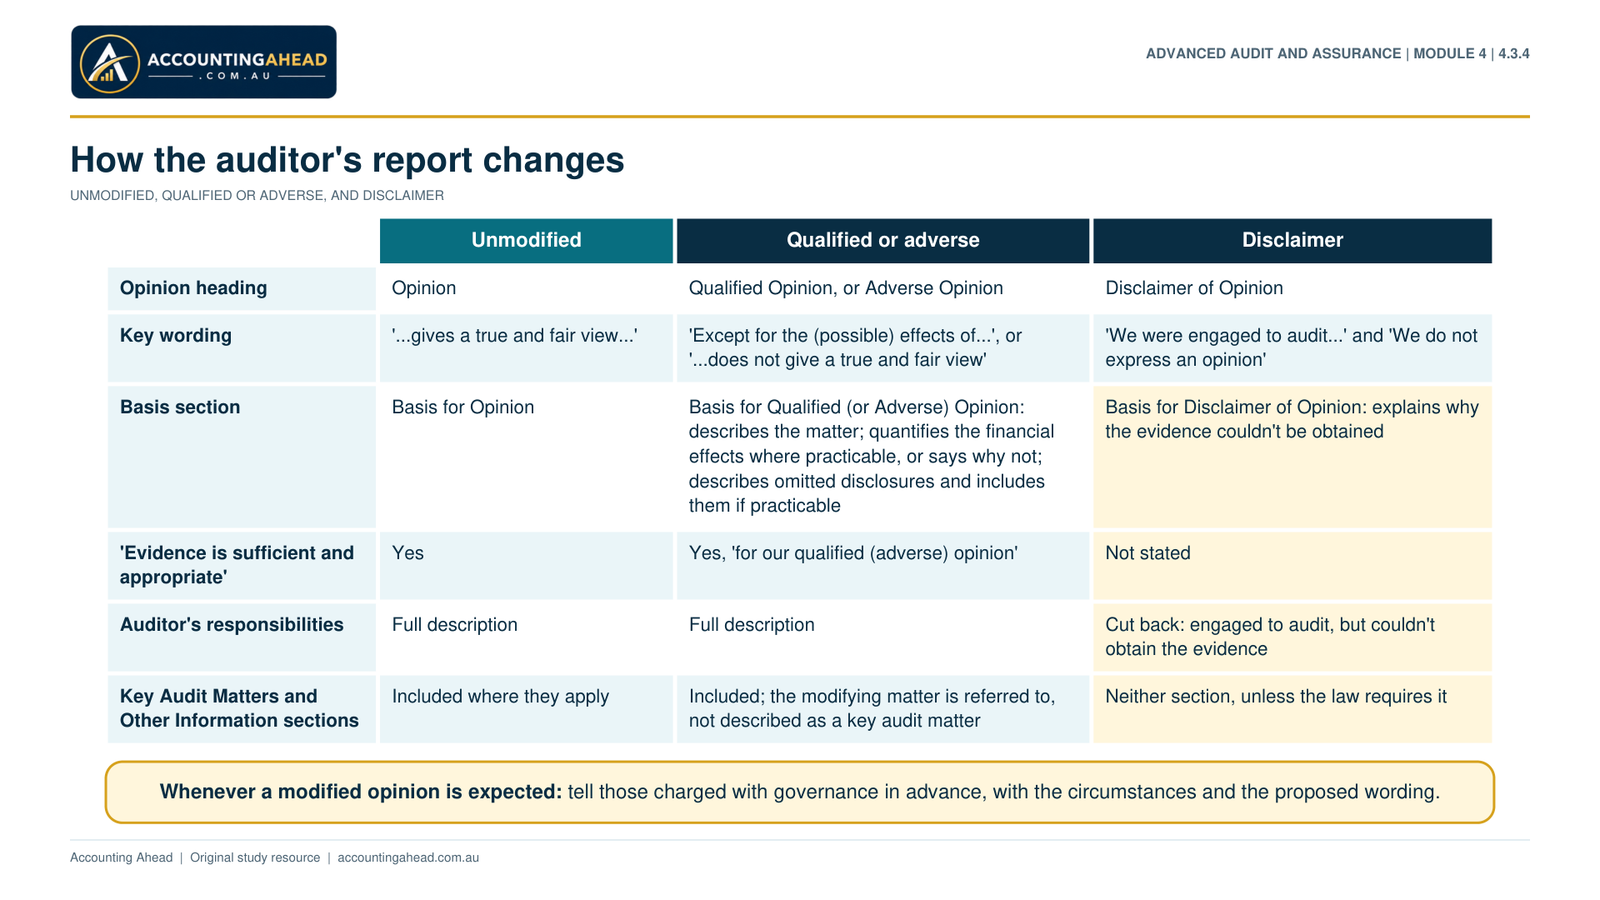
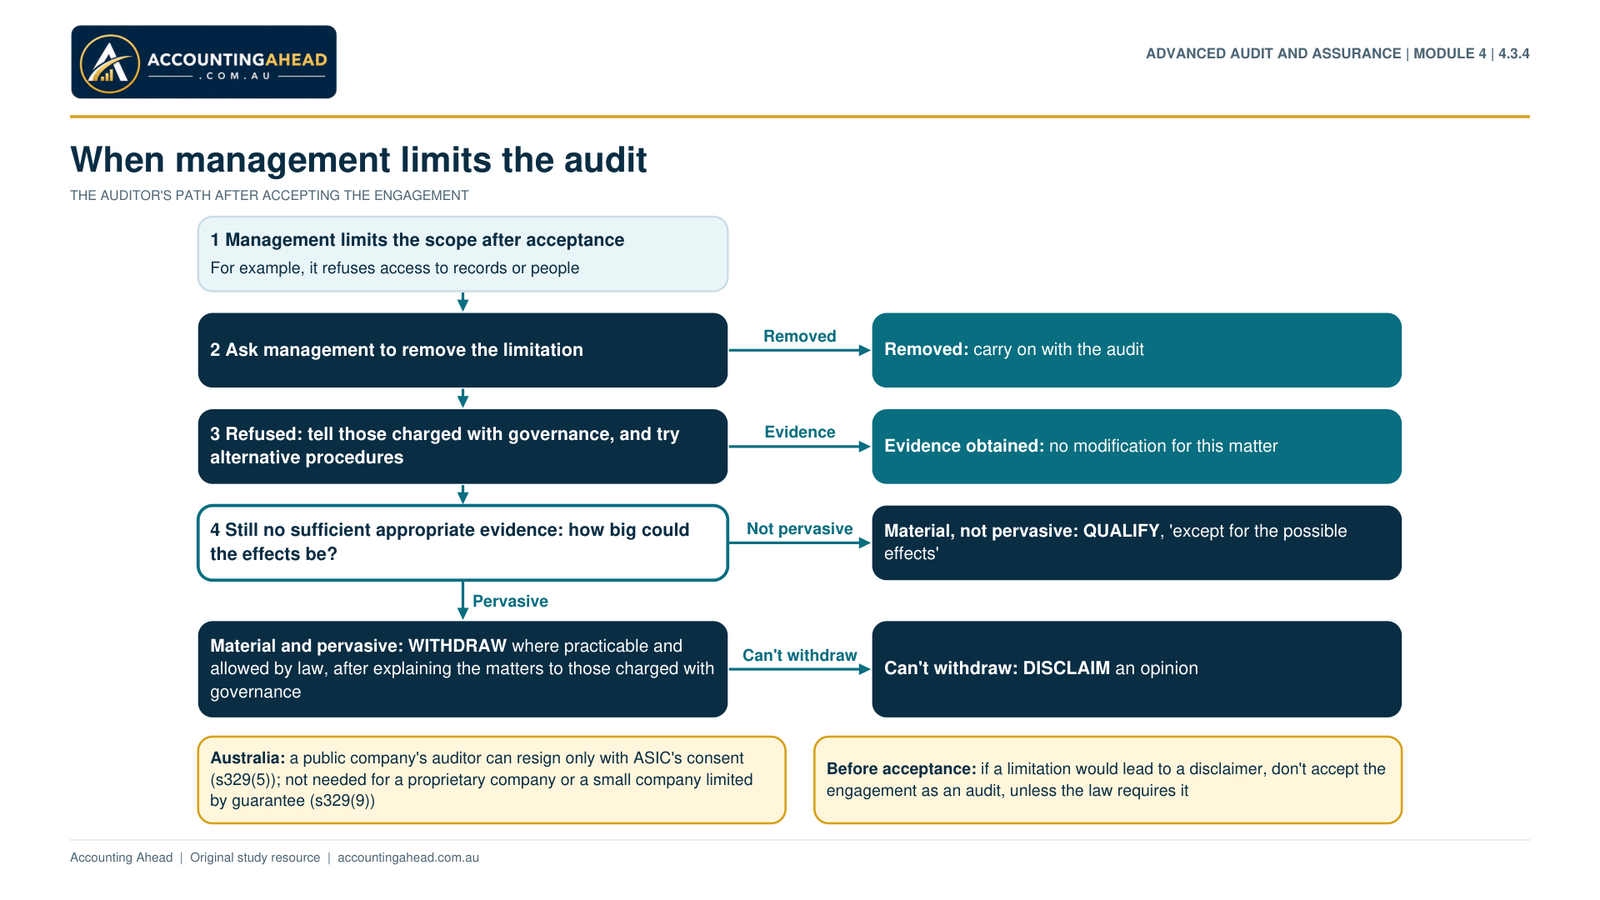
Part 4.3.4 · Modified Opinions
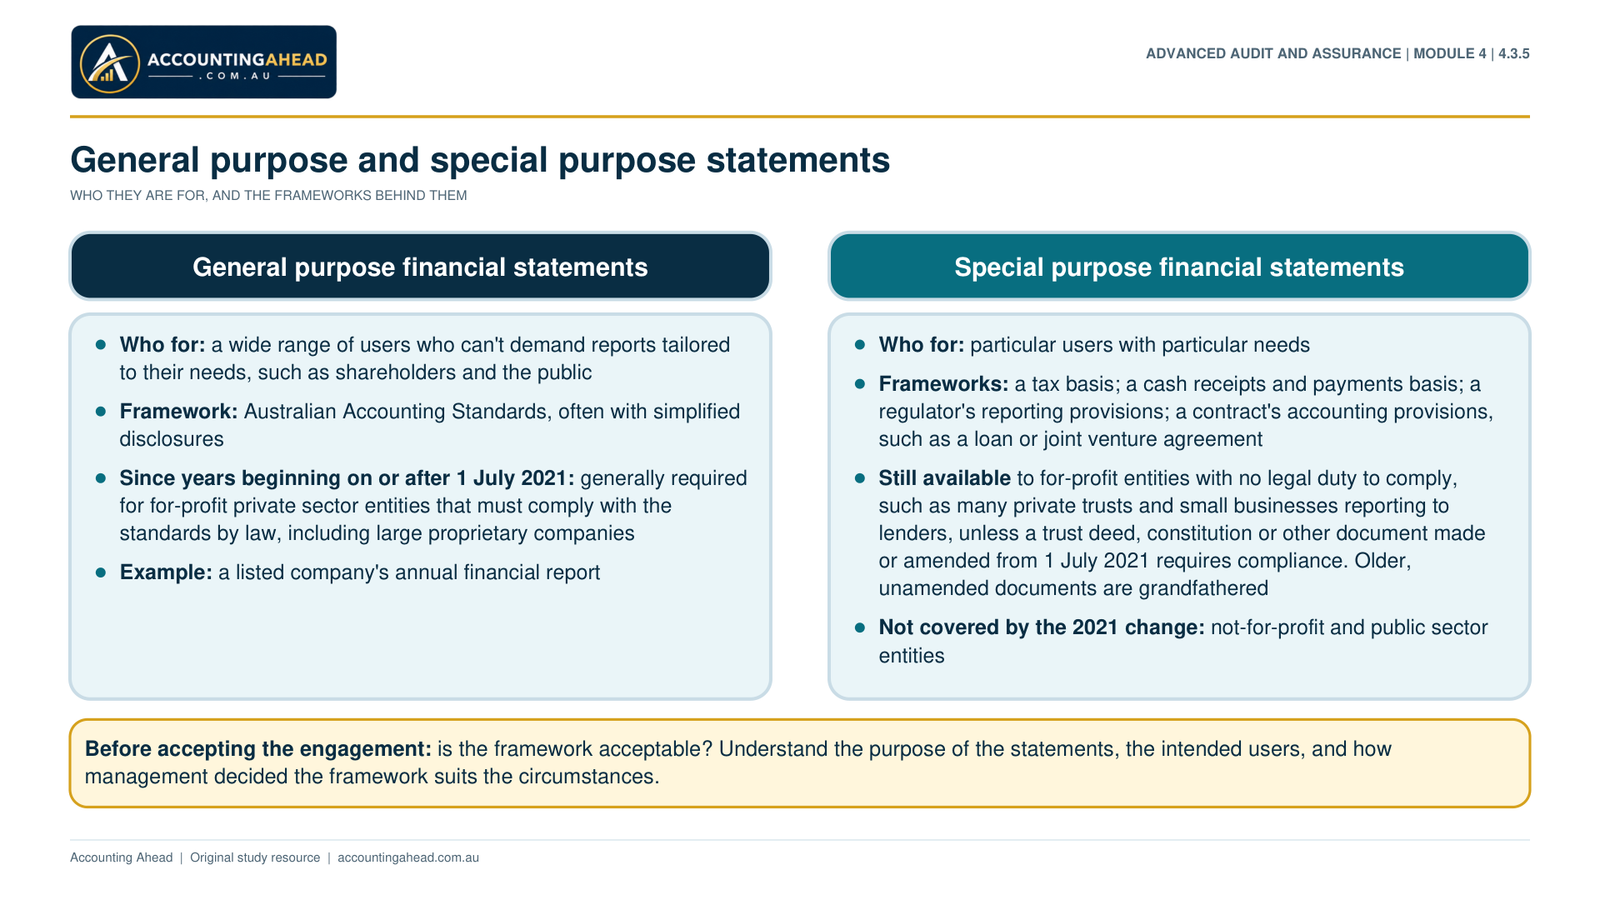
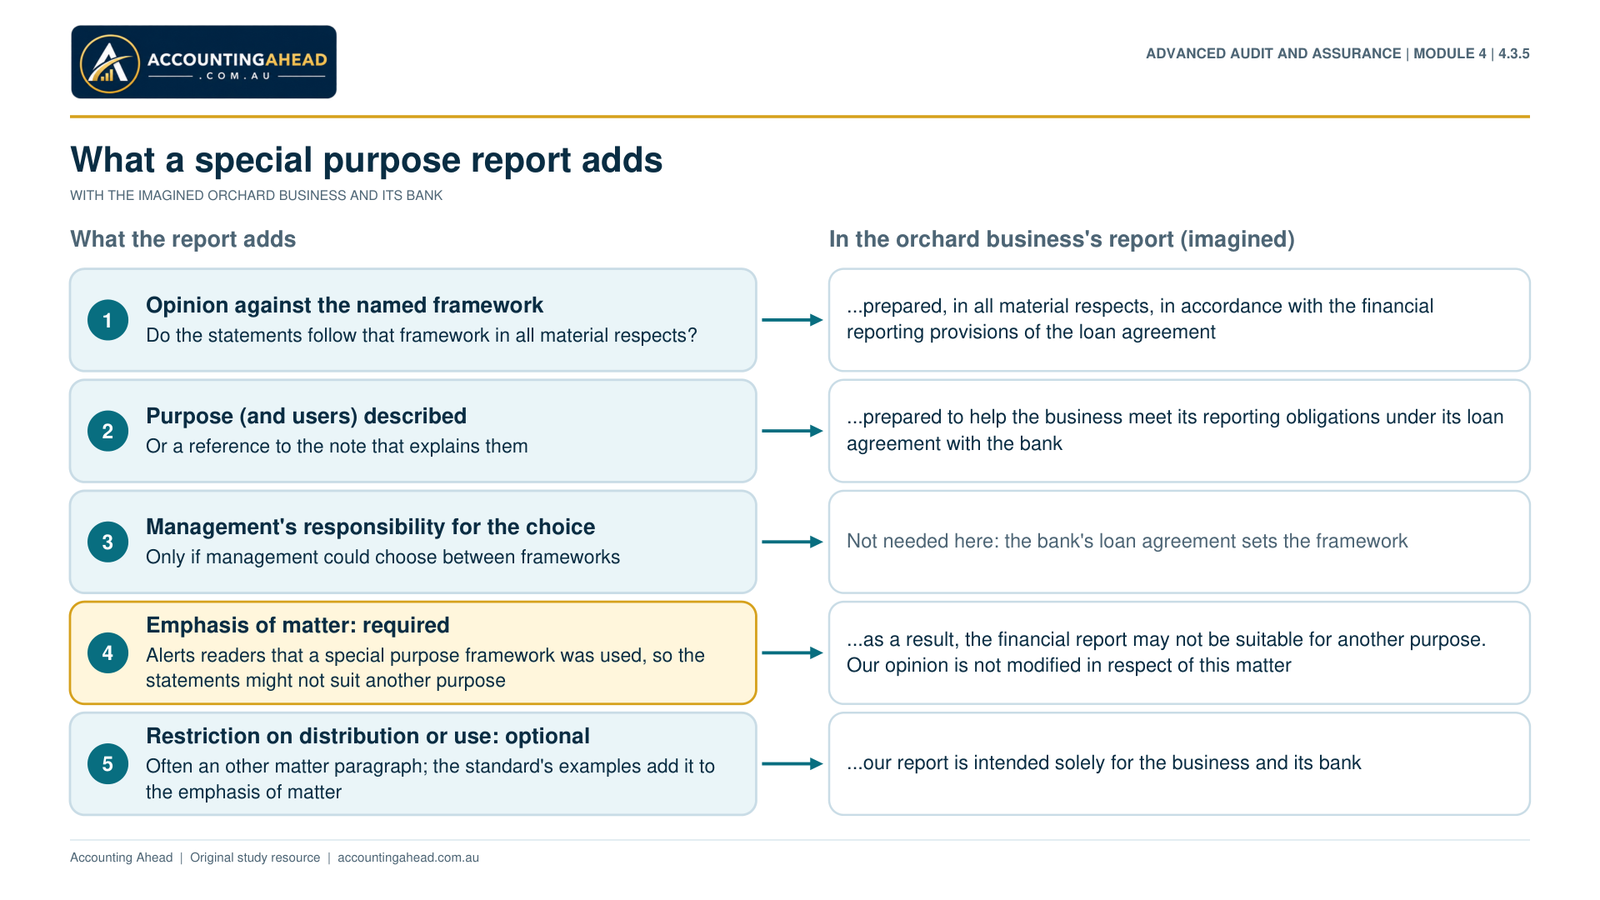
Part 4.3.5 · Reporting on Special Purpose Statements
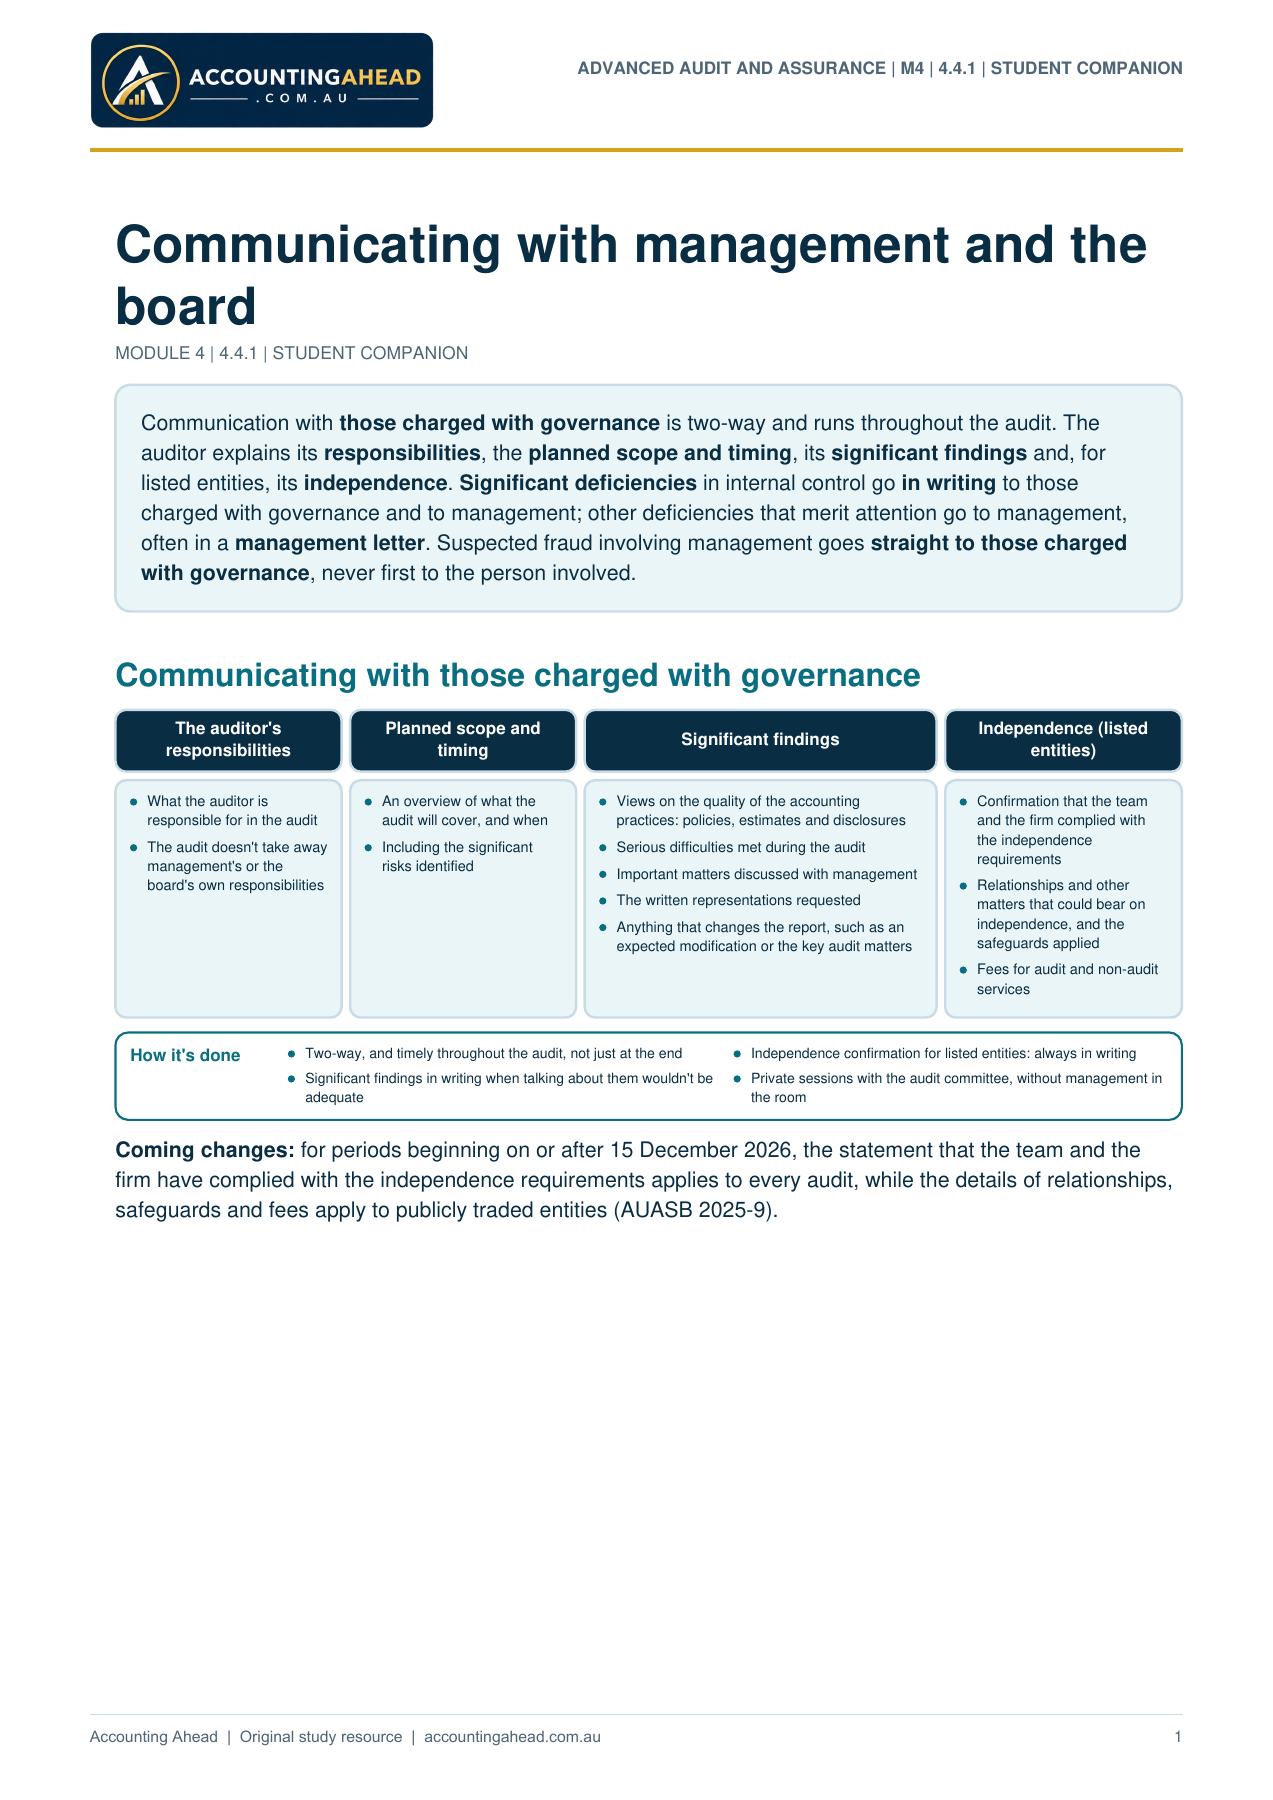
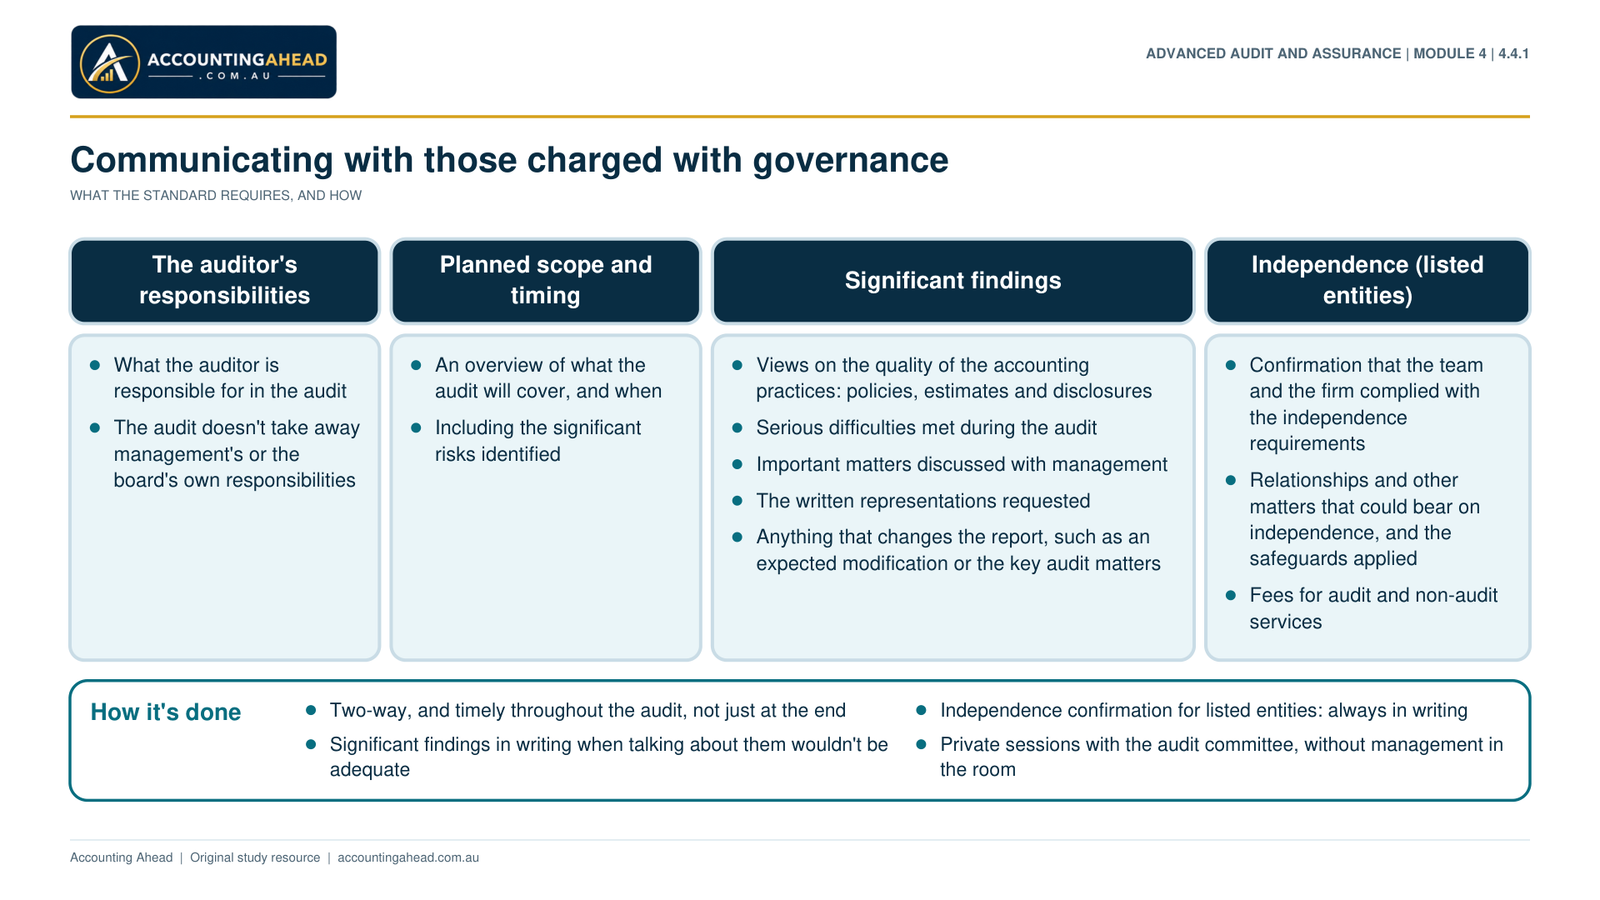
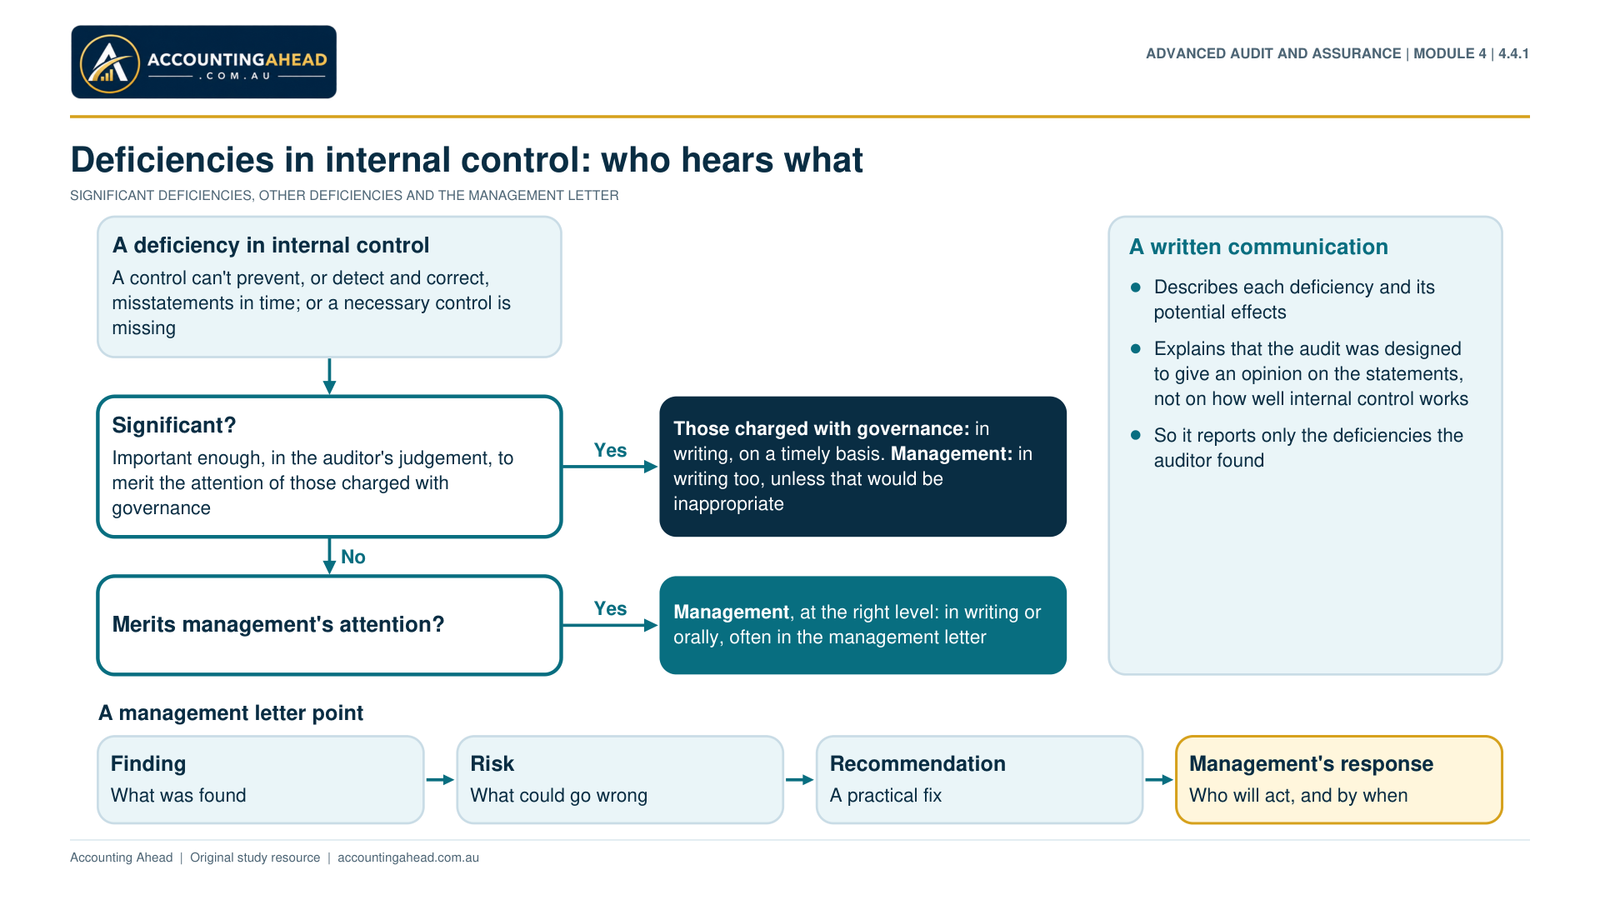
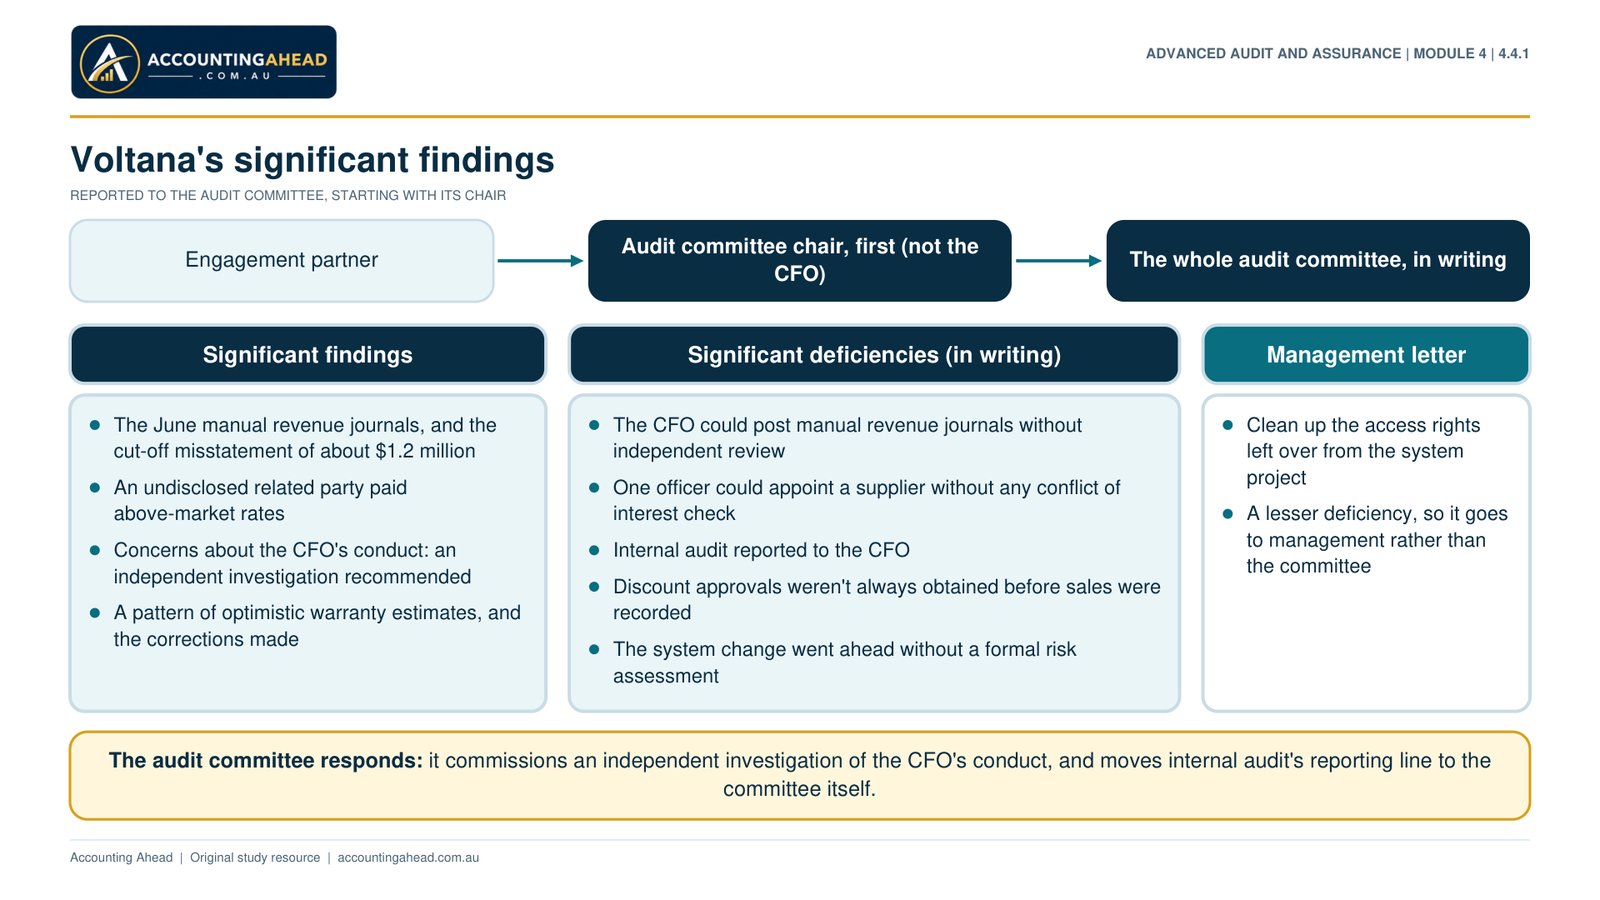
Part 4.4.1 · Communicating with Management and the Board
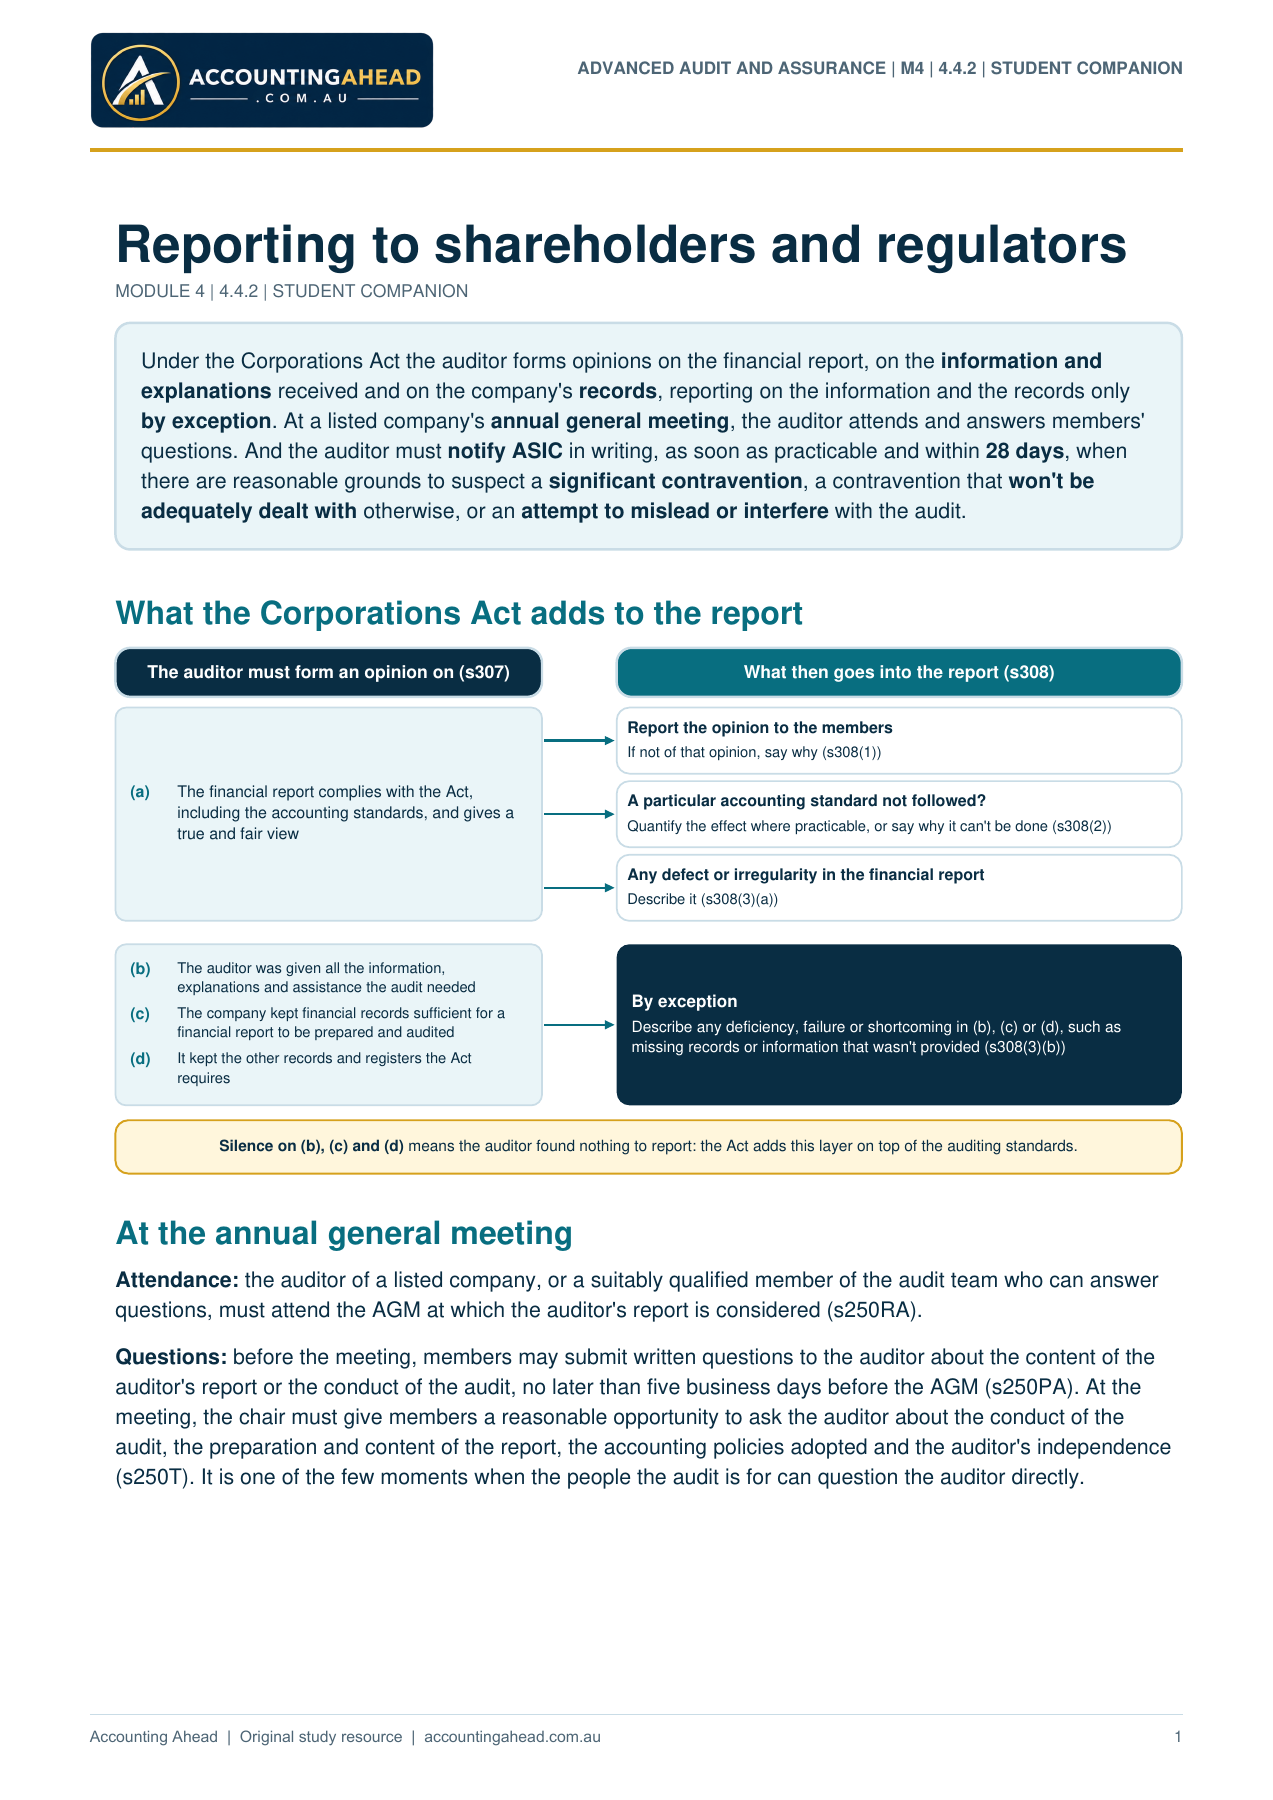
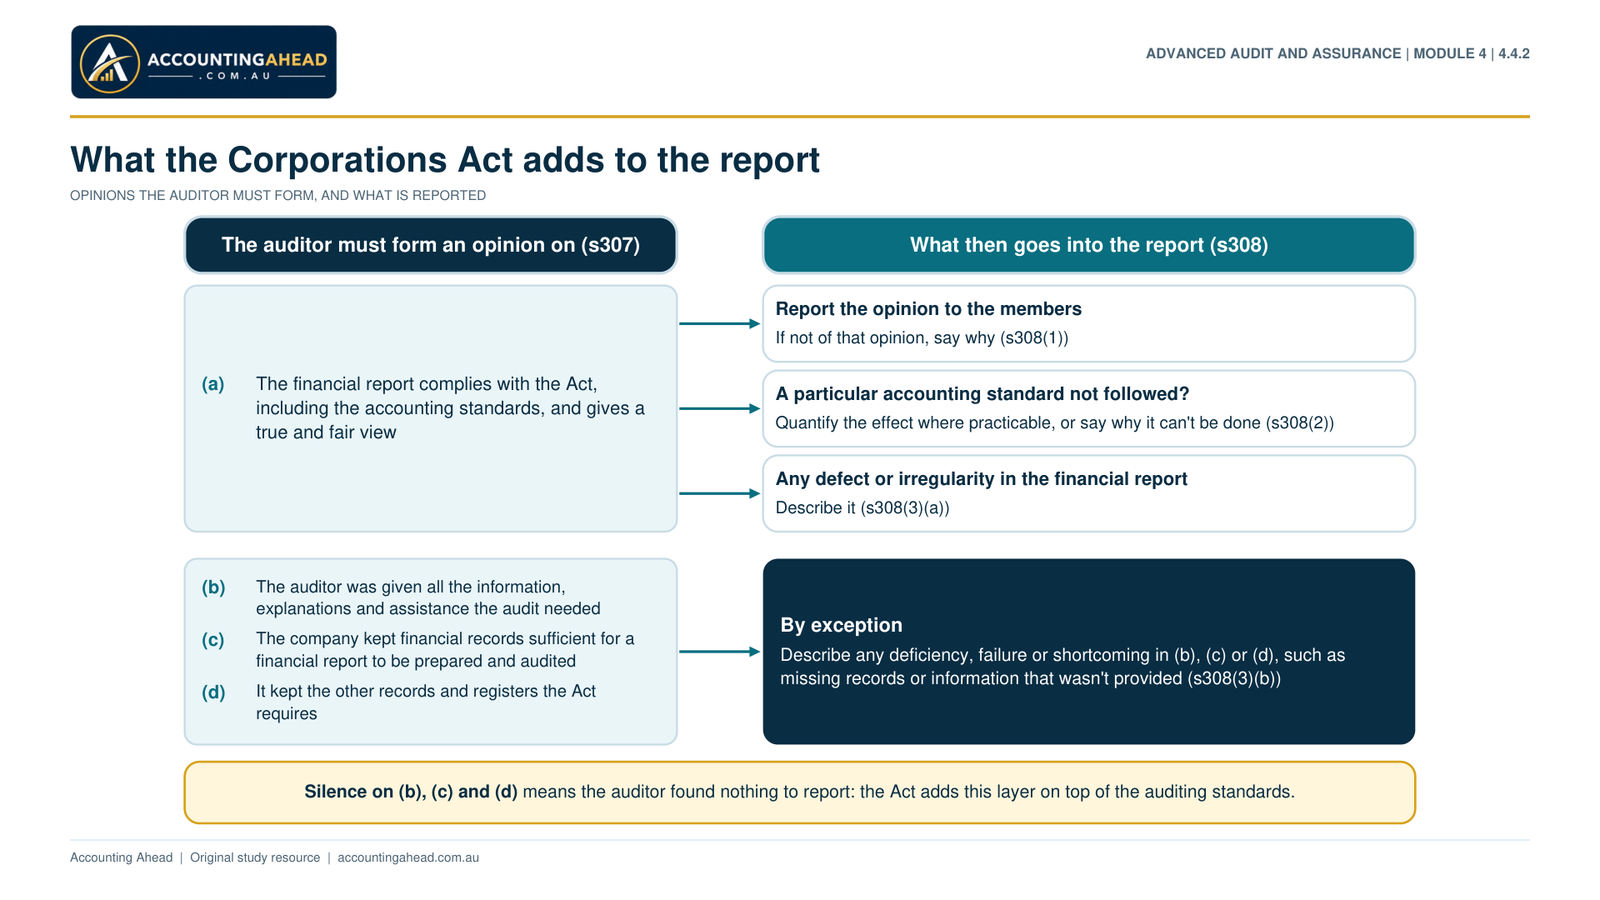
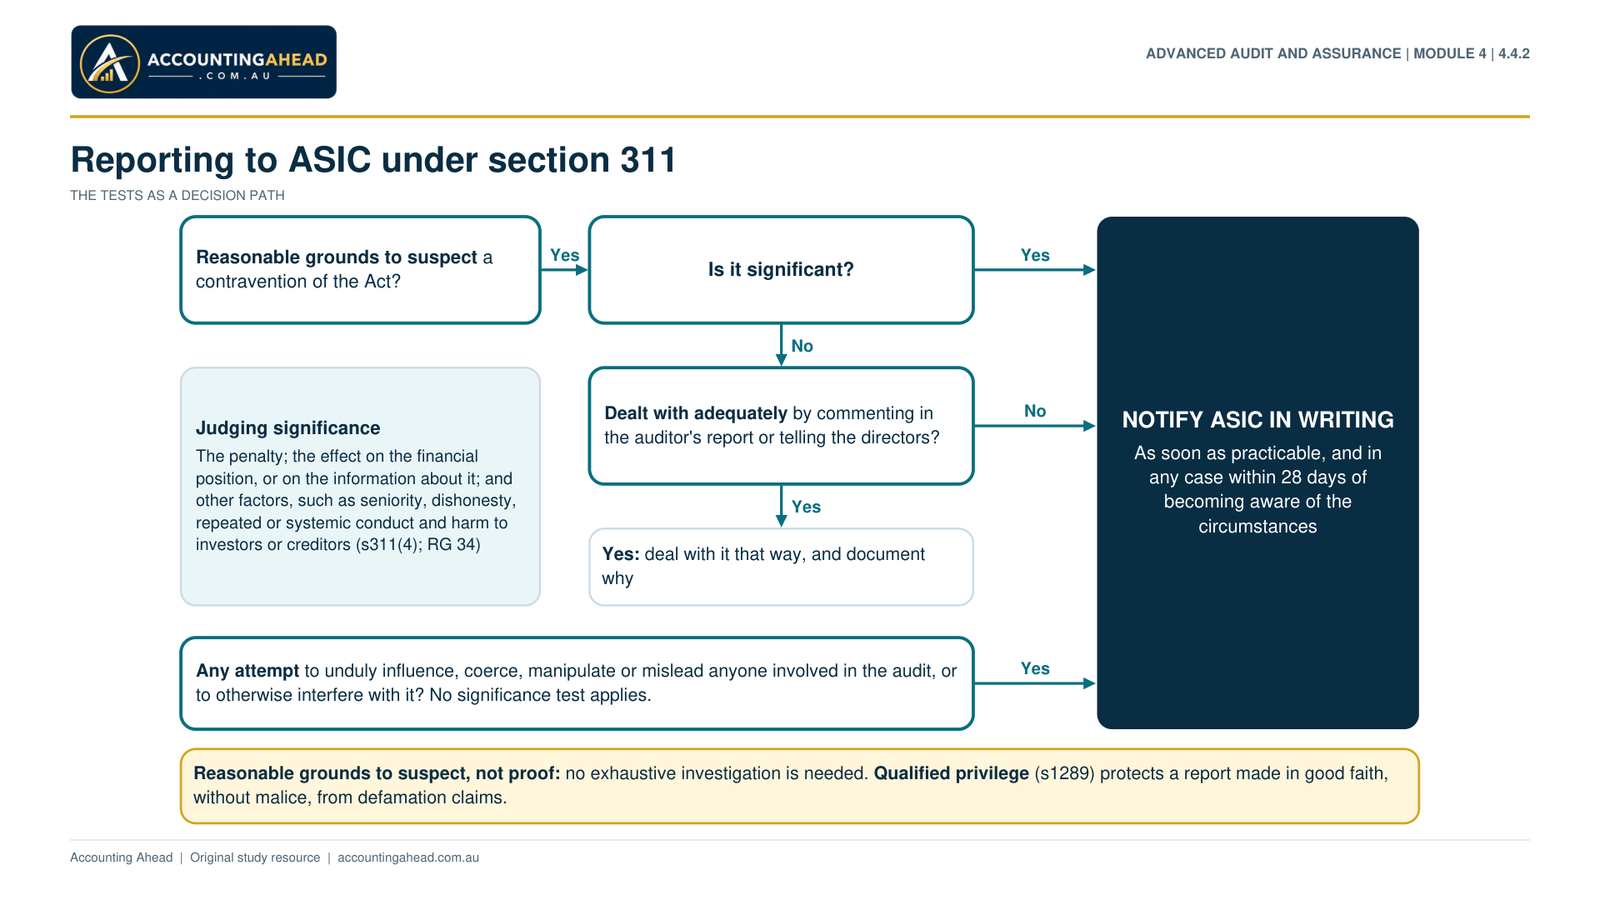
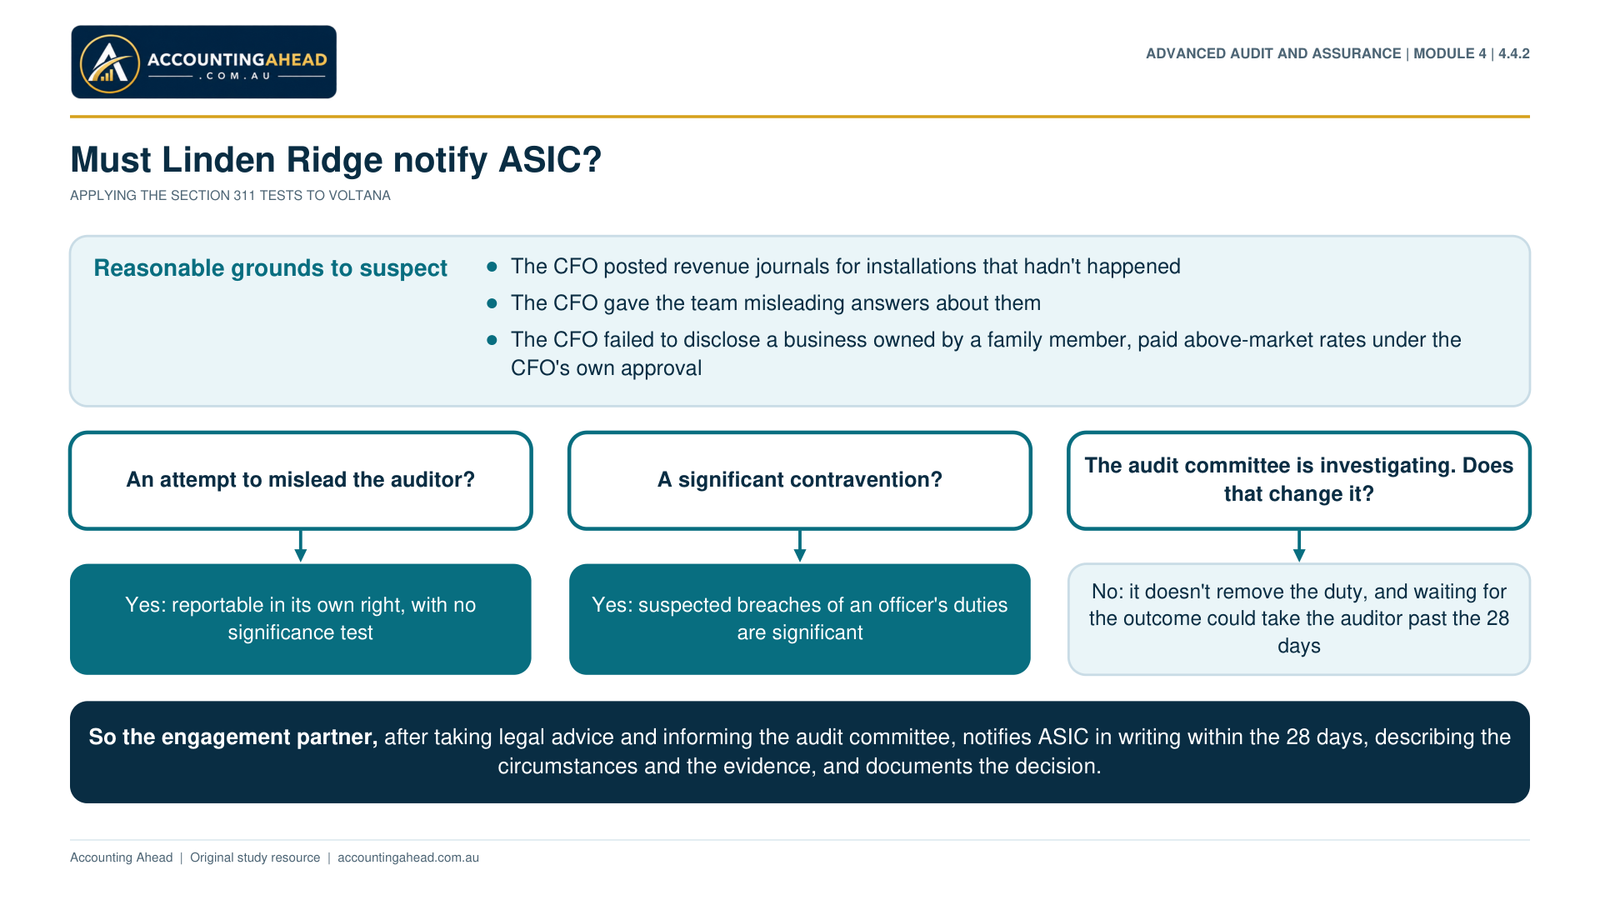
Part 4.4.2 · Reporting to Shareholders and Regulators
Module 5 · Other assurance engagements
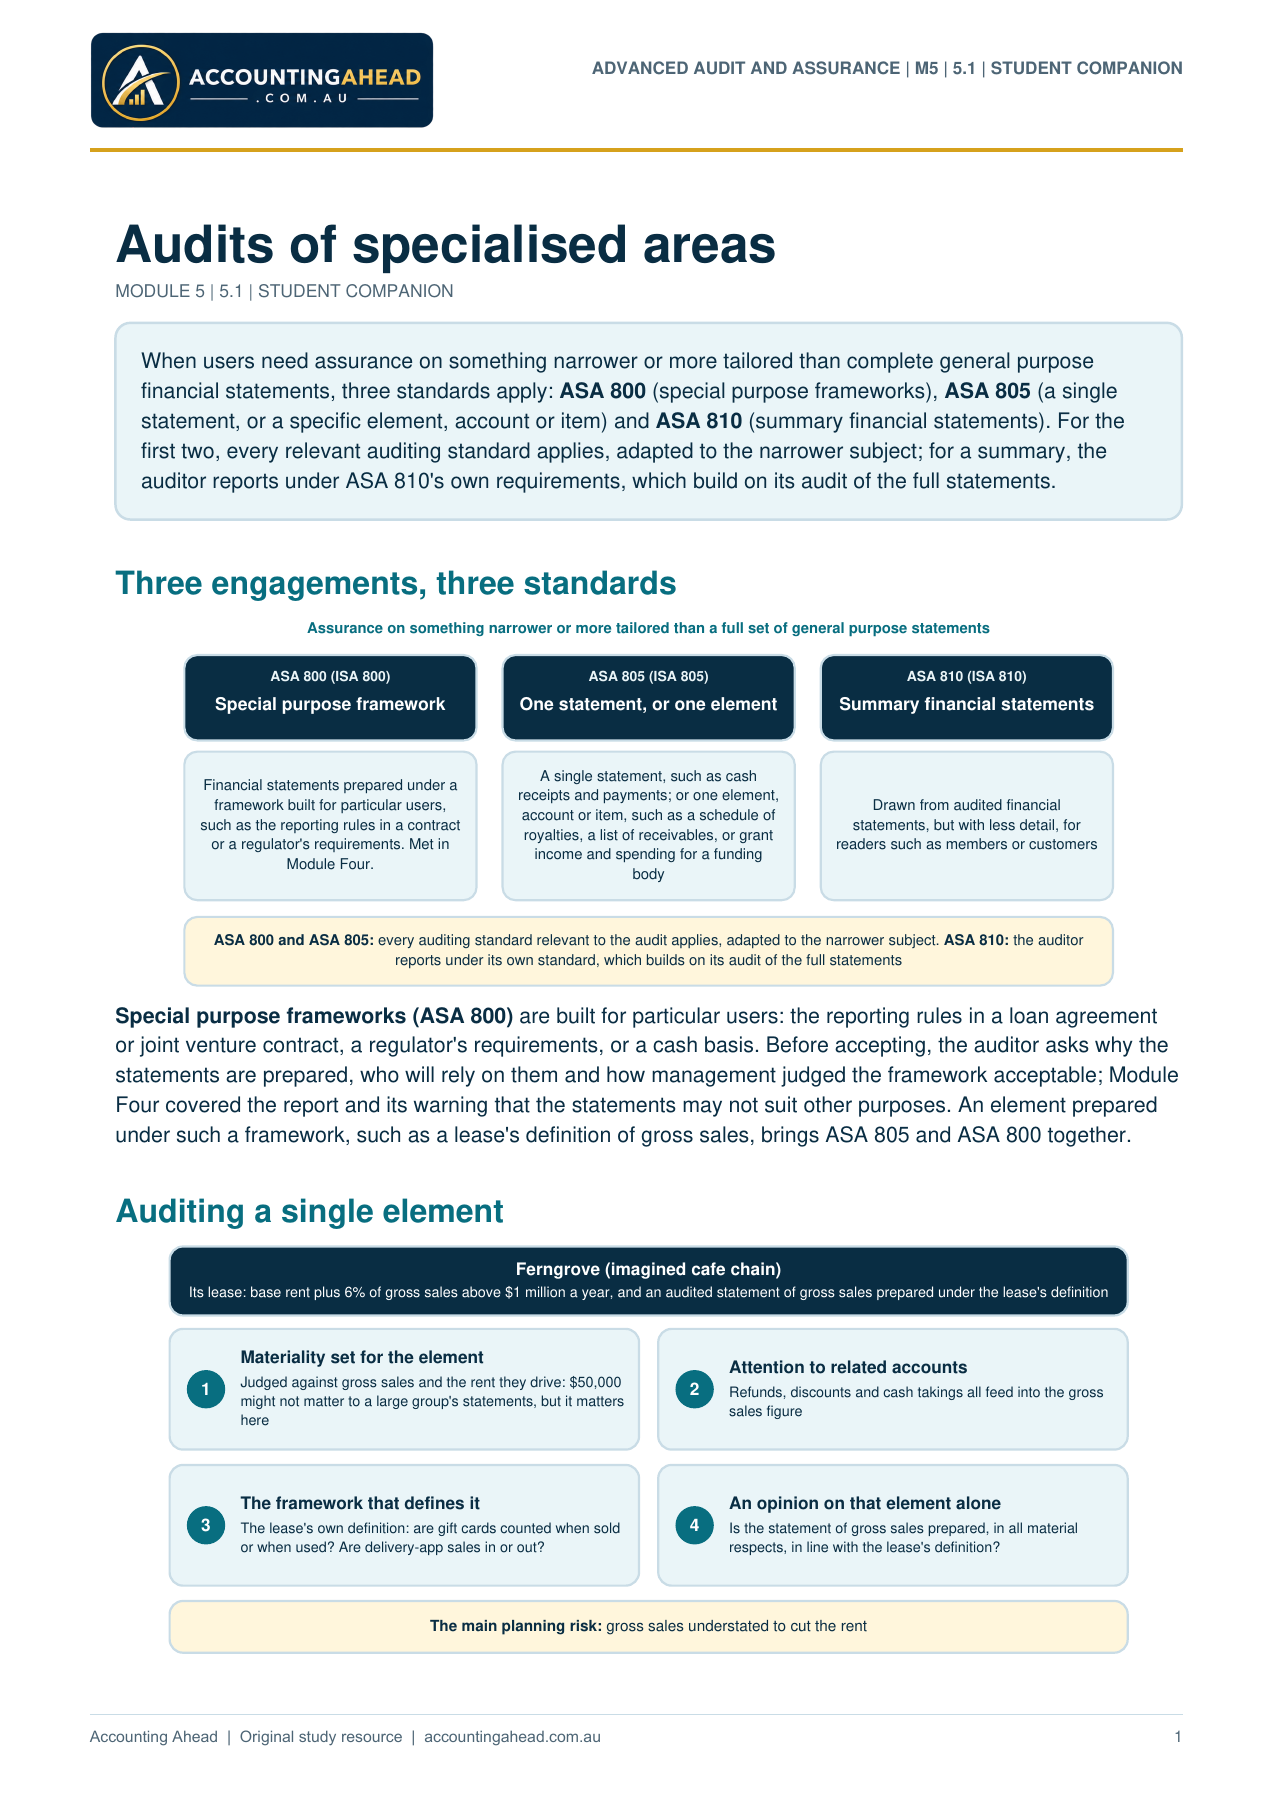
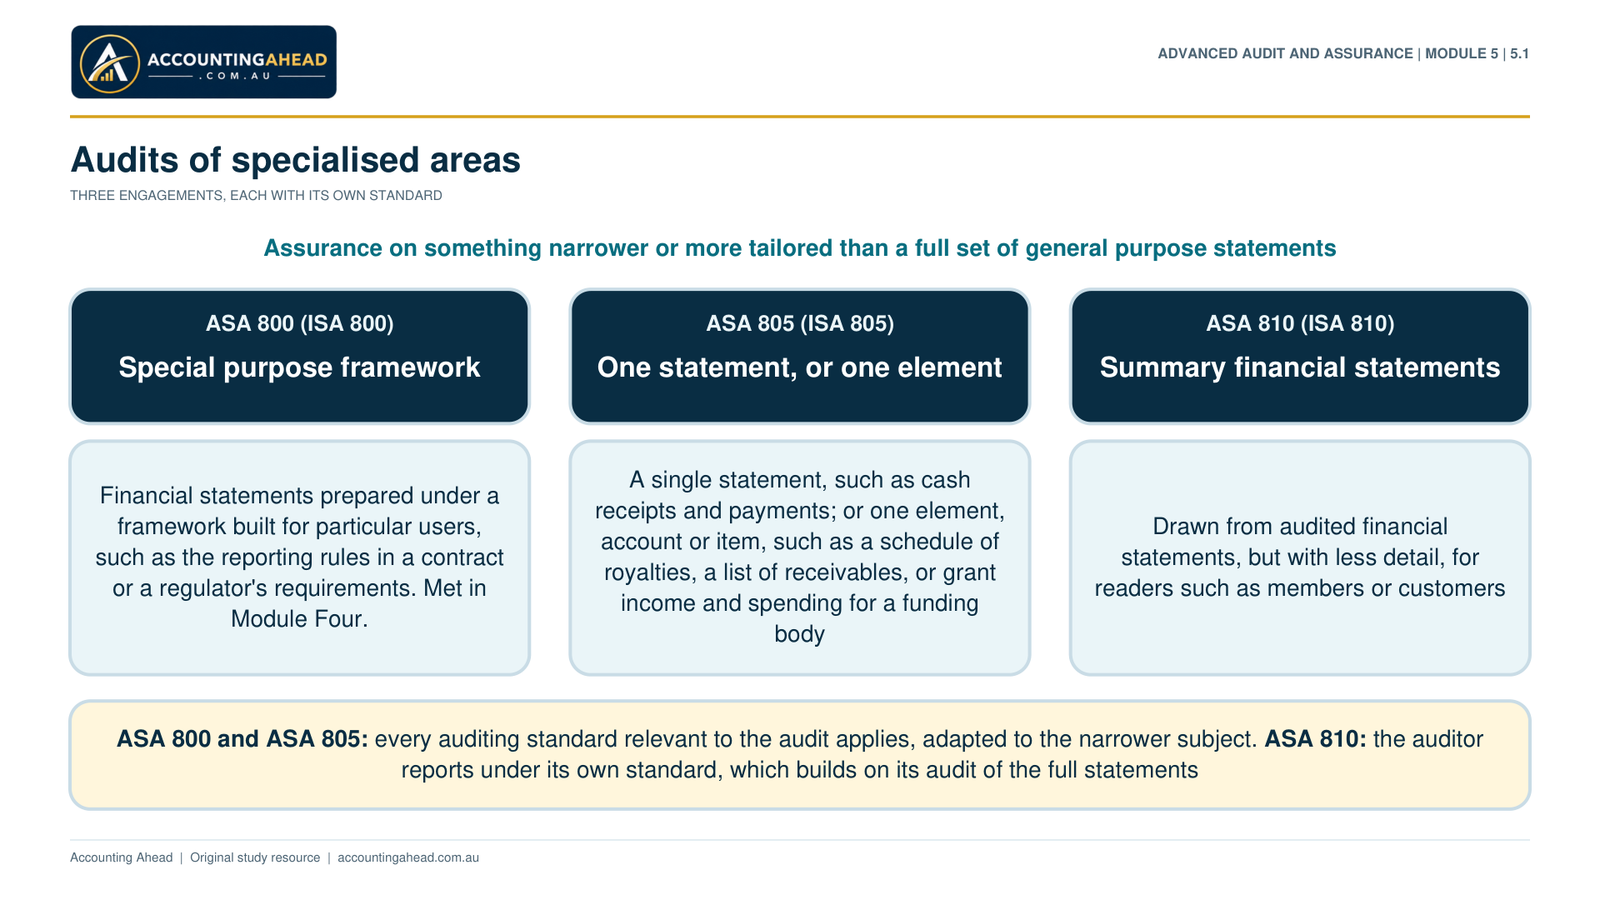
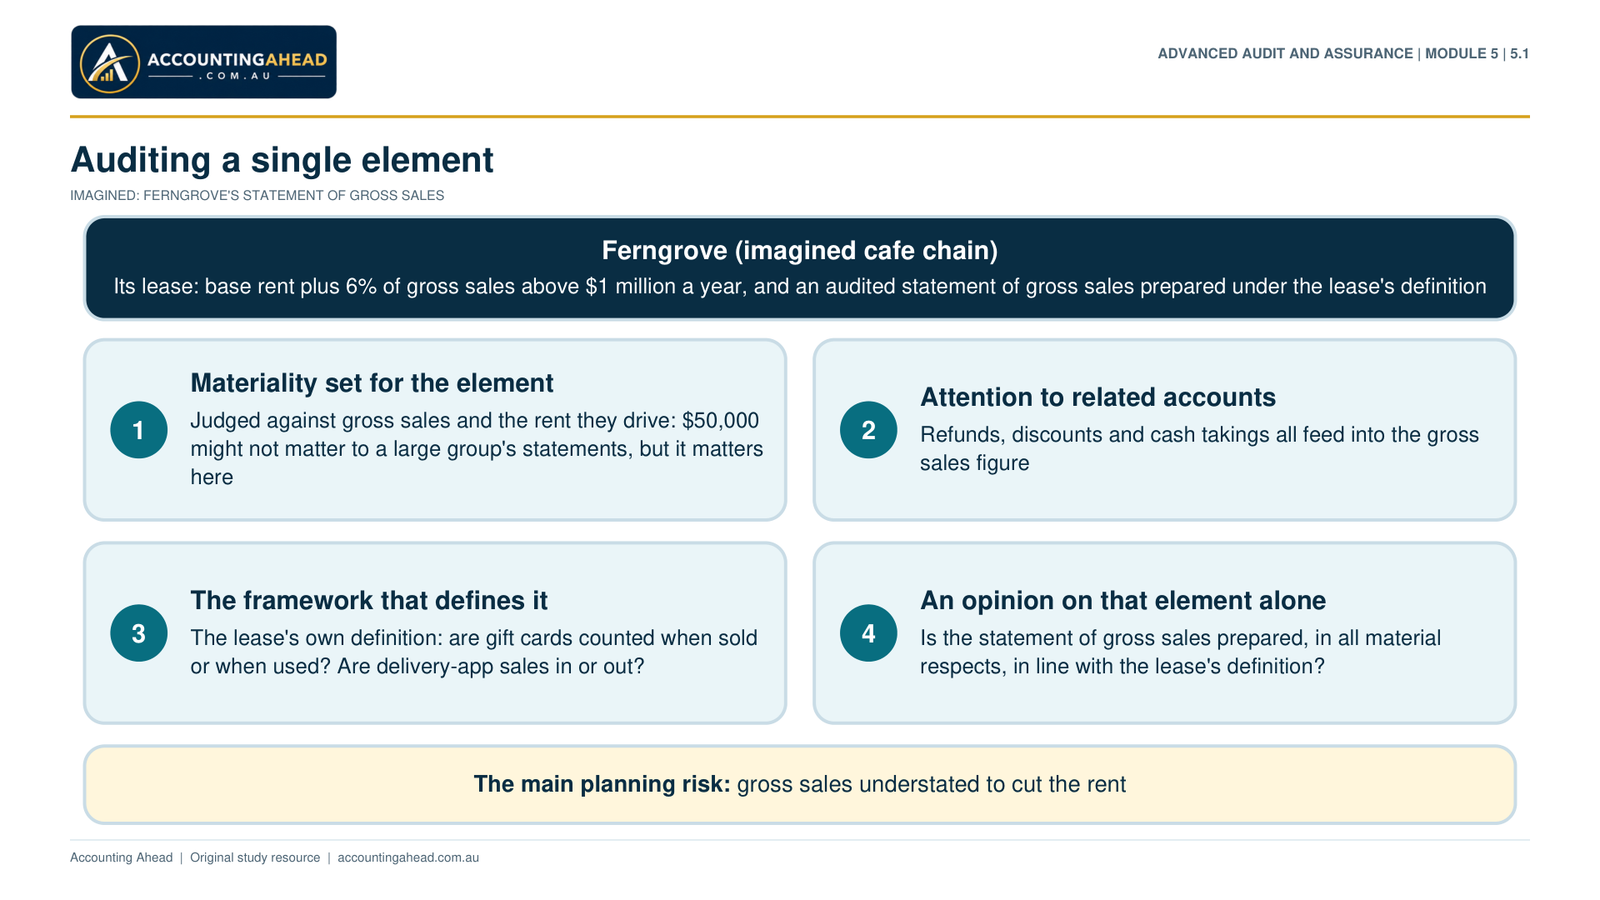
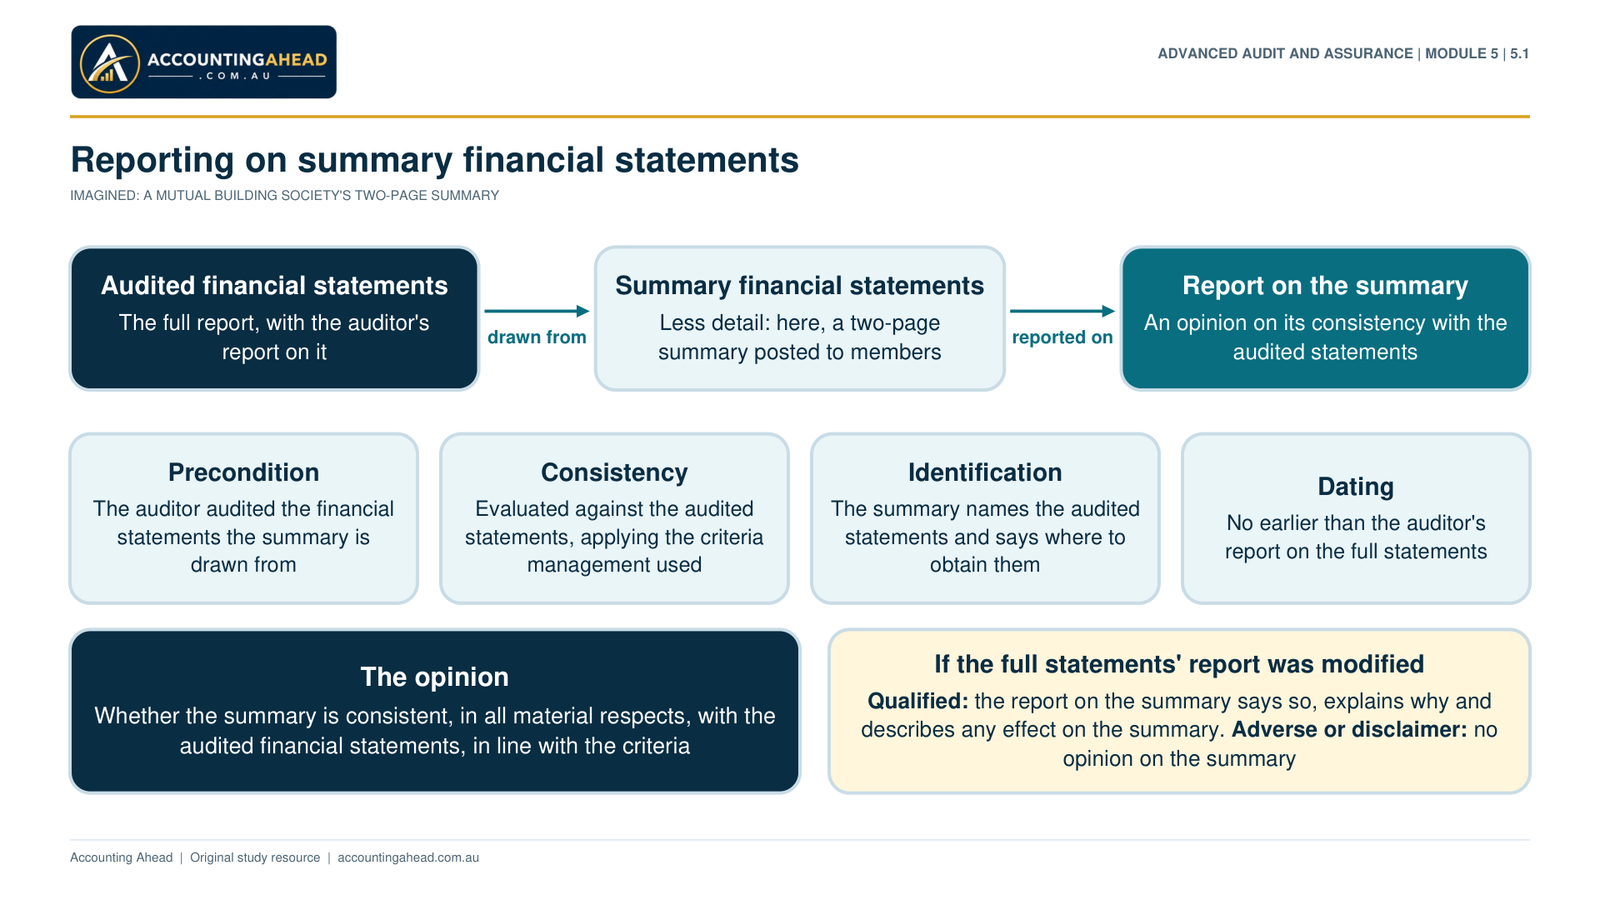
Part 5.1 · Audits of Specialised Areas
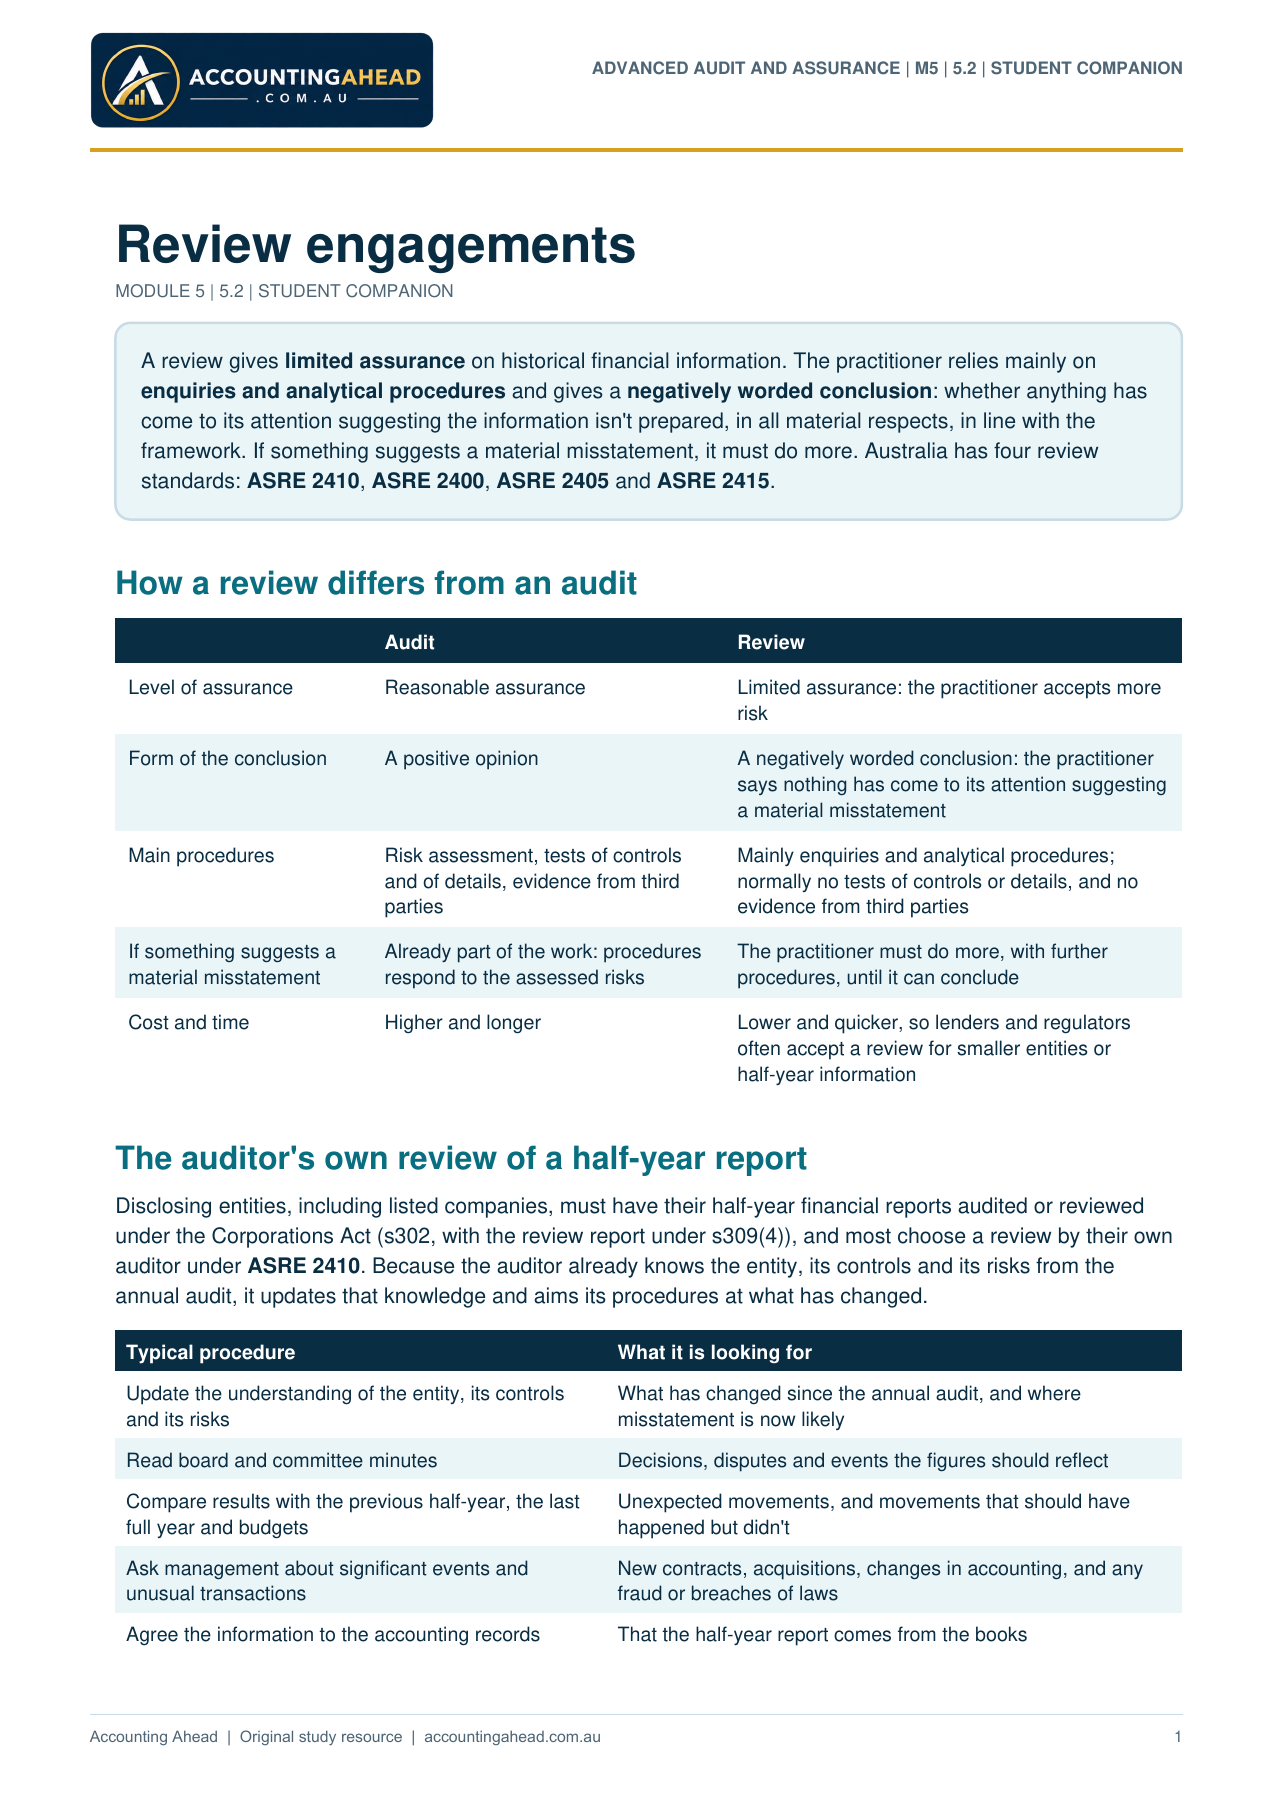
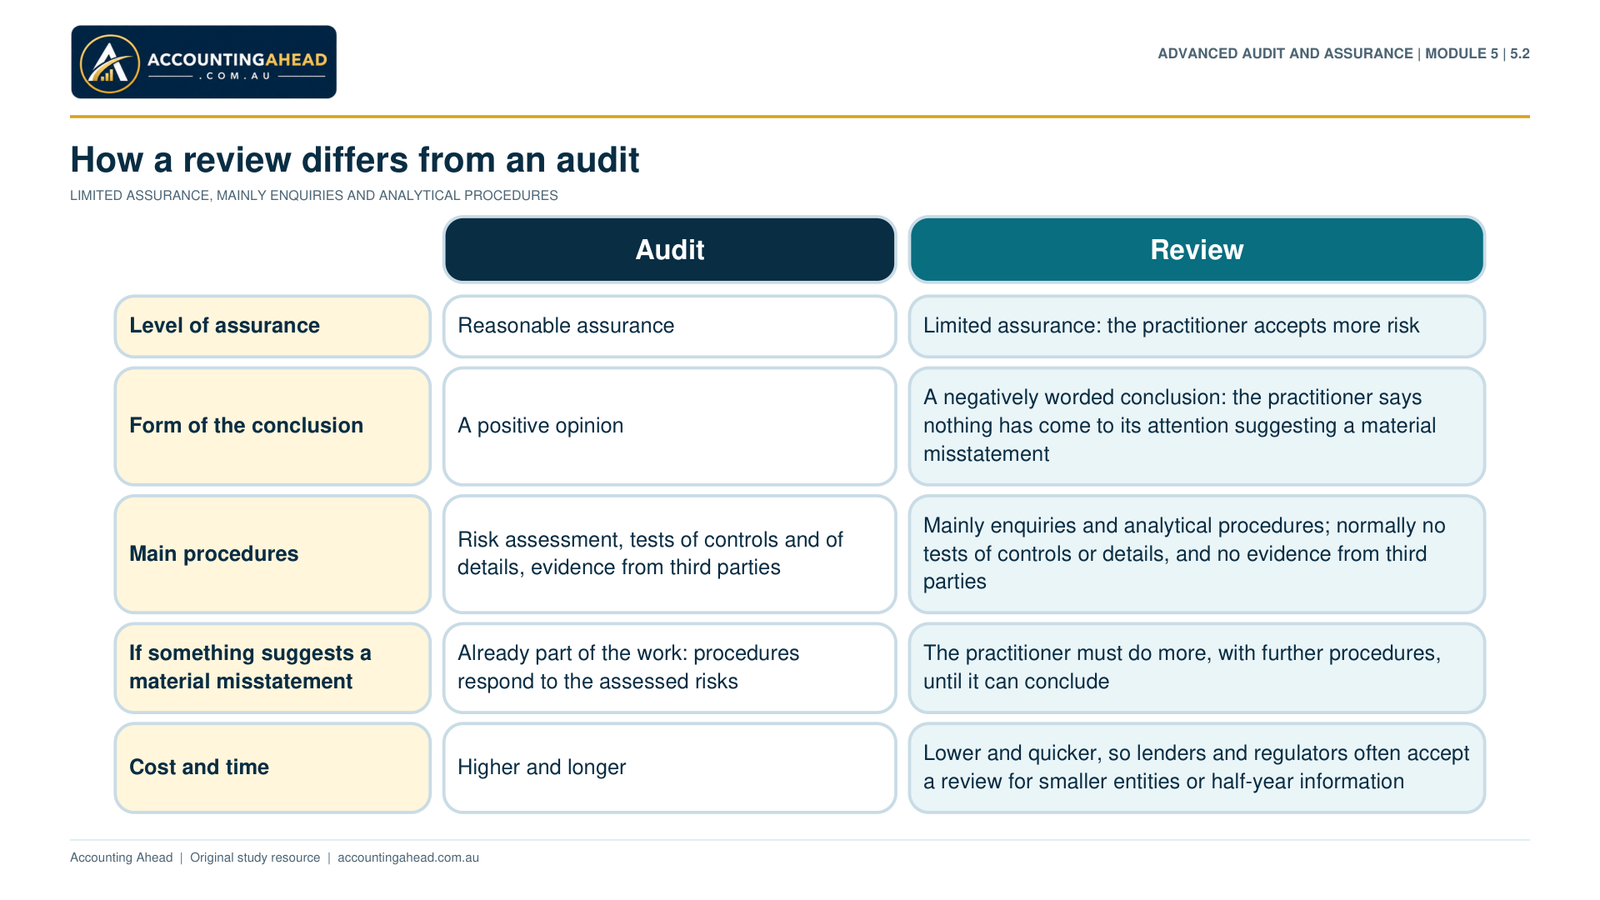
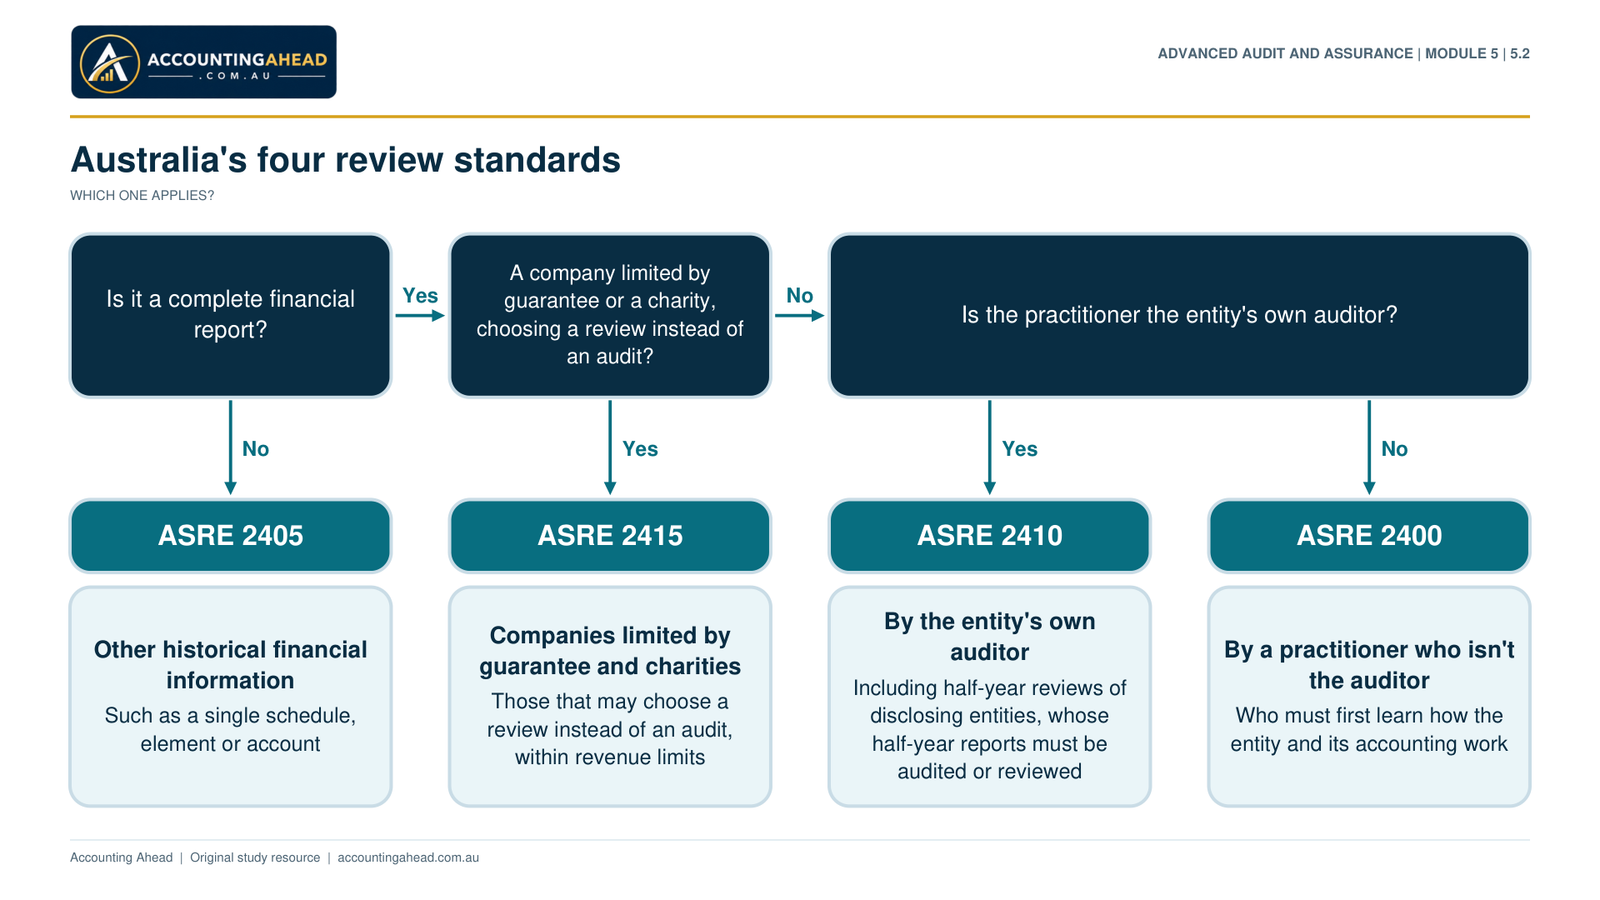
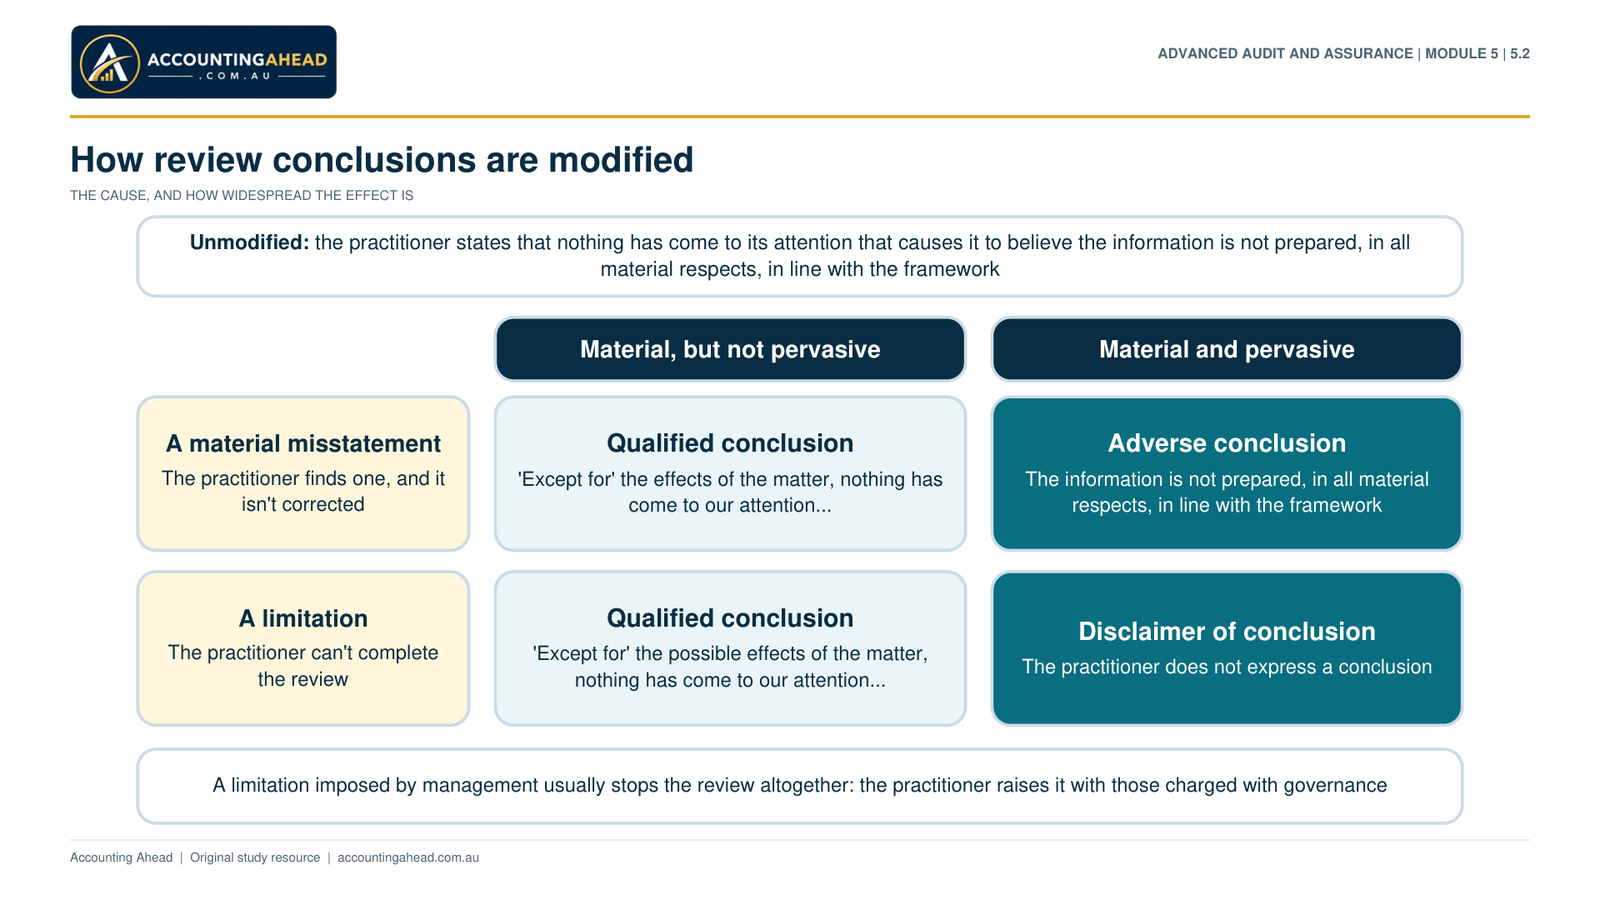
Part 5.2 · Review Engagements
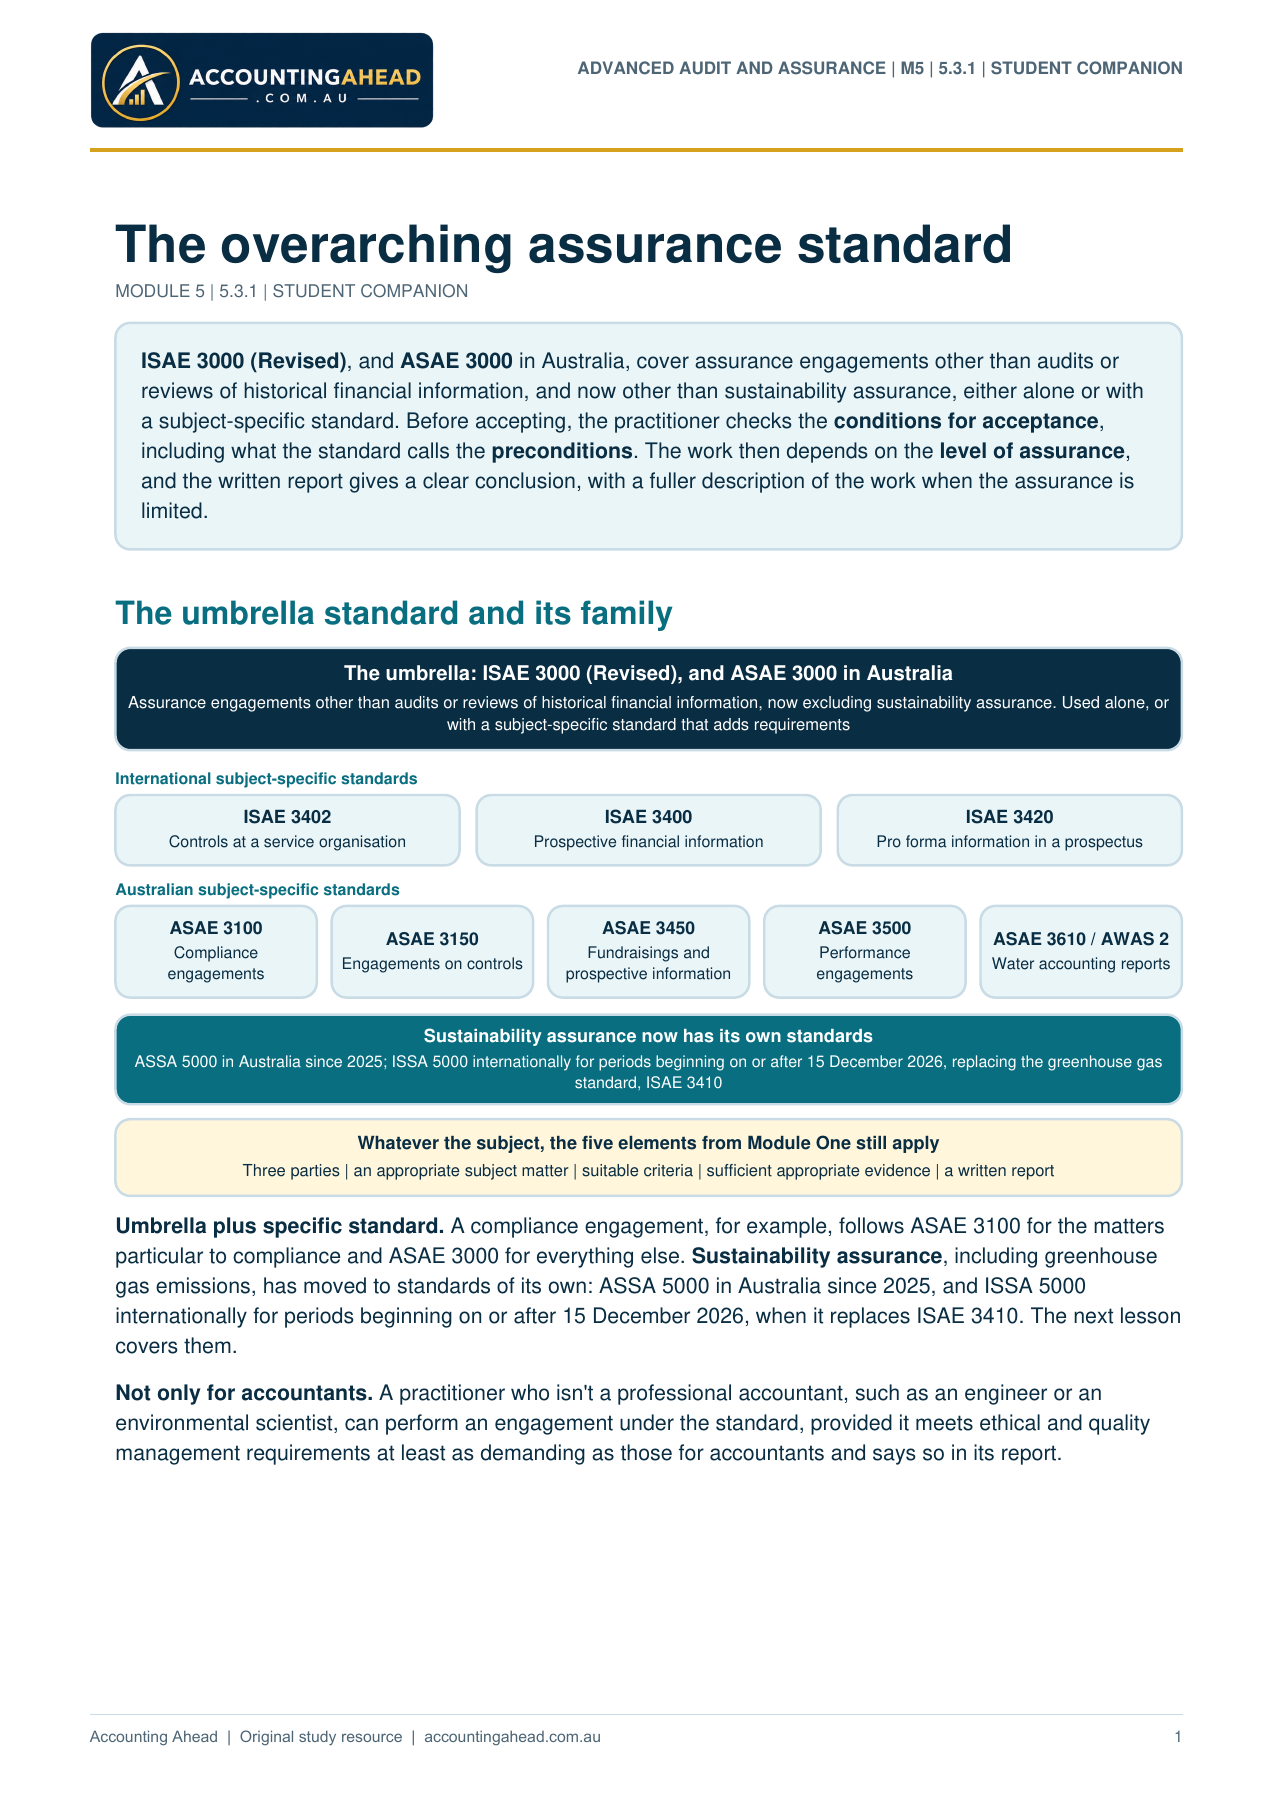
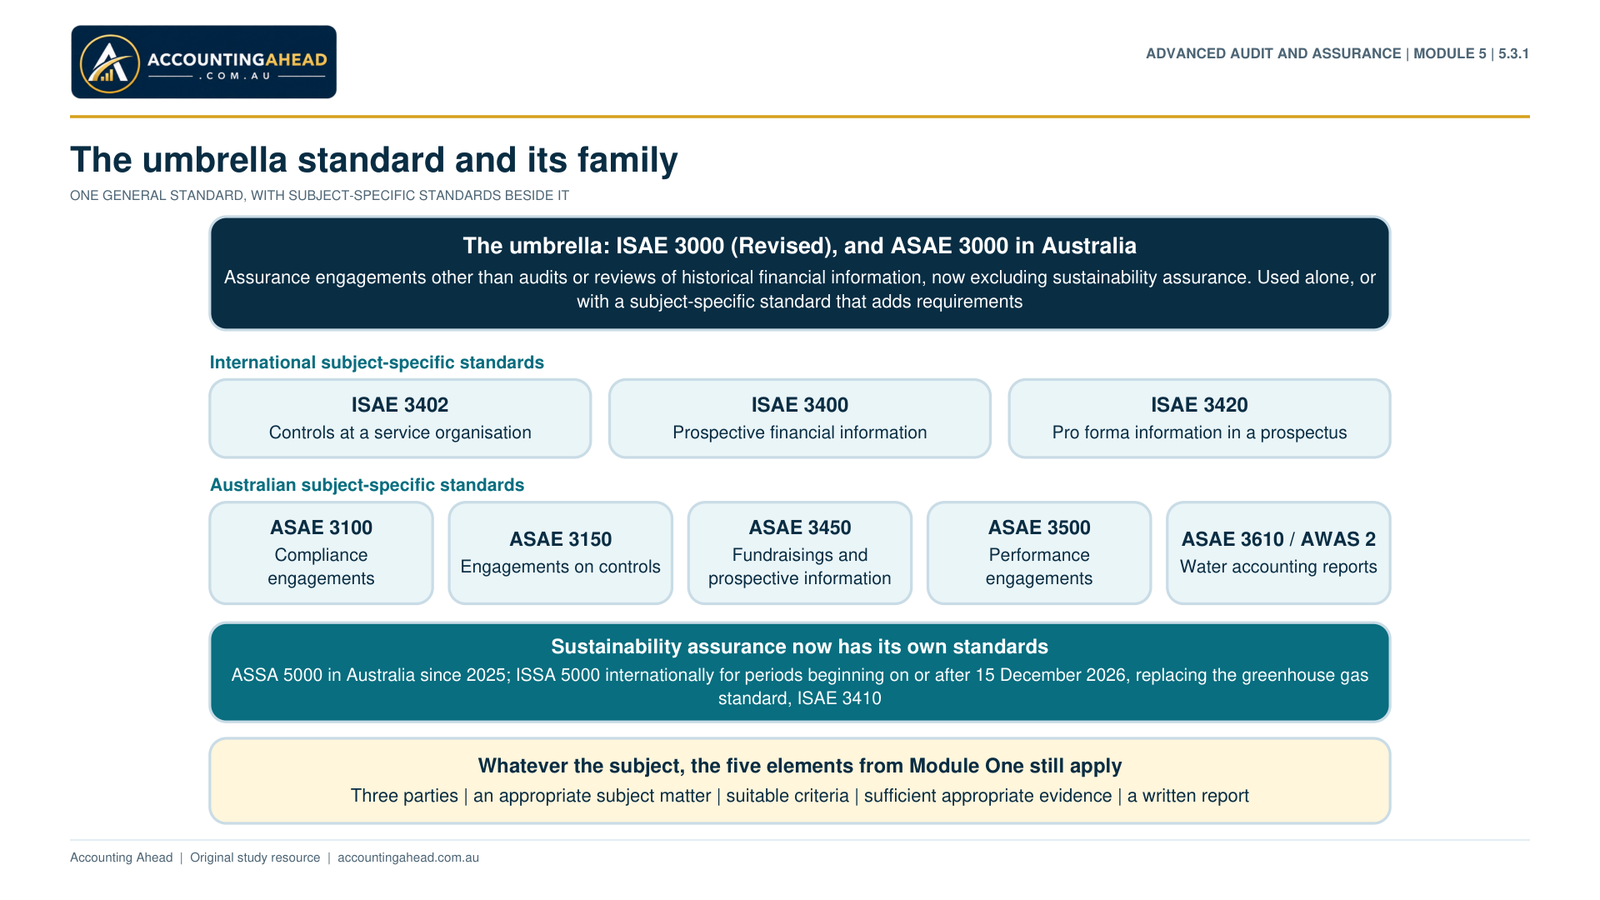
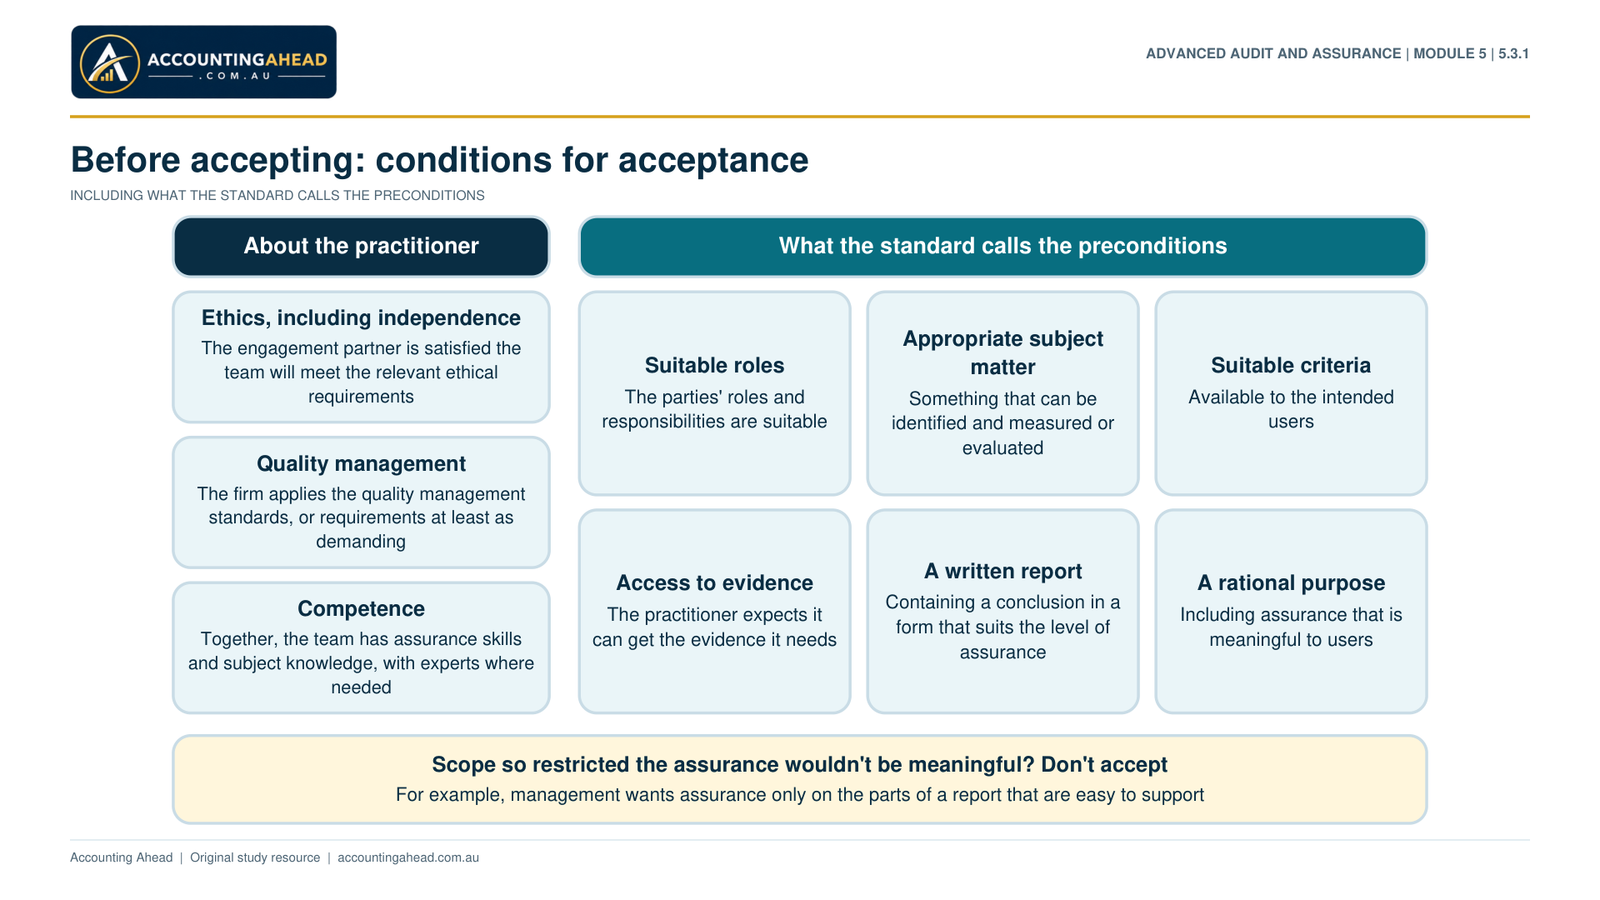
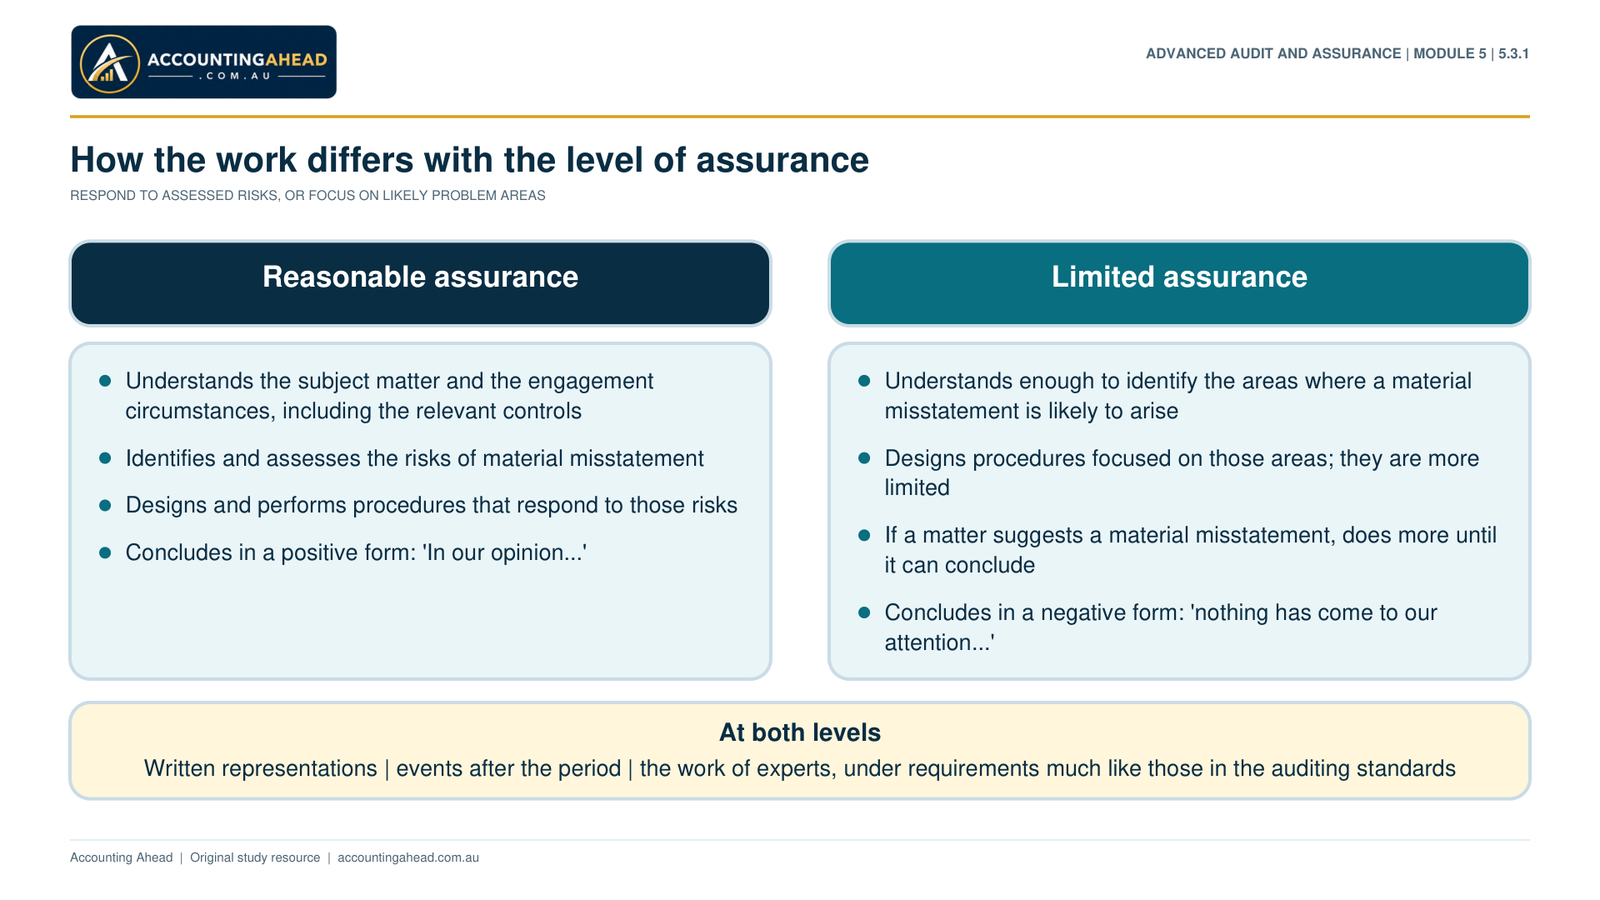
Part 5.3.1 · The Overarching Assurance Standard
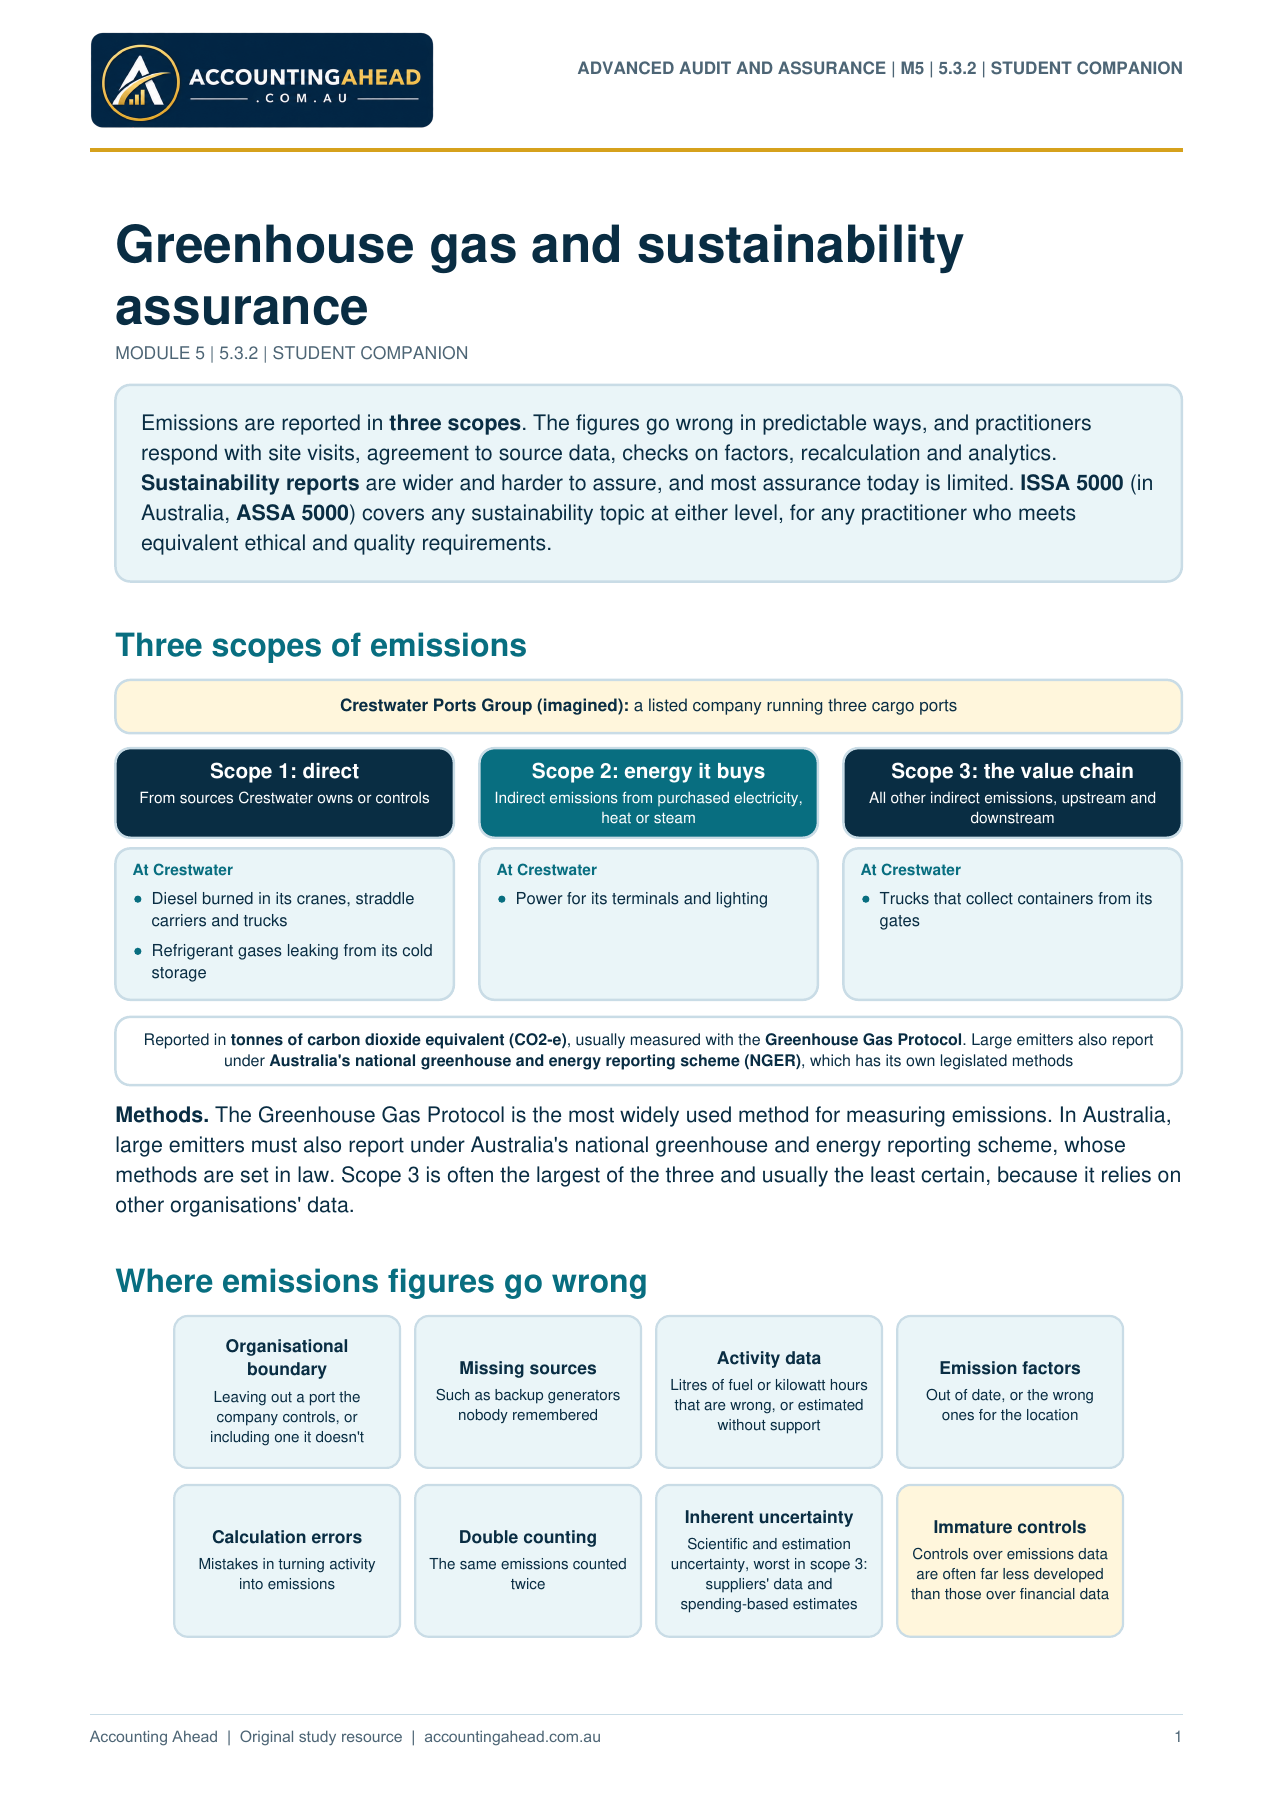
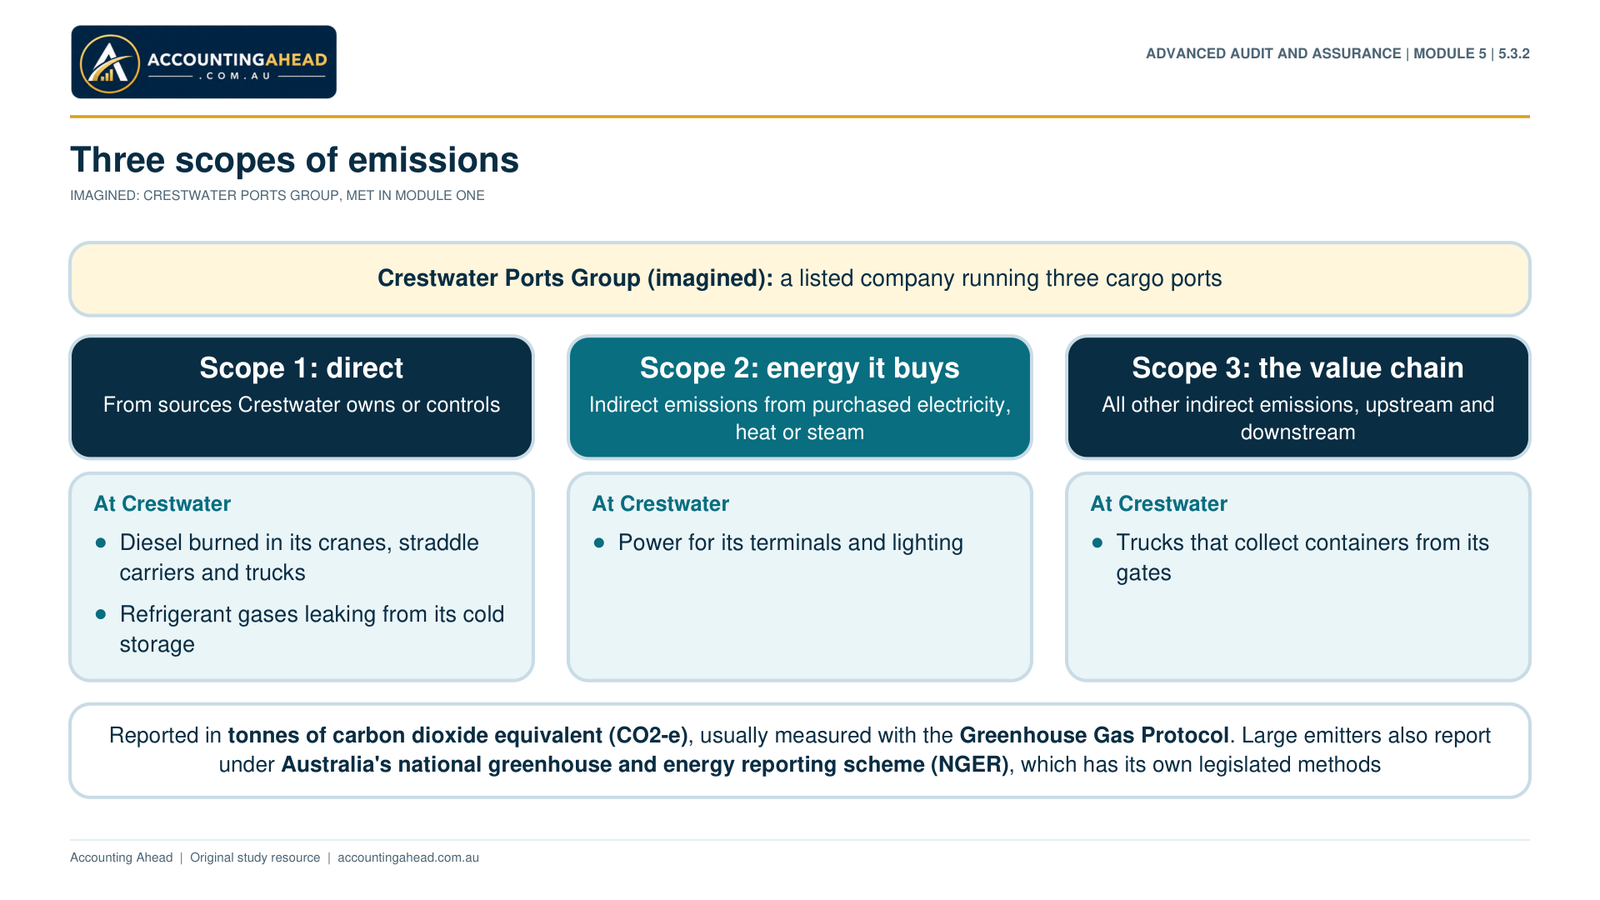
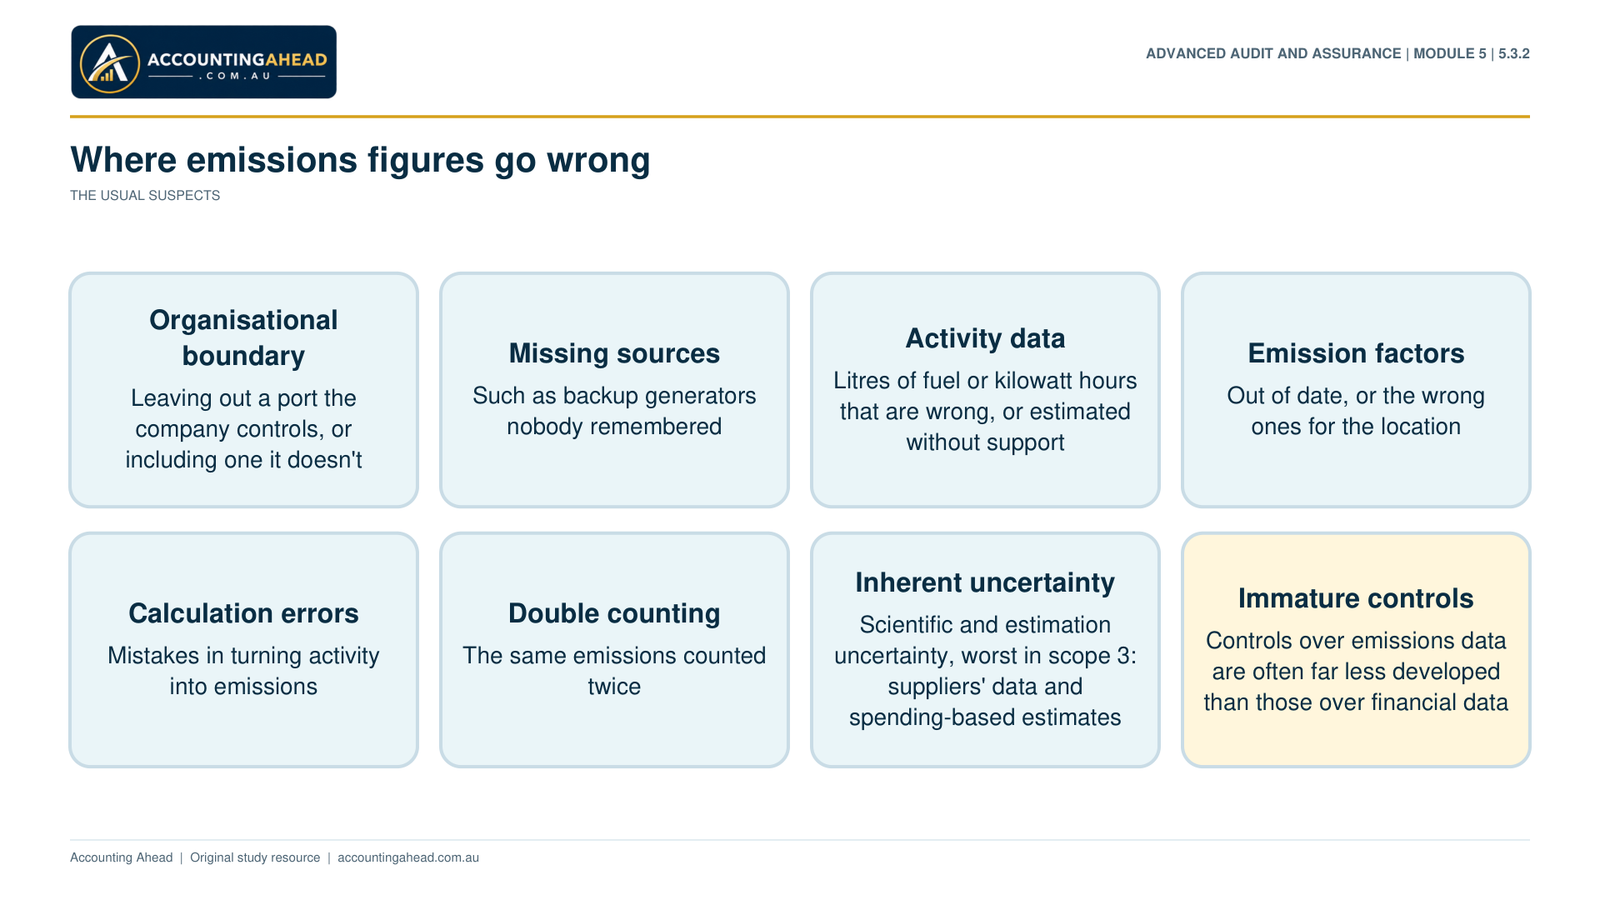
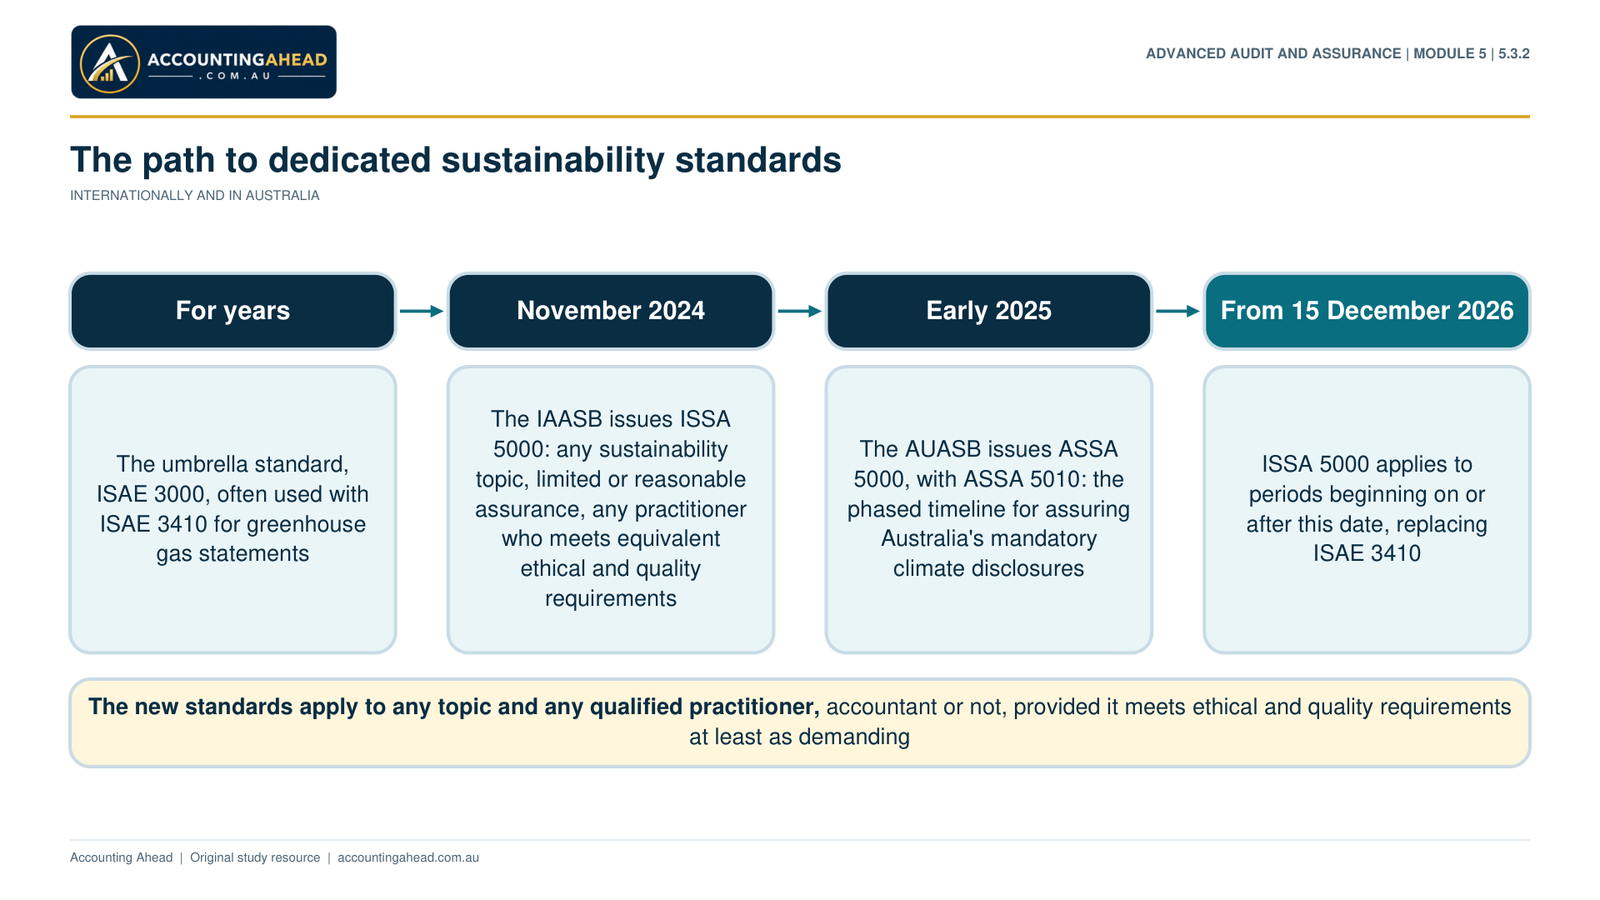
Part 5.3.2 · Greenhouse Gas and Sustainability Assurance
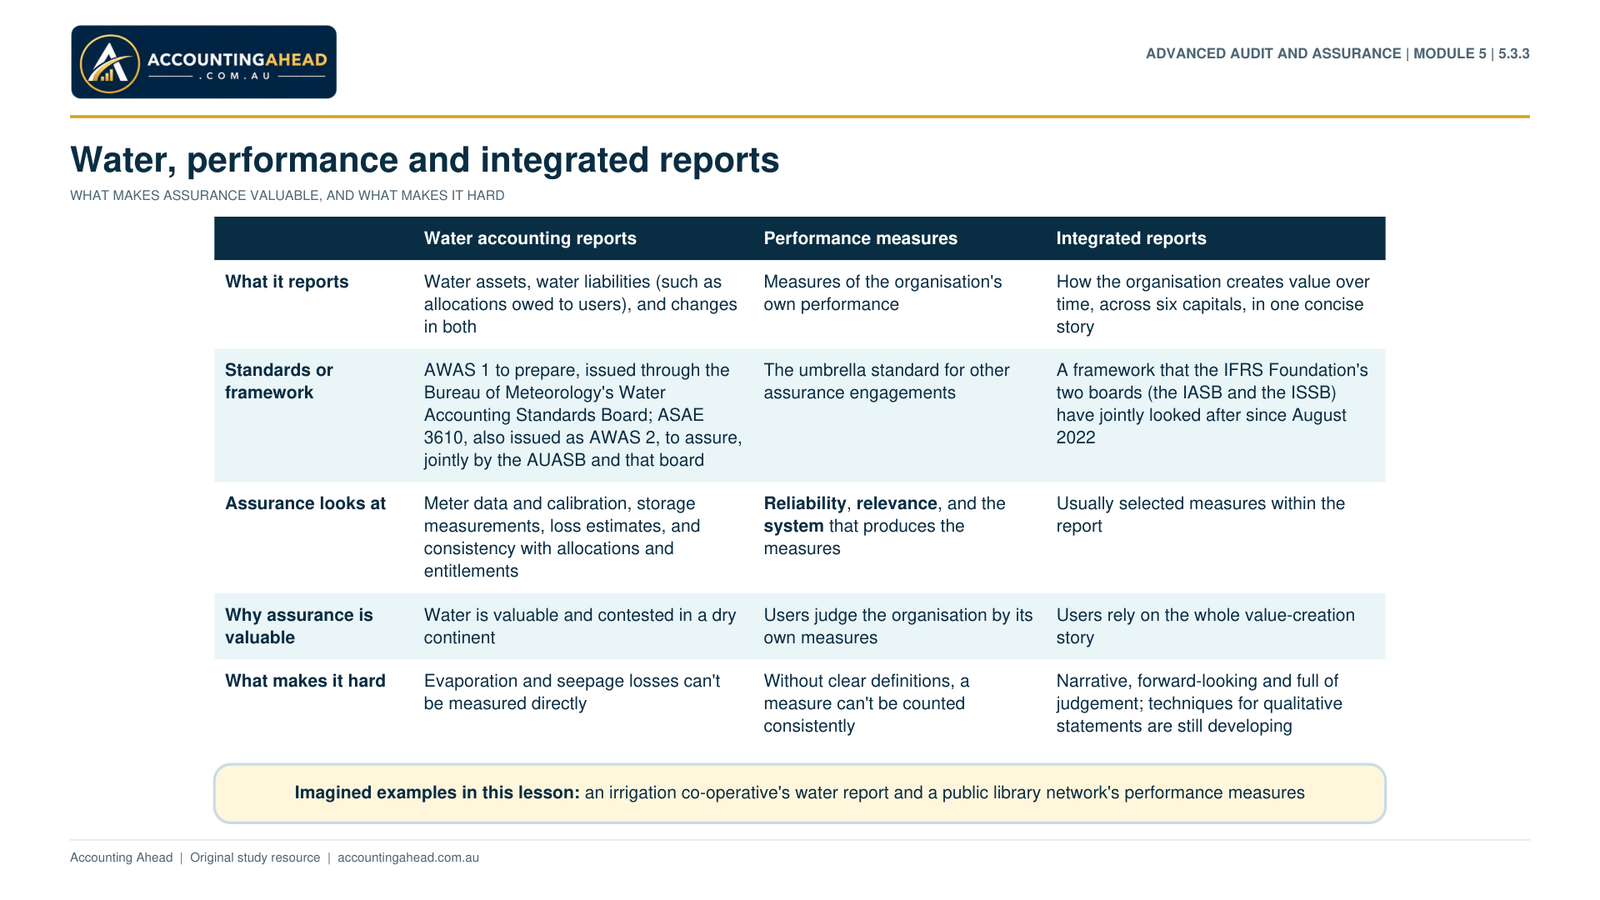
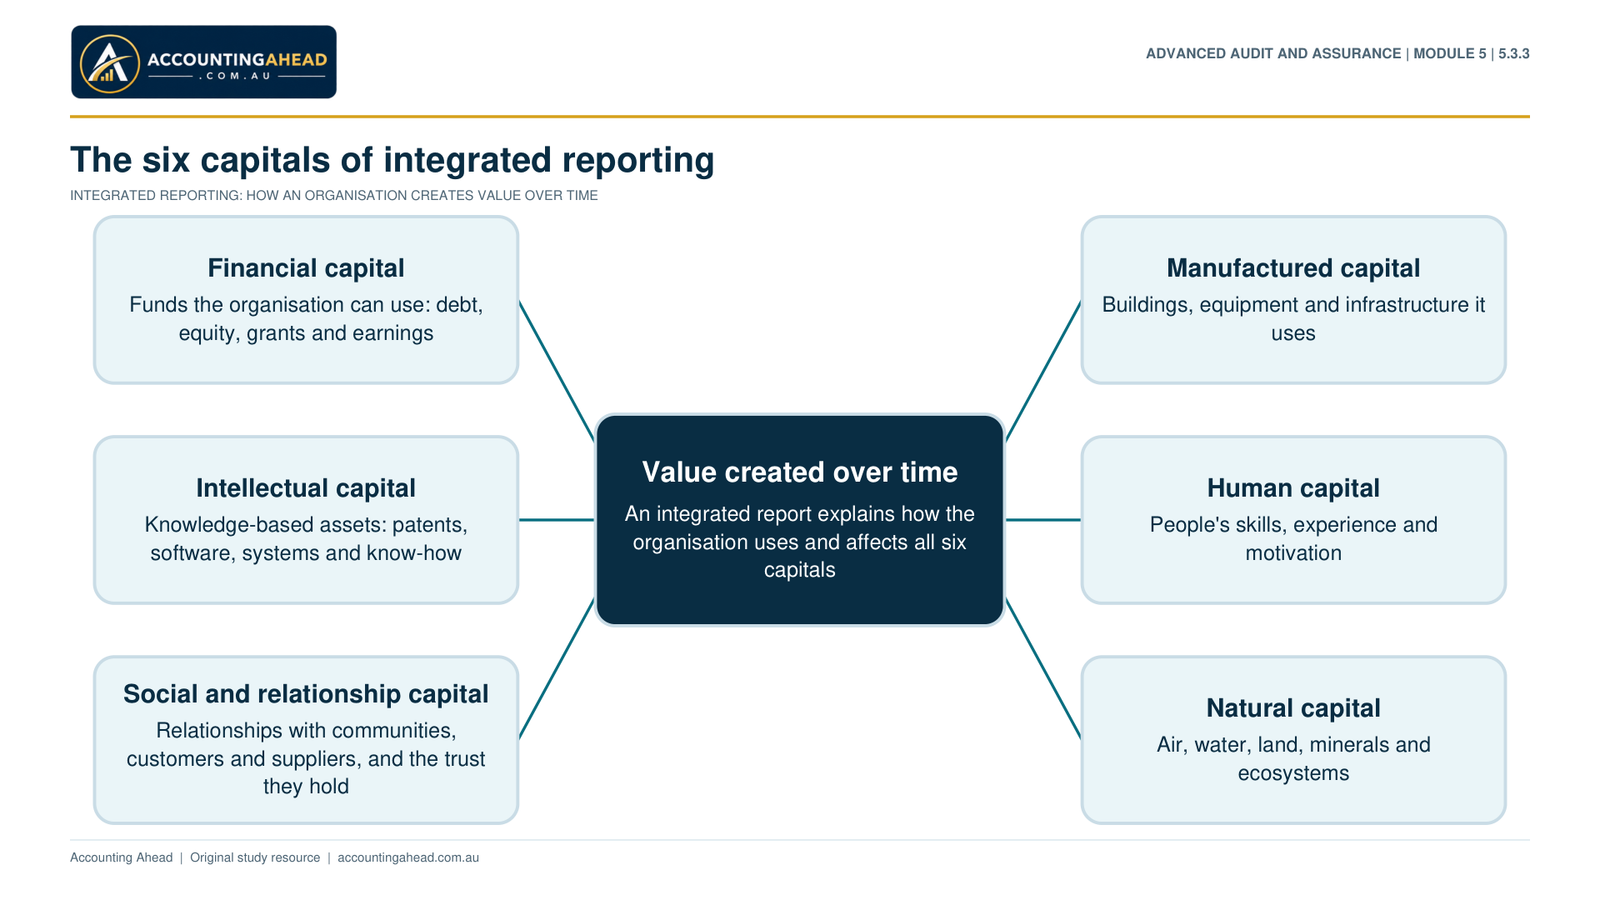
Part 5.3.3 · Water, Performance and Integrated Reports
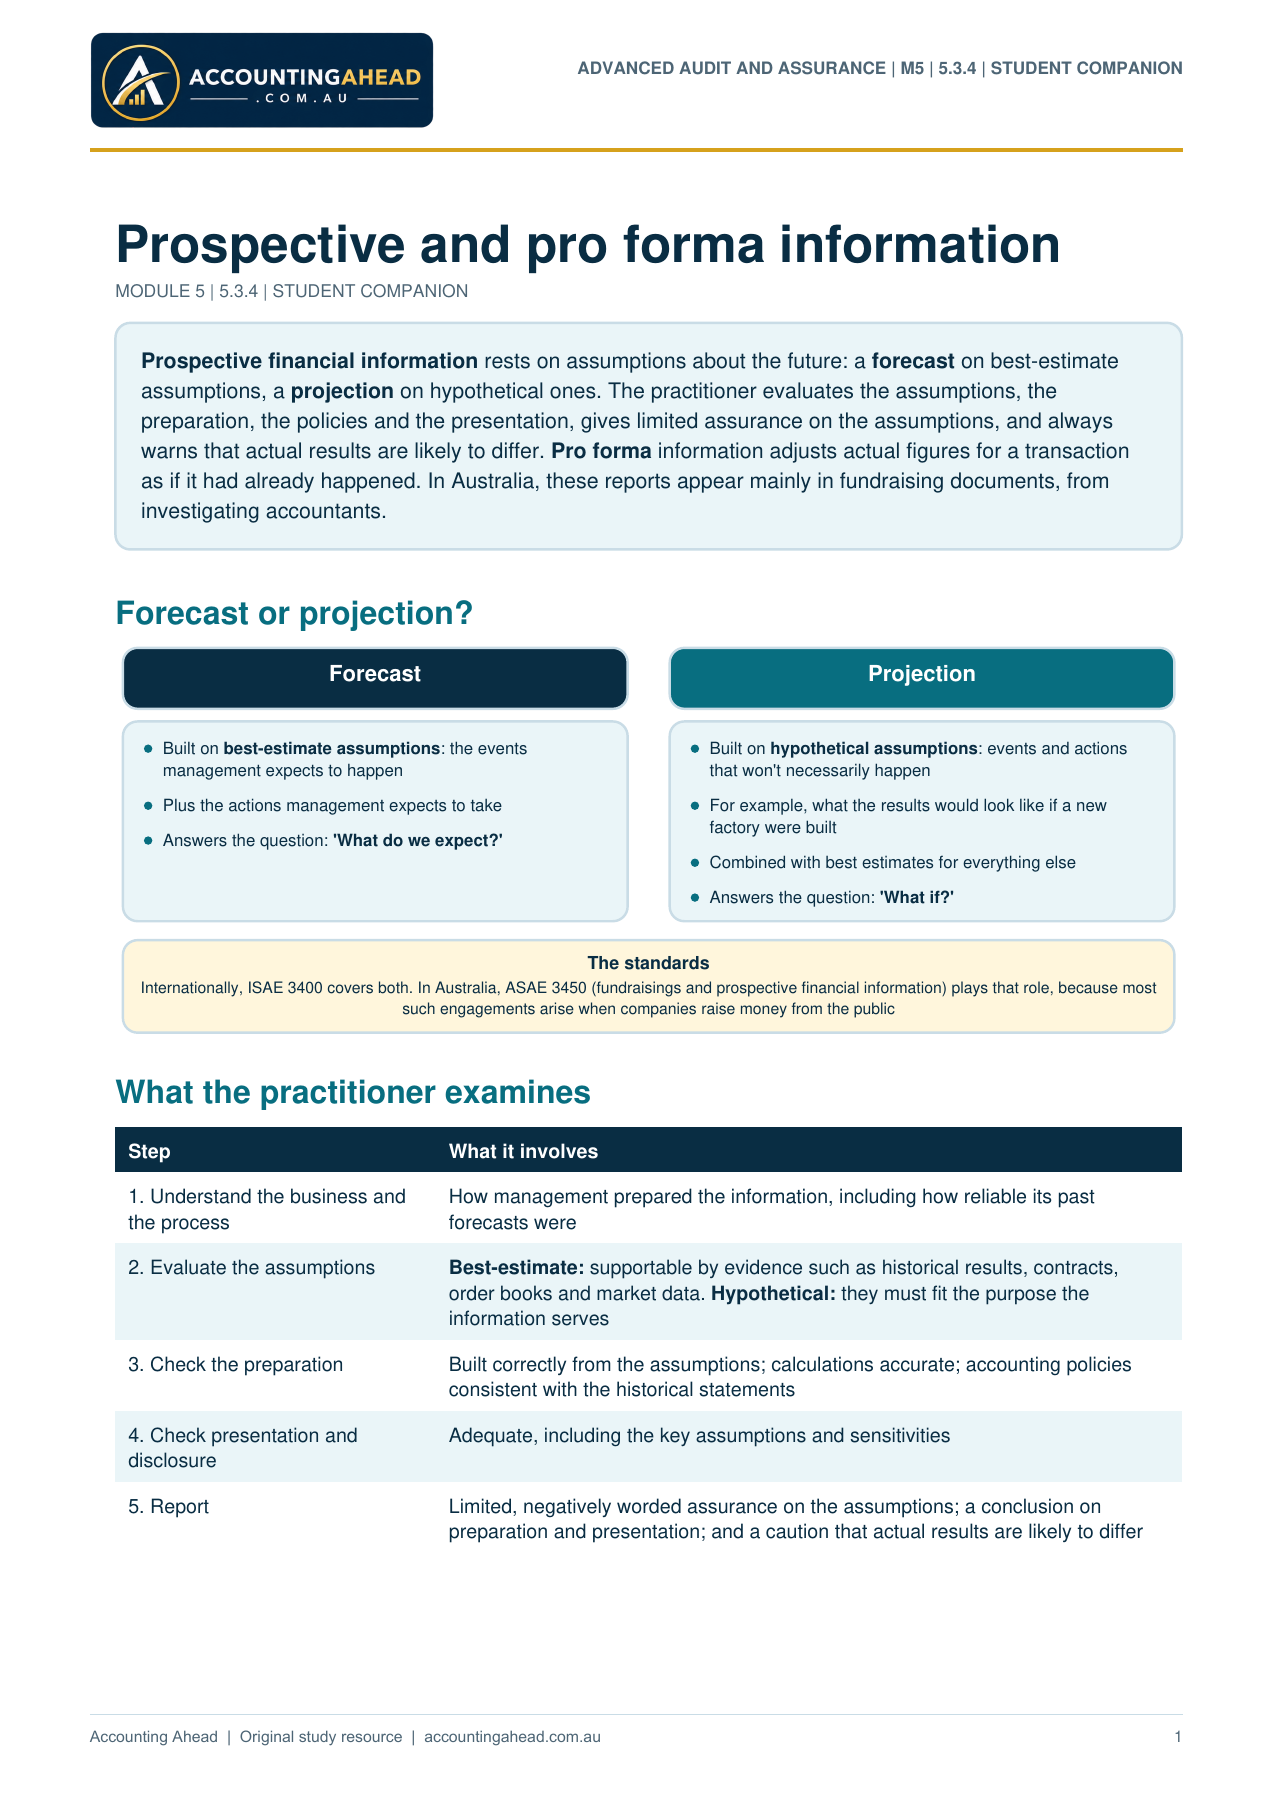
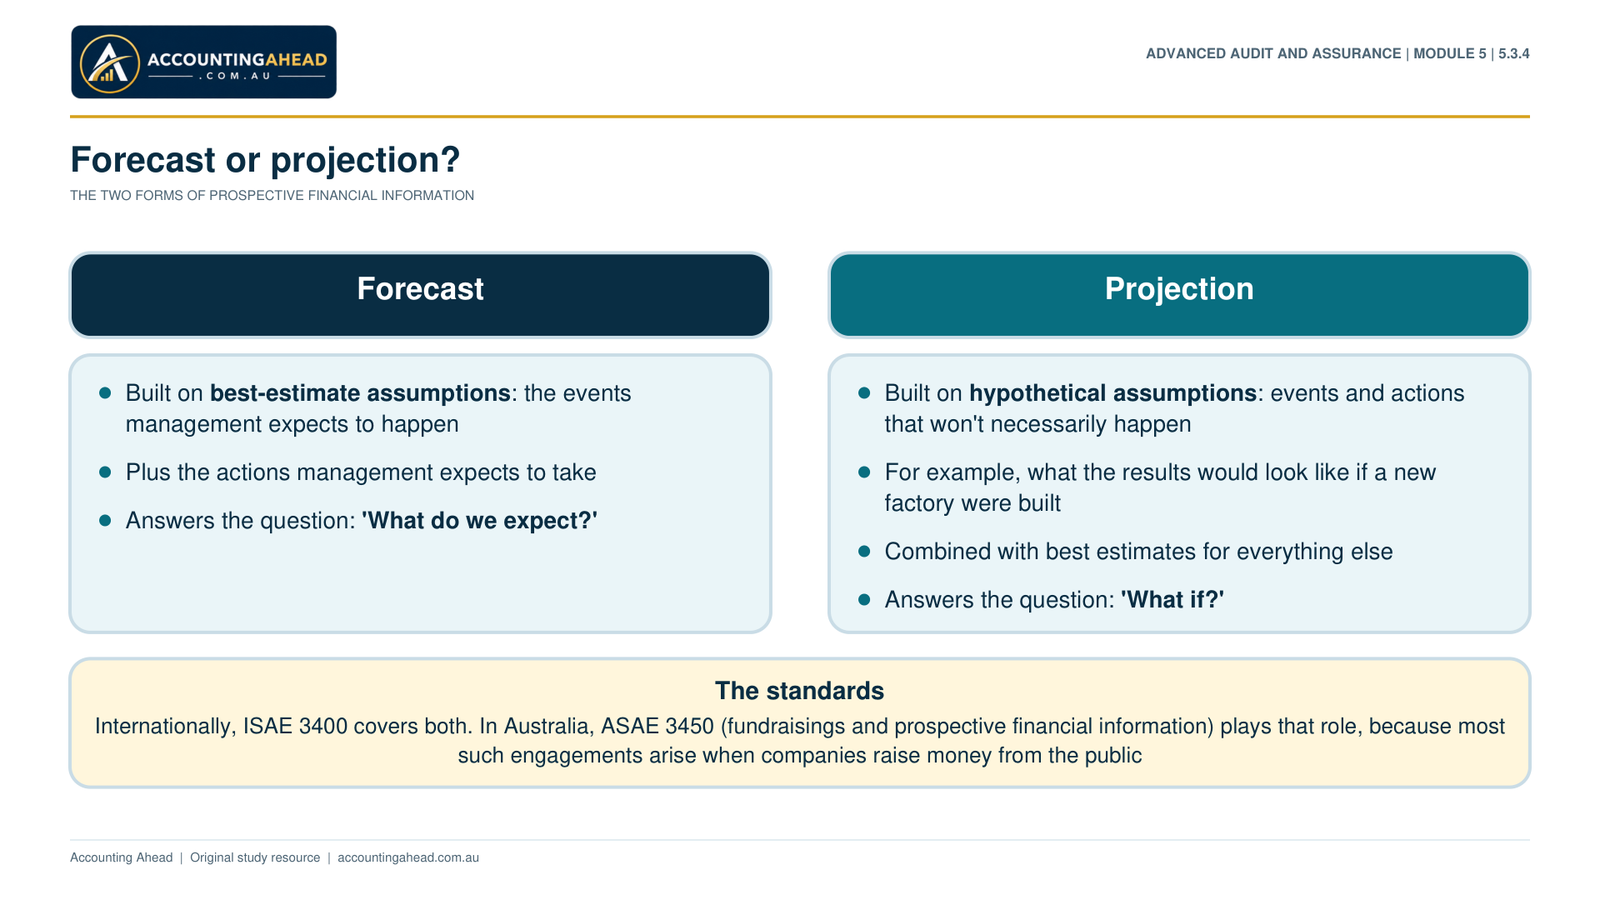
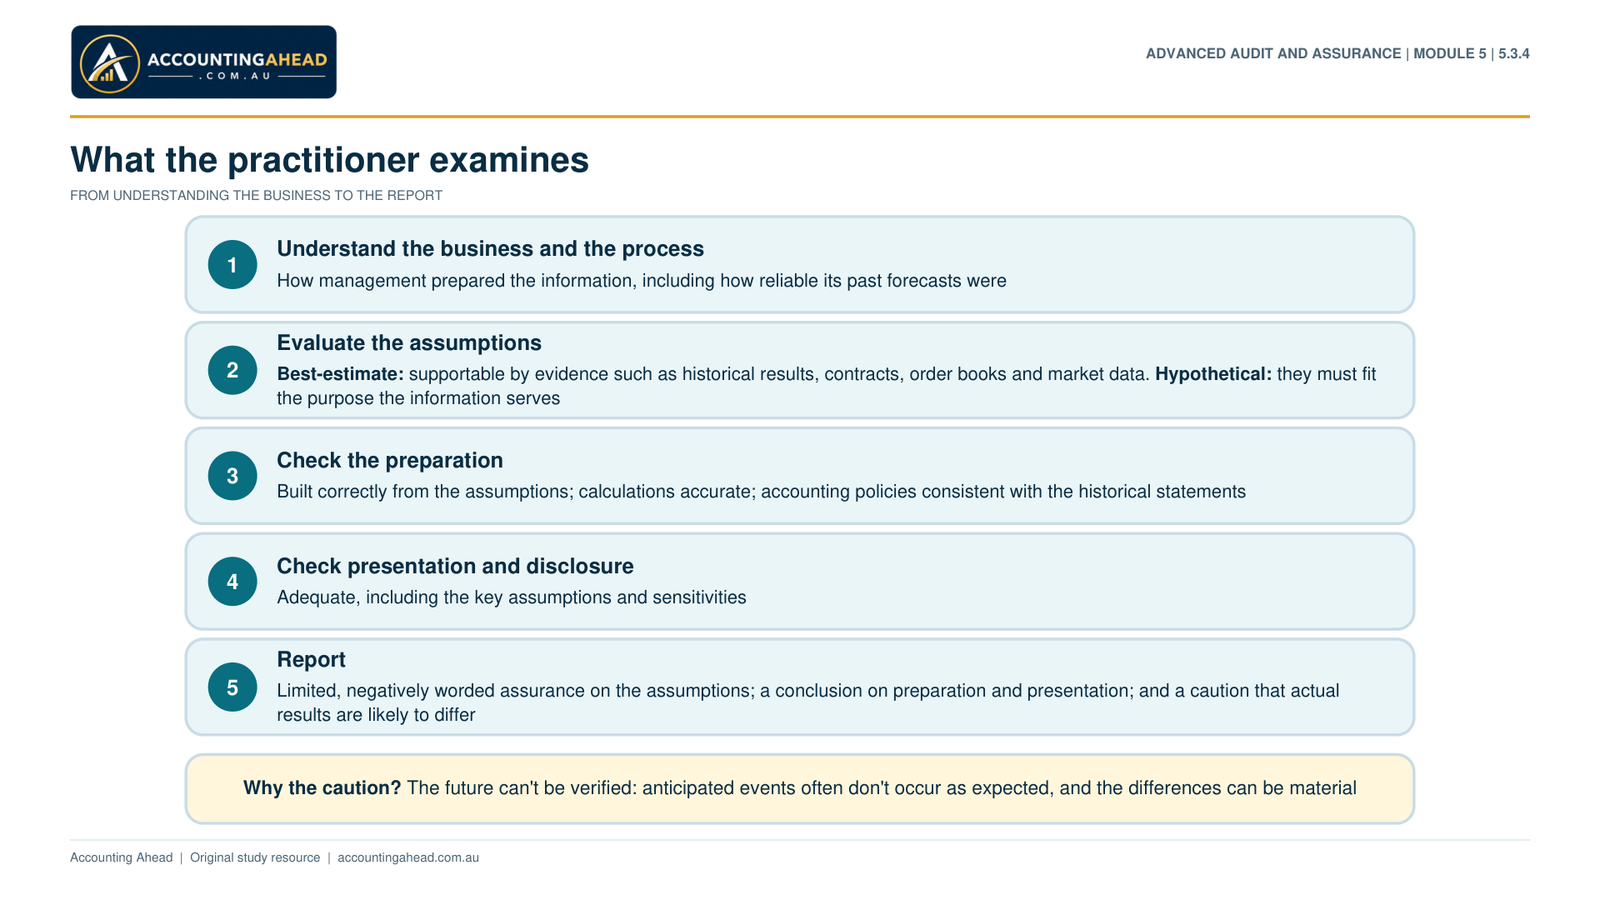
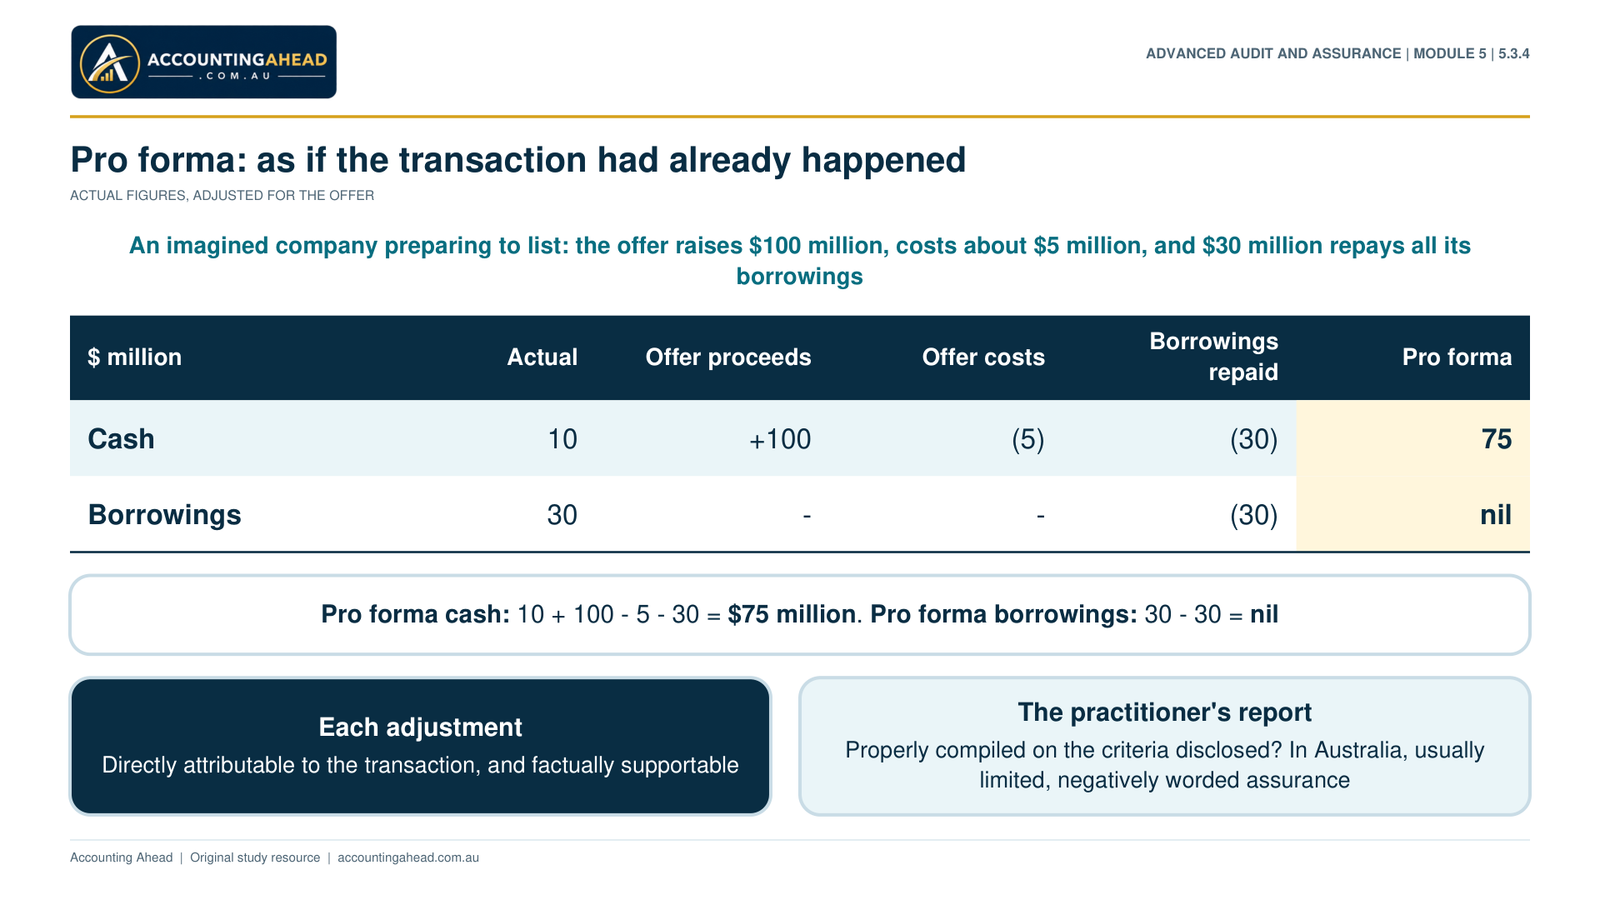
Part 5.3.4 · Prospective and Pro Forma Information
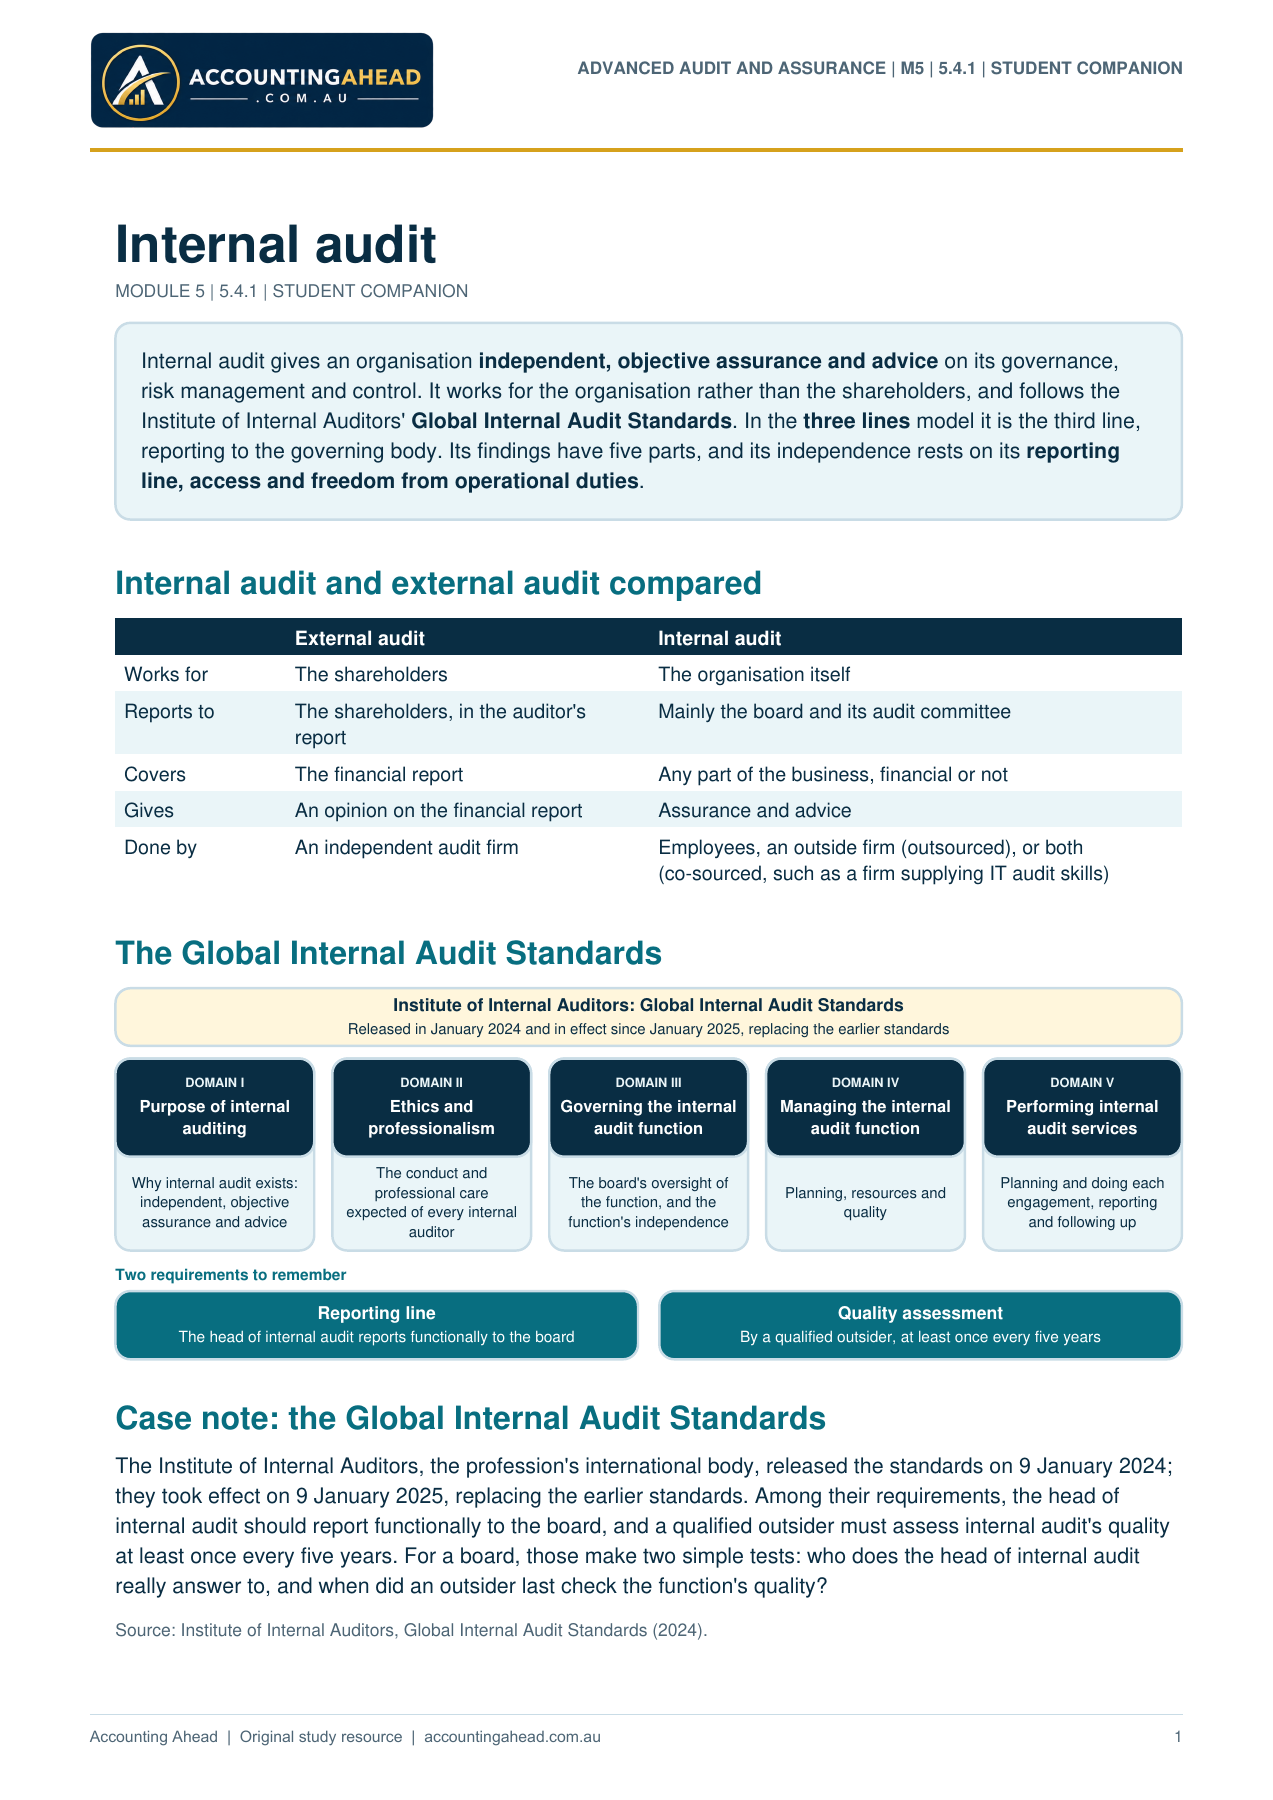
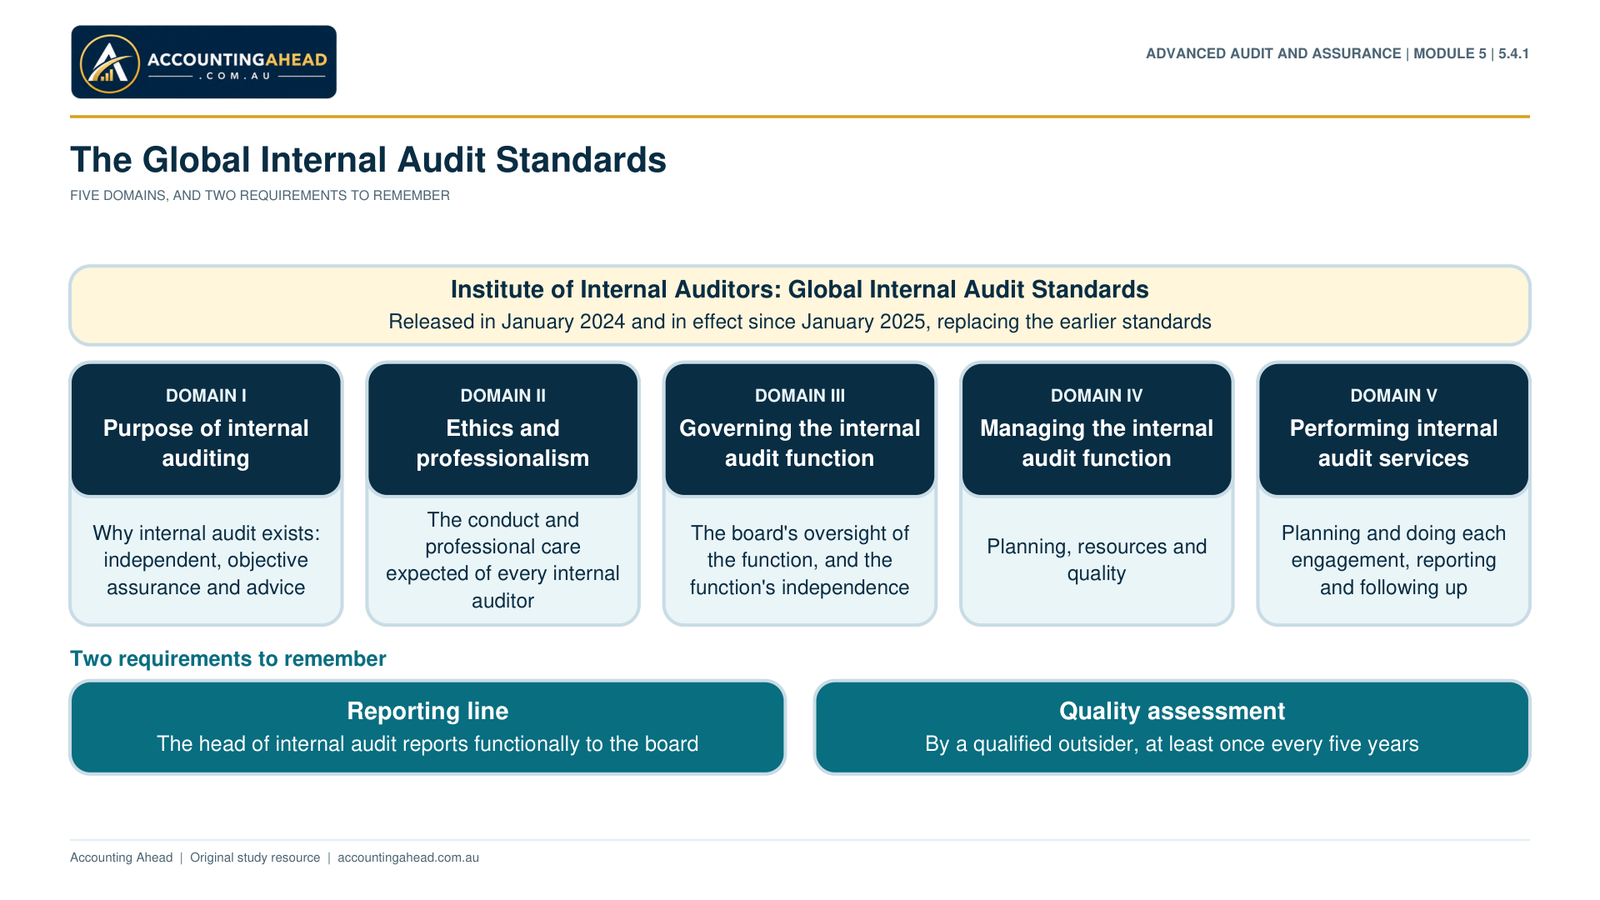
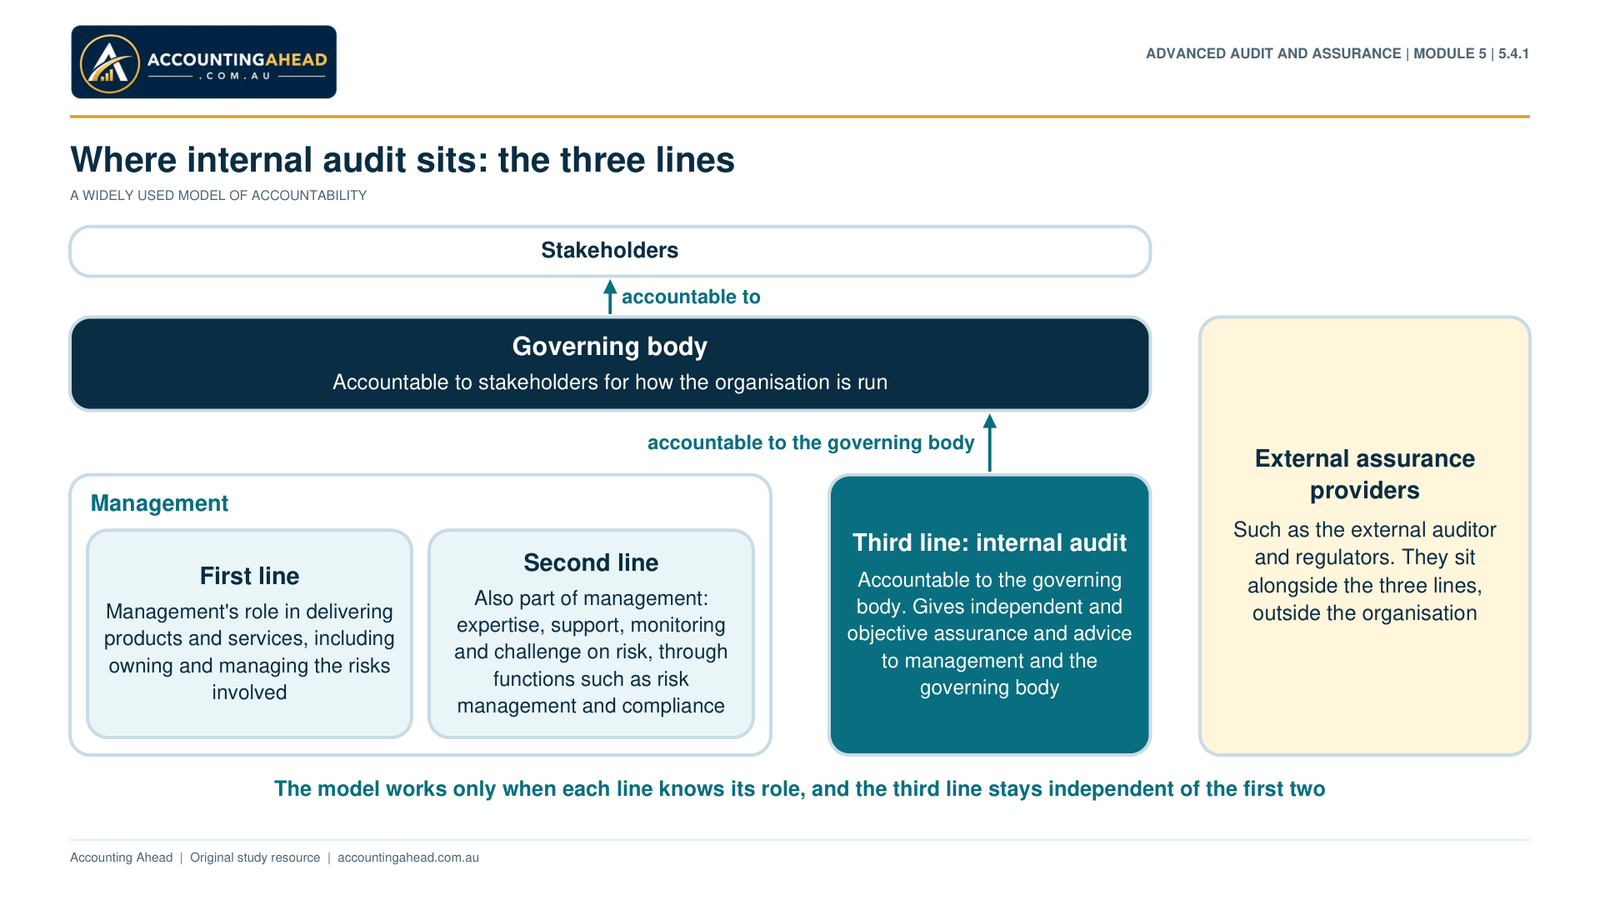
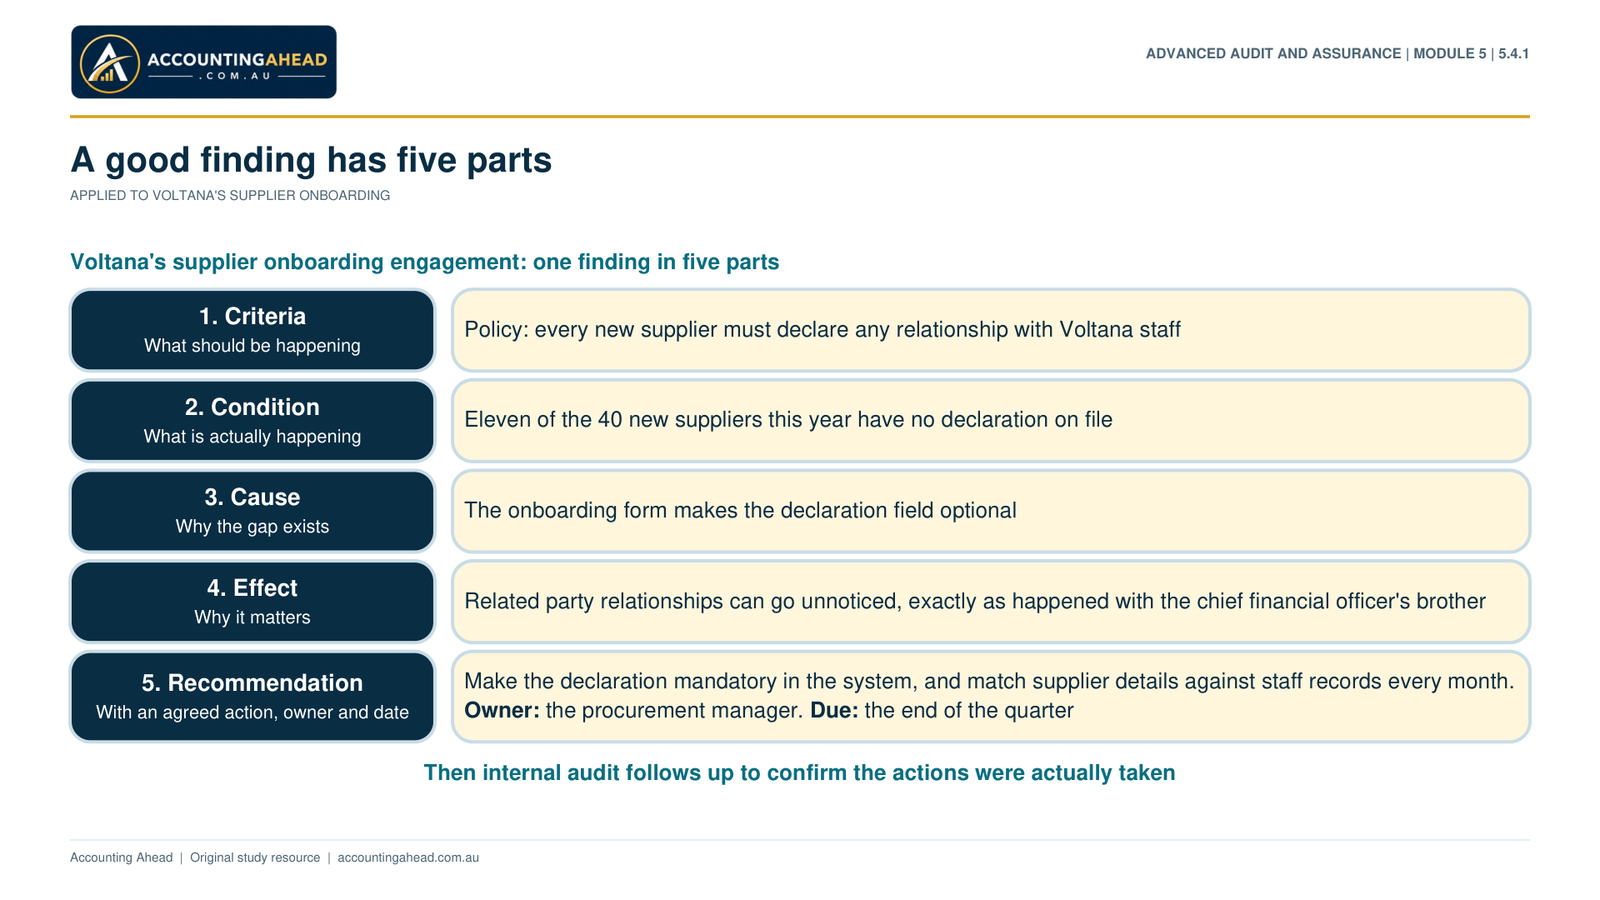
Part 5.4.1 · Internal Audit
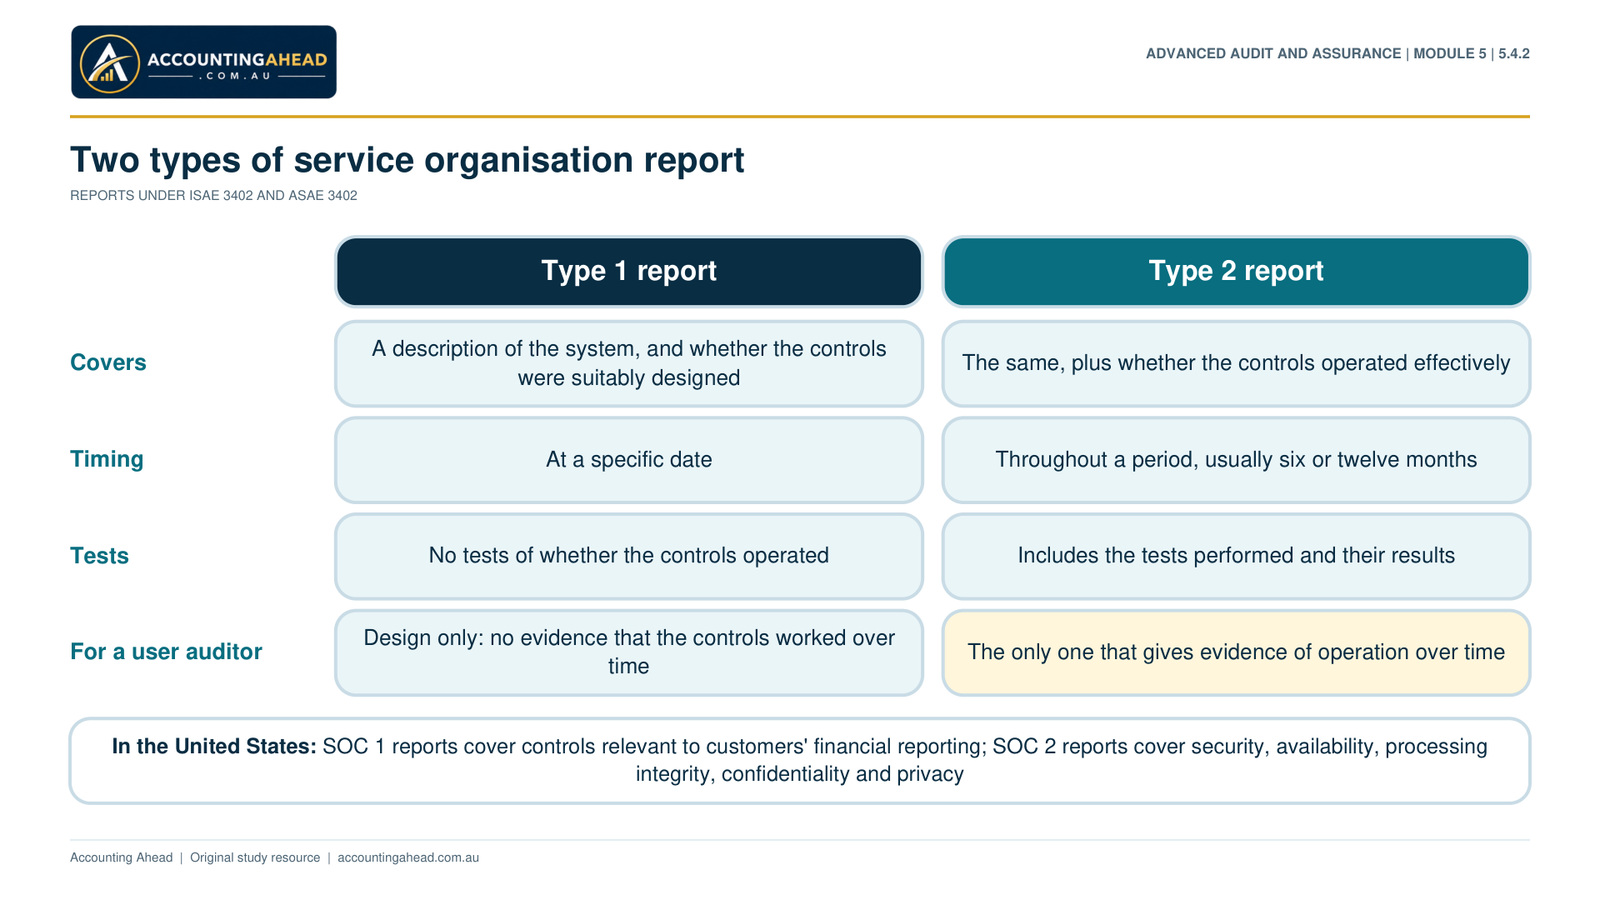
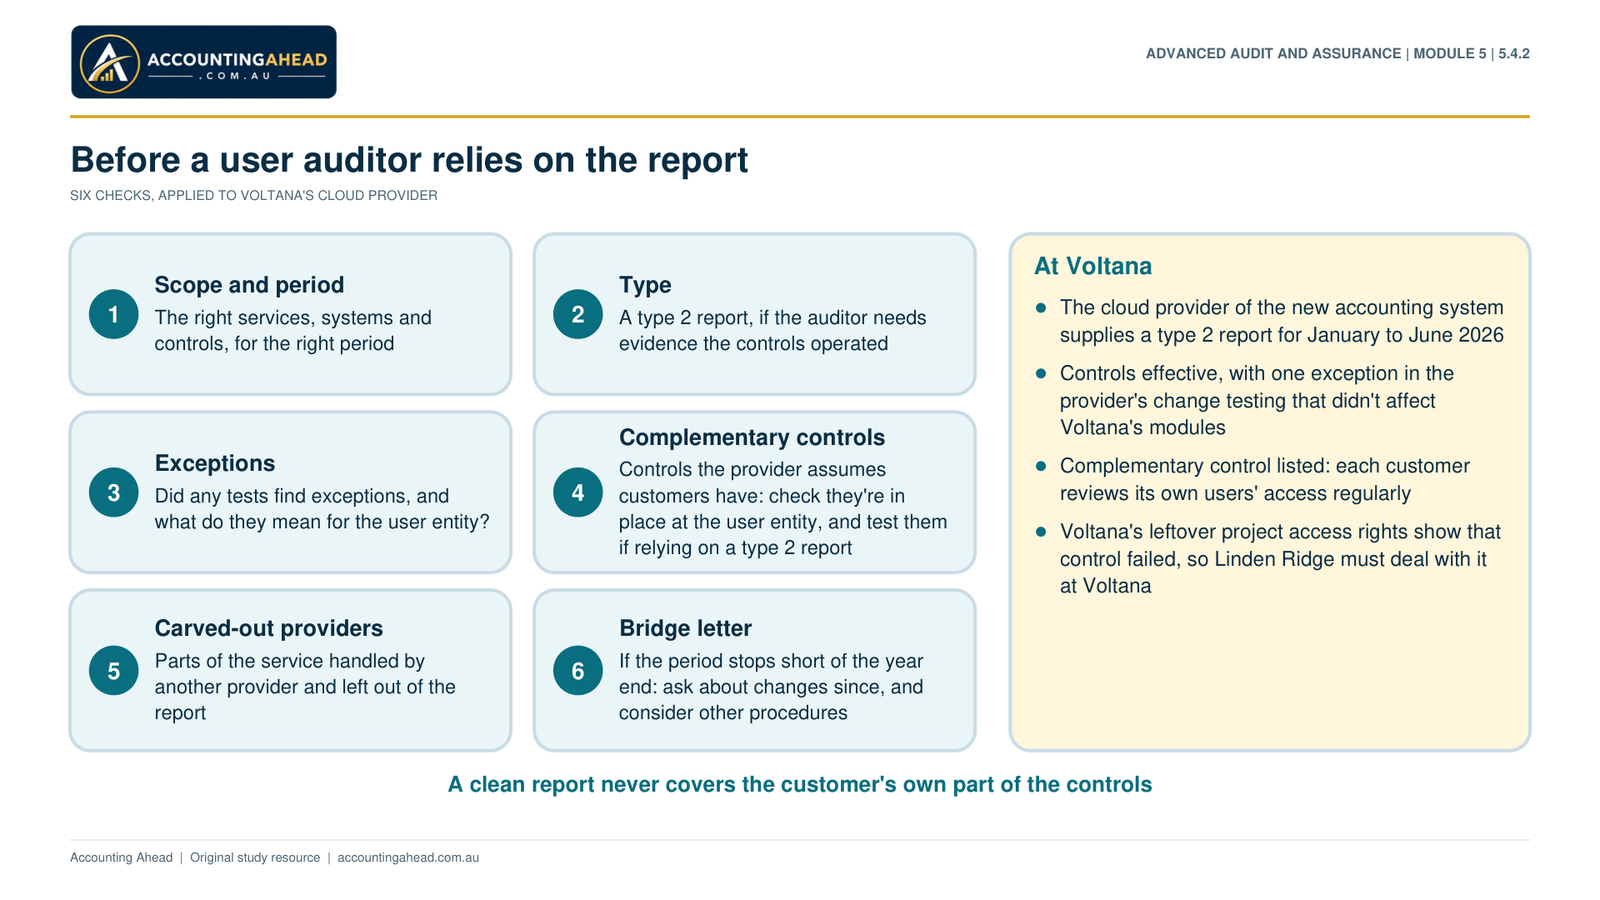
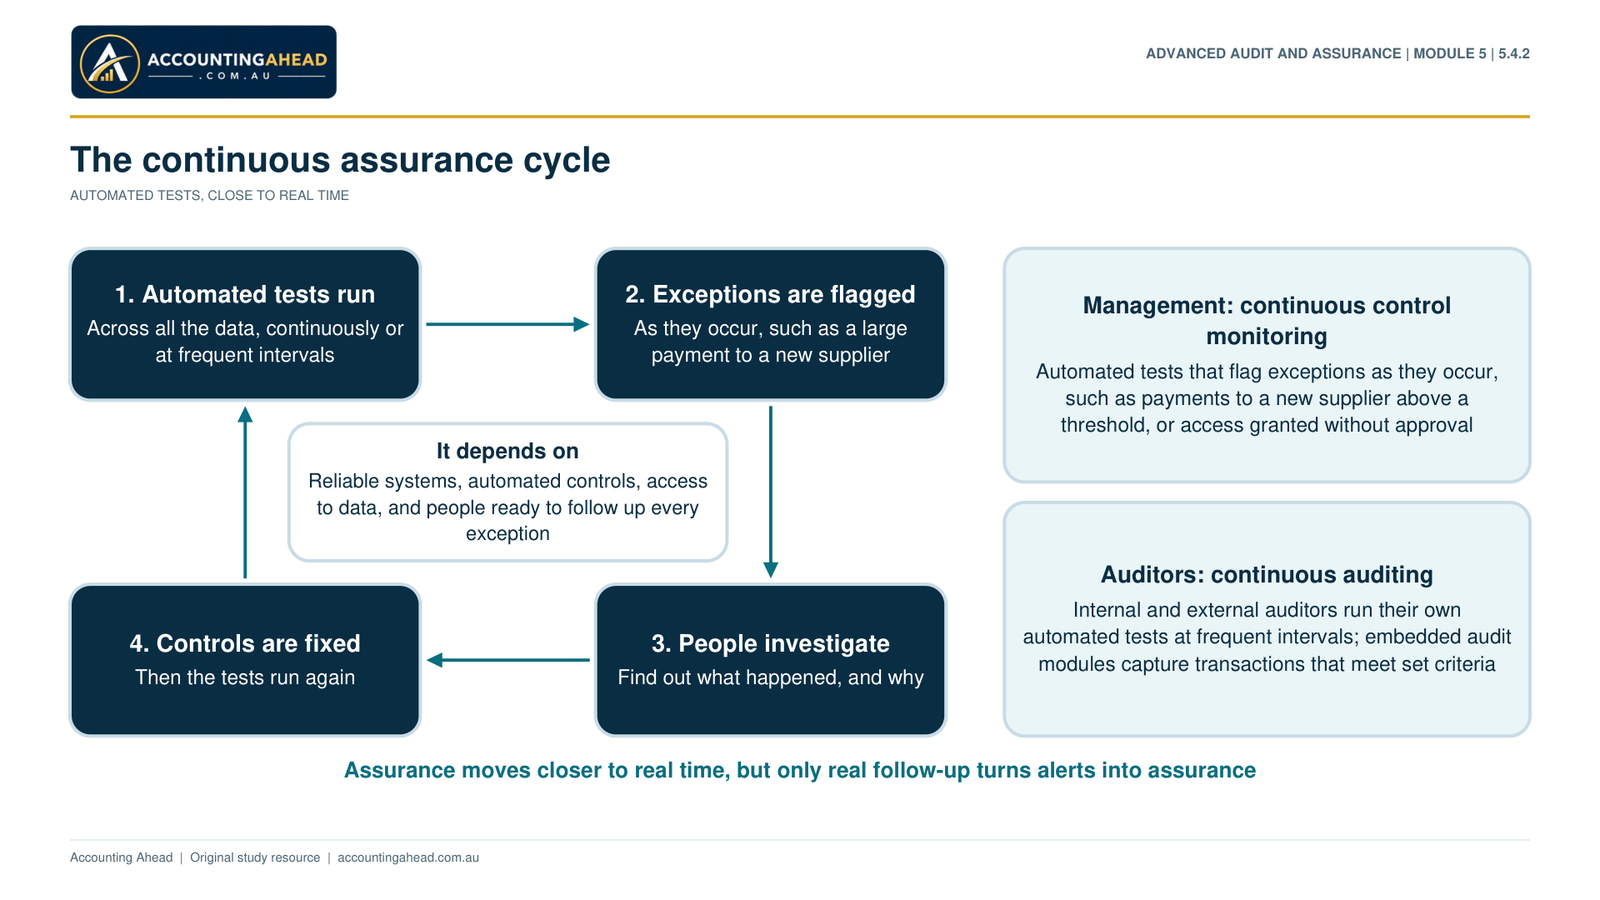
Part 5.4.2 · Controls Assurance and Continuous Assurance
Part 5.4.3 · Compliance and Governance Assurance
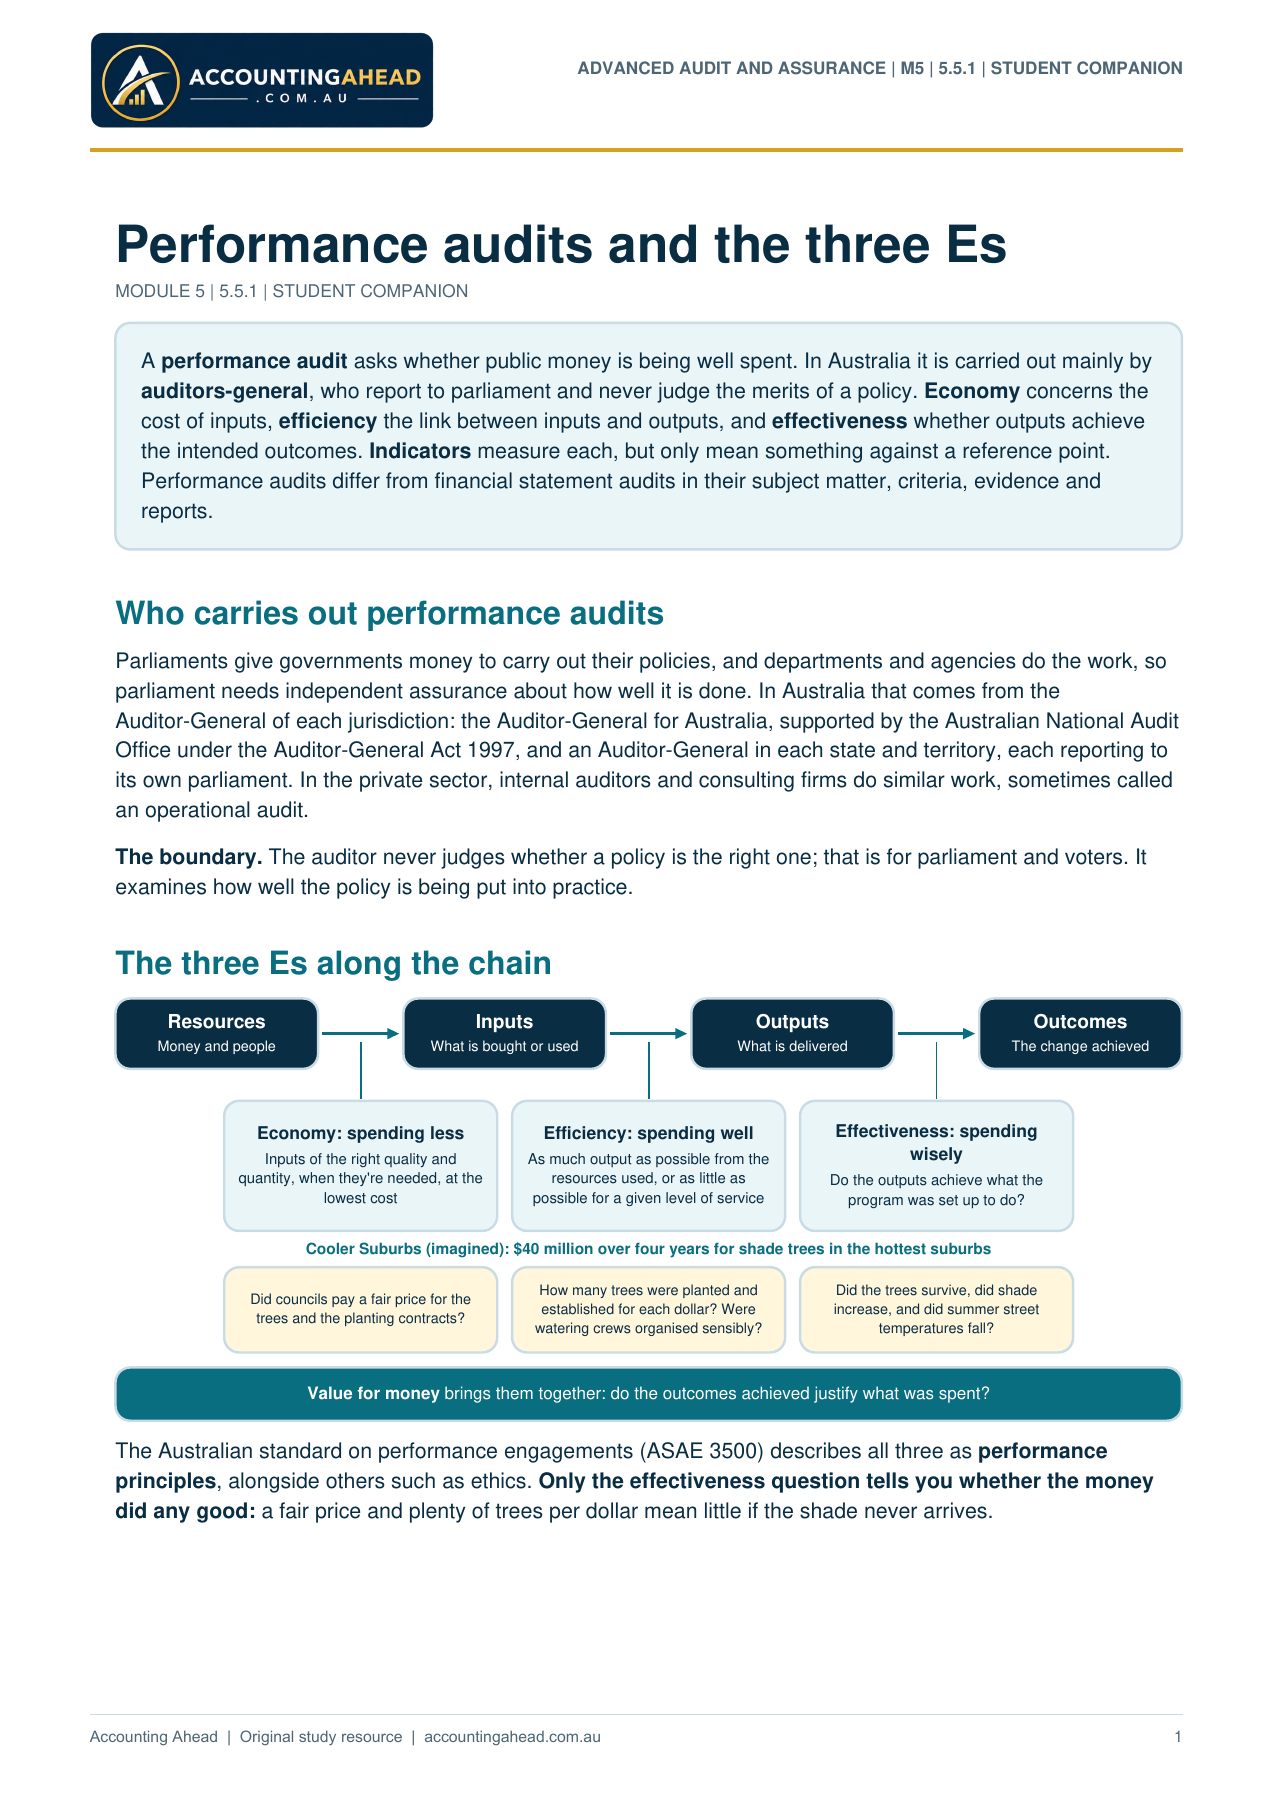
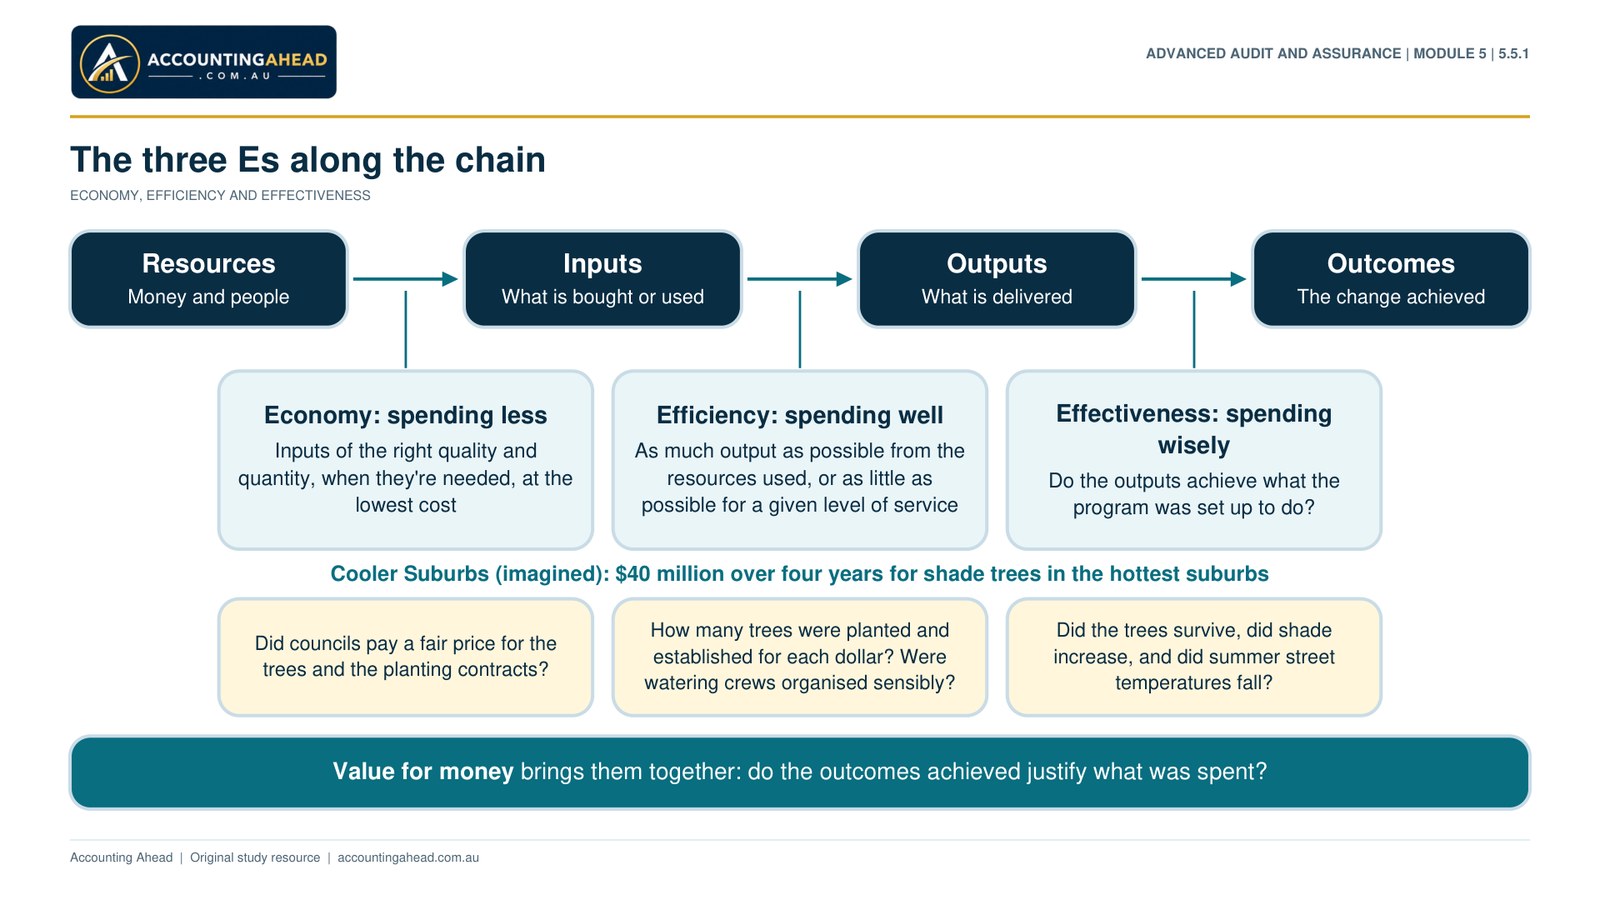
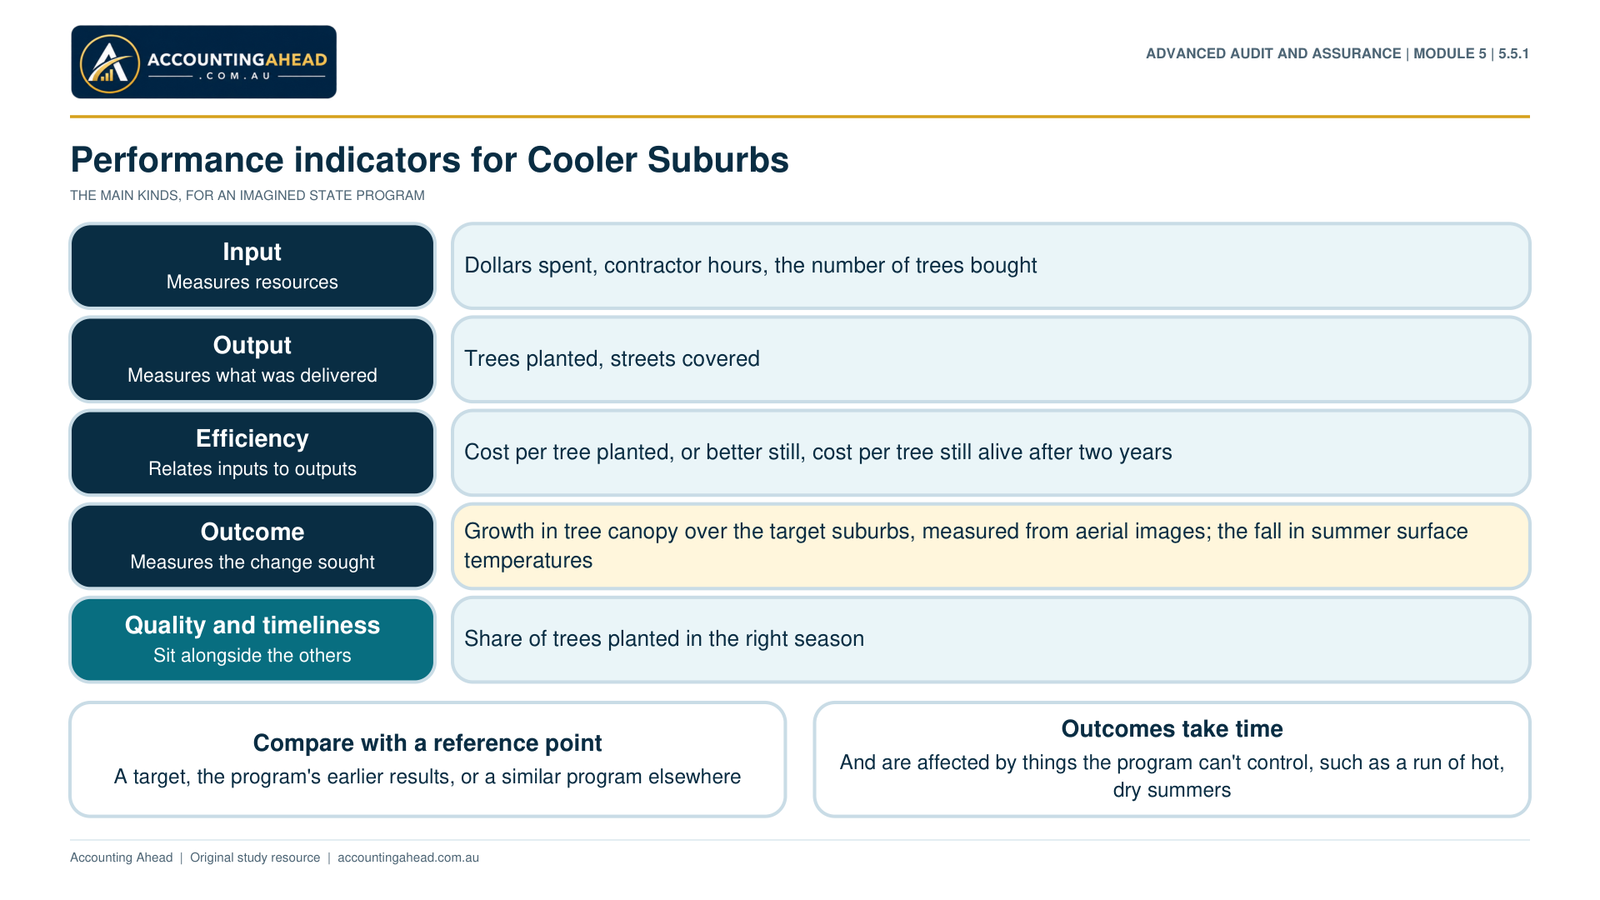
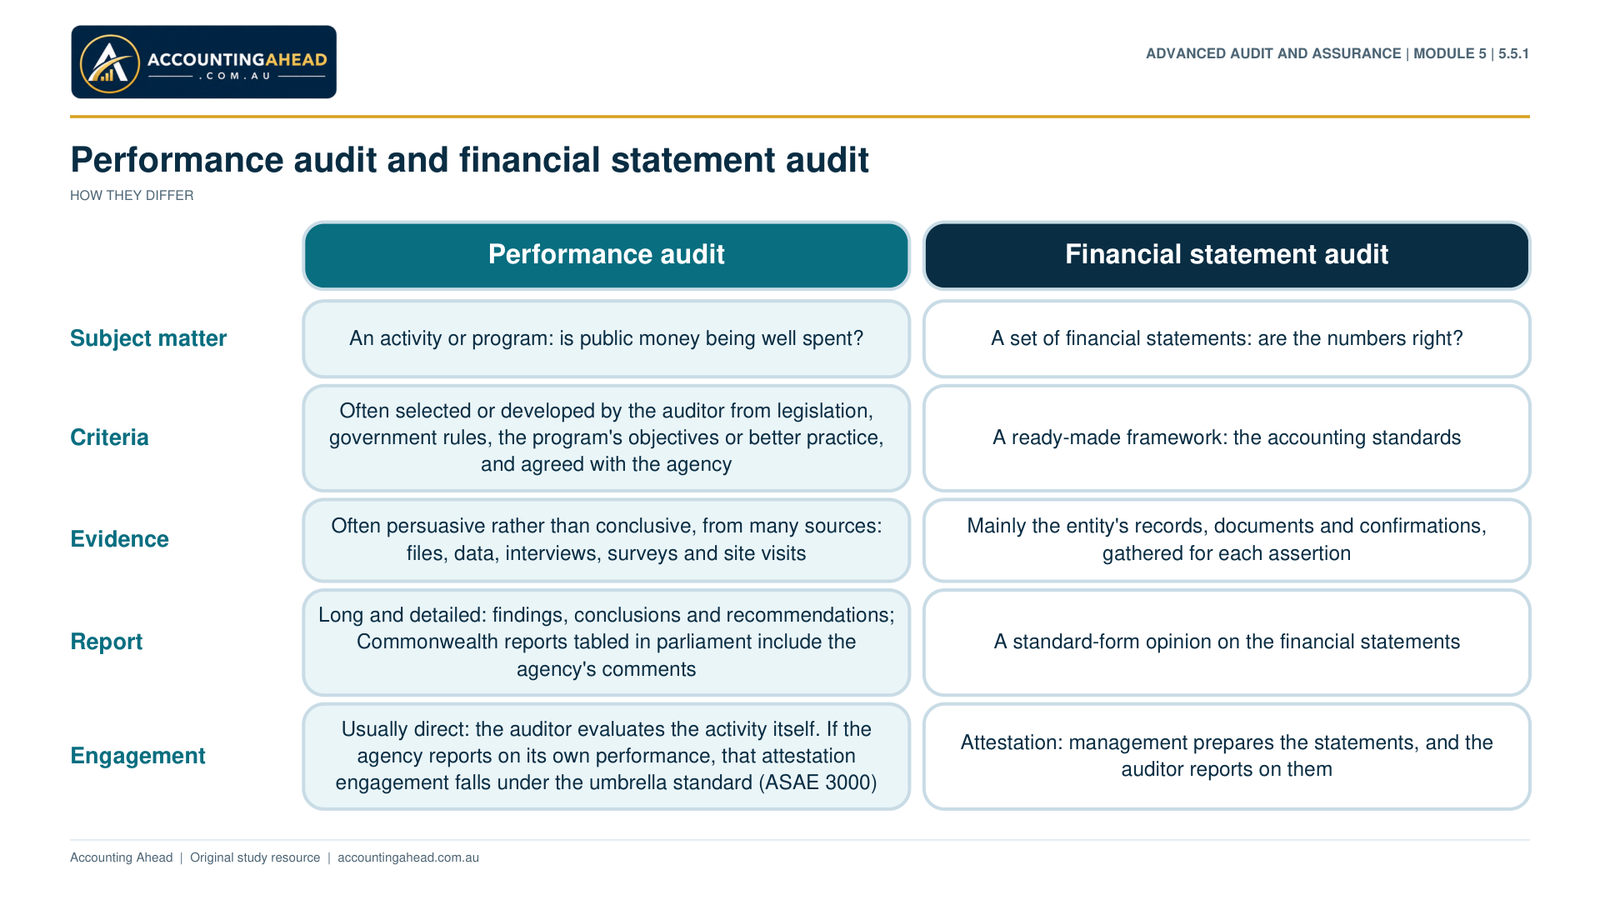
Part 5.5.1 · Performance Audits and the Three Es
Part 5.5.2 · Conducting a Performance Audit
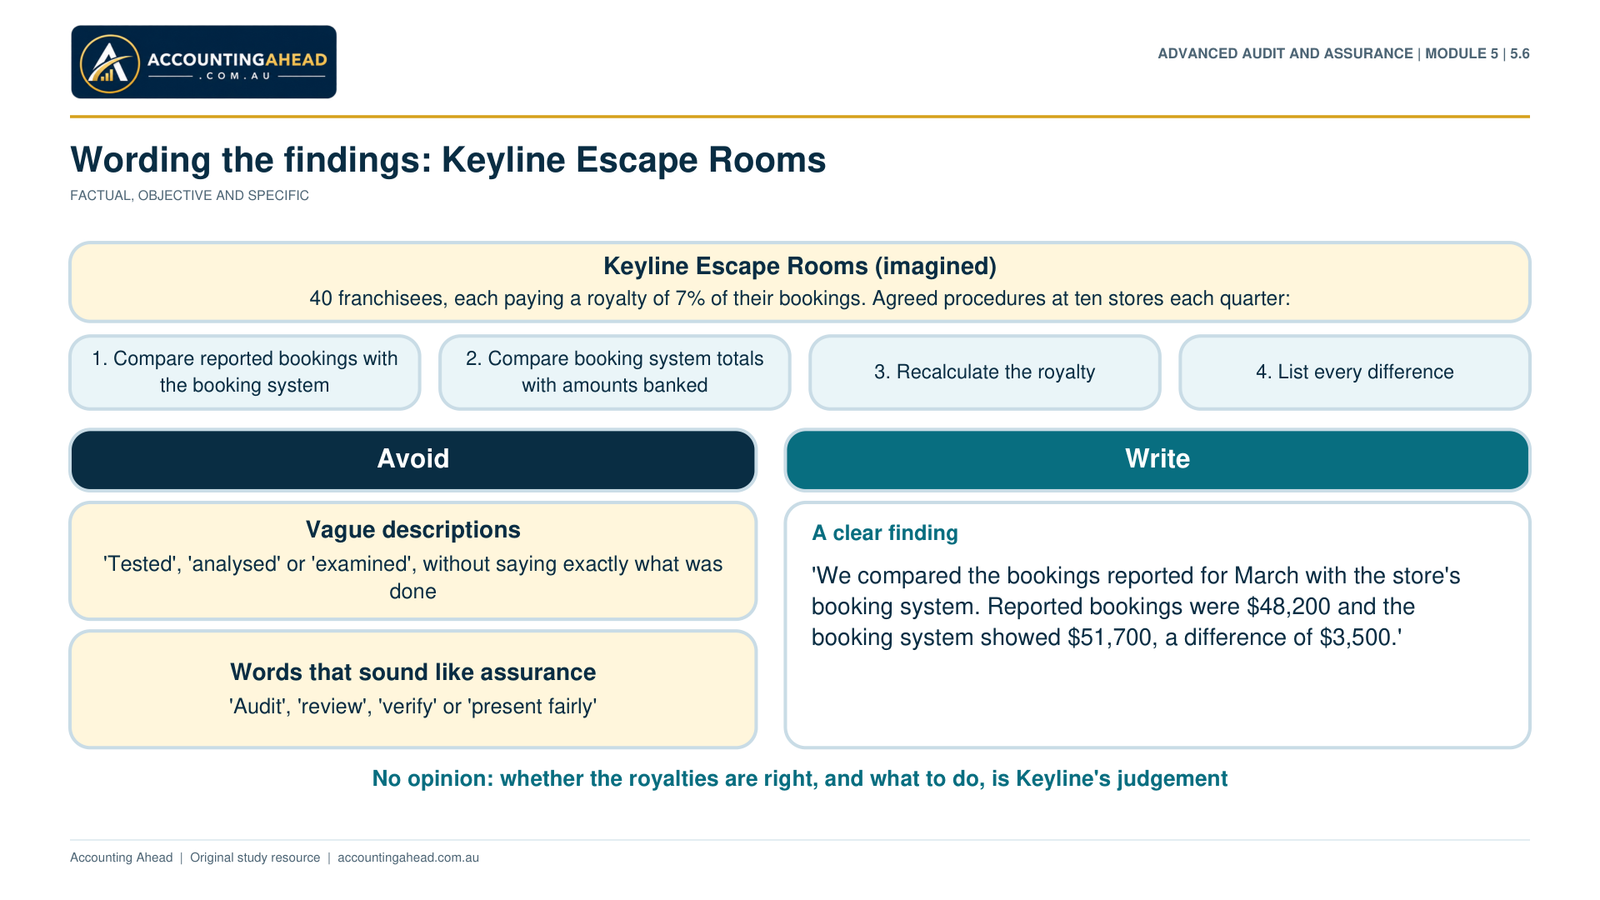
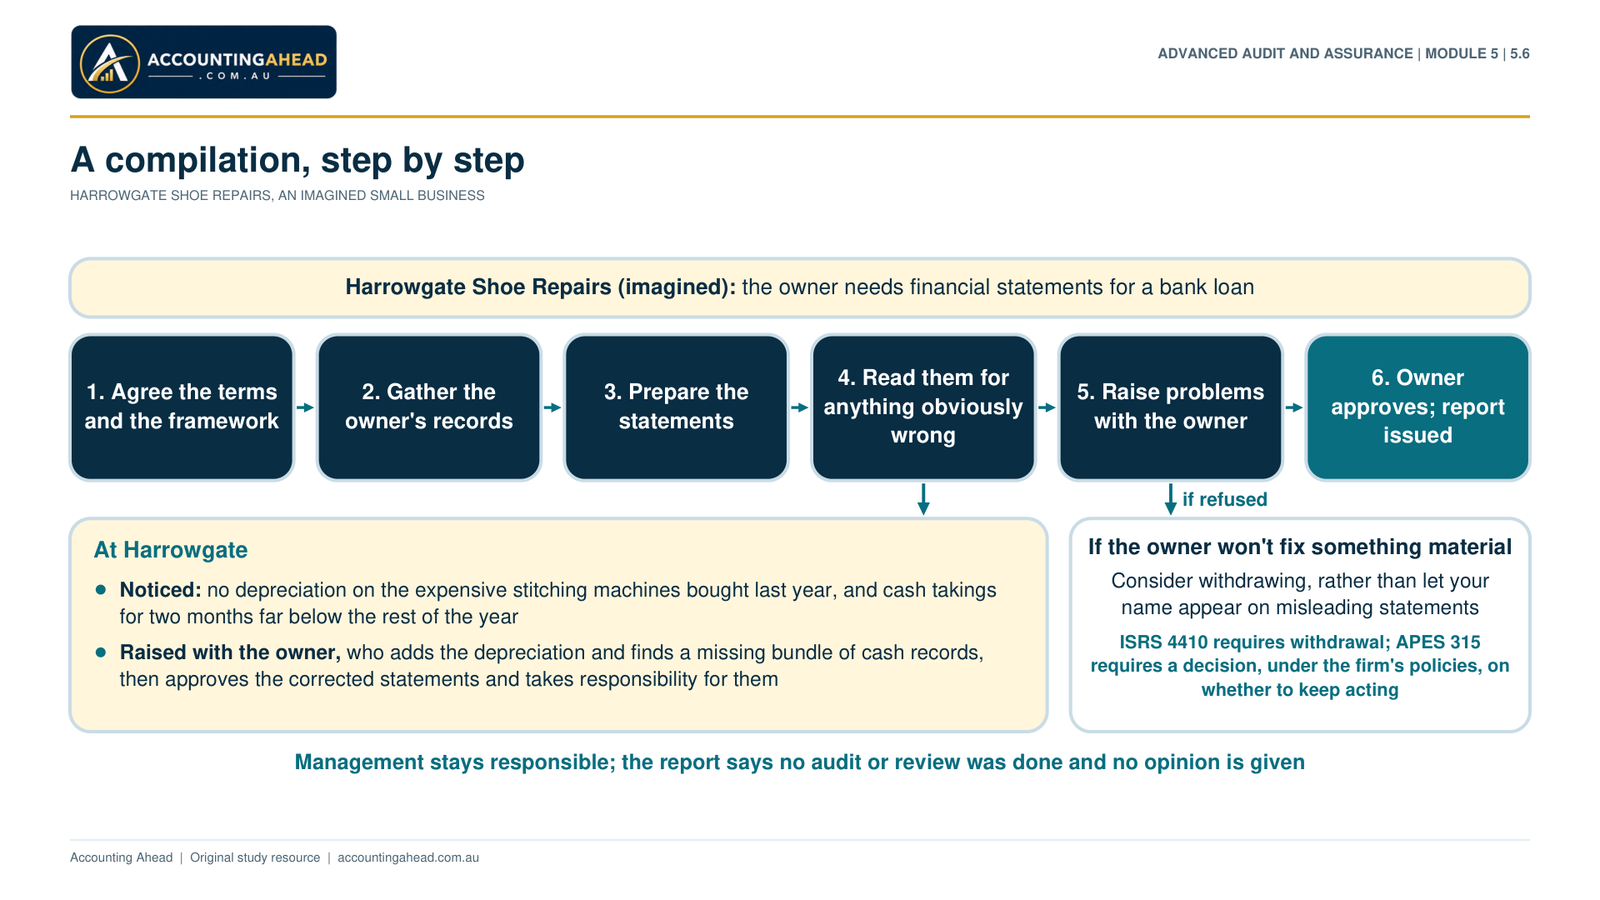
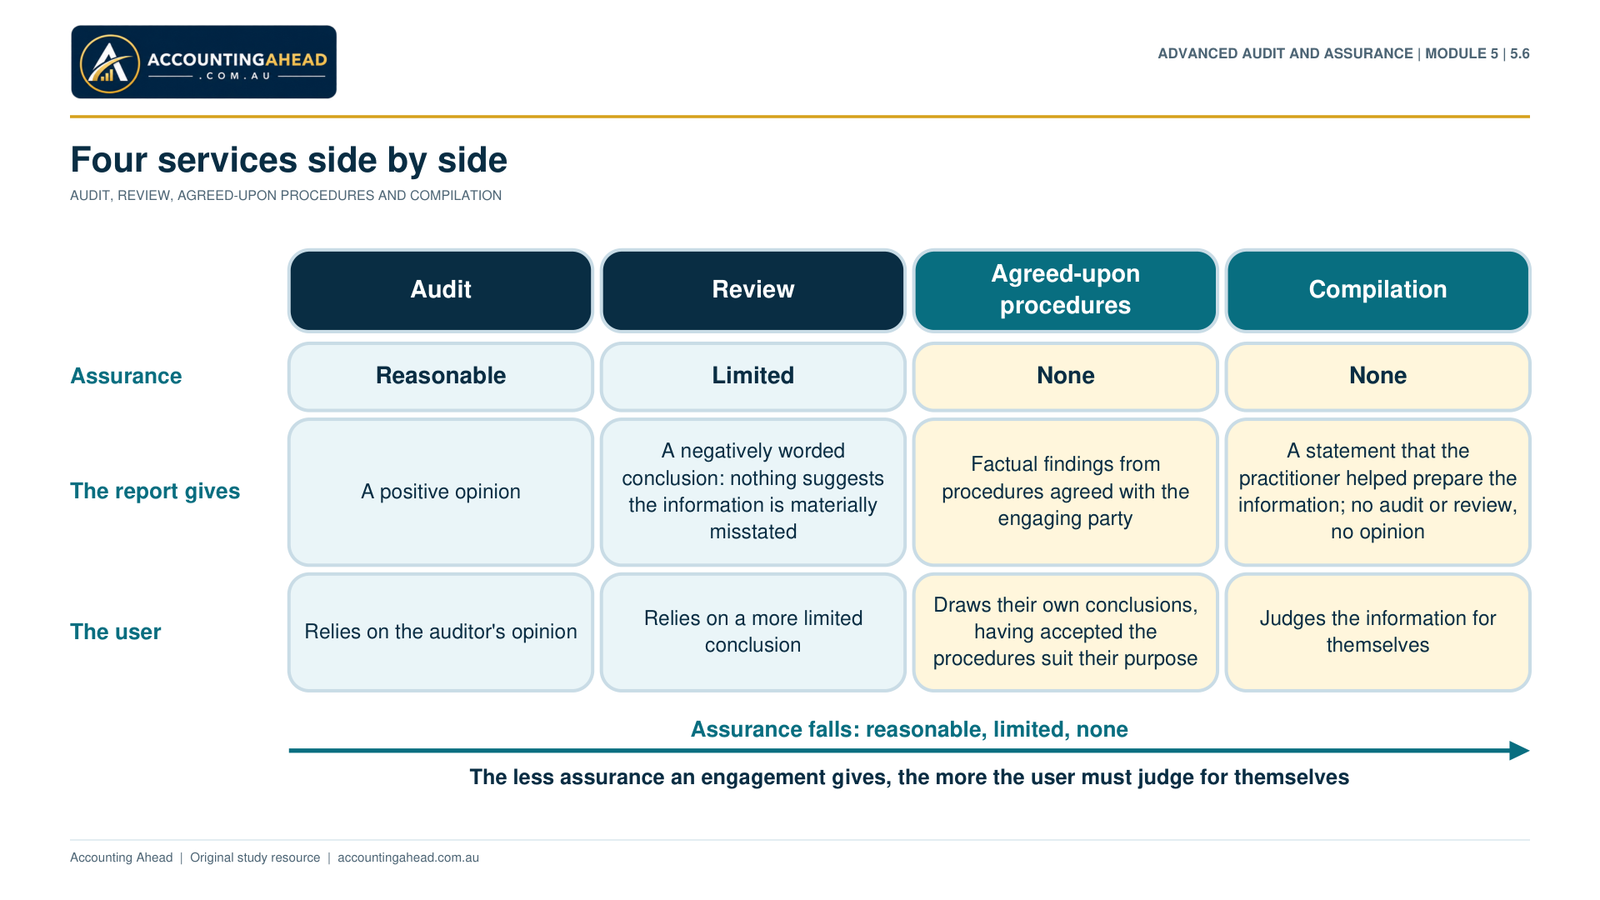
Part 5.6 · Agreed-Upon Procedures and Compilations
AAA exam reference pack
Subject-wide exam references and visual summaries. Open each file to preview, download or print.