
Going concern, climate and NOCLAR risks
Printable study notes, diagrams and practice support for Part 2.6.3.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
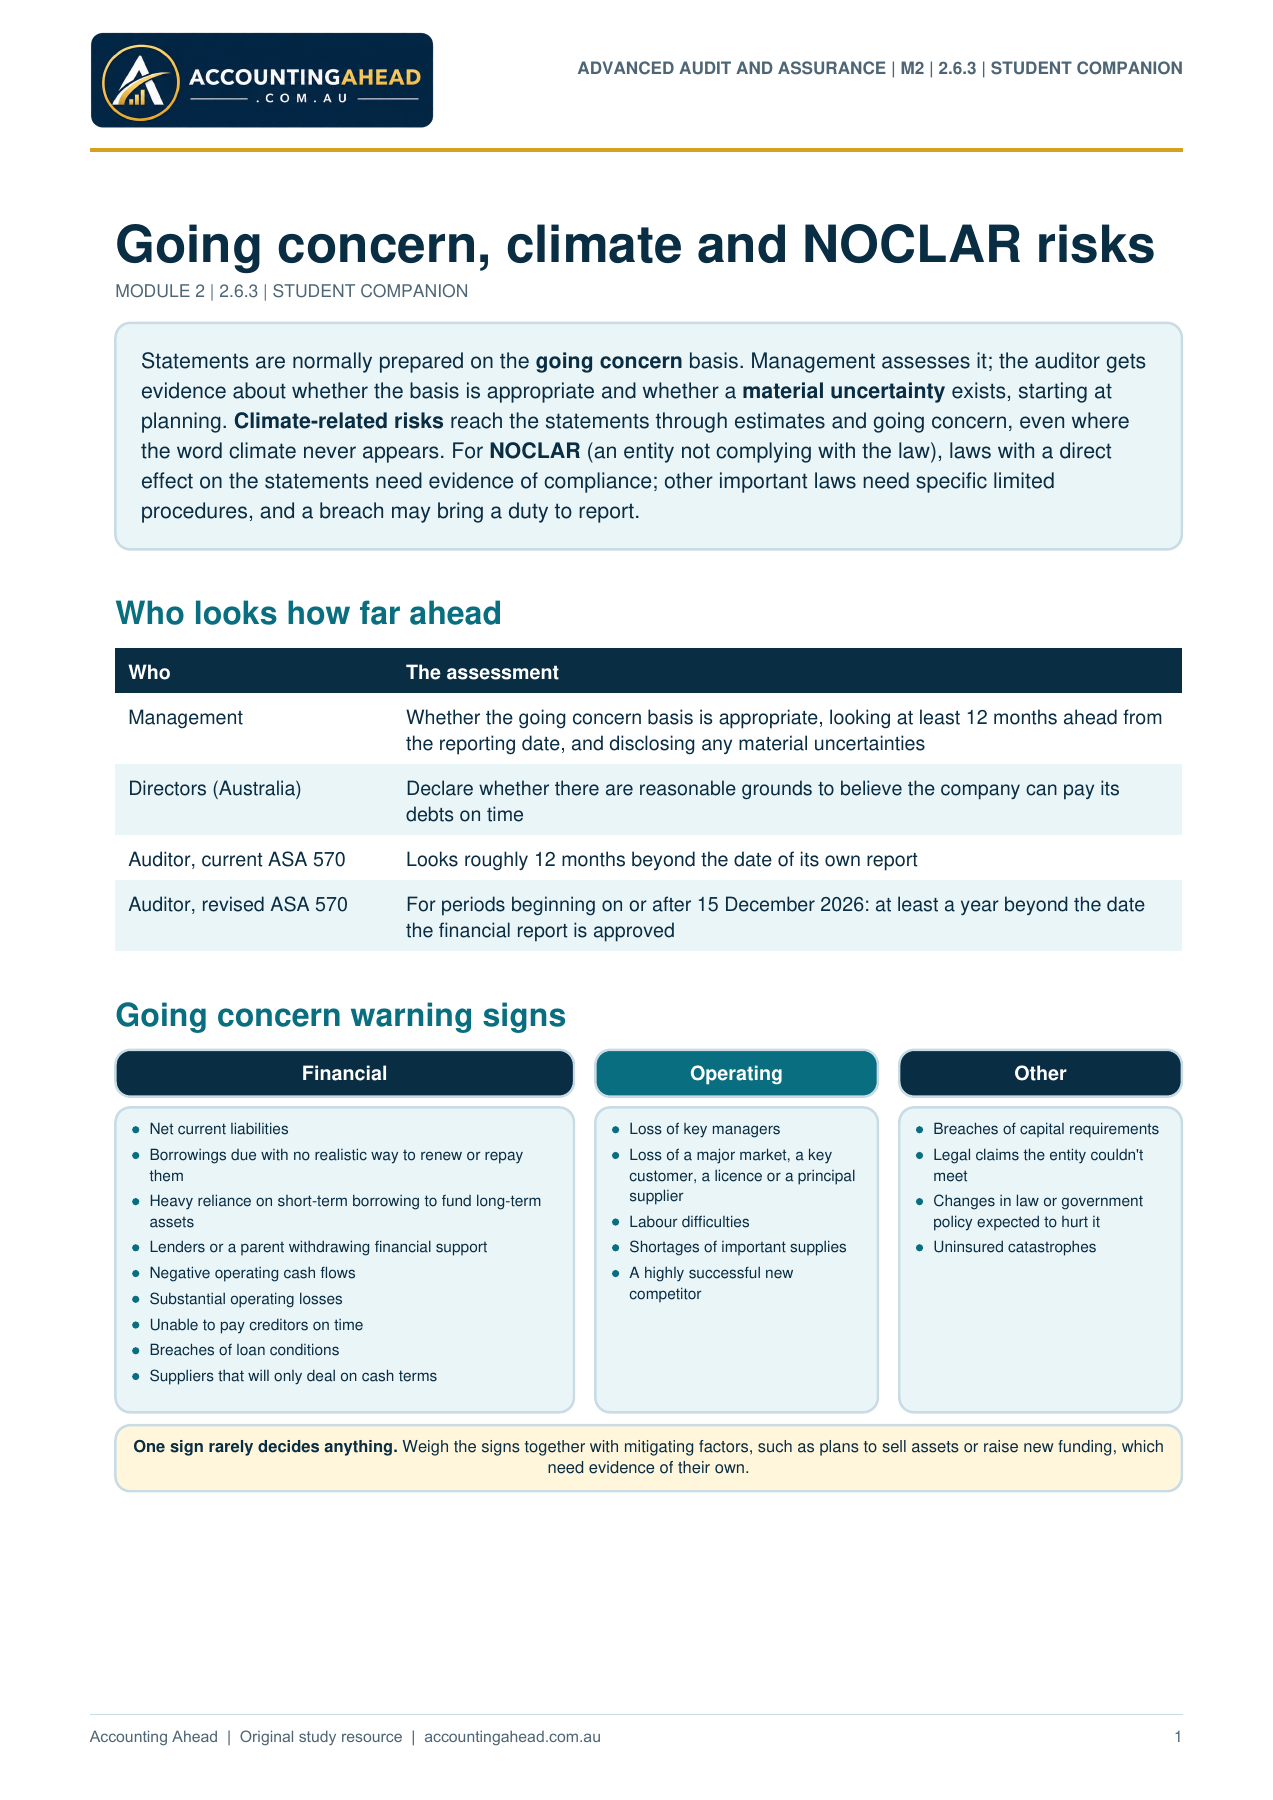
Going concern, climate and NOCLAR risks
MODULE 2 | 2.6.3 | STUDENT COMPANION
Statements are normally prepared on the going concern basis. Management assesses it; the auditor gets
evidence about whether the basis is appropriate and whether a material uncertainty exists, starting at
planning. Climate-related risks reach the statements through estimates and going concern, even where
the word climate never appears. For NOCLAR (an entity not complying with the law), laws with a direct
effect on the statements need evidence of compliance; other important laws need specific limited
procedures, and a breach may bring a duty to report.
Who looks how far ahead
Who The assessment
Management Whether the going concern basis is appropriate, looking at least 12 months ahead from
the reporting date, and disclosing any material uncertainties
Directors (Australia) Declare whether there are reasonable grounds to believe the company can pay its
debts on time
Auditor, current ASA 570 Looks roughly 12 months beyond the date of its own report
Auditor, revised ASA 570 For periods beginning on or after 15 December 2026: at least a year beyond the date
the financial report is approved
Going concern warning signs
Financial
Net current liabilities
Borrowings due with no realistic way to renew or repay
them
Heavy reliance on short-term borrowing to fund long-term
assets
Lenders or a parent withdrawing financial support
Negative operating cash flows
Substantial operating losses
Unable to pay creditors on time
Breaches of loan conditions
Suppliers that will only deal on cash terms
Operating
Loss of key managers
Loss of a major market, a key
customer, a licence or a principal
supplier
Labour difficulties
Shortages of important supplies
A highly successful new
competitor
Other
Breaches of capital requirements
Legal claims the entity couldn't
meet
Changes in law or government
policy expected to hurt it
Uninsured catastrophes
One sign rarely decides anything. Weigh the signs together with mitigating factors, such as plans to sell assets or raise new funding, which
need evidence of their own.
ADVANCED AUDIT AND ASSURANCE | M2 | 2.6.3 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
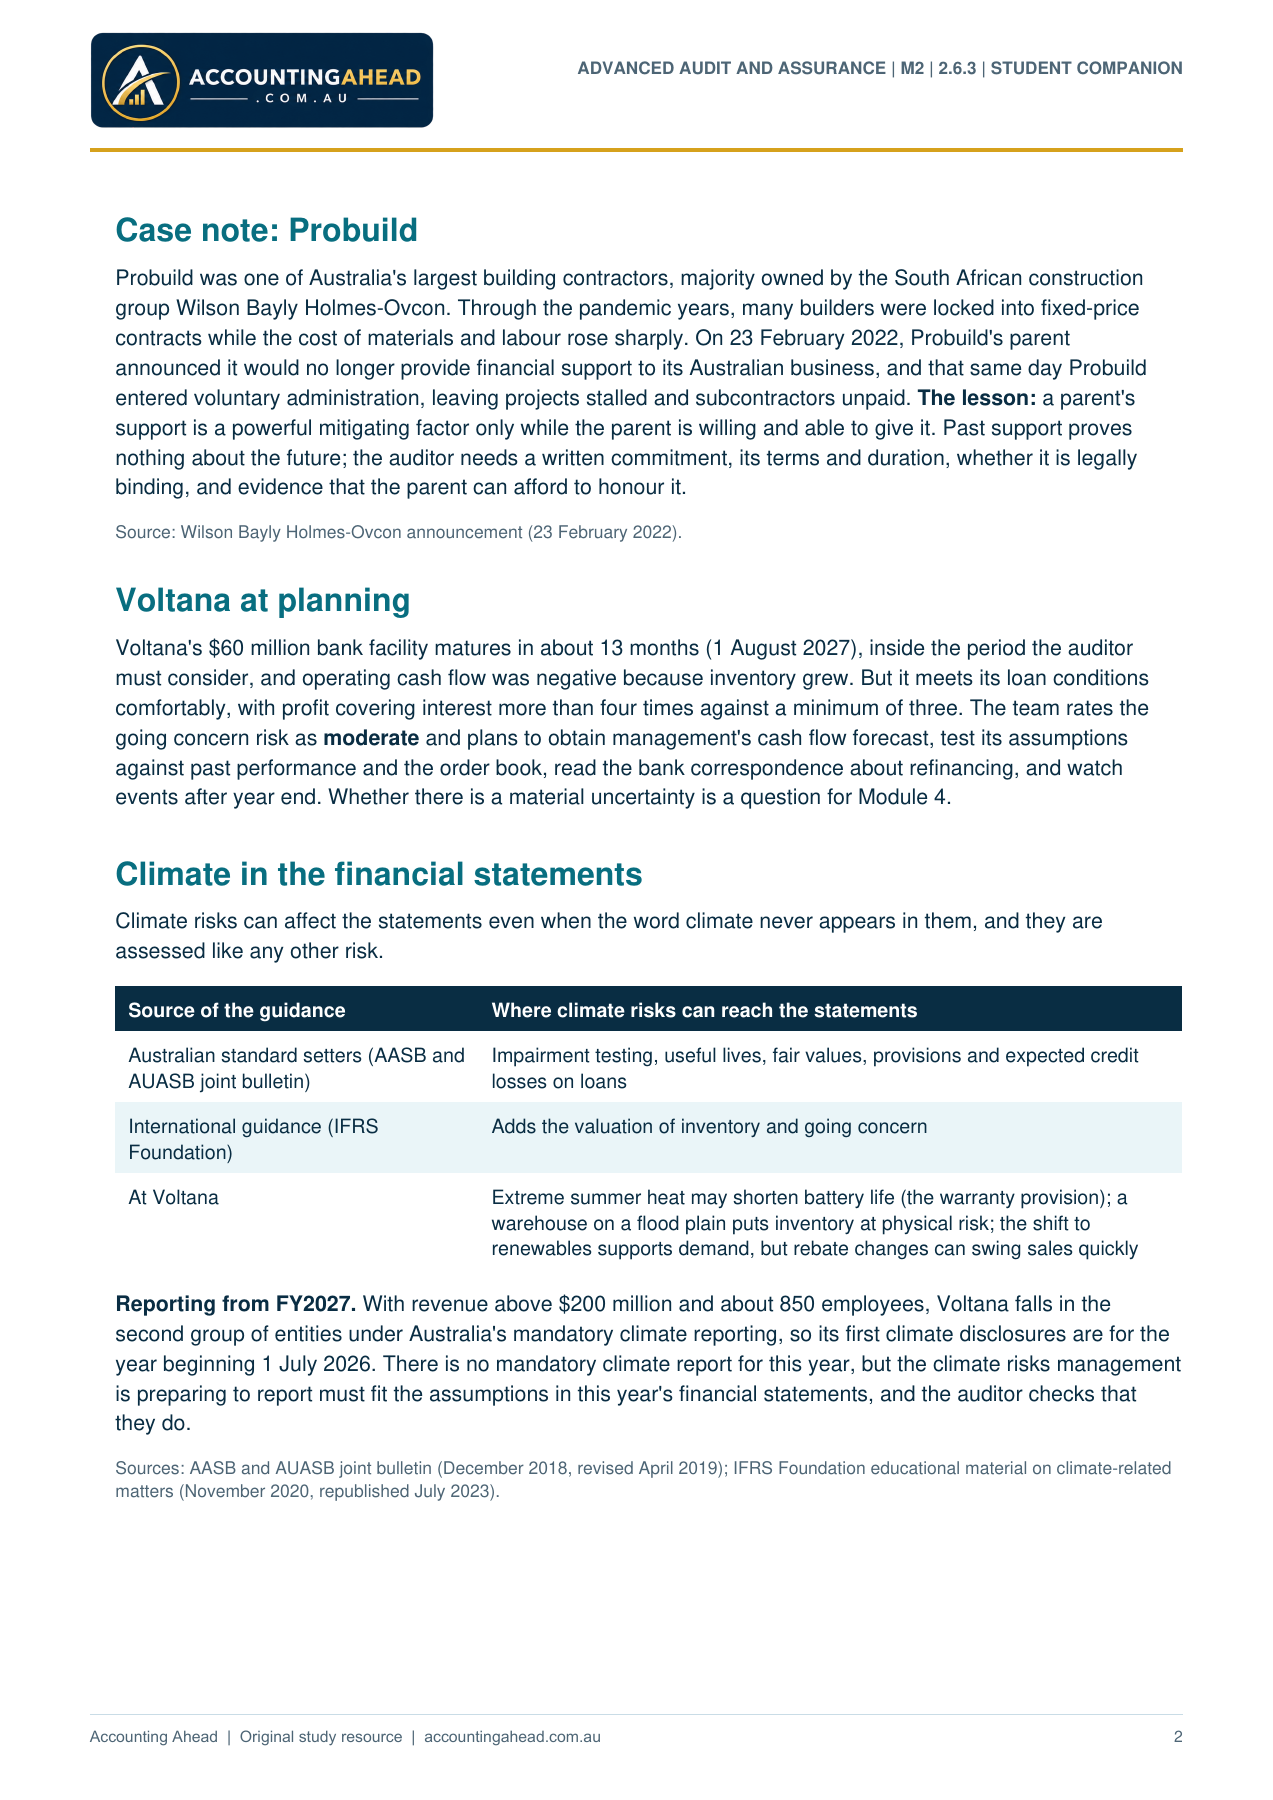
Case note: Probuild
Probuild was one of Australia's largest building contractors, majority owned by the South African construction
group Wilson Bayly Holmes-Ovcon. Through the pandemic years, many builders were locked into fixed-price
contracts while the cost of materials and labour rose sharply. On 23 February 2022, Probuild's parent
announced it would no longer provide financial support to its Australian business, and that same day Probuild
entered voluntary administration, leaving projects stalled and subcontractors unpaid. The lesson: a parent's
support is a powerful mitigating factor only while the parent is willing and able to give it. Past support proves
nothing about the future; the auditor needs a written commitment, its terms and duration, whether it is legally
binding, and evidence that the parent can afford to honour it.
Source: Wilson Bayly Holmes-Ovcon announcement (23 February 2022).
Voltana at planning
Voltana's $60 million bank facility matures in about 13 months (1 August 2027), inside the period the auditor
must consider, and operating cash flow was negative because inventory grew. But it meets its loan conditions
comfortably, with profit covering interest more than four times against a minimum of three. The team rates the
going concern risk as moderate and plans to obtain management's cash flow forecast, test its assumptions
against past performance and the order book, read the bank correspondence about refinancing, and watch
events after year end. Whether there is a material uncertainty is a question for Module 4.
Climate in the financial statements
Climate risks can affect the statements even when the word climate never appears in them, and they are
assessed like any other risk.
Source of the guidance Where climate risks can reach the statements
Australian standard setters (AASB and
AUASB joint bulletin)
Impairment testing, useful lives, fair values, provisions and expected credit
losses on loans
International guidance (IFRS
Foundation)
Adds the valuation of inventory and going concern
At Voltana Extreme summer heat may shorten battery life (the warranty provision); a
warehouse on a flood plain puts inventory at physical risk; the shift to
renewables supports demand, but rebate changes can swing sales quickly
Reporting from FY2027. With revenue above $200 million and about 850 employees, Voltana falls in the
second group of entities under Australia's mandatory climate reporting, so its first climate disclosures are for the
year beginning 1 July 2026. There is no mandatory climate report for this year, but the climate risks management
is preparing to report must fit the assumptions in this year's financial statements, and the auditor checks that
they do.
Sources: AASB and AUASB joint bulletin (December 2018, revised April 2019); IFRS Foundation educational material on climate-related
matters (November 2020, republished July 2023).
ADVANCED AUDIT AND ASSURANCE | M2 | 2.6.3 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
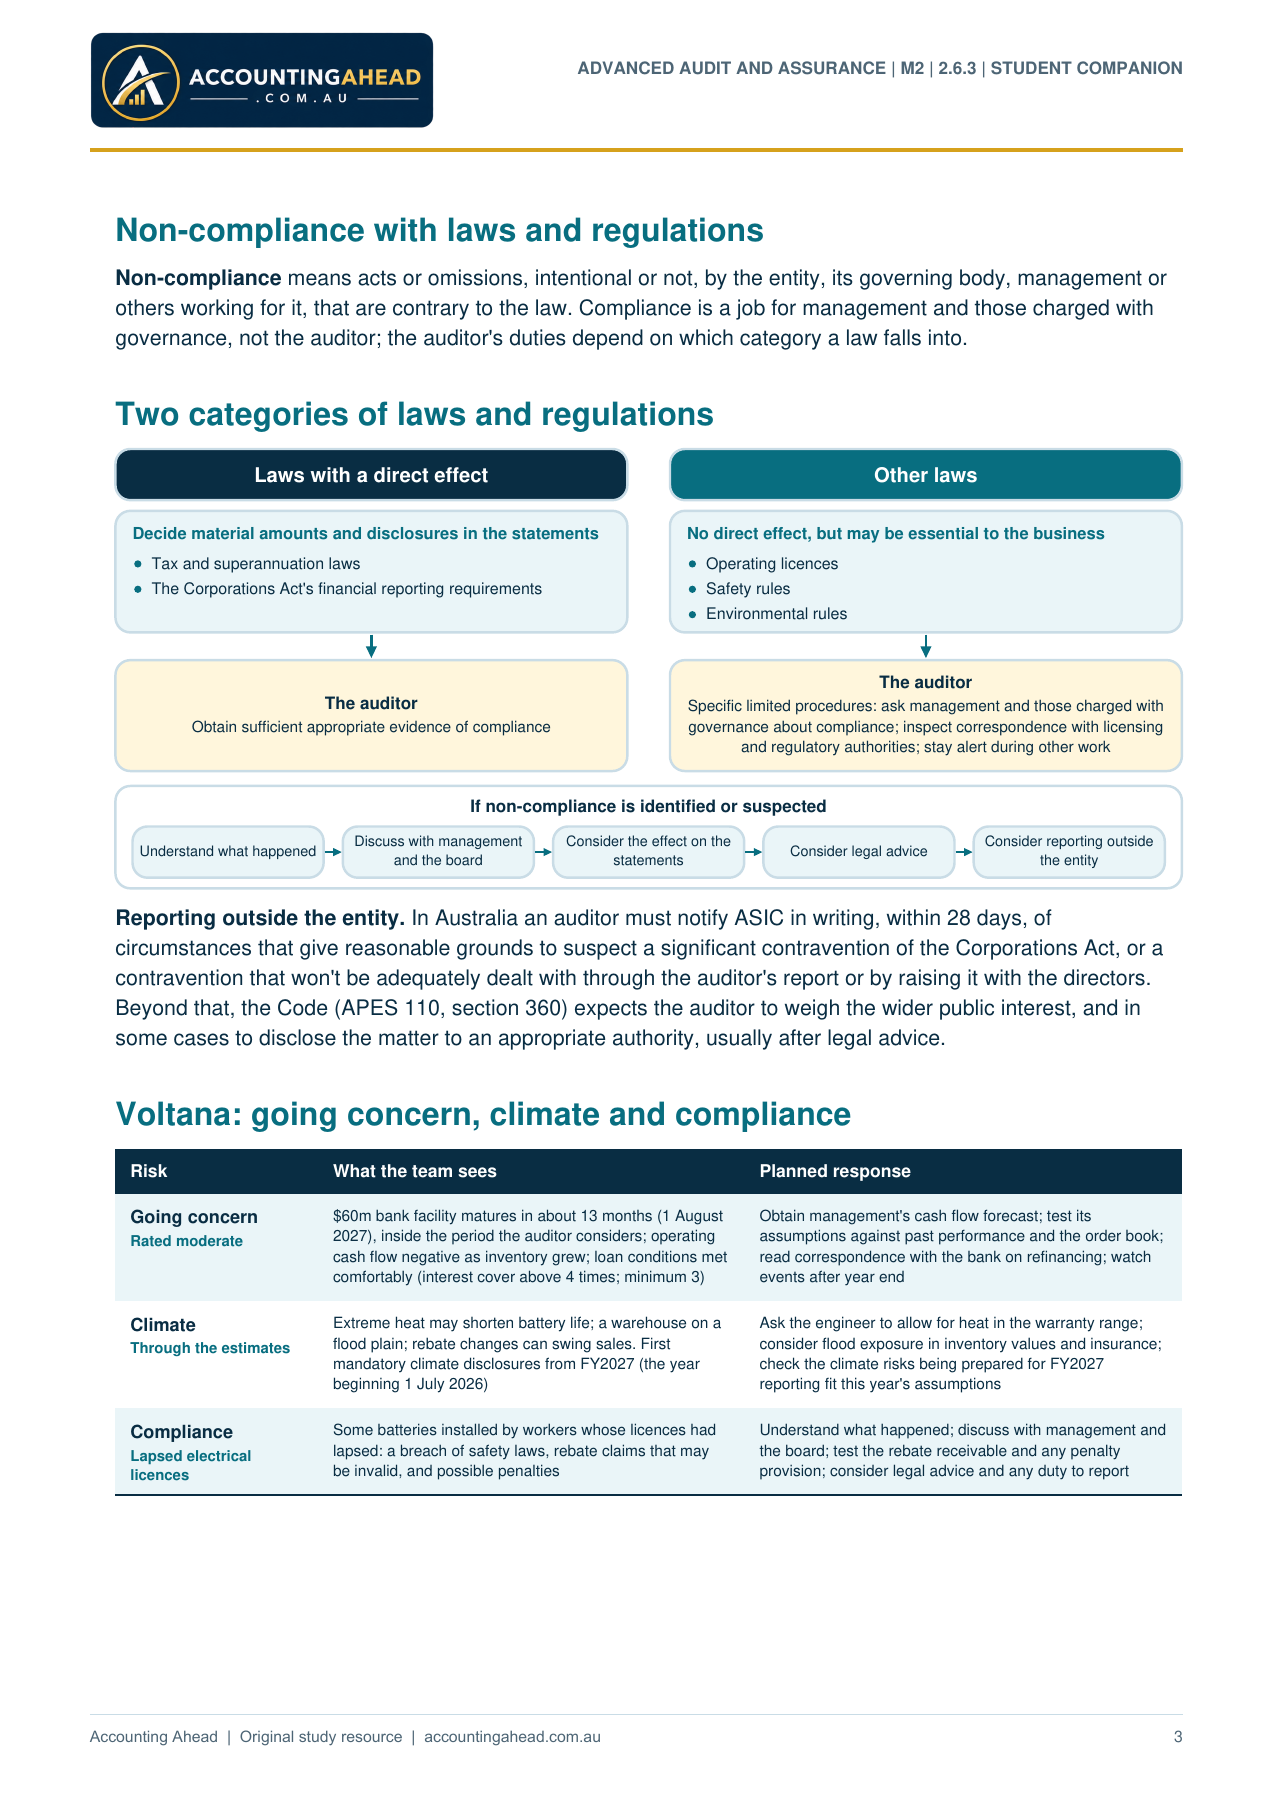
Non-compliance with laws and regulations
Non-compliance means acts or omissions, intentional or not, by the entity, its governing body, management or
others working for it, that are contrary to the law. Compliance is a job for management and those charged with
governance, not the auditor; the auditor's duties depend on which category a law falls into.
Two categories of laws and regulations
Laws with a direct effect
Decide material amounts and disclosures in the statements
Tax and superannuation laws
The Corporations Act's financial reporting requirements
The auditor
Obtain sufficient appropriate evidence of compliance
Other laws
No direct effect, but may be essential to the business
Operating licences
Safety rules
Environmental rules
The auditor
Specific limited procedures: ask management and those charged with
governance about compliance; inspect correspondence with licensing
and regulatory authorities; stay alert during other work
If non-compliance is identified or suspected
Understand what happened Discuss with management
and the board
Consider the effect on the
statements Consider legal advice Consider reporting outside
the entity
Reporting outside the entity. In Australia an auditor must notify ASIC in writing, within 28 days, of
circumstances that give reasonable grounds to suspect a significant contravention of the Corporations Act, or a
contravention that won't be adequately dealt with through the auditor's report or by raising it with the directors.
Beyond that, the Code (APES 110, section 360) expects the auditor to weigh the wider public interest, and in
some cases to disclose the matter to an appropriate authority, usually after legal advice.
Voltana: going concern, climate and compliance
Risk What the team sees Planned response
Going concern
Rated moderate
$60m bank facility matures in about 13 months (1 August
2027), inside the period the auditor considers; operating
cash flow negative as inventory grew; loan conditions met
comfortably (interest cover above 4 times; minimum 3)
Obtain management's cash flow forecast; test its
assumptions against past performance and the order book;
read correspondence with the bank on refinancing; watch
events after year end
Climate
Through the estimates
Extreme heat may shorten battery life; a warehouse on a
flood plain; rebate changes can swing sales. First
mandatory climate disclosures from FY2027 (the year
beginning 1 July 2026)
Ask the engineer to allow for heat in the warranty range;
consider flood exposure in inventory values and insurance;
check the climate risks being prepared for FY2027
reporting fit this year's assumptions
Compliance
Lapsed electrical
licences
Some batteries installed by workers whose licences had
lapsed: a breach of safety laws, rebate claims that may
be invalid, and possible penalties
Understand what happened; discuss with management and
the board; test the rebate receivable and any penalty
provision; consider legal advice and any duty to report
ADVANCED AUDIT AND ASSURANCE | M2 | 2.6.3 | STUDENT COMPANION
3
Accounting Ahead | Original study resource | accountingahead.com.au
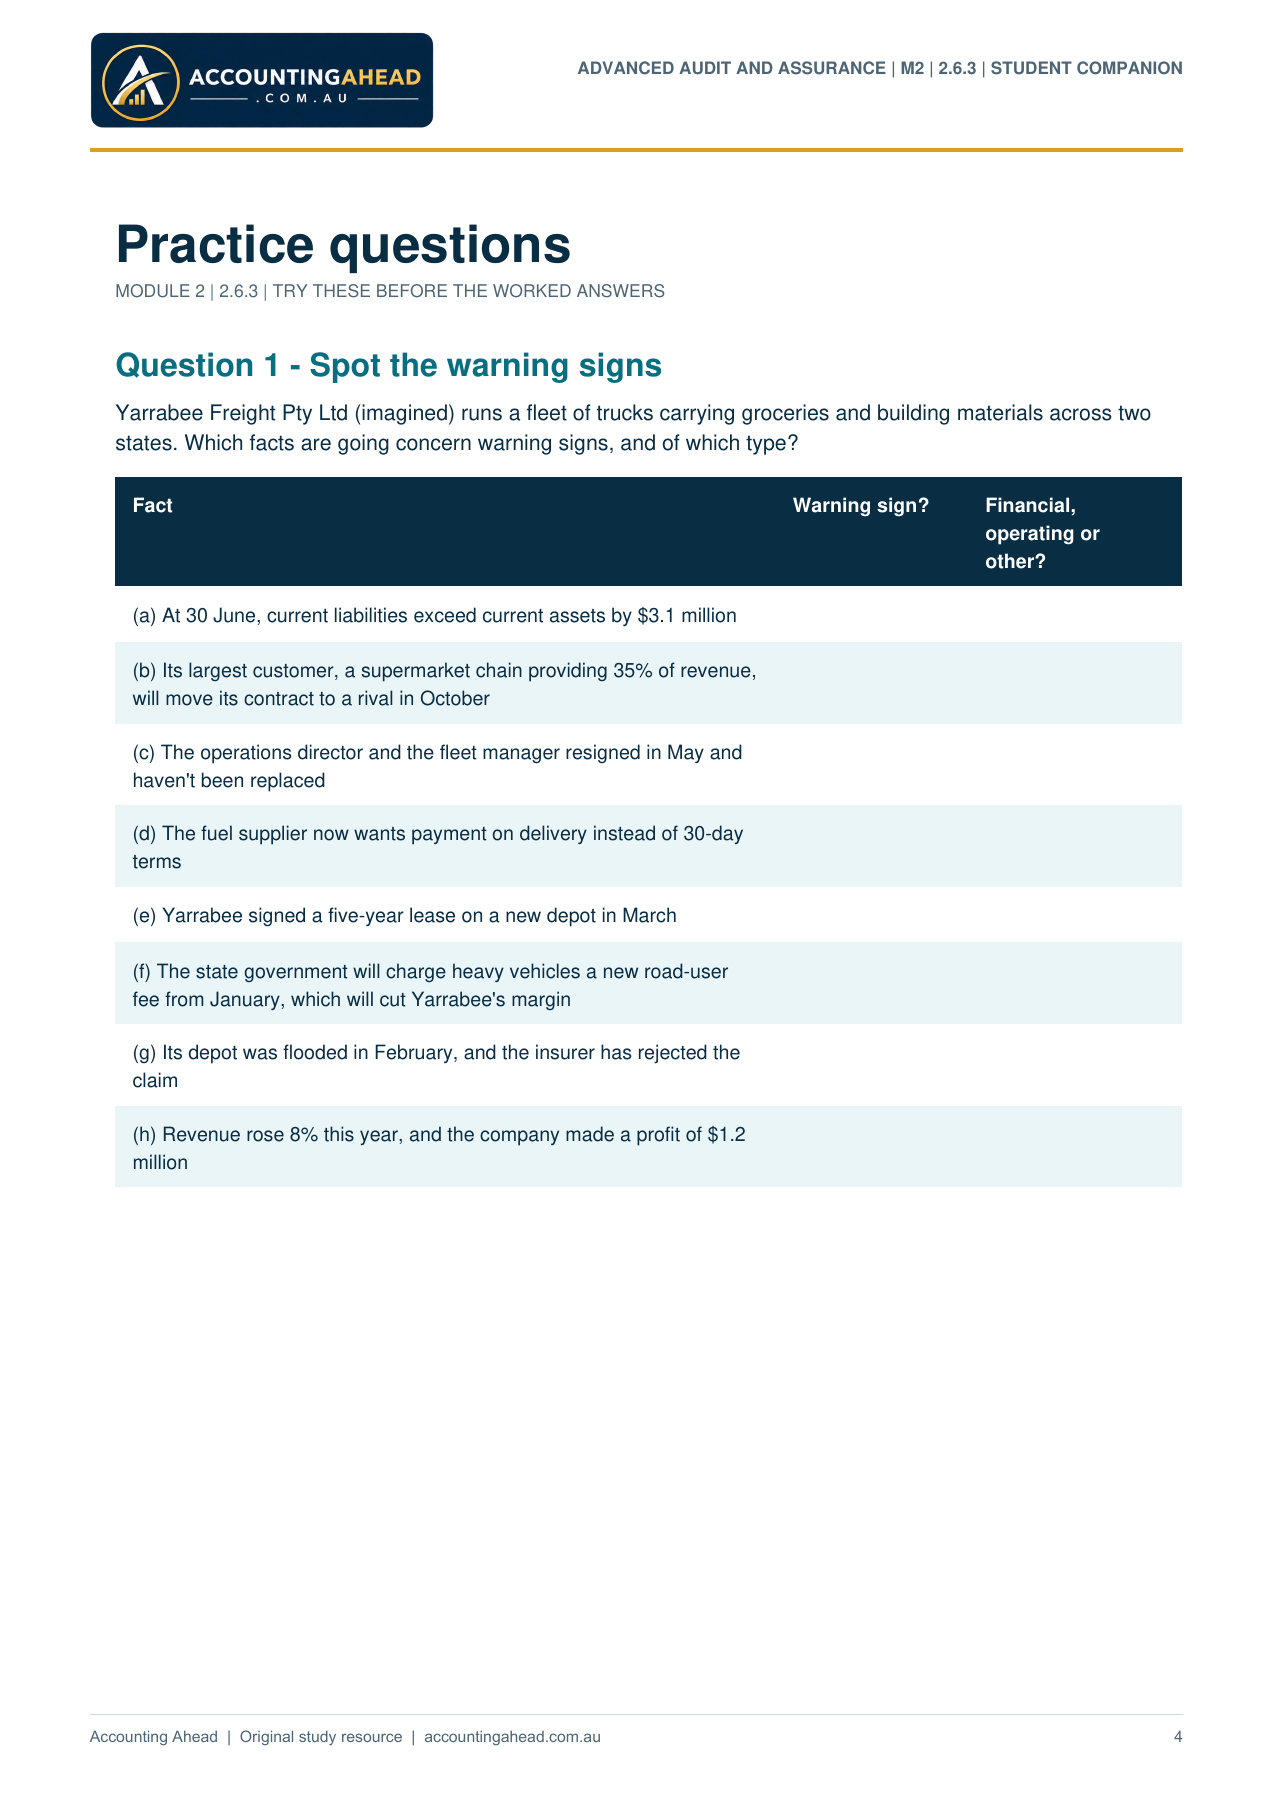
Practice questions
MODULE 2 | 2.6.3 | TRY THESE BEFORE THE WORKED ANSWERS
Question 1 - Spot the warning signs
Yarrabee Freight Pty Ltd (imagined) runs a fleet of trucks carrying groceries and building materials across two
states. Which facts are going concern warning signs, and of which type?
Fact Warning sign? Financial,
operating or
other?
(a) At 30 June, current liabilities exceed current assets by $3.1 million
(b) Its largest customer, a supermarket chain providing 35% of revenue,
will move its contract to a rival in October
(c) The operations director and the fleet manager resigned in May and
haven't been replaced
(d) The fuel supplier now wants payment on delivery instead of 30-day
terms
(e) Yarrabee signed a five-year lease on a new depot in March
(f) The state government will charge heavy vehicles a new road-user
fee from January, which will cut Yarrabee's margin
(g) Its depot was flooded in February, and the insurer has rejected the
claim
(h) Revenue rose 8% this year, and the company made a profit of $1.2
million
ADVANCED AUDIT AND ASSURANCE | M2 | 2.6.3 | STUDENT COMPANION
4
Accounting Ahead | Original study resource | accountingahead.com.au
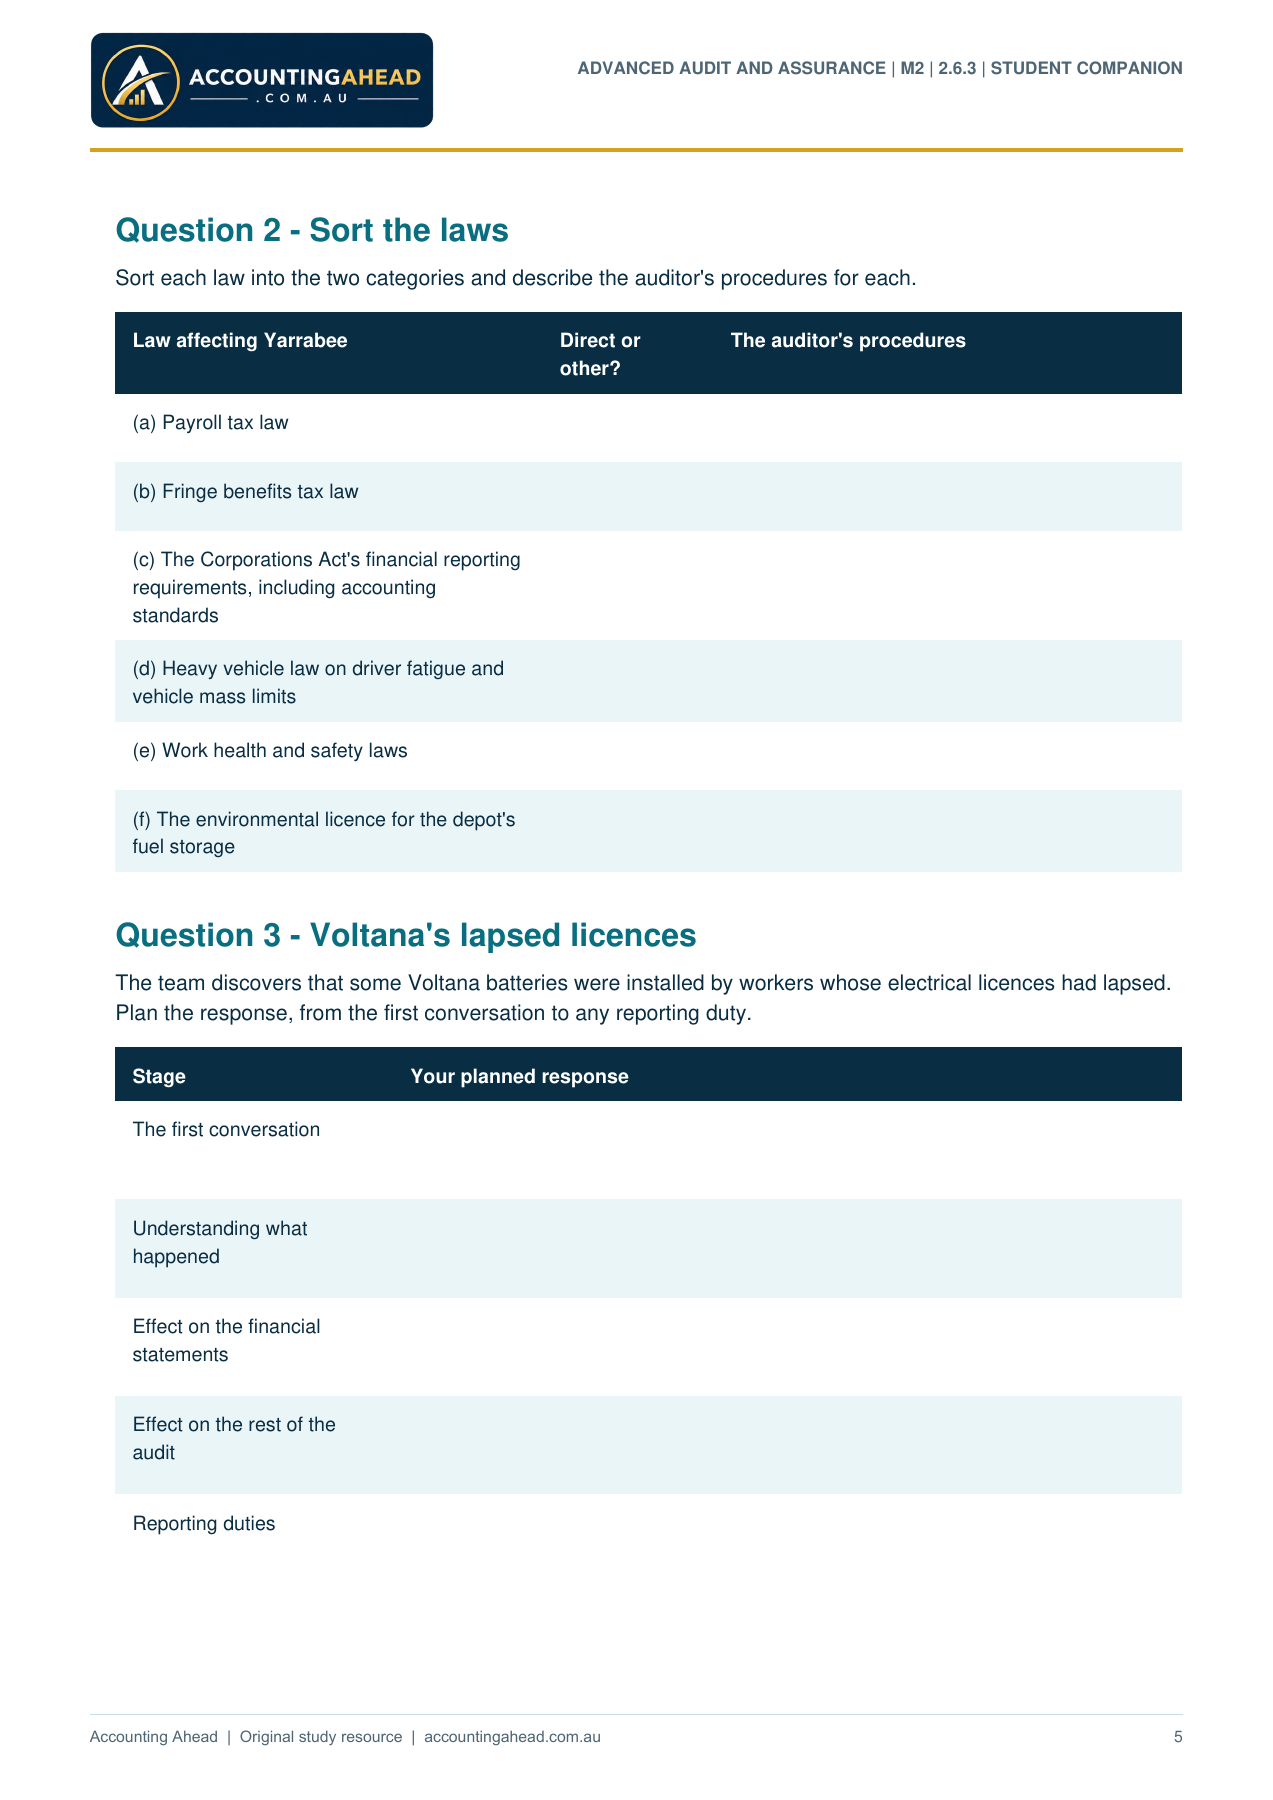
Question 2 - Sort the laws
Sort each law into the two categories and describe the auditor's procedures for each.
Law affecting Yarrabee Direct or
other?
The auditor's procedures
(a) Payroll tax law
(b) Fringe benefits tax law
(c) The Corporations Act's financial reporting
requirements, including accounting
standards
(d) Heavy vehicle law on driver fatigue and
vehicle mass limits
(e) Work health and safety laws
(f) The environmental licence for the depot's
fuel storage
Question 3 - Voltana's lapsed licences
The team discovers that some Voltana batteries were installed by workers whose electrical licences had lapsed.
Plan the response, from the first conversation to any reporting duty.
Stage Your planned response
The first conversation
Understanding what
happened
Effect on the financial
statements
Effect on the rest of the
audit
Reporting duties
ADVANCED AUDIT AND ASSURANCE | M2 | 2.6.3 | STUDENT COMPANION
5
Accounting Ahead | Original study resource | accountingahead.com.au
Worked answers
MODULE 2 | 2.6.3 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
Question 1 - Yarrabee Freight
Weigh them together: (a), (b), (d) and (g) at once would make the risk high.
Warning sign? Why
(a) Yes: financial Net current liabilities
(b) Yes: operating Loss of a key customer worth over a third of revenue
(c) Yes: operating Loss of key managers, with no replacements
(d) Yes: financial Suppliers moving to cash terms signal a loss of trust in its credit
(e) Not on its own A normal commitment, though it adds to fixed costs if revenue falls
(f) Yes: other A change in government policy expected to hurt the business
(g) Yes: other An uninsured catastrophe
(h) No Possibly mitigating, but profit isn't cash: test whether it is turning into cash
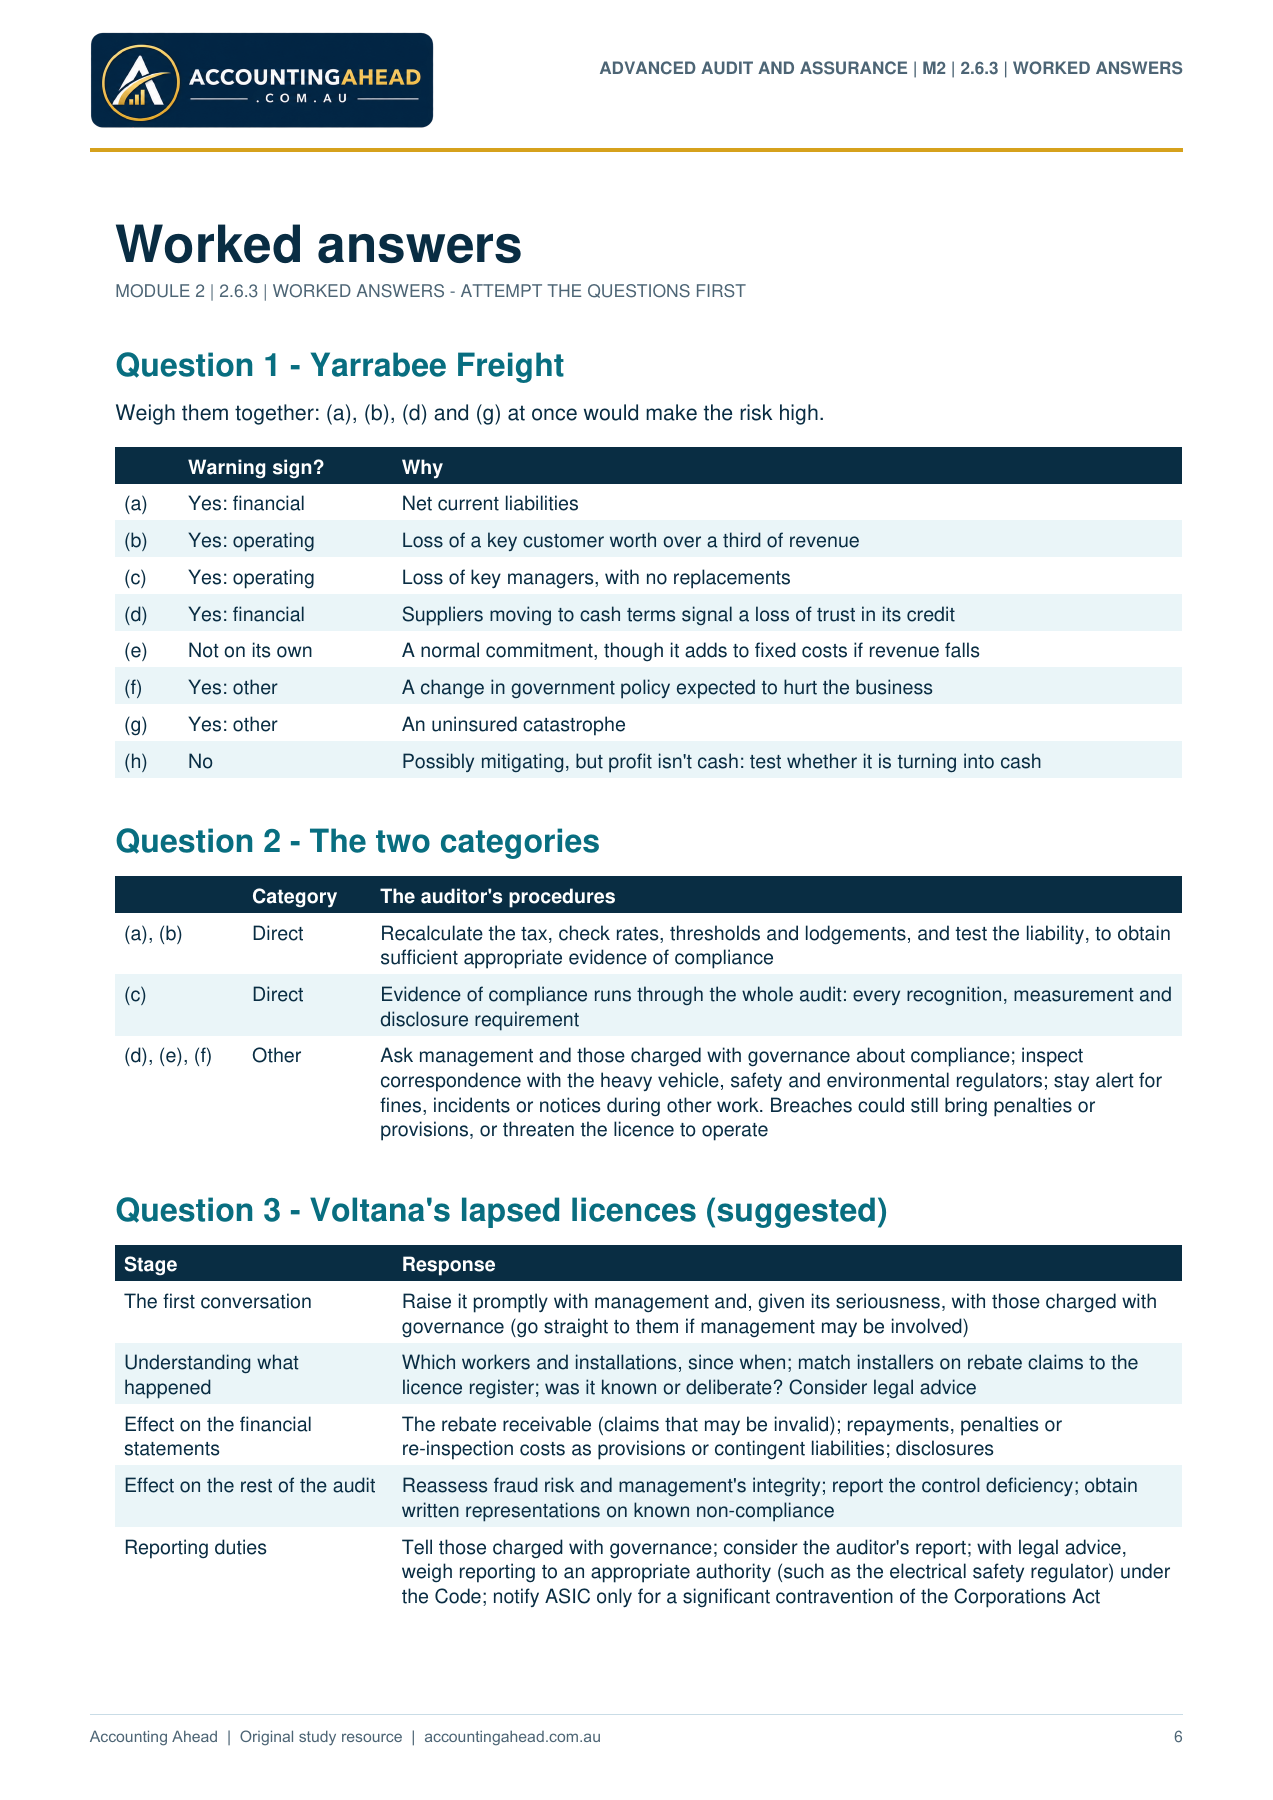
Question 2 - The two categories
Category The auditor's procedures
(a), (b) Direct Recalculate the tax, check rates, thresholds and lodgements, and test the liability, to obtain
sufficient appropriate evidence of compliance
(c) Direct Evidence of compliance runs through the whole audit: every recognition, measurement and
disclosure requirement
(d), (e), (f) Other Ask management and those charged with governance about compliance; inspect
correspondence with the heavy vehicle, safety and environmental regulators; stay alert for
fines, incidents or notices during other work. Breaches could still bring penalties or
provisions, or threaten the licence to operate
Question 3 - Voltana's lapsed licences (suggested)
Stage Response
The first conversation Raise it promptly with management and, given its seriousness, with those charged with
governance (go straight to them if management may be involved)
Understanding what
happened
Which workers and installations, since when; match installers on rebate claims to the
licence register; was it known or deliberate? Consider legal advice
Effect on the financial
statements
The rebate receivable (claims that may be invalid); repayments, penalties or
re-inspection costs as provisions or contingent liabilities; disclosures
Effect on the rest of the audit Reassess fraud risk and management's integrity; report the control deficiency; obtain
written representations on known non-compliance
Reporting duties Tell those charged with governance; consider the auditor's report; with legal advice,
weigh reporting to an appropriate authority (such as the electrical safety regulator) under
the Code; notify ASIC only for a significant contravention of the Corporations Act
ADVANCED AUDIT AND ASSURANCE | M2 | 2.6.3 | WORKED ANSWERS
6