
Audits of specialised areas
Printable study notes, diagrams and practice support for Part 5.1.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
Audits of specialised areas
MODULE 5 | 5.1 | STUDENT COMPANION
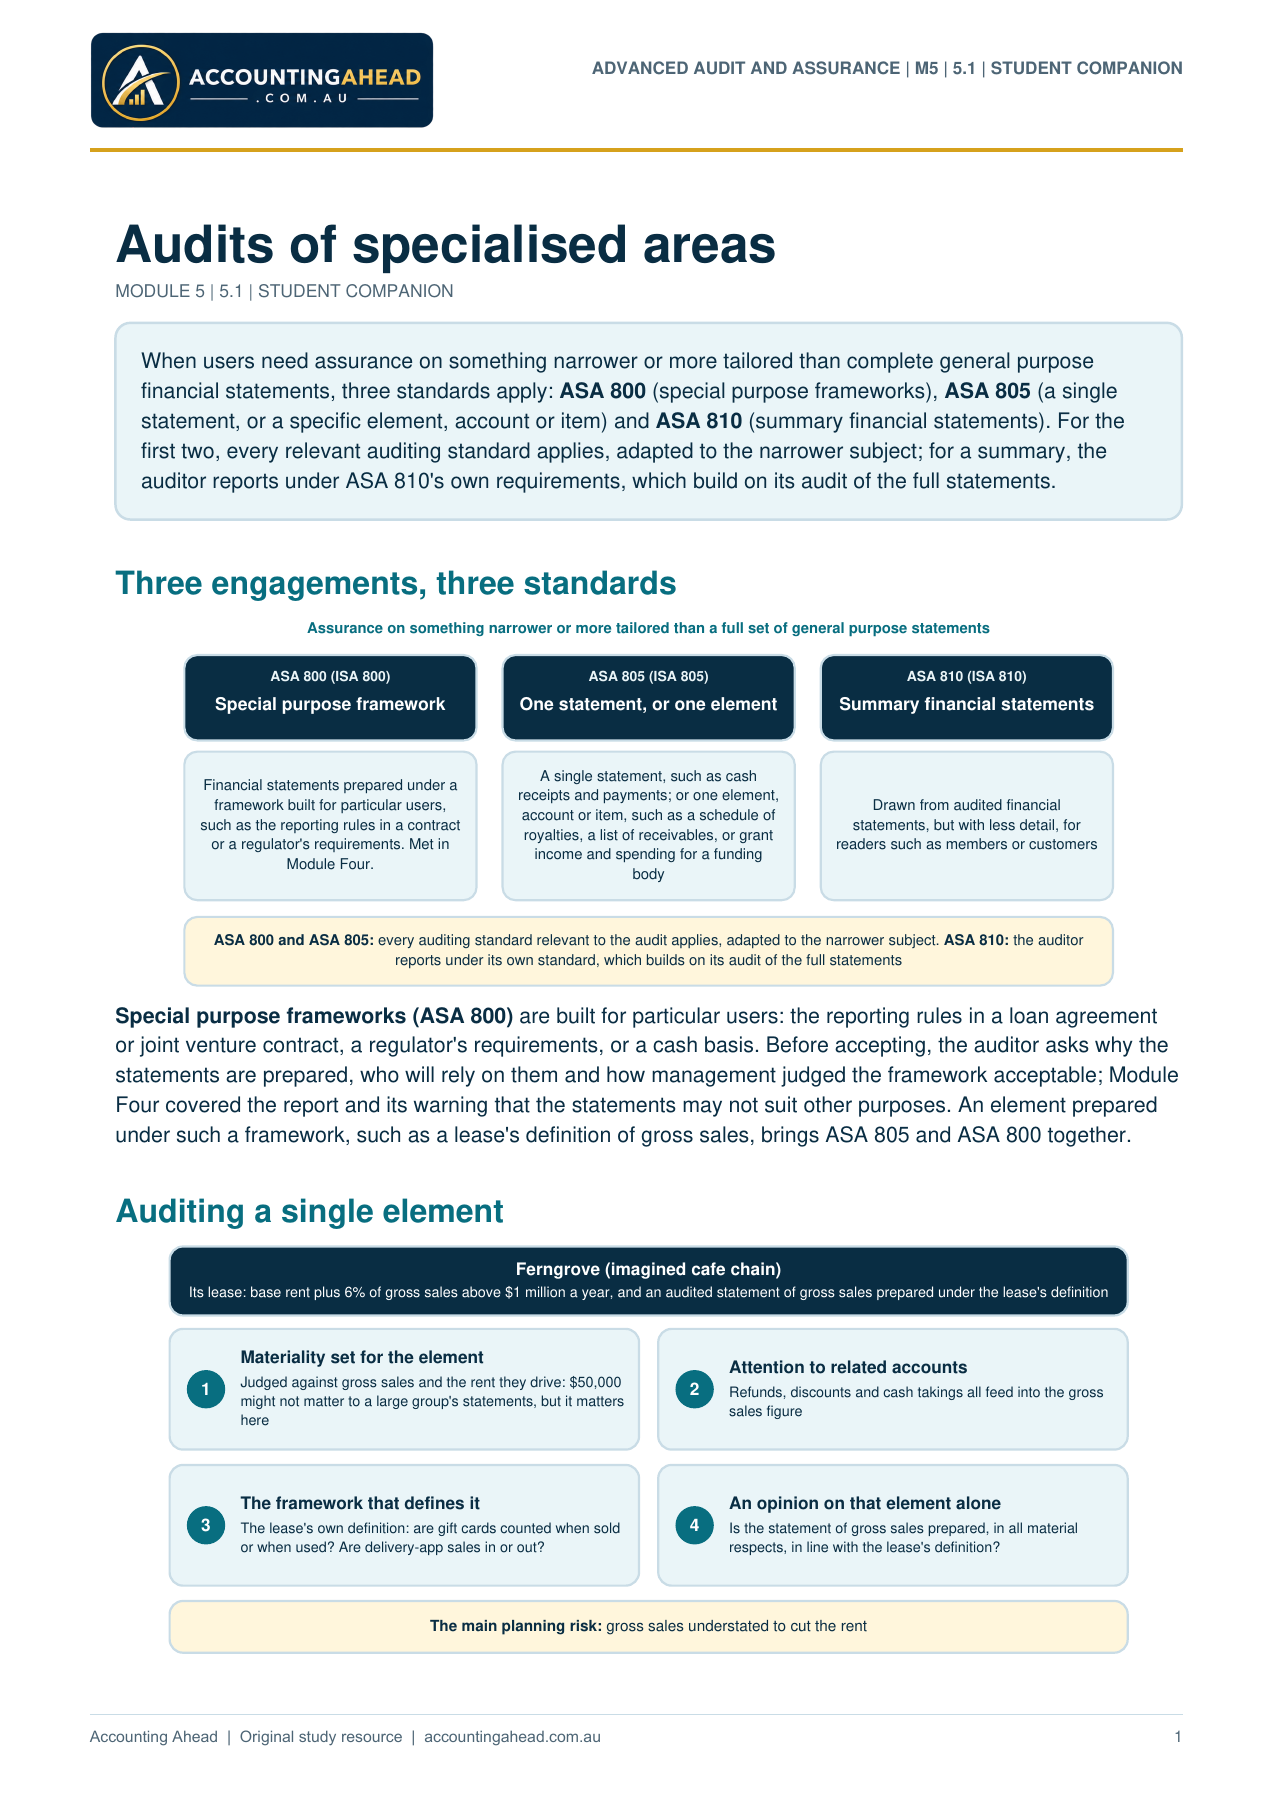
When users need assurance on something narrower or more tailored than complete general purpose
financial statements, three standards apply: ASA 800 (special purpose frameworks), ASA 805 (a single
statement, or a specific element, account or item) and ASA 810 (summary financial statements). For the
first two, every relevant auditing standard applies, adapted to the narrower subject; for a summary, the
auditor reports under ASA 810's own requirements, which build on its audit of the full statements.
Three engagements, three standards
Assurance on something narrower or more tailored than a full set of general purpose statements
ASA 800 (ISA 800)
Special purpose framework
Financial statements prepared under a
framework built for particular users,
such as the reporting rules in a contract
or a regulator's requirements. Met in
Module Four.
ASA 805 (ISA 805)
One statement, or one element
A single statement, such as cash
receipts and payments; or one element,
account or item, such as a schedule of
royalties, a list of receivables, or grant
income and spending for a funding
body
ASA 810 (ISA 810)
Summary financial statements
Drawn from audited financial
statements, but with less detail, for
readers such as members or customers
ASA 800 and ASA 805: every auditing standard relevant to the audit applies, adapted to the narrower subject. ASA 810: the auditor
reports under its own standard, which builds on its audit of the full statements
Special purpose frameworks (ASA 800) are built for particular users: the reporting rules in a loan agreement
or joint venture contract, a regulator's requirements, or a cash basis. Before accepting, the auditor asks why the
statements are prepared, who will rely on them and how management judged the framework acceptable; Module
Four covered the report and its warning that the statements may not suit other purposes. An element prepared
under such a framework, such as a lease's definition of gross sales, brings ASA 805 and ASA 800 together.
Auditing a single element
Ferngrove (imagined cafe chain)
Its lease: base rent plus 6% of gross sales above $1 million a year, and an audited statement of gross sales prepared under the lease's definition
1
Materiality set for the element
Judged against gross sales and the rent they drive: $50,000
might not matter to a large group's statements, but it matters
here
2
Attention to related accounts
Refunds, discounts and cash takings all feed into the gross
sales figure
3
The framework that defines it
The lease's own definition: are gift cards counted when sold
or when used? Are delivery-app sales in or out?
4
An opinion on that element alone
Is the statement of gross sales prepared, in all material
respects, in line with the lease's definition?
The main planning risk: gross sales understated to cut the rent
ADVANCED AUDIT AND ASSURANCE | M5 | 5.1 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
Before accepting an element audit, the auditor checks that the definition can actually be applied the same way
every time; at Ferngrove, that means knowing when gift card sales count and whether delivery-app sales are in.
Materiality is then judged against the element and the people who use it, not the whole entity. A $50,000
misstatement is probably too small to change how investors see a large group, but above Ferngrove's $1 million
threshold it changes the extra rent by $3,000 (6% of $50,000), so the landlord and the tenant both care.
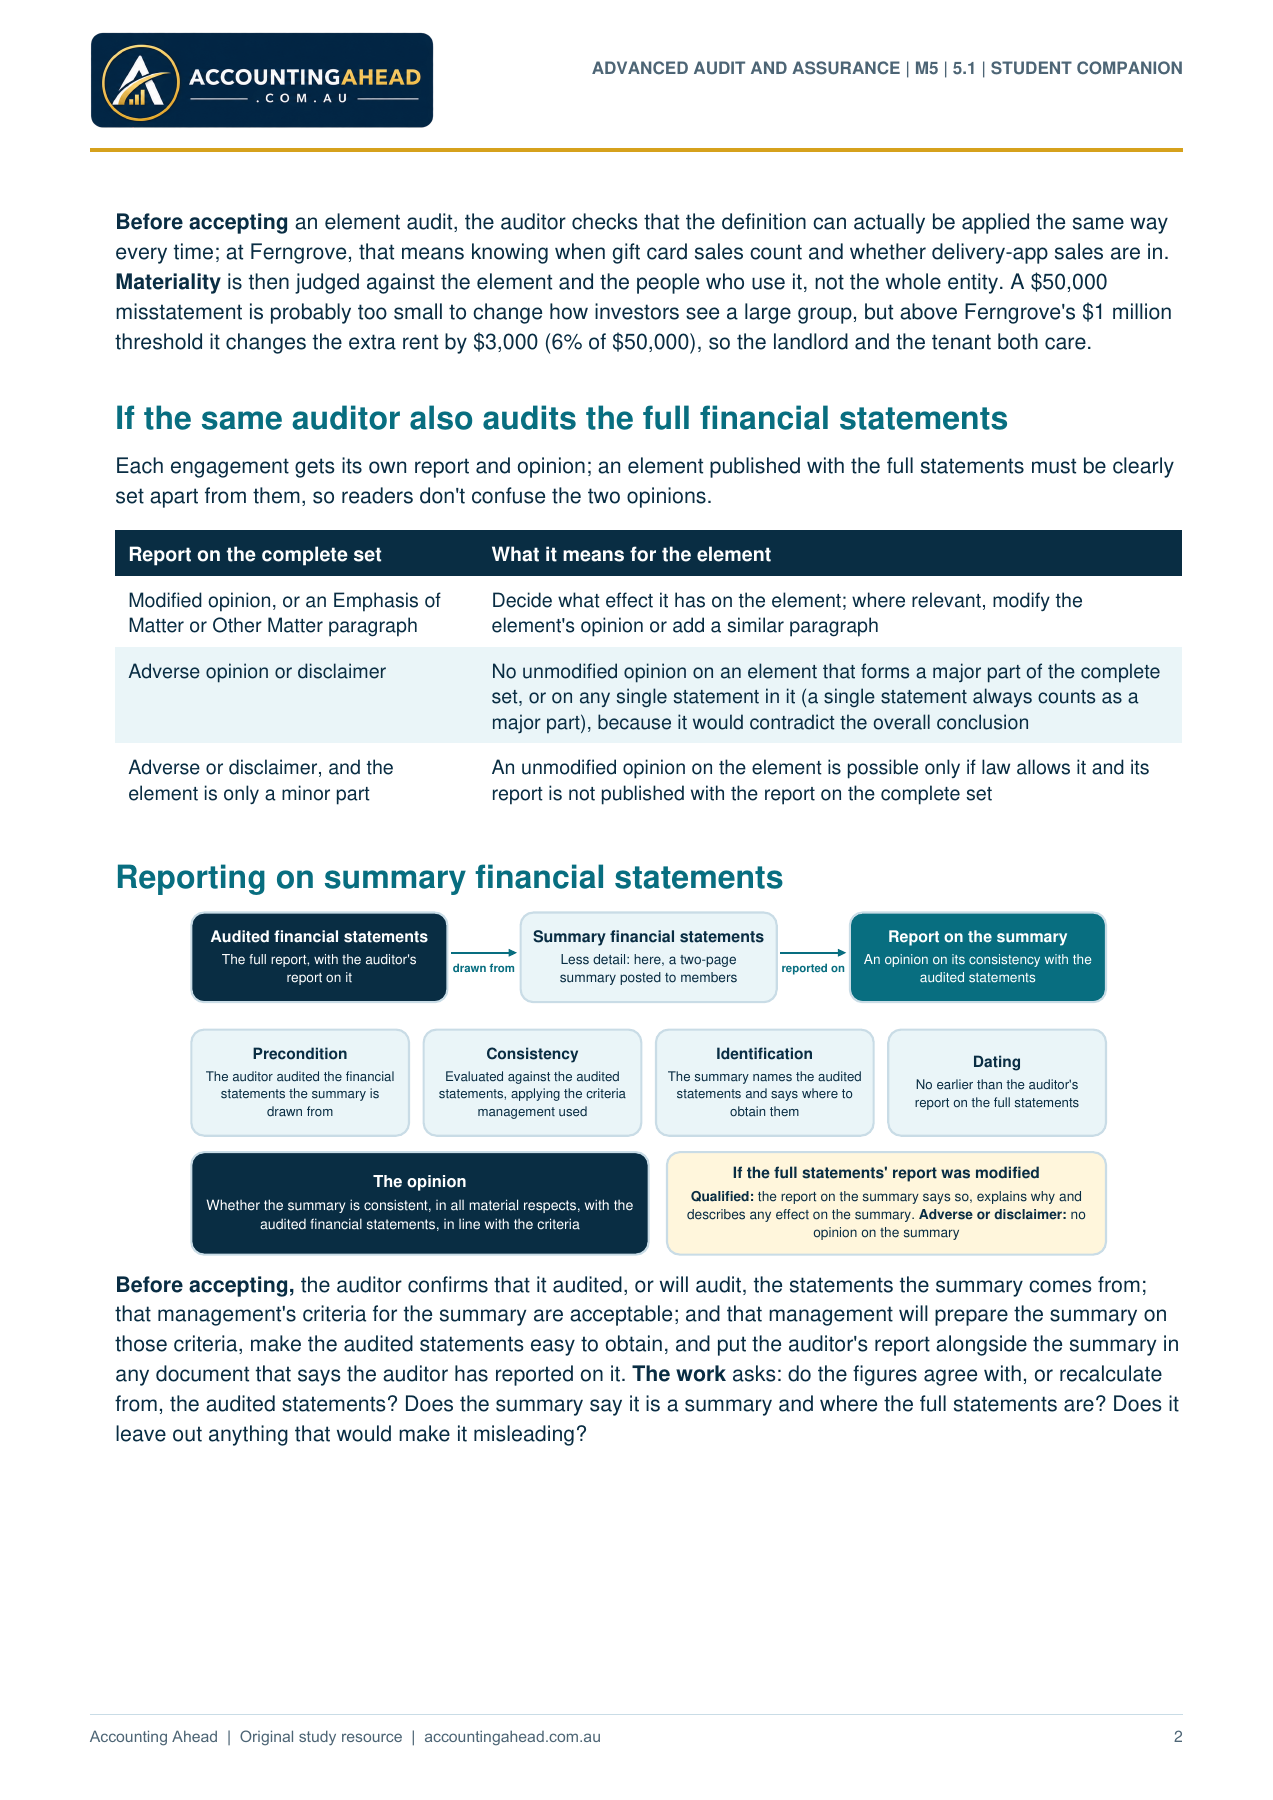
If the same auditor also audits the full financial statements
Each engagement gets its own report and opinion; an element published with the full statements must be clearly
set apart from them, so readers don't confuse the two opinions.
Report on the complete set What it means for the element
Modified opinion, or an Emphasis of
Matter or Other Matter paragraph
Decide what effect it has on the element; where relevant, modify the
element's opinion or add a similar paragraph
Adverse opinion or disclaimer No unmodified opinion on an element that forms a major part of the complete
set, or on any single statement in it (a single statement always counts as a
major part), because it would contradict the overall conclusion
Adverse or disclaimer, and the
element is only a minor part
An unmodified opinion on the element is possible only if law allows it and its
report is not published with the report on the complete set
Reporting on summary financial statements
Audited financial statements
The full report, with the auditor's
report on it drawnfrom
Summary financial statements
Less detail: here, a two-page
summary posted to members reportedon
Report on the summary
An opinion on its consistency with the
audited statements
Precondition
The auditor audited the financial
statements the summary is
drawn from
Consistency
Evaluated against the audited
statements, applying the criteria
management used
Identification
The summary names the audited
statements and says where to
obtain them
Dating
No earlier than the auditor's
report on the full statements
The opinion
Whether the summary is consistent, in all material respects, with the
audited financial statements, in line with the criteria
If the full statements' report was modified
Qualified: the report on the summary says so, explains why and
describes any effect on the summary. Adverse or disclaimer: no
opinion on the summary
Before accepting, the auditor confirms that it audited, or will audit, the statements the summary comes from;
that management's criteria for the summary are acceptable; and that management will prepare the summary on
those criteria, make the audited statements easy to obtain, and put the auditor's report alongside the summary in
any document that says the auditor has reported on it. The work asks: do the figures agree with, or recalculate
from, the audited statements? Does the summary say it is a summary and where the full statements are? Does it
leave out anything that would make it misleading?
ADVANCED AUDIT AND ASSURANCE | M5 | 5.1 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
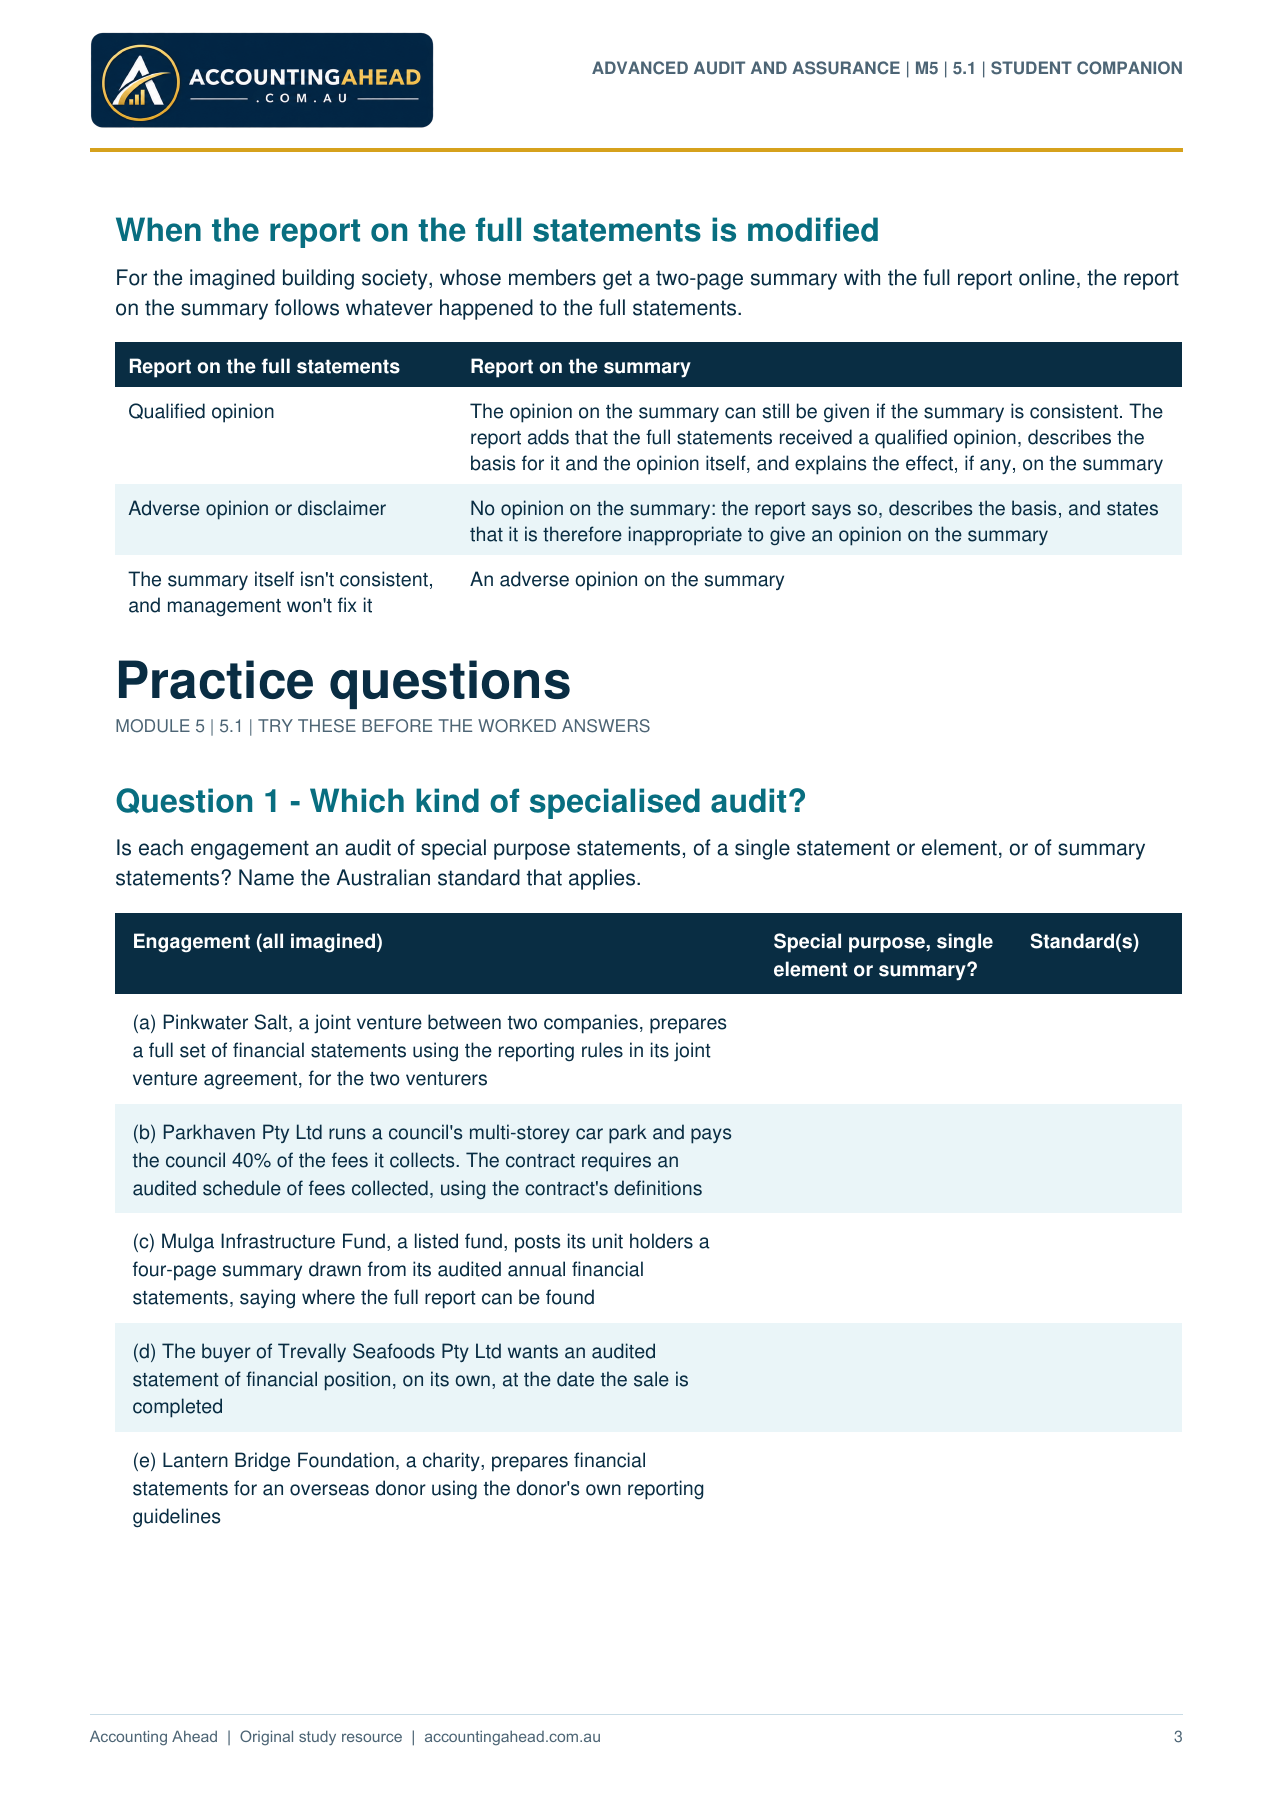
When the report on the full statements is modified
For the imagined building society, whose members get a two-page summary with the full report online, the report
on the summary follows whatever happened to the full statements.
Report on the full statements Report on the summary
Qualified opinion The opinion on the summary can still be given if the summary is consistent. The
report adds that the full statements received a qualified opinion, describes the
basis for it and the opinion itself, and explains the effect, if any, on the summary
Adverse opinion or disclaimer No opinion on the summary: the report says so, describes the basis, and states
that it is therefore inappropriate to give an opinion on the summary
The summary itself isn't consistent,
and management won't fix it
An adverse opinion on the summary
Practice questions
MODULE 5 | 5.1 | TRY THESE BEFORE THE WORKED ANSWERS
Question 1 - Which kind of specialised audit?
Is each engagement an audit of special purpose statements, of a single statement or element, or of summary
statements? Name the Australian standard that applies.
Engagement (all imagined) Special purpose, single
element or summary?
Standard(s)
(a) Pinkwater Salt, a joint venture between two companies, prepares
a full set of financial statements using the reporting rules in its joint
venture agreement, for the two venturers
(b) Parkhaven Pty Ltd runs a council's multi-storey car park and pays
the council 40% of the fees it collects. The contract requires an
audited schedule of fees collected, using the contract's definitions
(c) Mulga Infrastructure Fund, a listed fund, posts its unit holders a
four-page summary drawn from its audited annual financial
statements, saying where the full report can be found
(d) The buyer of Trevally Seafoods Pty Ltd wants an audited
statement of financial position, on its own, at the date the sale is
completed
(e) Lantern Bridge Foundation, a charity, prepares financial
statements for an overseas donor using the donor's own reporting
guidelines
ADVANCED AUDIT AND ASSURANCE | M5 | 5.1 | STUDENT COMPANION
3
Accounting Ahead | Original study resource | accountingahead.com.au
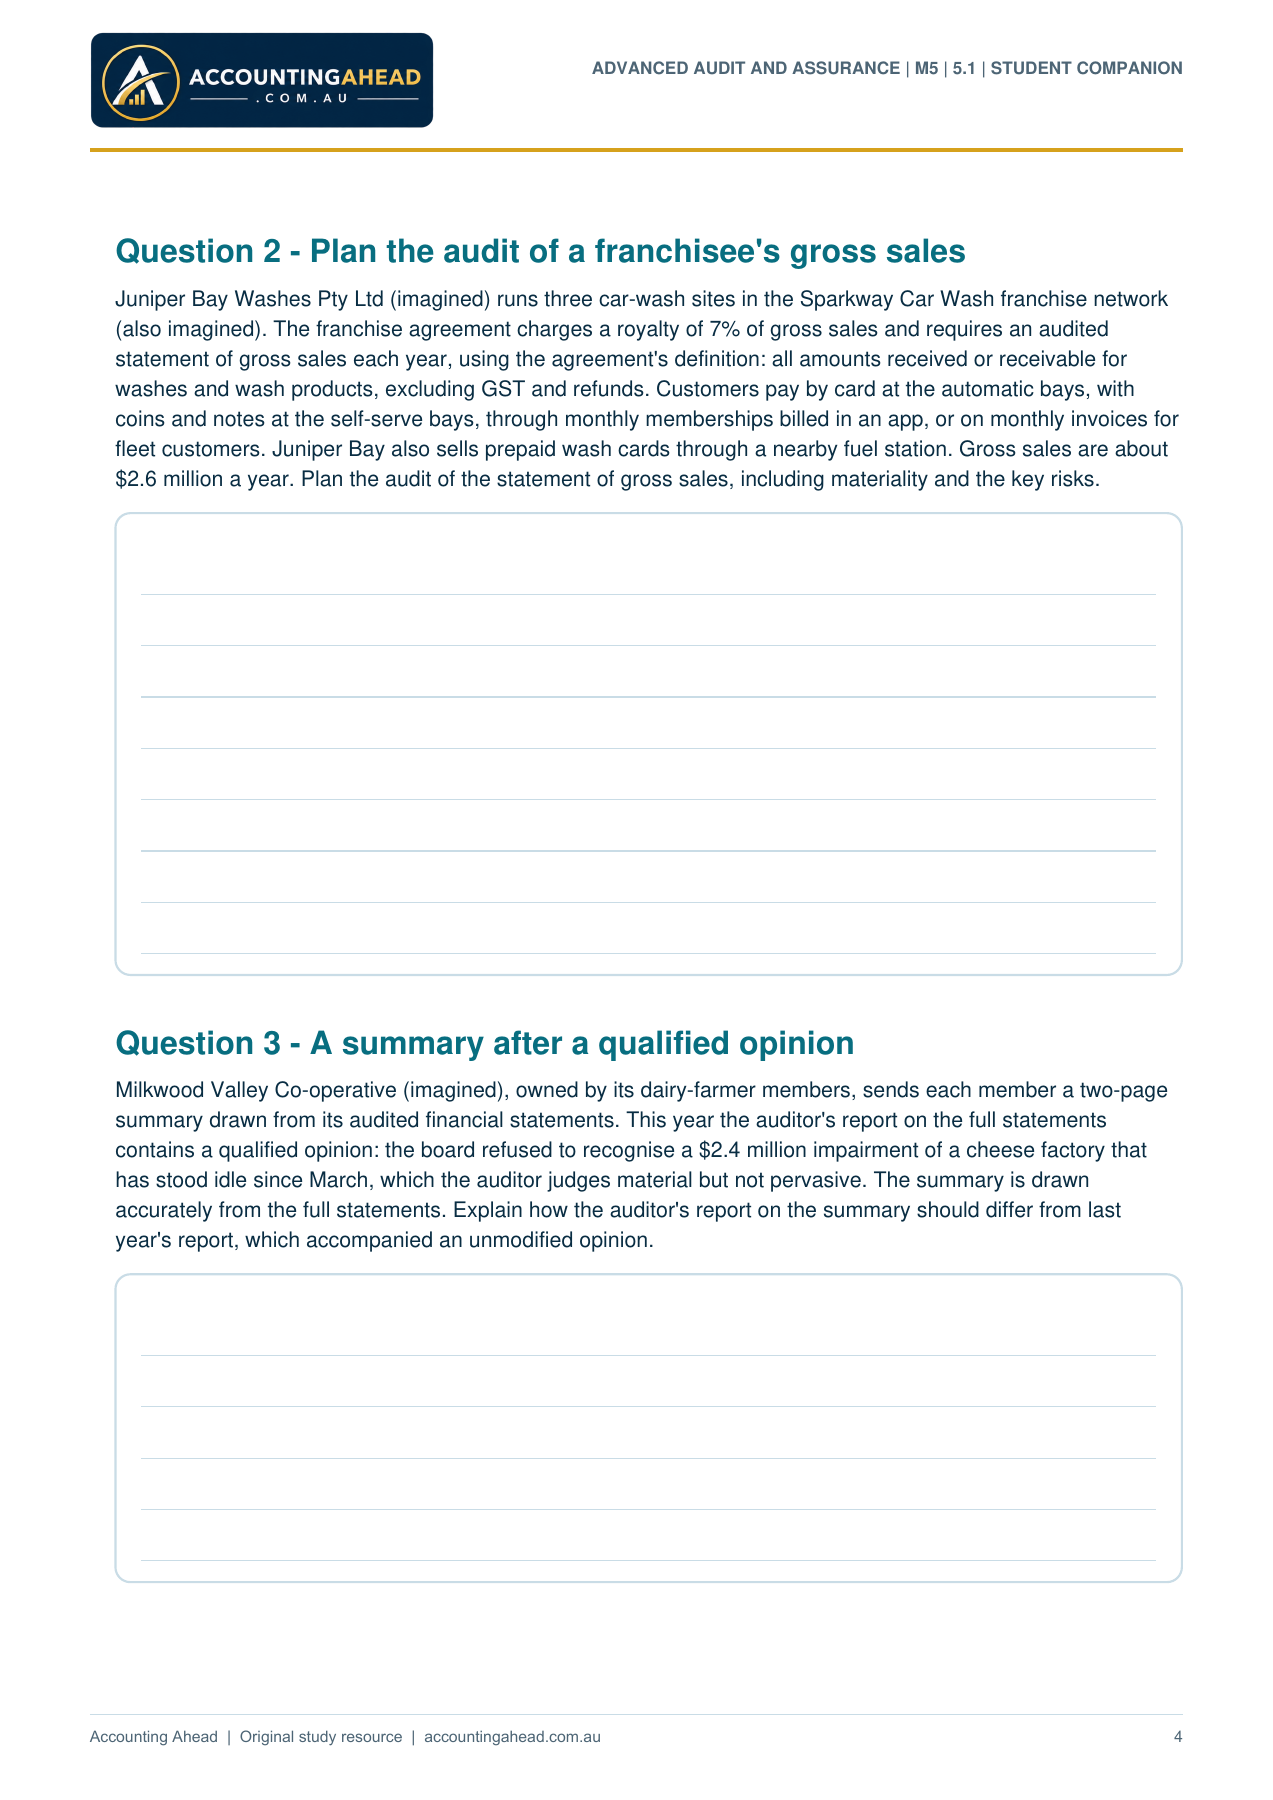
Question 2 - Plan the audit of a franchisee's gross sales
Juniper Bay Washes Pty Ltd (imagined) runs three car-wash sites in the Sparkway Car Wash franchise network
(also imagined). The franchise agreement charges a royalty of 7% of gross sales and requires an audited
statement of gross sales each year, using the agreement's definition: all amounts received or receivable for
washes and wash products, excluding GST and refunds. Customers pay by card at the automatic bays, with
coins and notes at the self-serve bays, through monthly memberships billed in an app, or on monthly invoices for
fleet customers. Juniper Bay also sells prepaid wash cards through a nearby fuel station. Gross sales are about
$2.6 million a year. Plan the audit of the statement of gross sales, including materiality and the key risks.
Question 3 - A summary after a qualified opinion
Milkwood Valley Co-operative (imagined), owned by its dairy-farmer members, sends each member a two-page
summary drawn from its audited financial statements. This year the auditor's report on the full statements
contains a qualified opinion: the board refused to recognise a $2.4 million impairment of a cheese factory that
has stood idle since March, which the auditor judges material but not pervasive. The summary is drawn
accurately from the full statements. Explain how the auditor's report on the summary should differ from last
year's report, which accompanied an unmodified opinion.
ADVANCED AUDIT AND ASSURANCE | M5 | 5.1 | STUDENT COMPANION
4
Accounting Ahead | Original study resource | accountingahead.com.au
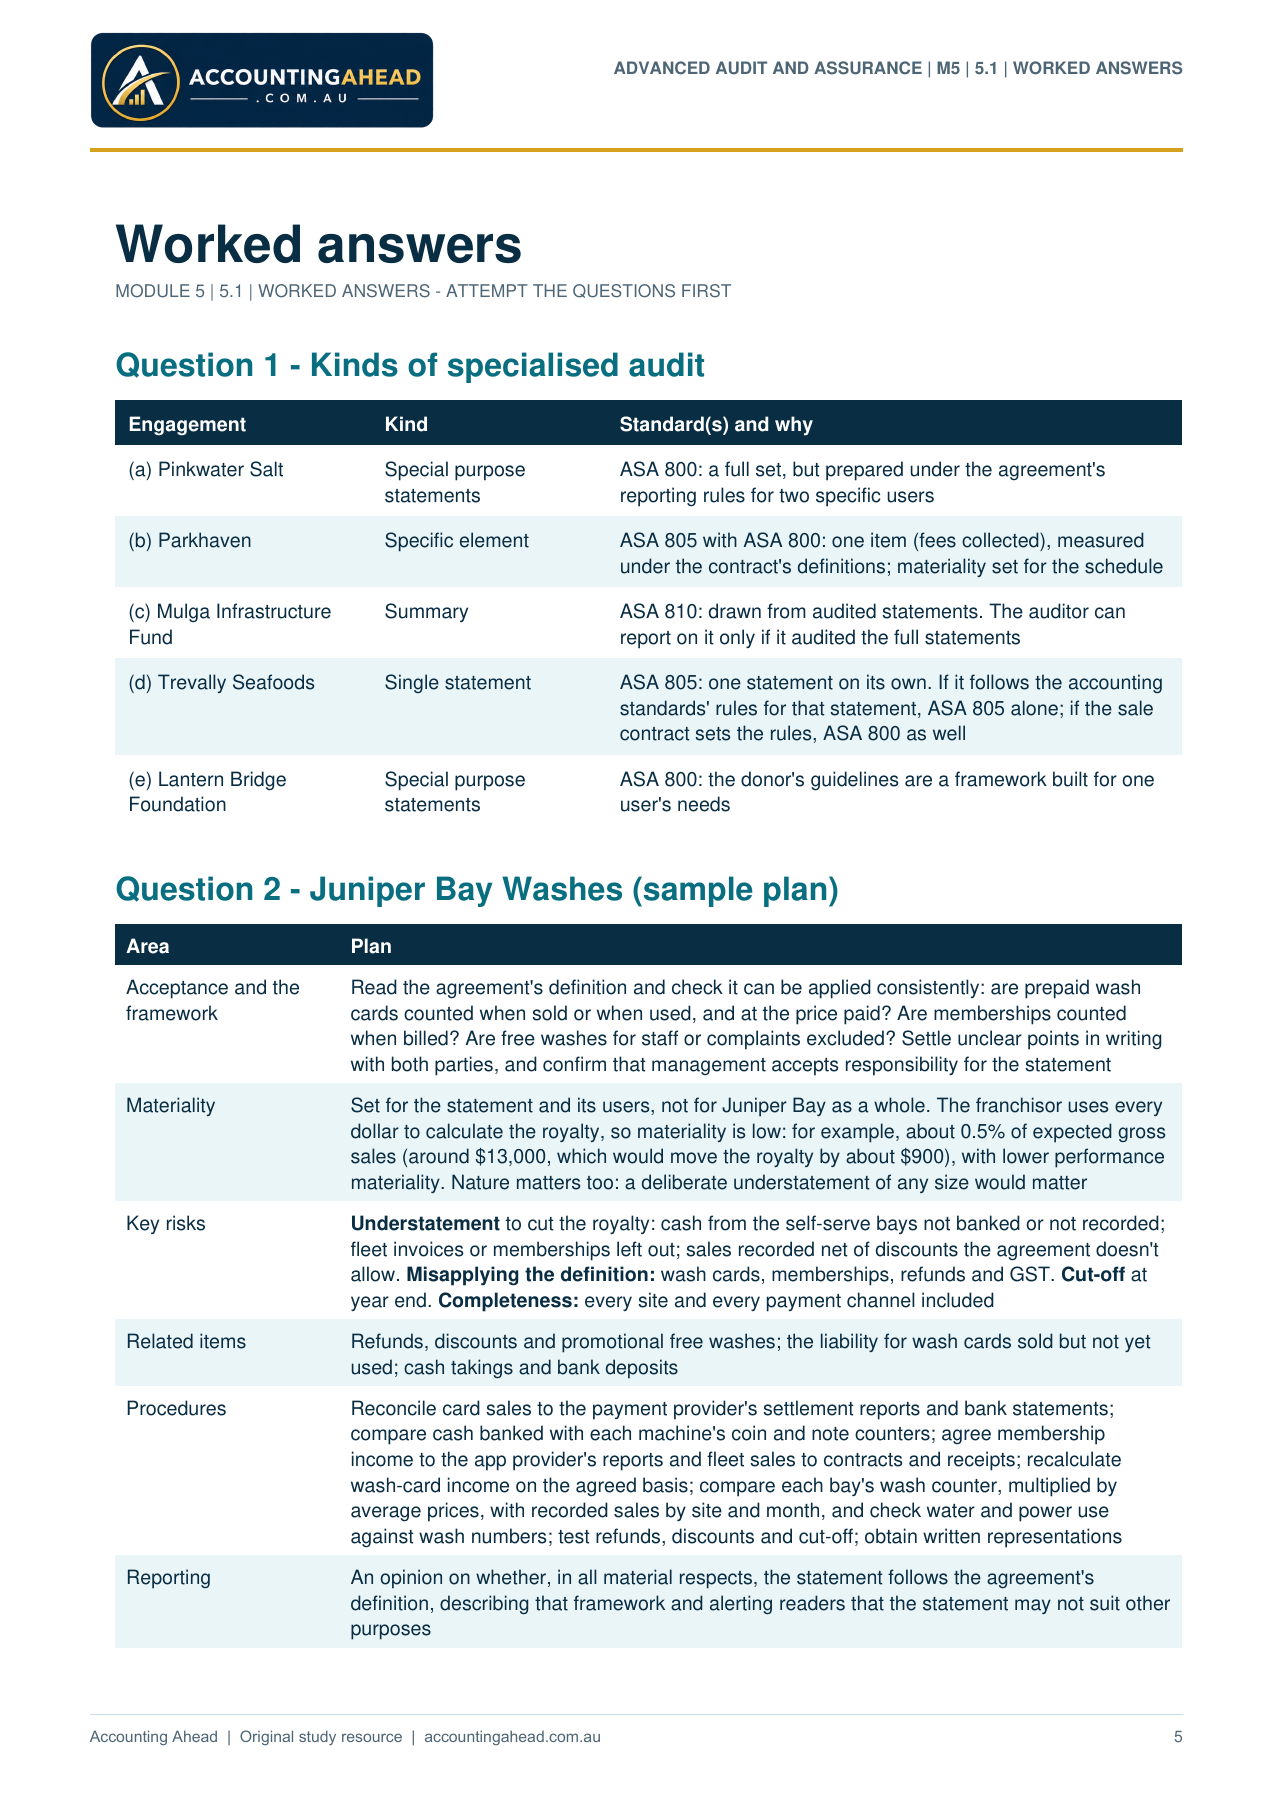
Worked answers
MODULE 5 | 5.1 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
Question 1 - Kinds of specialised audit
Engagement Kind Standard(s) and why
(a) Pinkwater Salt Special purpose
statements
ASA 800: a full set, but prepared under the agreement's
reporting rules for two specific users
(b) Parkhaven Specific element ASA 805 with ASA 800: one item (fees collected), measured
under the contract's definitions; materiality set for the schedule
(c) Mulga Infrastructure
Fund
Summary ASA 810: drawn from audited statements. The auditor can
report on it only if it audited the full statements
(d) Trevally Seafoods Single statement ASA 805: one statement on its own. If it follows the accounting
standards' rules for that statement, ASA 805 alone; if the sale
contract sets the rules, ASA 800 as well
(e) Lantern Bridge
Foundation
Special purpose
statements
ASA 800: the donor's guidelines are a framework built for one
user's needs
Question 2 - Juniper Bay Washes (sample plan)
Area Plan
Acceptance and the
framework
Read the agreement's definition and check it can be applied consistently: are prepaid wash
cards counted when sold or when used, and at the price paid? Are memberships counted
when billed? Are free washes for staff or complaints excluded? Settle unclear points in writing
with both parties, and confirm that management accepts responsibility for the statement
Materiality Set for the statement and its users, not for Juniper Bay as a whole. The franchisor uses every
dollar to calculate the royalty, so materiality is low: for example, about 0.5% of expected gross
sales (around $13,000, which would move the royalty by about $900), with lower performance
materiality. Nature matters too: a deliberate understatement of any size would matter
Key risks Understatement to cut the royalty: cash from the self-serve bays not banked or not recorded;
fleet invoices or memberships left out; sales recorded net of discounts the agreement doesn't
allow. Misapplying the definition: wash cards, memberships, refunds and GST. Cut-off at
year end. Completeness: every site and every payment channel included
Related items Refunds, discounts and promotional free washes; the liability for wash cards sold but not yet
used; cash takings and bank deposits
Procedures Reconcile card sales to the payment provider's settlement reports and bank statements;
compare cash banked with each machine's coin and note counters; agree membership
income to the app provider's reports and fleet sales to contracts and receipts; recalculate
wash-card income on the agreed basis; compare each bay's wash counter, multiplied by
average prices, with recorded sales by site and month, and check water and power use
against wash numbers; test refunds, discounts and cut-off; obtain written representations
Reporting An opinion on whether, in all material respects, the statement follows the agreement's
definition, describing that framework and alerting readers that the statement may not suit other
purposes
ADVANCED AUDIT AND ASSURANCE | M5 | 5.1 | WORKED ANSWERS
5
Accounting Ahead | Original study resource | accountingahead.com.au
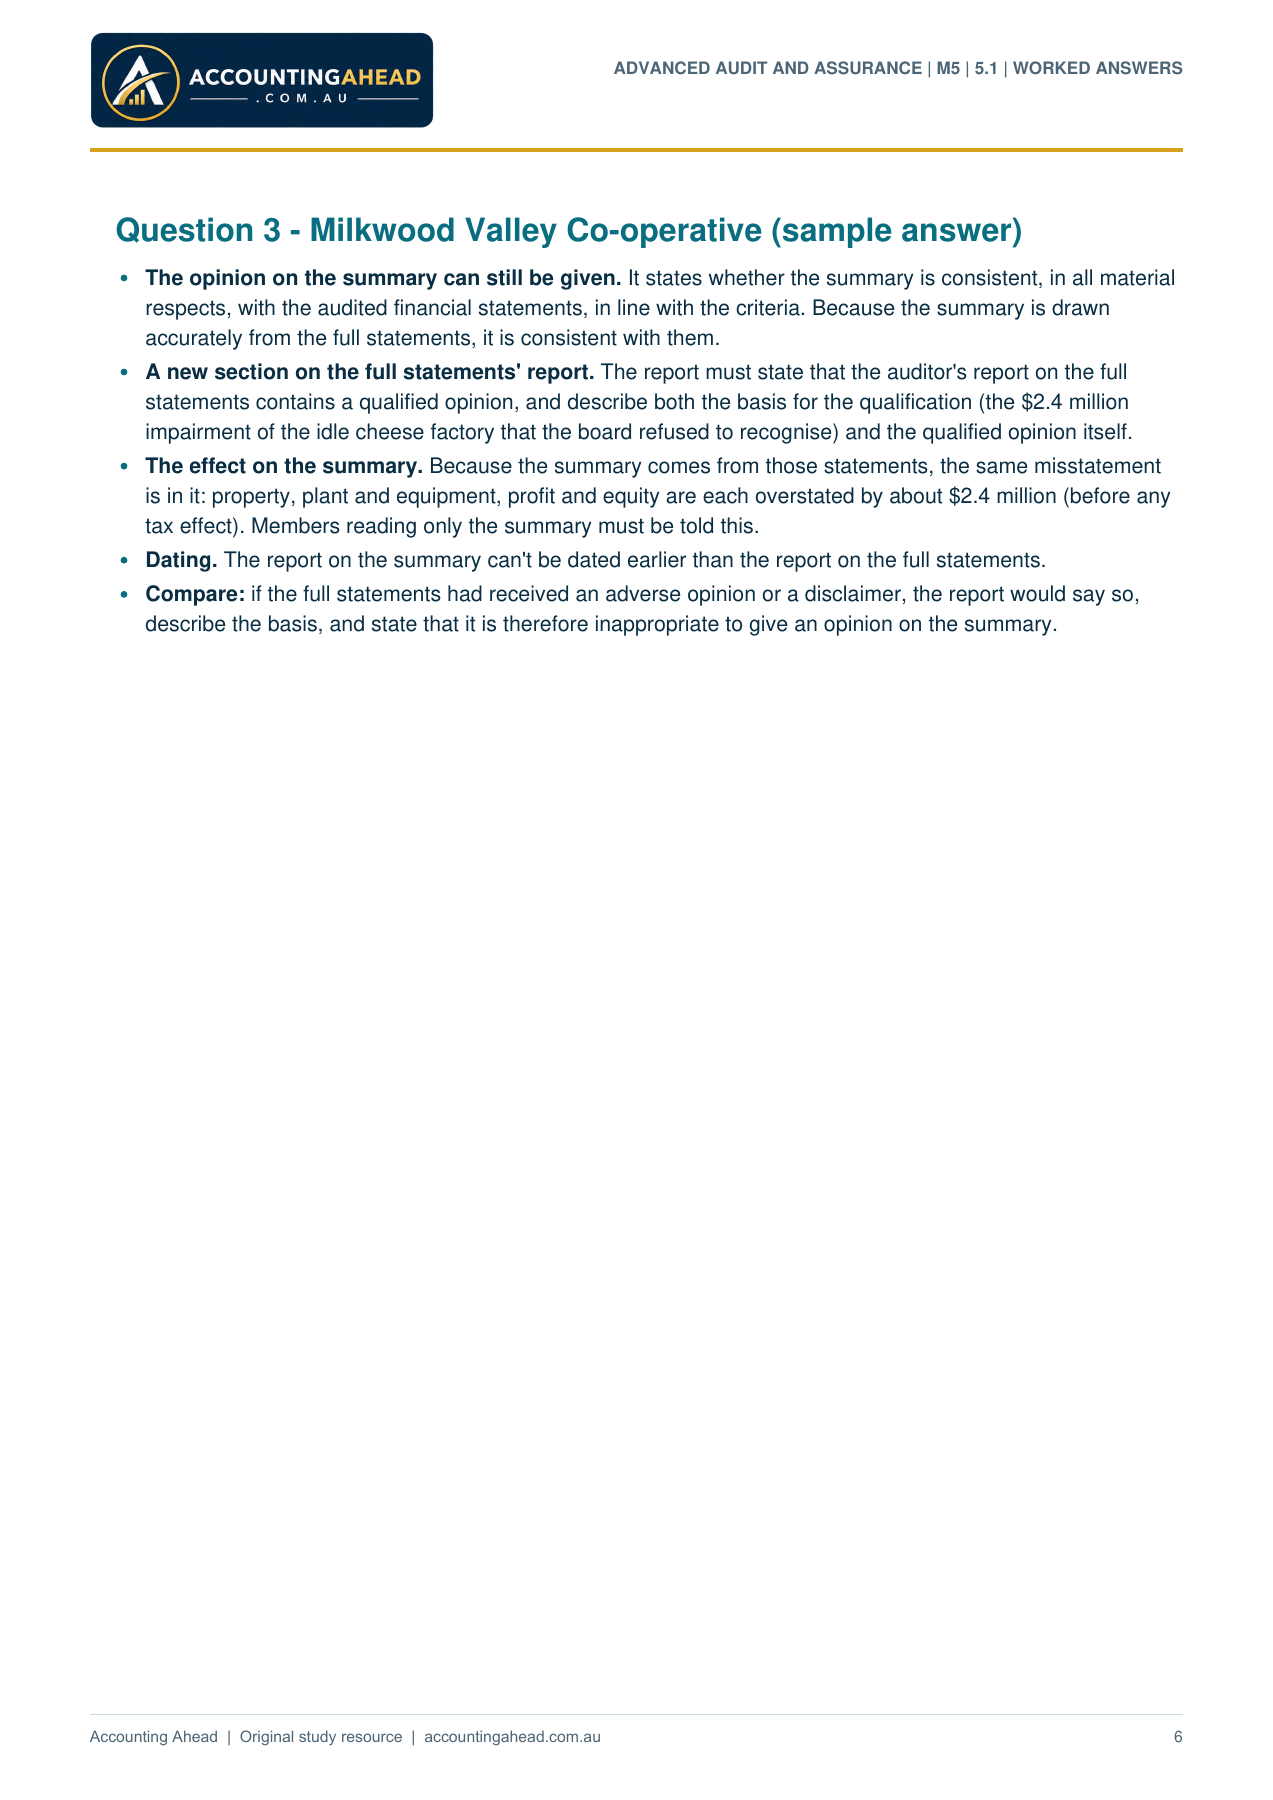
Question 3 - Milkwood Valley Co-operative (sample answer)
The opinion on the summary can still be given. It states whether the summary is consistent, in all material
respects, with the audited financial statements, in line with the criteria. Because the summary is drawn
accurately from the full statements, it is consistent with them.
A new section on the full statements' report. The report must state that the auditor's report on the full
statements contains a qualified opinion, and describe both the basis for the qualification (the $2.4 million
impairment of the idle cheese factory that the board refused to recognise) and the qualified opinion itself.
The effect on the summary. Because the summary comes from those statements, the same misstatement
is in it: property, plant and equipment, profit and equity are each overstated by about $2.4 million (before any
tax effect). Members reading only the summary must be told this.
Dating. The report on the summary can't be dated earlier than the report on the full statements.
Compare: if the full statements had received an adverse opinion or a disclaimer, the report would say so,
describe the basis, and state that it is therefore inappropriate to give an opinion on the summary.
ADVANCED AUDIT AND ASSURANCE | M5 | 5.1 | WORKED ANSWERS
6