
Financial reporting, audit and wider accountability — student companion
Original branded notes, diagrams and practice with worked answers for Part A.4: connect directors’ financial-reporting duties with audit independence, then consider public-sector and charity accountability.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
Reporting, audit and accountability beyond
companies
MODULE 4 | PART A.4 | STUDENT COMPANION
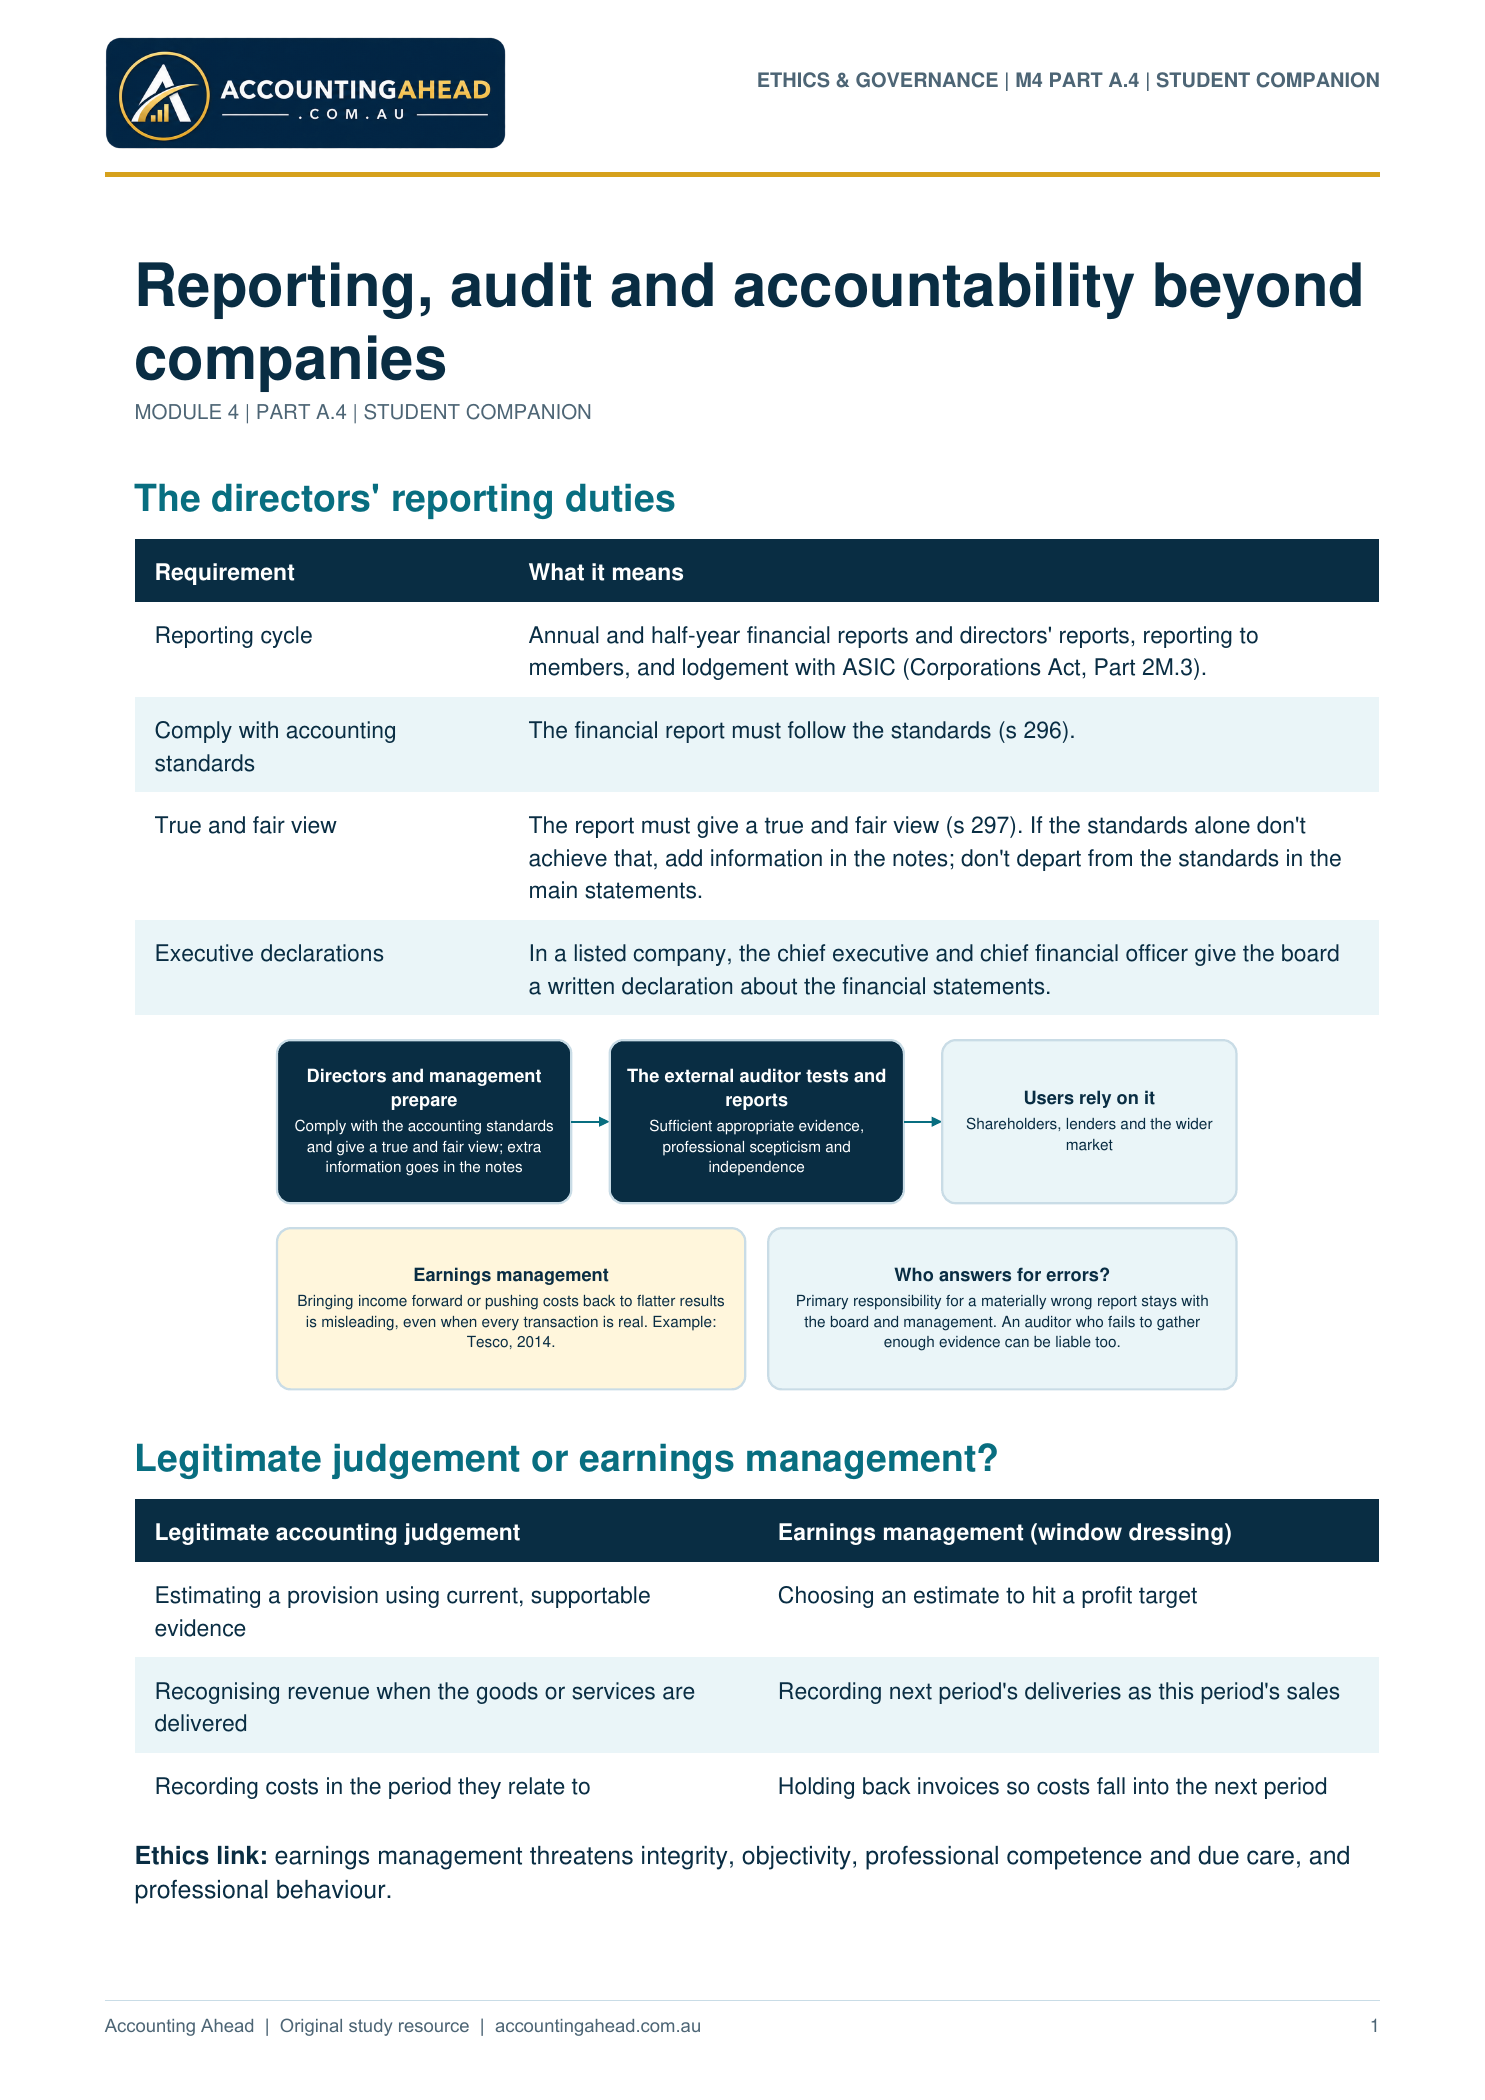
The directors' reporting duties
Requirement What it means
Reporting cycle Annual and half-year financial reports and directors' reports, reporting to
members, and lodgement with ASIC (Corporations Act, Part 2M.3).
Comply with accounting
standards
The financial report must follow the standards (s 296).
True and fair view The report must give a true and fair view (s 297). If the standards alone don't
achieve that, add information in the notes; don't depart from the standards in the
main statements.
Executive declarations In a listed company, the chief executive and chief financial officer give the board
a written declaration about the financial statements.
Directors and management
prepare
Comply with the accounting standards
and give a true and fair view; extra
information goes in the notes
The external auditor tests and
reports
Sufficient appropriate evidence,
professional scepticism and
independence
Users rely on it
Shareholders, lenders and the wider
market
Earnings management
Bringing income forward or pushing costs back to flatter results
is misleading, even when every transaction is real. Example:
Tesco, 2014.
Who answers for errors?
Primary responsibility for a materially wrong report stays with
the board and management. An auditor who fails to gather
enough evidence can be liable too.
Legitimate judgement or earnings management?
Legitimate accounting judgement Earnings management (window dressing)
Estimating a provision using current, supportable
evidence
Choosing an estimate to hit a profit target
Recognising revenue when the goods or services are
delivered
Recording next period's deliveries as this period's sales
Recording costs in the period they relate to Holding back invoices so costs fall into the next period
Ethics link: earnings management threatens integrity, objectivity, professional competence and due care, and
professional behaviour.
ETHICS & GOVERNANCE | M4 PART A.4 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
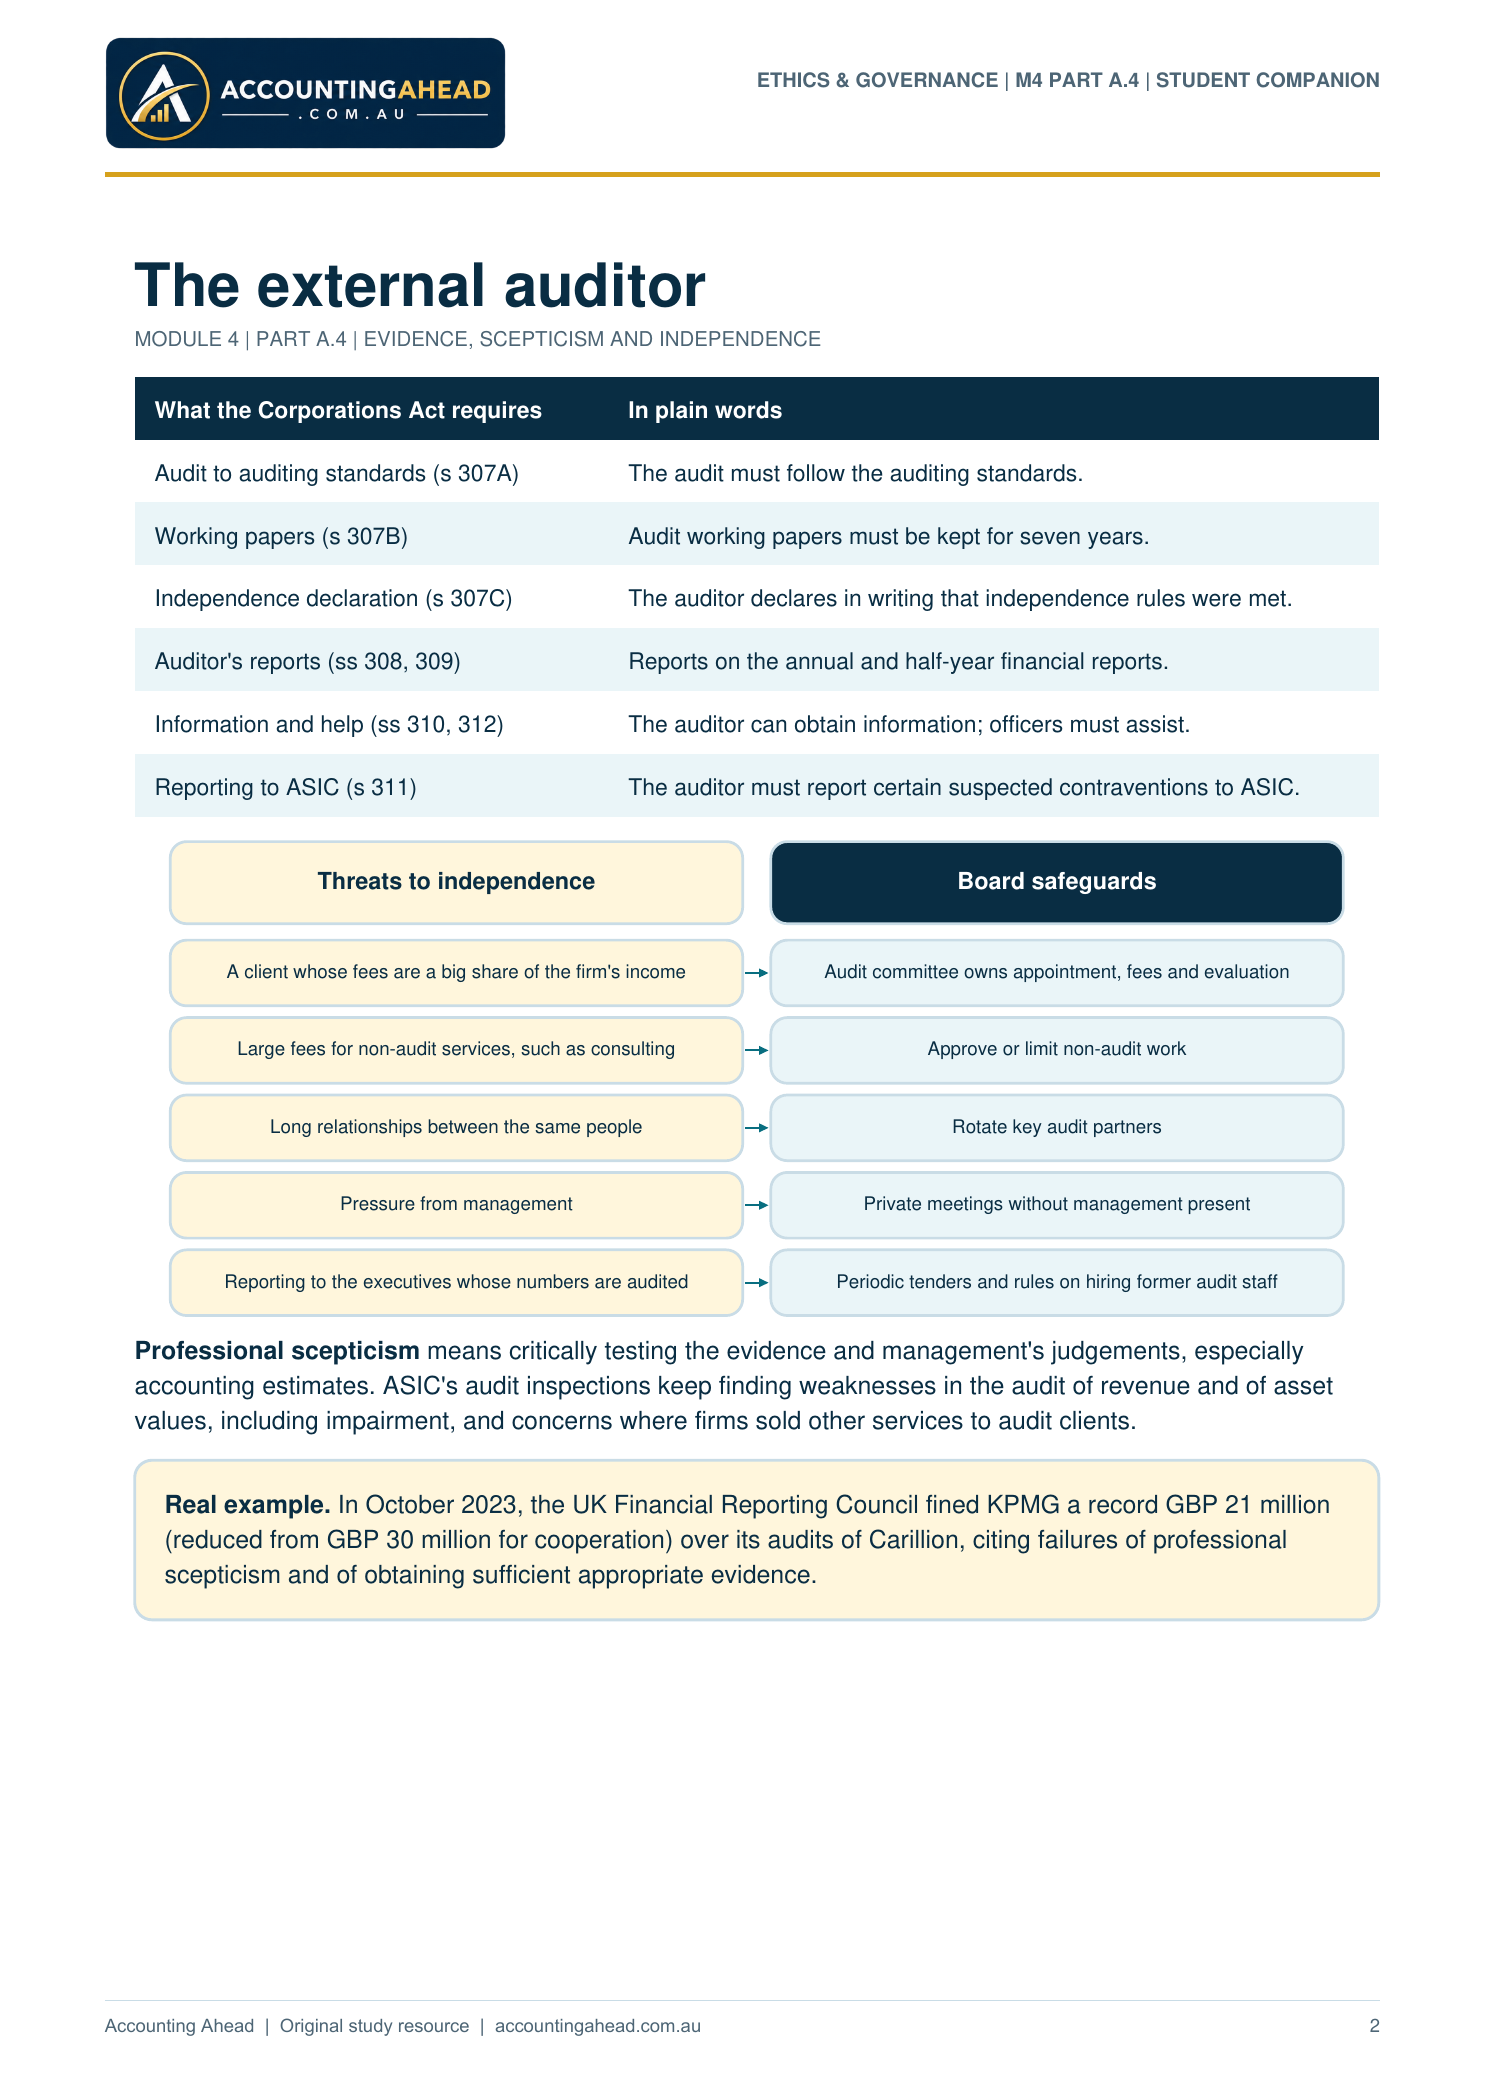
The external auditor
MODULE 4 | PART A.4 | EVIDENCE, SCEPTICISM AND INDEPENDENCE
What the Corporations Act requires In plain words
Audit to auditing standards (s 307A) The audit must follow the auditing standards.
Working papers (s 307B) Audit working papers must be kept for seven years.
Independence declaration (s 307C) The auditor declares in writing that independence rules were met.
Auditor's reports (ss 308, 309) Reports on the annual and half-year financial reports.
Information and help (ss 310, 312) The auditor can obtain information; officers must assist.
Reporting to ASIC (s 311) The auditor must report certain suspected contraventions to ASIC.
Threats to independence Board safeguards
A client whose fees are a big share of the firm's income Audit committee owns appointment, fees and evaluation
Large fees for non-audit services, such as consulting Approve or limit non-audit work
Long relationships between the same people Rotate key audit partners
Pressure from management Private meetings without management present
Reporting to the executives whose numbers are audited Periodic tenders and rules on hiring former audit staff
Professional scepticism means critically testing the evidence and management's judgements, especially
accounting estimates. ASIC's audit inspections keep finding weaknesses in the audit of revenue and of asset
values, including impairment, and concerns where firms sold other services to audit clients.
Real example. In October 2023, the UK Financial Reporting Council fined KPMG a record GBP 21 million
(reduced from GBP 30 million for cooperation) over its audits of Carillion, citing failures of professional
scepticism and of obtaining sufficient appropriate evidence.
ETHICS & GOVERNANCE | M4 PART A.4 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
Widening responsibilities
MODULE 4 | PART A.4 | SUSTAINABILITY REPORTING, GOVERNMENT BODIES AND CHARITIES
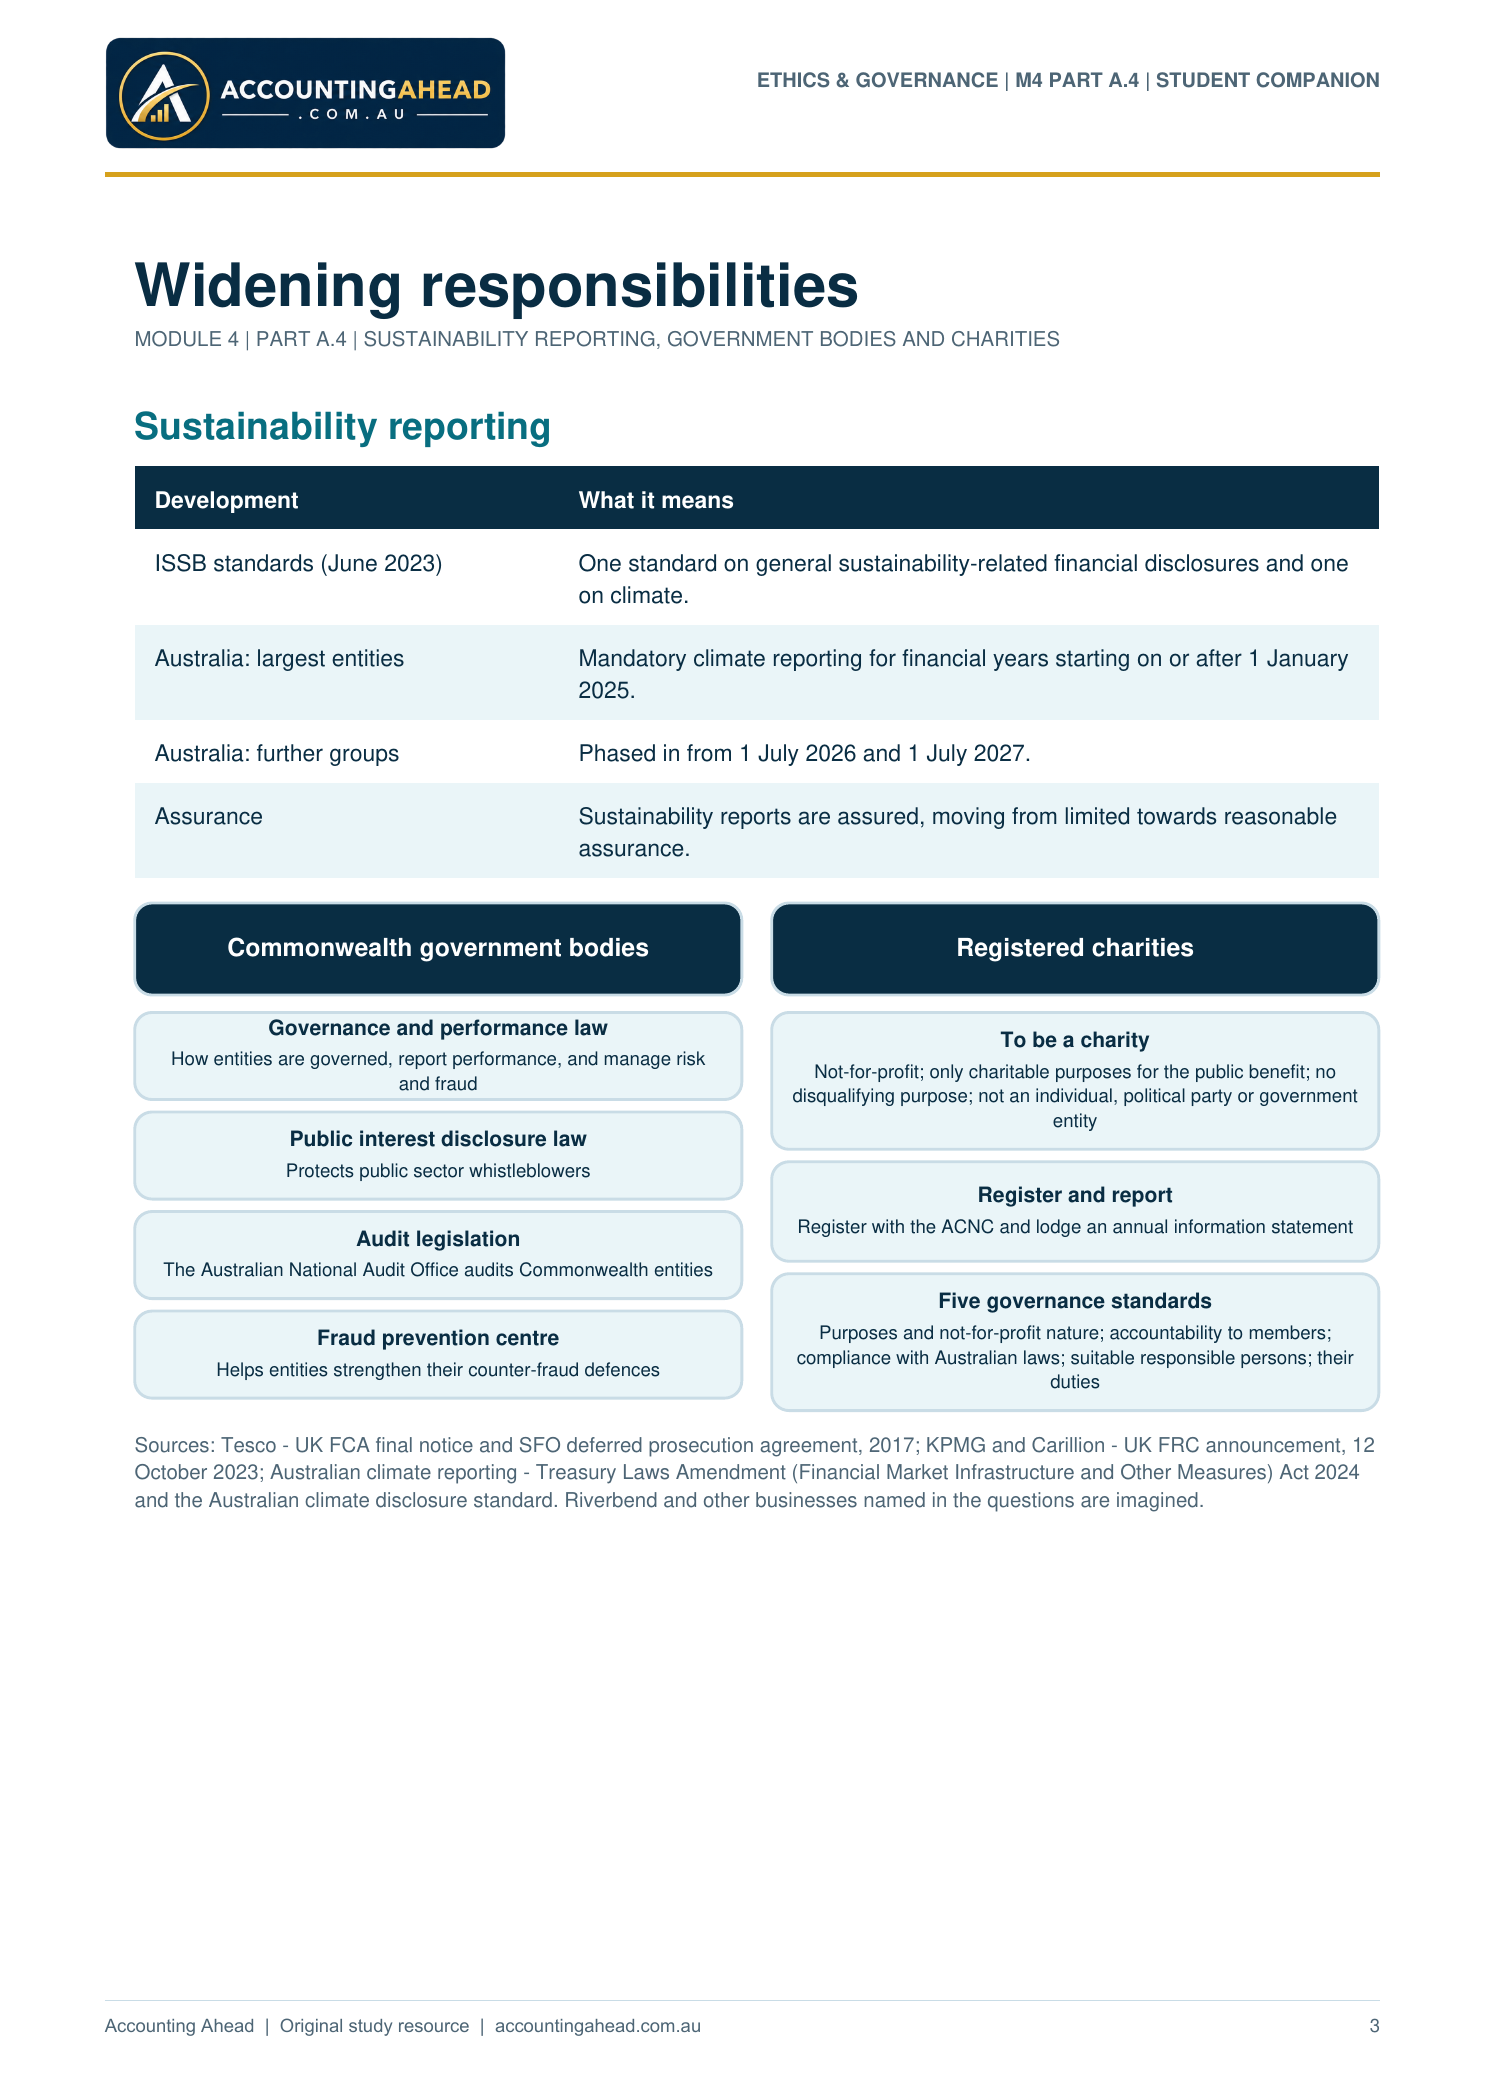
Sustainability reporting
Development What it means
ISSB standards (June 2023) One standard on general sustainability-related financial disclosures and one
on climate.
Australia: largest entities Mandatory climate reporting for financial years starting on or after 1 January
2025.
Australia: further groups Phased in from 1 July 2026 and 1 July 2027.
Assurance Sustainability reports are assured, moving from limited towards reasonable
assurance.
Commonwealth government bodies Registered charities
Governance and performance law
How entities are governed, report performance, and manage risk
and fraud
Public interest disclosure law
Protects public sector whistleblowers
Audit legislation
The Australian National Audit Office audits Commonwealth entities
Fraud prevention centre
Helps entities strengthen their counter-fraud defences
To be a charity
Not-for-profit; only charitable purposes for the public benefit; no
disqualifying purpose; not an individual, political party or government
entity
Register and report
Register with the ACNC and lodge an annual information statement
Five governance standards
Purposes and not-for-profit nature; accountability to members;
compliance with Australian laws; suitable responsible persons; their
duties
Sources: Tesco - UK FCA final notice and SFO deferred prosecution agreement, 2017; KPMG and Carillion - UK FRC announcement, 12
October 2023; Australian climate reporting - Treasury Laws Amendment (Financial Market Infrastructure and Other Measures) Act 2024
and the Australian climate disclosure standard. Riverbend and other businesses named in the questions are imagined.
ETHICS & GOVERNANCE | M4 PART A.4 | STUDENT COMPANION
3
Accounting Ahead | Original study resource | accountingahead.com.au
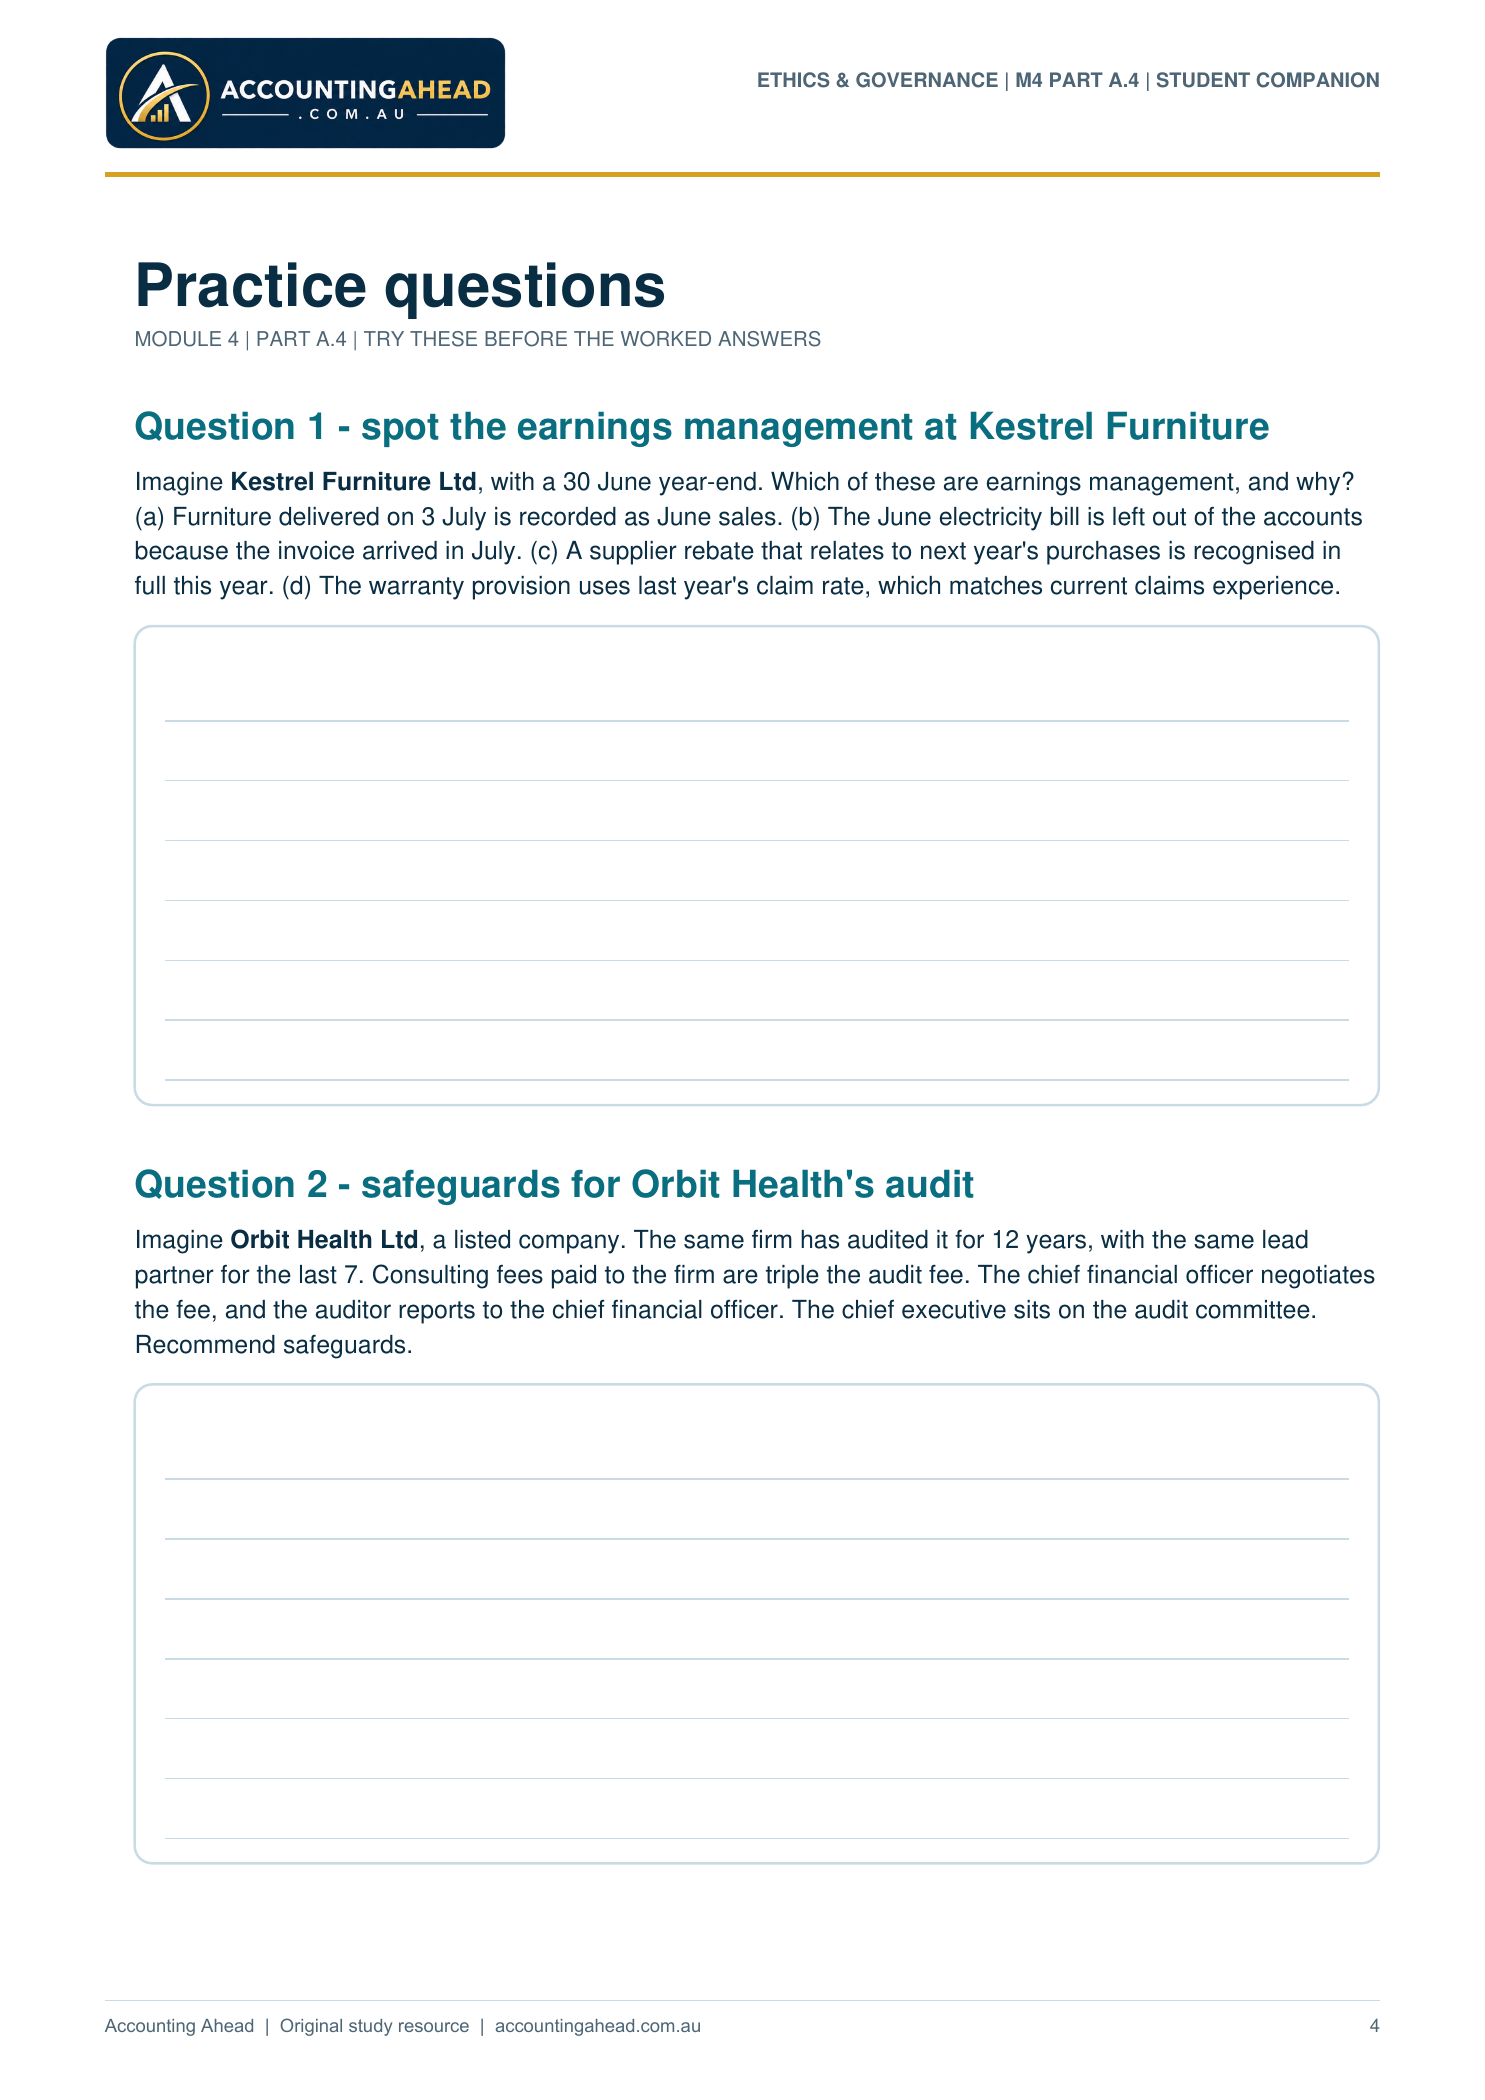
Practice questions
MODULE 4 | PART A.4 | TRY THESE BEFORE THE WORKED ANSWERS
Question 1 - spot the earnings management at Kestrel Furniture
Imagine Kestrel Furniture Ltd, with a 30 June year-end. Which of these are earnings management, and why?
(a) Furniture delivered on 3 July is recorded as June sales. (b) The June electricity bill is left out of the accounts
because the invoice arrived in July. (c) A supplier rebate that relates to next year's purchases is recognised in
full this year. (d) The warranty provision uses last year's claim rate, which matches current claims experience.
Question 2 - safeguards for Orbit Health's audit
Imagine Orbit Health Ltd, a listed company. The same firm has audited it for 12 years, with the same lead
partner for the last 7. Consulting fees paid to the firm are triple the audit fee. The chief financial officer negotiates
the fee, and the auditor reports to the chief financial officer. The chief executive sits on the audit committee.
Recommend safeguards.
ETHICS & GOVERNANCE | M4 PART A.4 | STUDENT COMPANION
4
Accounting Ahead | Original study resource | accountingahead.com.au
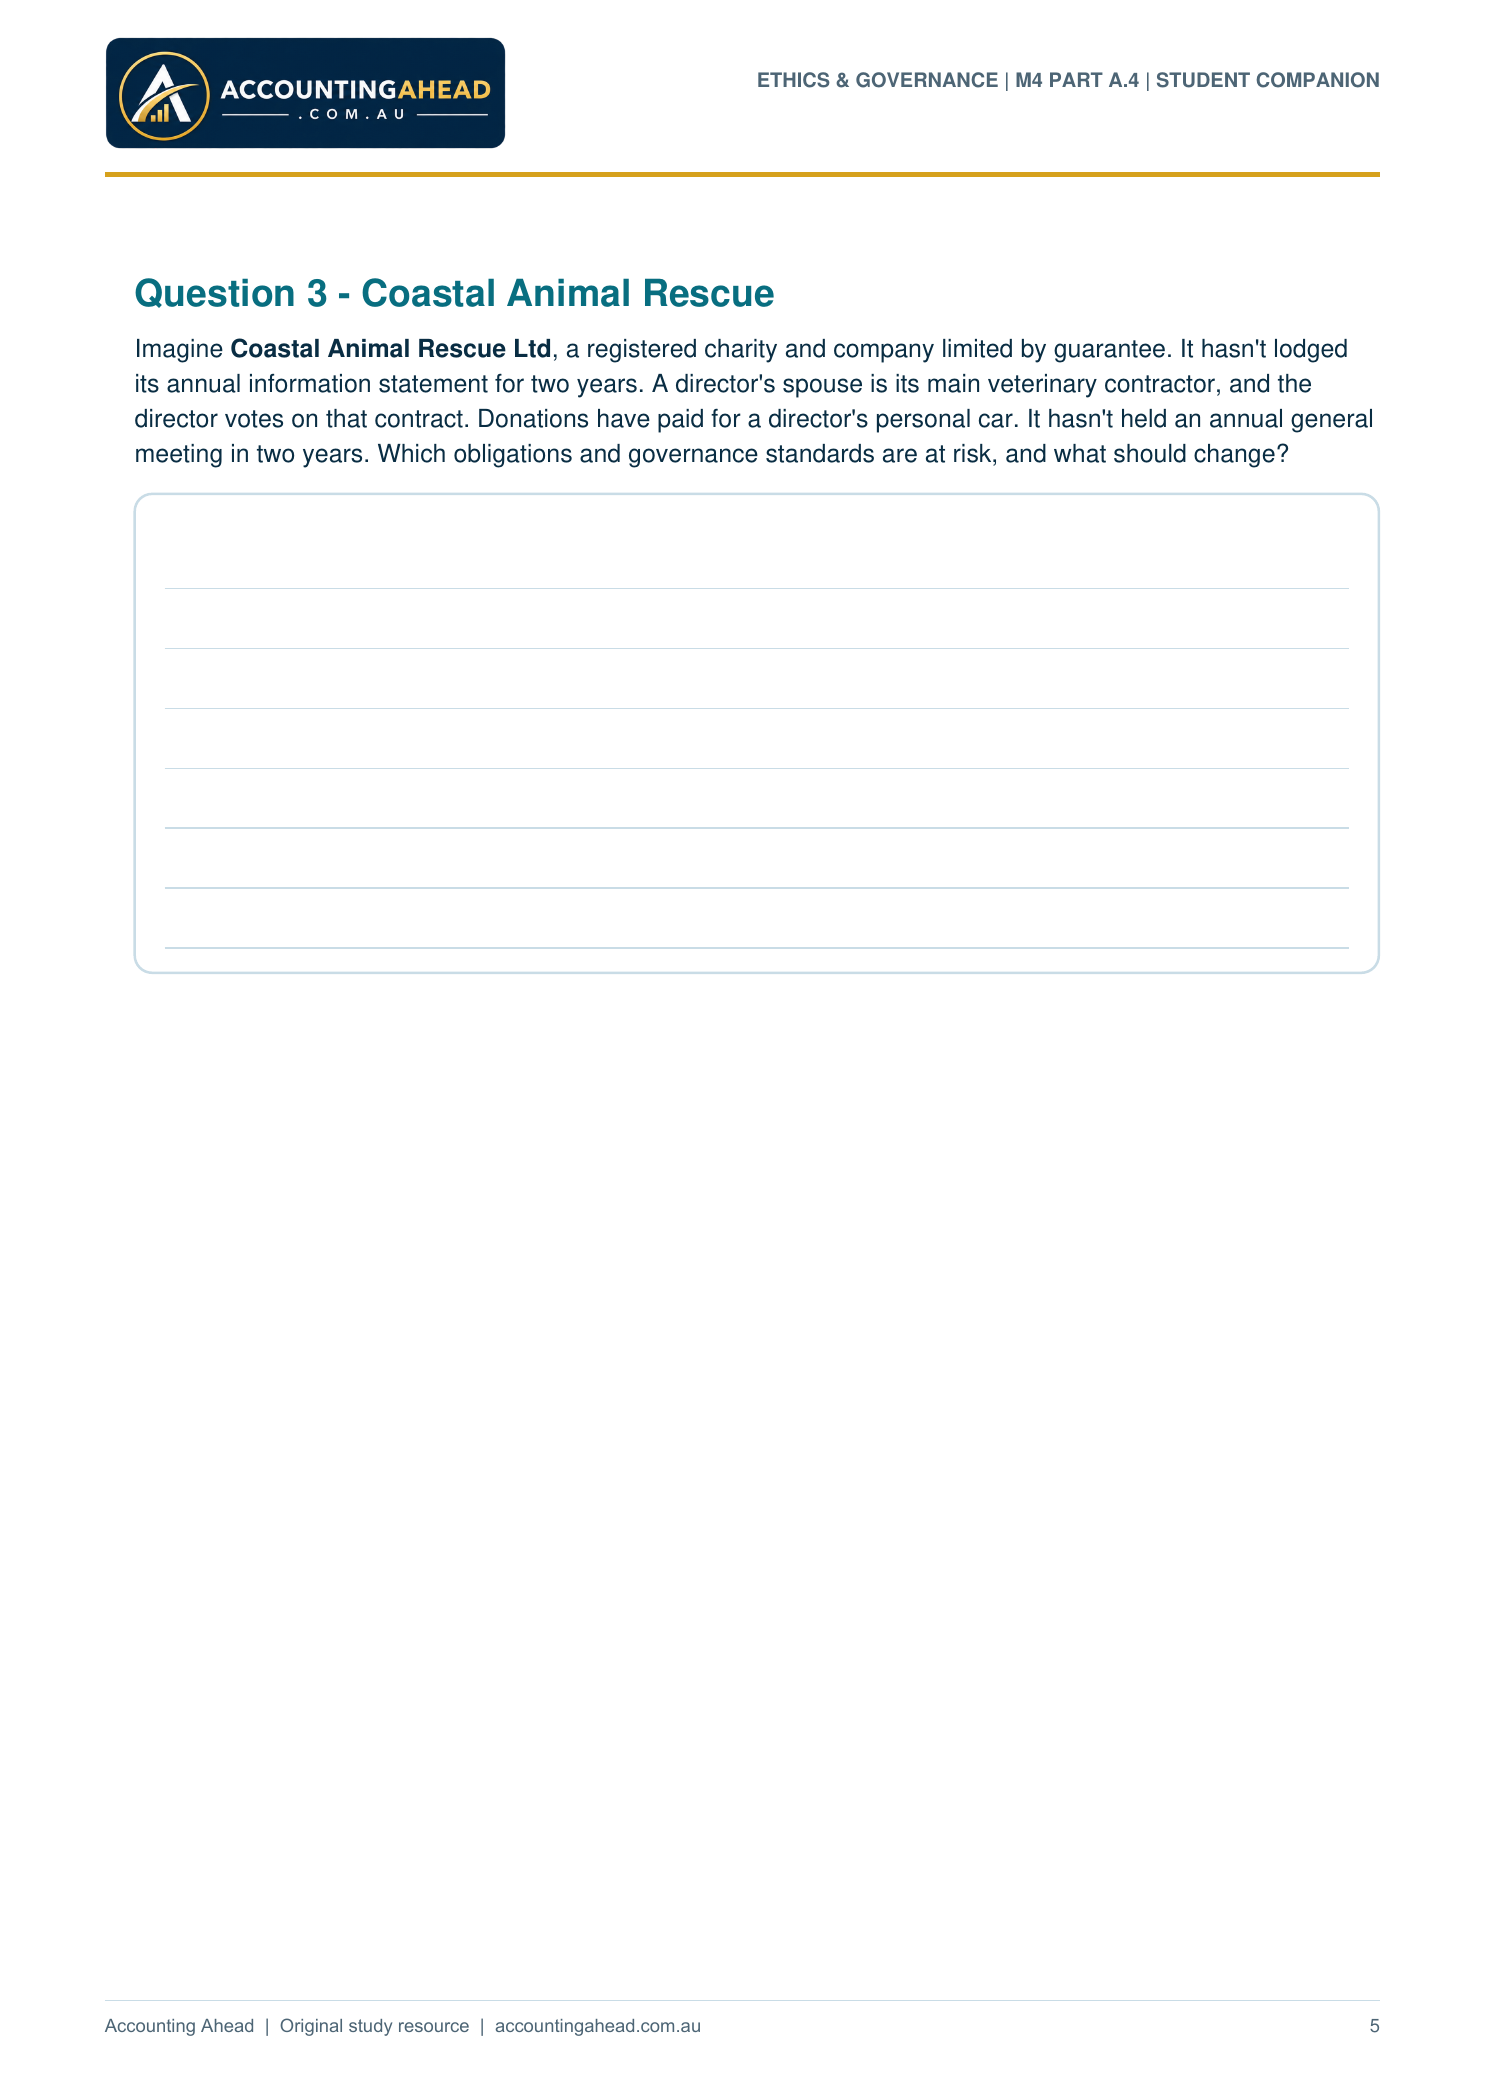
Question 3 - Coastal Animal Rescue
Imagine Coastal Animal Rescue Ltd, a registered charity and company limited by guarantee. It hasn't lodged
its annual information statement for two years. A director's spouse is its main veterinary contractor, and the
director votes on that contract. Donations have paid for a director's personal car. It hasn't held an annual general
meeting in two years. Which obligations and governance standards are at risk, and what should change?
ETHICS & GOVERNANCE | M4 PART A.4 | STUDENT COMPANION
5
Accounting Ahead | Original study resource | accountingahead.com.au
Worked answers
MODULE 4 | PART A.4 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
Question 1 - Kestrel Furniture
(a) Earnings management. The goods were delivered after year-end, so the revenue belongs to next year.
(b) Earnings management (or at least an error). The cost relates to June, so it should be accrued this year.
(c) Earnings management. The rebate relates to next year's purchases, so recognising it now brings income
forward.
(d) Legitimate judgement. The estimate uses current, supportable evidence.
Question 2 - Orbit Health
Move the auditor's reporting line to the audit committee, and let the committee own appointment, fees and
evaluation.
Remove the chief executive from the audit committee; it should consist of non-executive directors, mostly
independent.
Restrict non-audit services so fees no longer dwarf the audit fee.
Rotate the lead partner, who has served too long, and consider putting the audit out to tender after 12 years.
Hold private sessions between the committee and the auditor without management present.
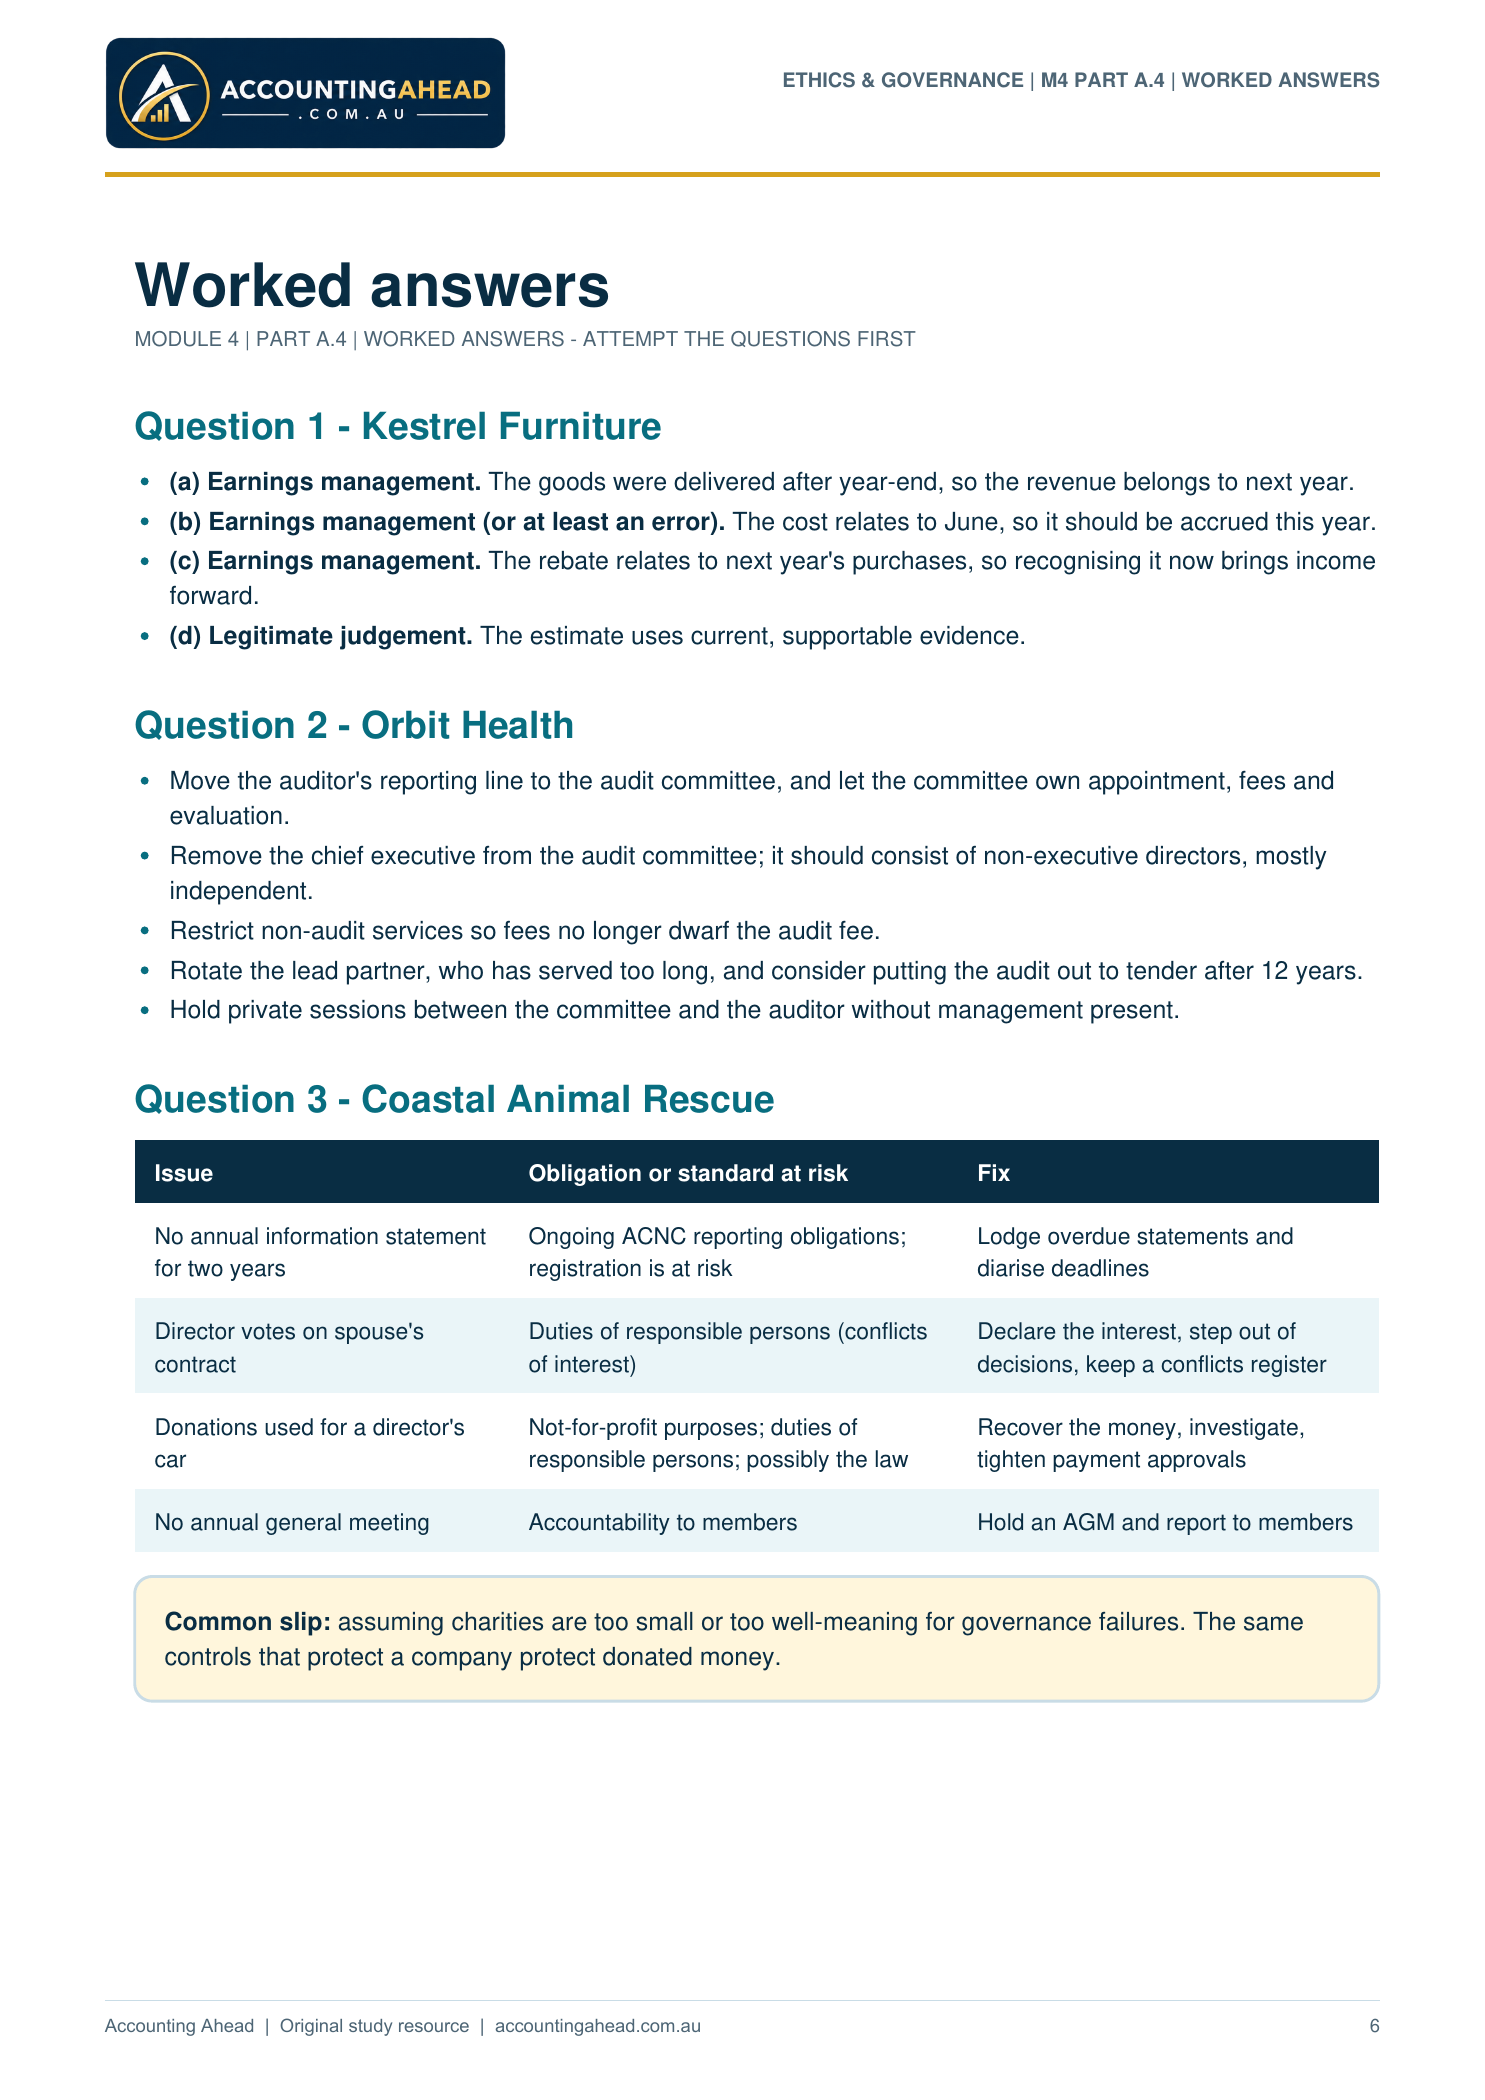
Question 3 - Coastal Animal Rescue
Issue Obligation or standard at risk Fix
No annual information statement
for two years
Ongoing ACNC reporting obligations;
registration is at risk
Lodge overdue statements and
diarise deadlines
Director votes on spouse's
contract
Duties of responsible persons (conflicts
of interest)
Declare the interest, step out of
decisions, keep a conflicts register
Donations used for a director's
car
Not-for-profit purposes; duties of
responsible persons; possibly the law
Recover the money, investigate,
tighten payment approvals
No annual general meeting Accountability to members Hold an AGM and report to members
Common slip: assuming charities are too small or too well-meaning for governance failures. The same
controls that protect a company protect donated money.
ETHICS & GOVERNANCE | M4 PART A.4 | WORKED ANSWERS
6