
The CPA's role in strategy and leadership
Printable study notes to use alongside Part 1.9.
Read the handout text
Accounting Ahead | Original study resource | accountingahead.com.au
The CPA's role in strategy and leadership
MODULE 1 | 1.9 | STUDENT COMPANION
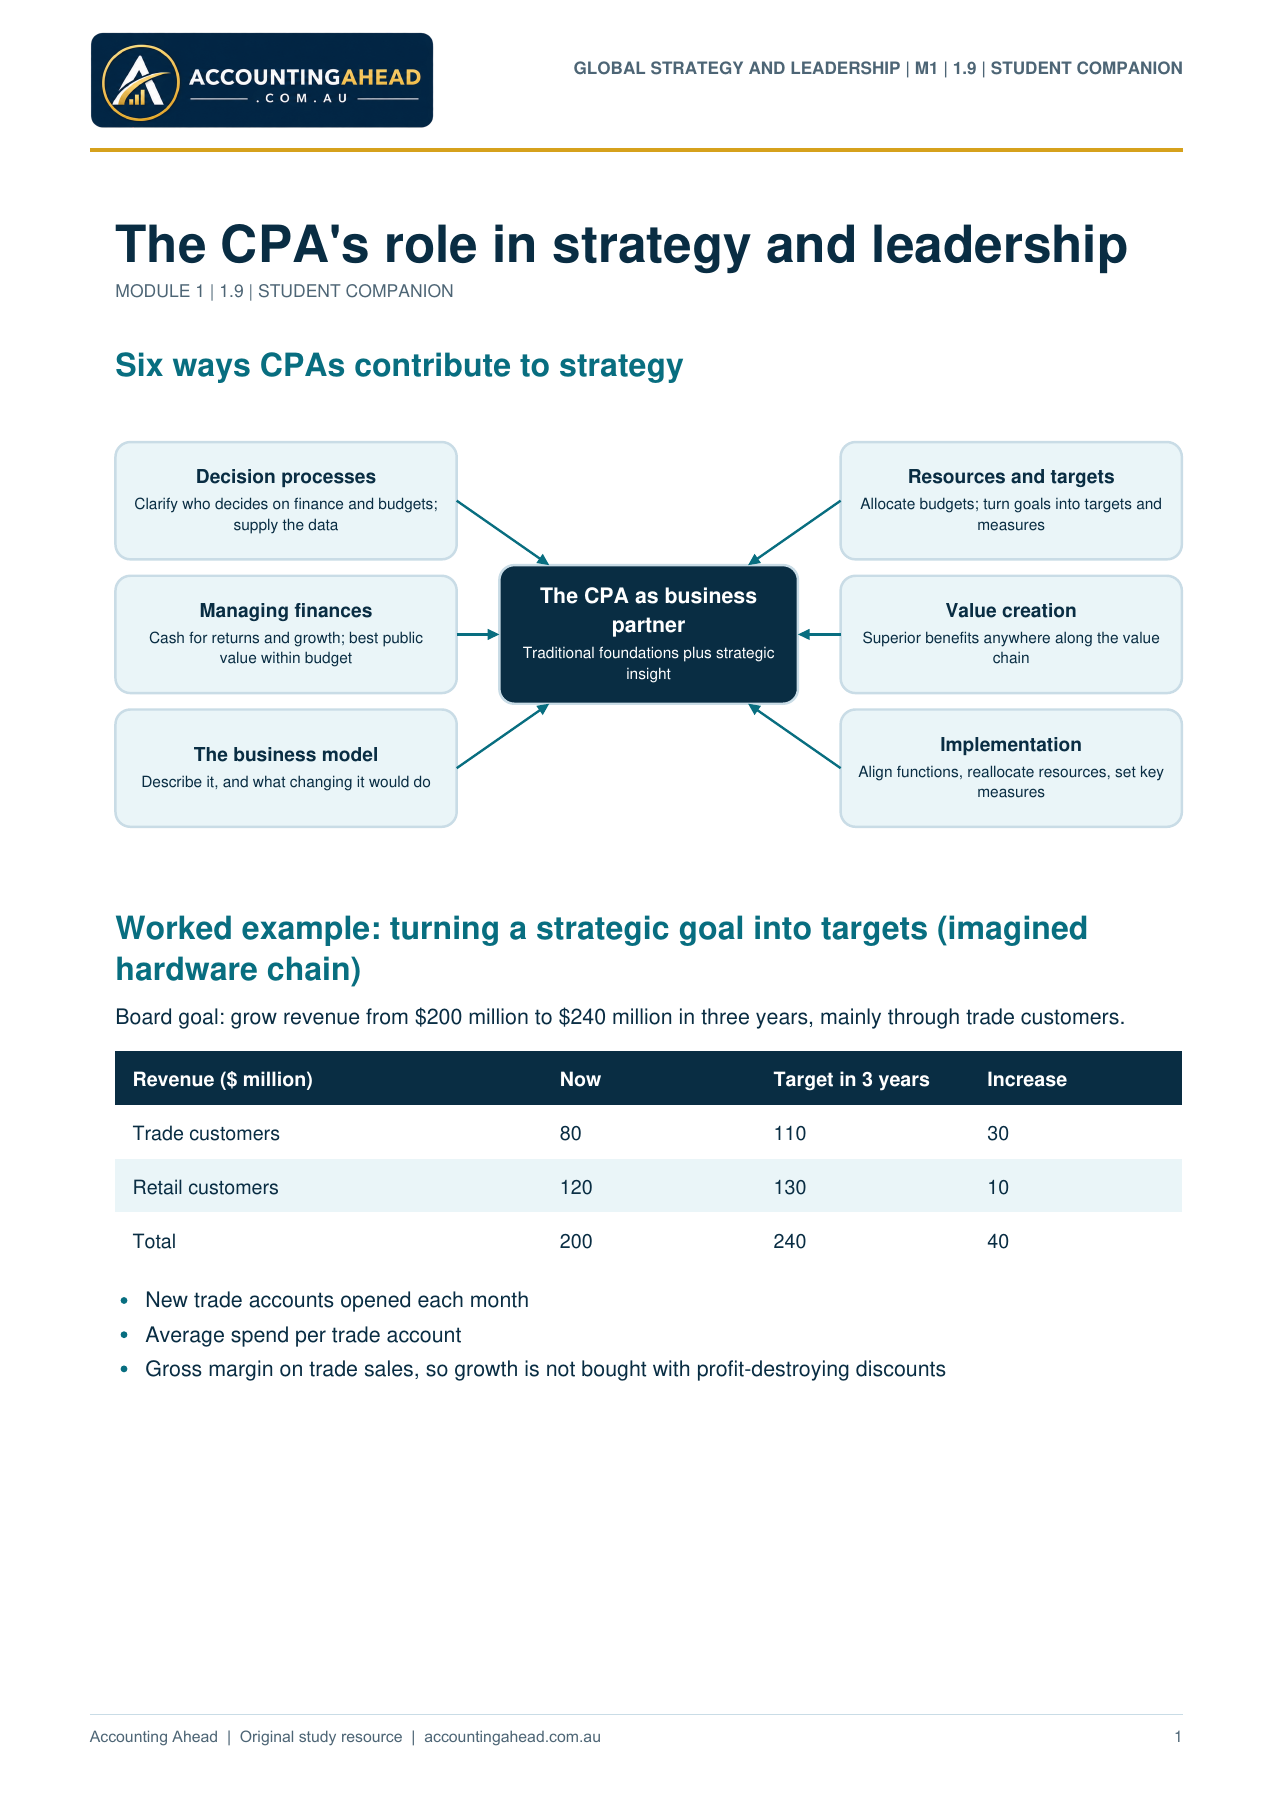
Six ways CPAs contribute to strategy
The CPA as business
partner
Traditional foundations plus strategic
insight
Decision processes
Clarify who decides on finance and budgets;
supply the data
Resources and targets
Allocate budgets; turn goals into targets and
measures
Managing finances
Cash for returns and growth; best public
value within budget
Value creation
Superior benefits anywhere along the value
chain
The business model
Describe it, and what changing it would do
Implementation
Align functions, reallocate resources, set key
measures
Worked example: turning a strategic goal into targets (imagined
hardware chain)
Board goal: grow revenue from $200 million to $240 million in three years, mainly through trade customers.
Revenue ($ million) Now Target in 3 years Increase
Trade customers 80 110 30
Retail customers 120 130 10
Total 200 240 40
New trade accounts opened each month
Average spend per trade account
Gross margin on trade sales, so growth is not bought with profit-destroying discounts
GLOBAL STRATEGY AND LEADERSHIP | M1 | 1.9 | STUDENT COMPANION
1
Accounting Ahead | Original study resource | accountingahead.com.au
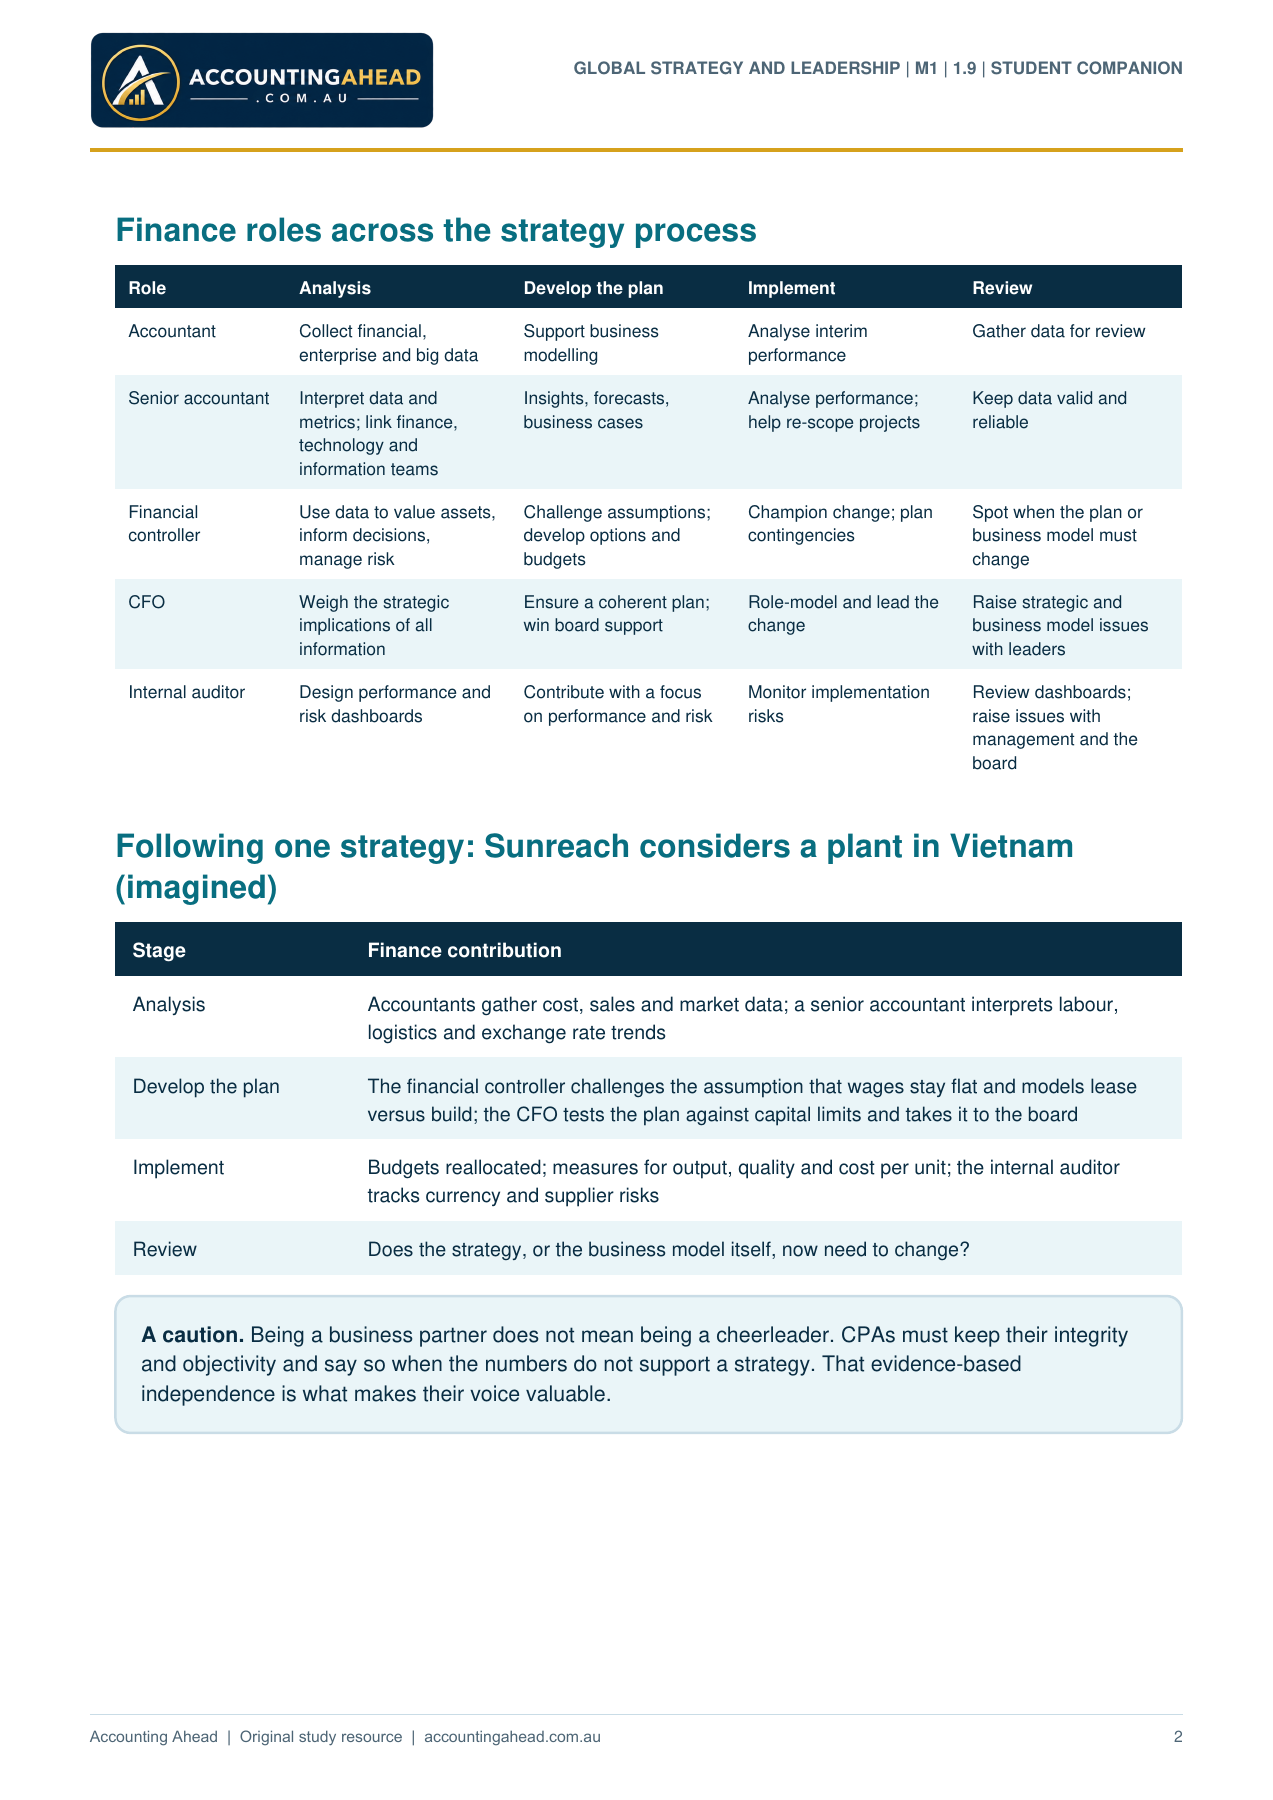
Finance roles across the strategy process
Role Analysis Develop the plan Implement Review
Accountant Collect financial,
enterprise and big data
Support business
modelling
Analyse interim
performance
Gather data for review
Senior accountant Interpret data and
metrics; link finance,
technology and
information teams
Insights, forecasts,
business cases
Analyse performance;
help re-scope projects
Keep data valid and
reliable
Financial
controller
Use data to value assets,
inform decisions,
manage risk
Challenge assumptions;
develop options and
budgets
Champion change; plan
contingencies
Spot when the plan or
business model must
change
CFO Weigh the strategic
implications of all
information
Ensure a coherent plan;
win board support
Role-model and lead the
change
Raise strategic and
business model issues
with leaders
Internal auditor Design performance and
risk dashboards
Contribute with a focus
on performance and risk
Monitor implementation
risks
Review dashboards;
raise issues with
management and the
board
Following one strategy: Sunreach considers a plant in Vietnam
(imagined)
Stage Finance contribution
Analysis Accountants gather cost, sales and market data; a senior accountant interprets labour,
logistics and exchange rate trends
Develop the plan The financial controller challenges the assumption that wages stay flat and models lease
versus build; the CFO tests the plan against capital limits and takes it to the board
Implement Budgets reallocated; measures for output, quality and cost per unit; the internal auditor
tracks currency and supplier risks
Review Does the strategy, or the business model itself, now need to change?
A caution. Being a business partner does not mean being a cheerleader. CPAs must keep their integrity
and objectivity and say so when the numbers do not support a strategy. That evidence-based
independence is what makes their voice valuable.
GLOBAL STRATEGY AND LEADERSHIP | M1 | 1.9 | STUDENT COMPANION
2
Accounting Ahead | Original study resource | accountingahead.com.au
Practice questions
MODULE 1 | 1.9 | TRY THESE BEFORE THE WORKED ANSWERS
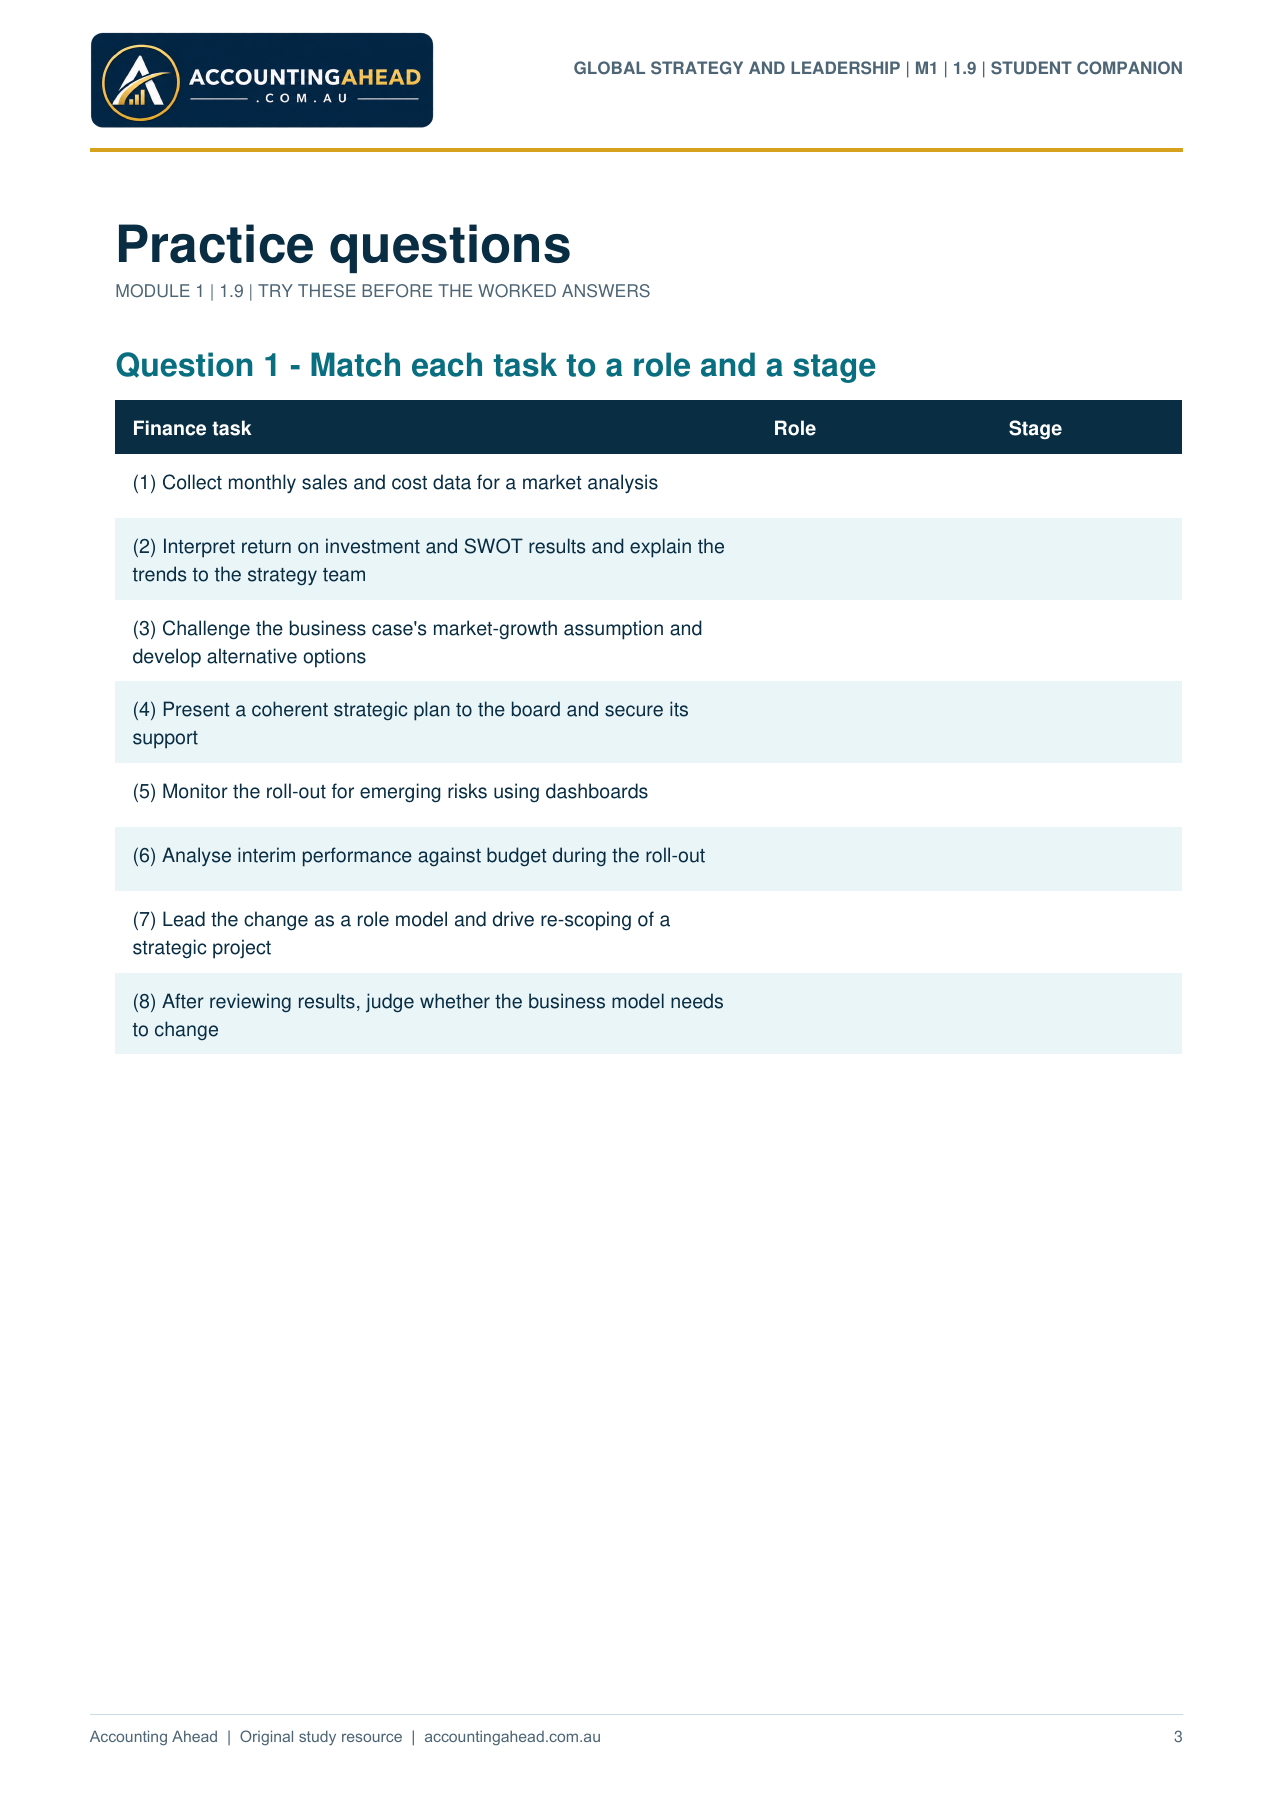
Question 1 - Match each task to a role and a stage
Finance task Role Stage
(1) Collect monthly sales and cost data for a market analysis
(2) Interpret return on investment and SWOT results and explain the
trends to the strategy team
(3) Challenge the business case's market-growth assumption and
develop alternative options
(4) Present a coherent strategic plan to the board and secure its
support
(5) Monitor the roll-out for emerging risks using dashboards
(6) Analyse interim performance against budget during the roll-out
(7) Lead the change as a role model and drive re-scoping of a
strategic project
(8) After reviewing results, judge whether the business model needs
to change
GLOBAL STRATEGY AND LEADERSHIP | M1 | 1.9 | STUDENT COMPANION
3
Accounting Ahead | Original study resource | accountingahead.com.au
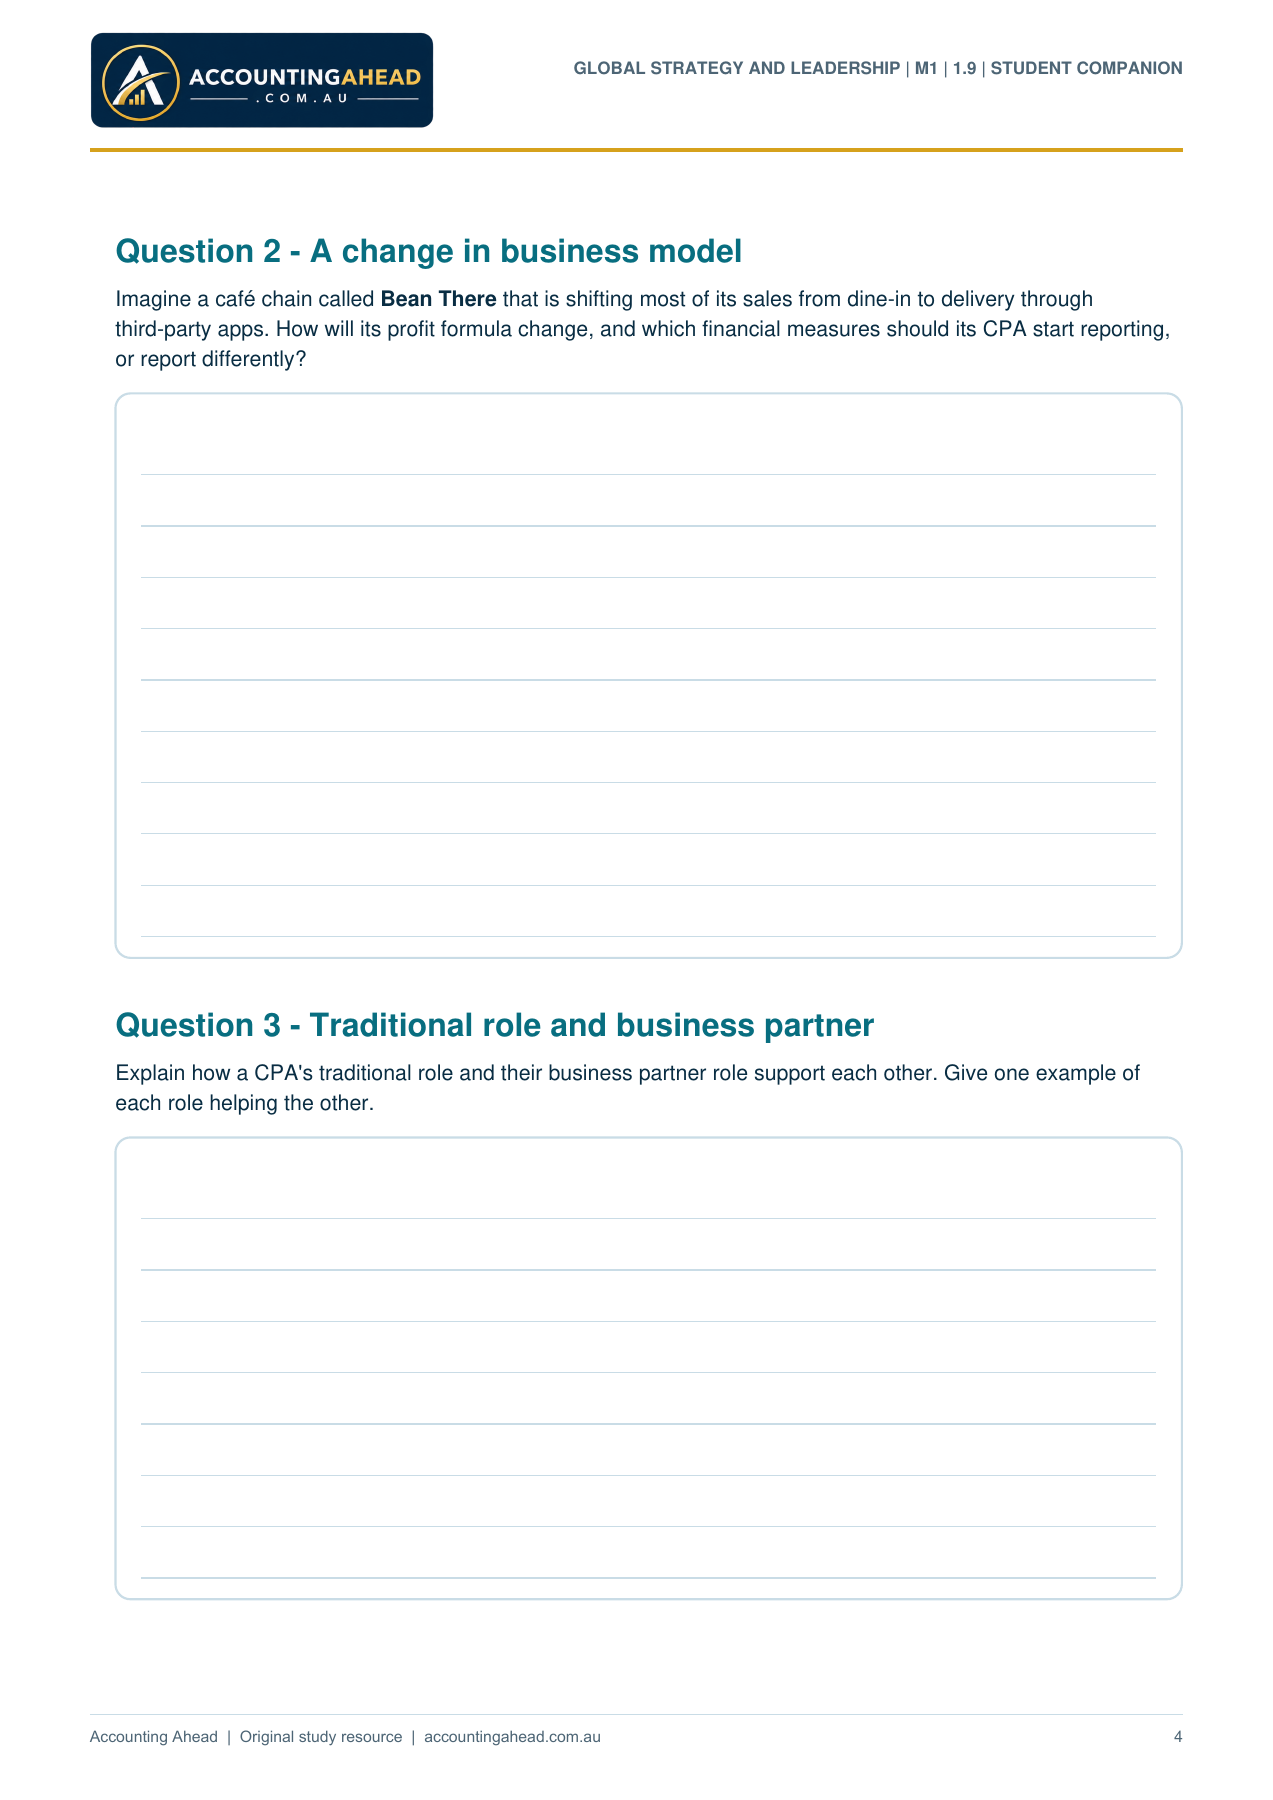
Question 2 - A change in business model
Imagine a café chain called Bean There that is shifting most of its sales from dine-in to delivery through
third-party apps. How will its profit formula change, and which financial measures should its CPA start reporting,
or report differently?
Question 3 - Traditional role and business partner
Explain how a CPA's traditional role and their business partner role support each other. Give one example of
each role helping the other.
GLOBAL STRATEGY AND LEADERSHIP | M1 | 1.9 | STUDENT COMPANION
4
Accounting Ahead | Original study resource | accountingahead.com.au
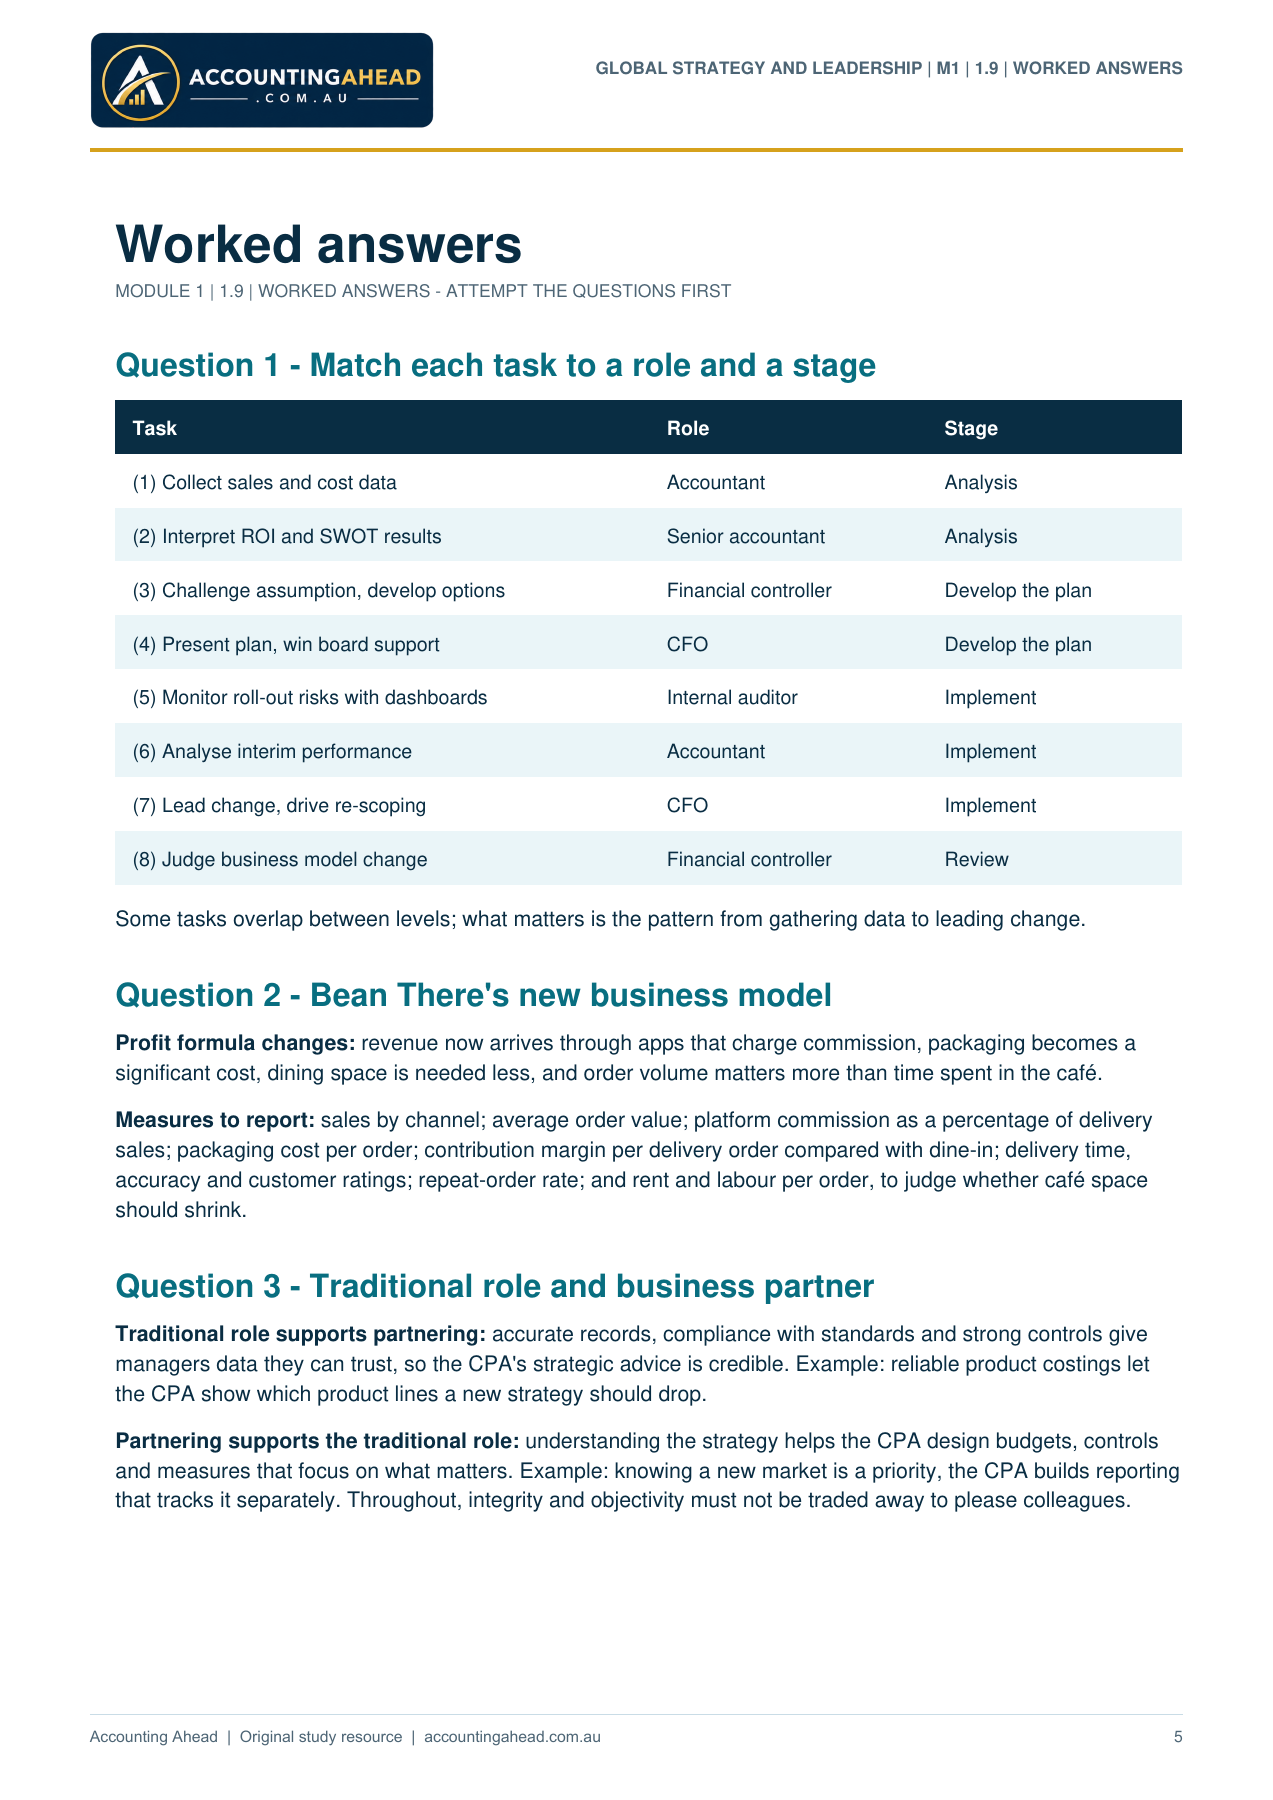
Worked answers
MODULE 1 | 1.9 | WORKED ANSWERS - ATTEMPT THE QUESTIONS FIRST
Question 1 - Match each task to a role and a stage
Task Role Stage
(1) Collect sales and cost data Accountant Analysis
(2) Interpret ROI and SWOT results Senior accountant Analysis
(3) Challenge assumption, develop options Financial controller Develop the plan
(4) Present plan, win board support CFO Develop the plan
(5) Monitor roll-out risks with dashboards Internal auditor Implement
(6) Analyse interim performance Accountant Implement
(7) Lead change, drive re-scoping CFO Implement
(8) Judge business model change Financial controller Review
Some tasks overlap between levels; what matters is the pattern from gathering data to leading change.
Question 2 - Bean There's new business model
Profit formula changes: revenue now arrives through apps that charge commission, packaging becomes a
significant cost, dining space is needed less, and order volume matters more than time spent in the café.
Measures to report: sales by channel; average order value; platform commission as a percentage of delivery
sales; packaging cost per order; contribution margin per delivery order compared with dine-in; delivery time,
accuracy and customer ratings; repeat-order rate; and rent and labour per order, to judge whether café space
should shrink.
Question 3 - Traditional role and business partner
Traditional role supports partnering: accurate records, compliance with standards and strong controls give
managers data they can trust, so the CPA's strategic advice is credible. Example: reliable product costings let
the CPA show which product lines a new strategy should drop.
Partnering supports the traditional role: understanding the strategy helps the CPA design budgets, controls
and measures that focus on what matters. Example: knowing a new market is a priority, the CPA builds reporting
that tracks it separately. Throughout, integrity and objectivity must not be traded away to please colleagues.
GLOBAL STRATEGY AND LEADERSHIP | M1 | 1.9 | WORKED ANSWERS
5